
 Europe Dairy Based Beverages Market | 2026-2036
Europe Dairy Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Based Beverages Market Foresight
Danish and German dairy cooperatives are expanding processing capacity for extended-shelf-life beverages across the region. Arla Foods amba leverages its farmer-owned structure to secure raw milk supply chains from Jutland to the Rhineland. Lactalis International anchors its position through scale advantages in UHT and fresh chilled logistics. Danone Groupe SA differentiates via probiotic and fermented drink portfolios that command shelf space in French and Benelux retail channels.
Europe dairy based beverages comprise heat-treated or fermented liquid products derived from cow, goat, or sheep milk, typically standardized to specific fat and protein contents before homogenization and aseptic or refrigerated packaging. These products serve nutritional refreshment, meal replacement, and gut-health functions across age demographics. Flavored milk and yogurt drinks lead volume contribution, while milkshakes capture premium positioning in convenience and foodservice channels. Health stores and online retail represent the fastest-expanding distribution vectors as consumers seek functional formulations with reduced added sugars.
EFSA nutrition and health claims regulation, EU organic certification standards, and national dairy quality schemes such as the French AOP and German g.g.A. labels collectively shape product development cycles and market access conditions across member states. REACH compliance for packaging materials and the EU Green Deal farm-to-fork targets are tightening emissions and waste benchmarks for processors. Stakeholders must monitor evolving Codex Alimentarius standards and member-state enforcement patterns to anticipate reformulation costs and label claim risks.
Market Dynamics
EFSA nutrition and health claims regulation is pressuring processors toward cleaner-label reformulation while fitness-oriented functional beverage demand reshapes portfolio priorities across the region.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Processors investing in emission-reduction pathways secure preferential retail placement and procurement contracts with sustainability-minded foodservice operators.
- Chilled dairy infrastructure expansion:German private-label innovation and Danish cooperative processing investments extend fresh product reach into convenience and premium channels.
- Probiotic and fermented drink portfolios:Gut-health positioning commands shelf space in French and Benelux retail, widening consumer base beyond traditional dairy demographics.
Market Restraints
- Raw milk supply concentration:Farmer-owned cooperative structures in Jutland and the Rhineland create procurement dependency risks for non-integrated processors.
- REACH compliance costs for packaging materials:Extended-shelf-life beverage formats face material substitution expenses and testing timelines.
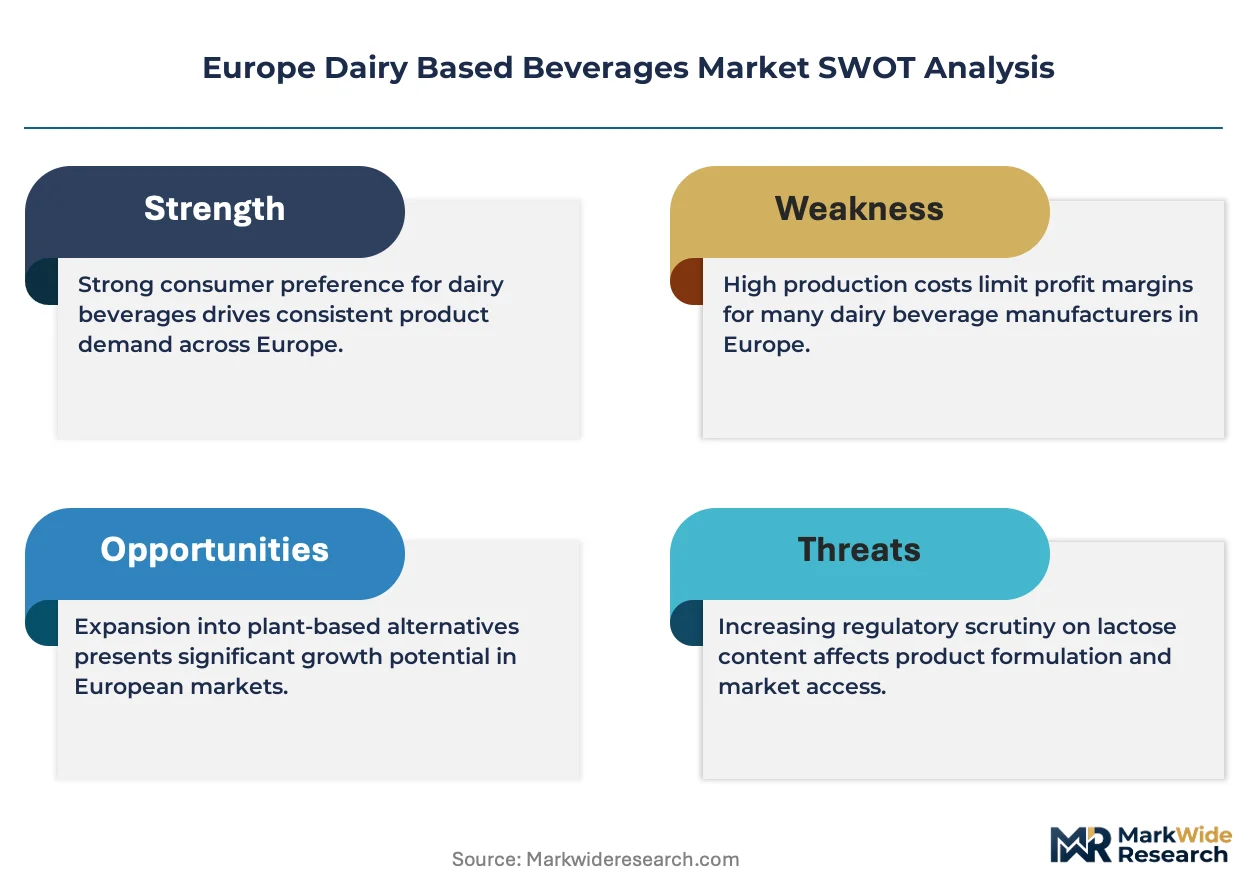
- Plant-based beverage substitution:Oat and almond alternatives capture lactose-intolerant and flexitarian consumers in urban Benelux and Scandinavian markets.
Strategic Opportunities
- Underpenetrated Polish and Romanian markets:Chilled infrastructure gaps create first-mover advantages for ambient-stable functional formulations with local flavor profiles.
- Online retail and health store channels:Direct-to-consumer distribution bypasses traditional retail slotting fees and enables subscription-based recurring revenue models.
- EU organic certification standards:Premium positioning through AOP and g.g.A. quality schemes captures price-insensitive segments in France and Germany.
Industry Challenges
- Reformulation expertise scarcity:Sugar reduction without sensory degradation requires specialized food technologists in short supply across Central European processing hubs.
- Codex Alimentarius alignment complexity:Member-state enforcement pattern variations create label claim risks and duplicate testing burdens for cross-border products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Based Beverages Market |
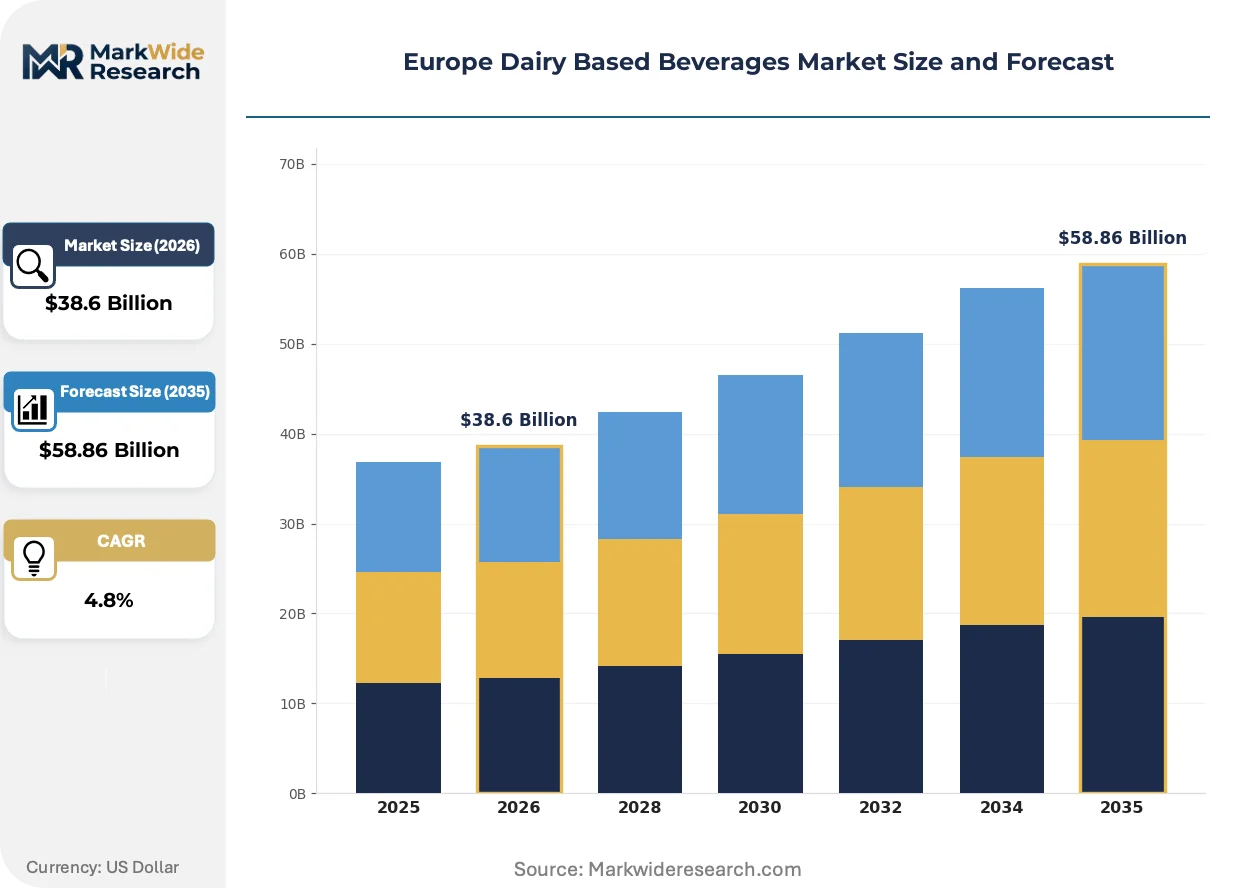
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milkshake, Yogurt Drink, Creamy Beverage, Flavored Milk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores End User: Children, Adults, Seniors, Fitness Enthusiasts Flavor Profile: Chocolate, Vanilla, Strawberry, Caramel |
| Companies Covered | Arla Foods amba, Lactalis International, Nestle SA, Chobani Global Holdings LLC, Ornua Co-operative Limited, Danone Groupe SA, SODIAAL, Uelzena Group, FrieslandCampina, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Based Beverages Market Shifts & Advancements
Aseptic processing advances and fermentation science are compressing the gap between fresh taste and extended shelf stability, while regulatory tightening and channel fragmentation reshape how value reaches consumers.
High-pressure processing technology is extending shelf life without thermal degradation of proteins and probiotics. German and Dutch dairy cooperatives are adopting HPP lines for premium chilled smoothies and functional shots. This capability is converging with clean-label positioning to justify 40-60% price premiums over heat-treated equivalents in Scandinavian and Benelux retail.
EFSA nutrition and health claims regulation is narrowing permissible gut-health and immunity statements on packaging. Processors must commission expensive human intervention studies to substantiate remaining claim categories. Fermented beverage portfolios in France and Italy face the strictest scrutiny, driving reformulation toward documented strain-specific probiotic concentrations.
Health stores and pharmacy channels are capturing functional beverage volumes previously routed through supermarkets. French and German consumers increasingly purchase protein-enriched recovery drinks and meal-replacement shakes from specialist retailers offering personalized nutrition guidance. This channel rotation concentrates margin with brands investing in practitioner education and sampling programs rather than slotting fee competition.
Europe Dairy Based Beverages Market Segmentation
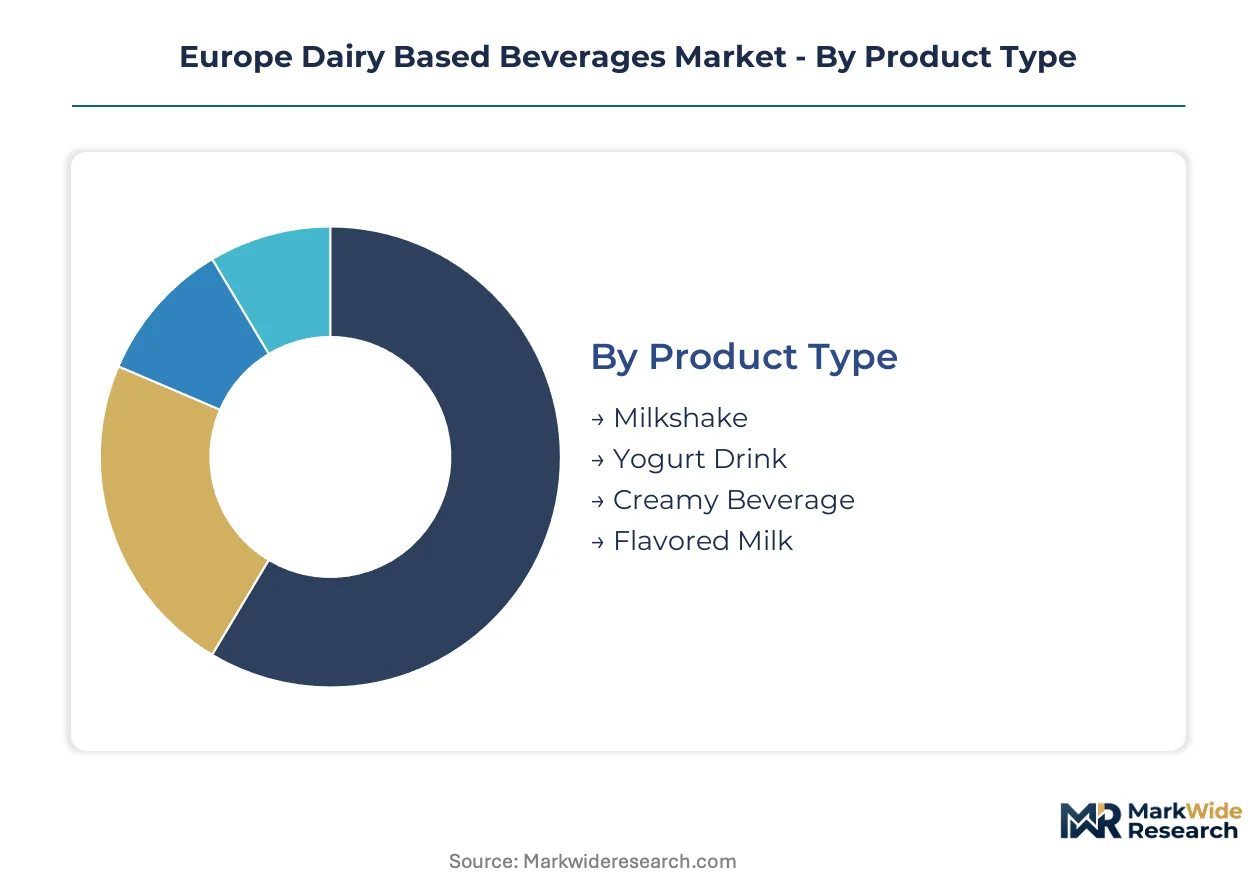
Segmentation in Europe dairy based beverages determines which EFSA health claim pathways and national quality labels apply to each product category. Certification burdens vary sharply across chilled versus ambient formats, direct-to-consumer versus retail channels, and functional versus indulgence-positioned offerings.
Product Type:
EFSA nutrition and health claims regulation imposes distinct substantiation requirements on fermented versus heat-treated formats, with probiotic portfolios facing the strictest clinical evidence thresholds.
- Yogurt Drink:Fermented beverages with live cultures require strain-specific documentation for gut-health claims under EFSA guidelines. Demand concentrates in French and Benelux retail channels where pharmacy and health store distribution commands premium shelf placement.
- Flavored Milk:Heat-treated, sweetened dairy beverages face sugar-reduction reformulation pressure from EU farm-to-fork targets. German private-label innovation and Danish cooperative processing investments are extending reduced-sugar variants into convenience channels.
- Milkshake:Indulgence-positioned thick beverages with elevated fat content target foodservice and premium retail. REACH compliance for packaging materials adds material substitution costs to extended-shelf-life formats.
- Creamy Beverage:High-viscosity dessert-style drinks with standardized protein content serve meal-replacement functions. French AOP and German g.g.A. quality schemes enable premium pricing in price-insensitive segments.
Flavored Milk sits at the top of the volume ranking, with Yogurt Drink climbing the fastest.
Distribution Channel:
Channel selection dictates cold-chain investment intensity and margin structure, with direct-to-consumer formats bypassing traditional slotting fee competition.
- Supermarkets:Mass-market retail dominates volume throughput but faces margin compression from private-label competition and promotional intensity.
- Online Retail:Direct-to-consumer distribution enables subscription-based recurring revenue models and personalized nutrition guidance. Health stores and pharmacy channels are capturing functional beverage volumes previously routed through supermarkets.
- Convenience Stores:Chilled infrastructure gaps in Polish and Romanian markets create first-mover advantages for ambient-stable functional formulations.
- Health Stores:Specialist retailers concentrate margin with brands investing in practitioner education rather than slotting fee competition.
Supermarkets maintain the largest volume base, while Online Retail gains share fastest through subscription models.
End User:
Demographic targeting shapes formulation priorities from sugar content to protein fortification and portion sizing.
- Fitness Enthusiasts:Protein-enriched recovery drinks and meal-replacement shakes command shelf space in French and German health stores. High-pressure processing technology justifies 40-60% price premiums over heat-treated equivalents.
- Children:Portion-controlled, calcium-fortified formats face strict sugar-reduction mandates under national school nutrition guidelines.
- Adults:Gut-health and immunity positioning targets working-age consumers through convenience channel placement.
- Seniors:Protein density and digestibility specifications address sarcopenia prevention in aging populations.
Adults represent the broadest addressable base, with Fitness Enthusiasts expanding most quickly through functional positioning.
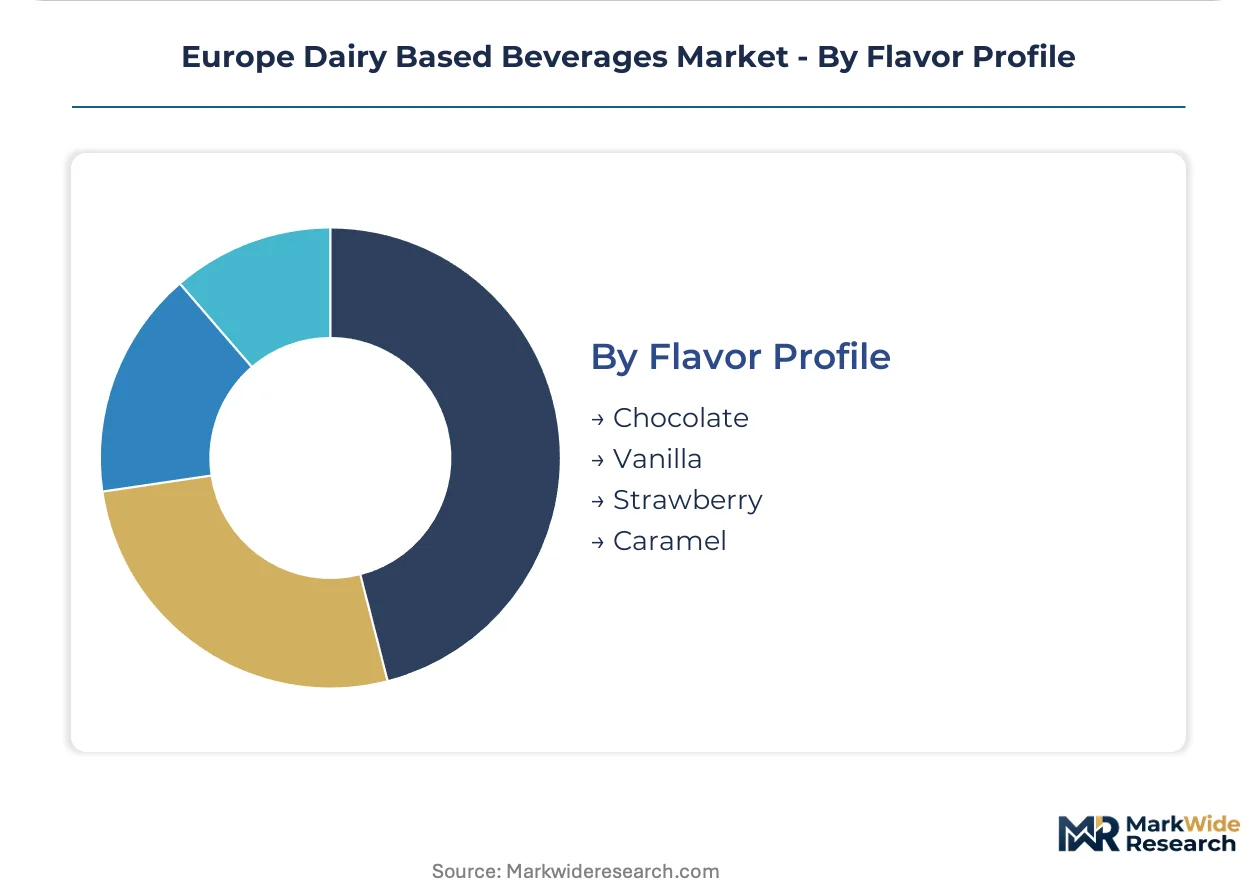
Flavor Profile:
Flavor selection intersects with clean-label reformulation, as natural extract costs and stability challenges reshape traditional chocolate and vanilla portfolios.
- Chocolate:Cocoa-based formulations face sugar-reduction challenges without sensory degradation, requiring specialized food technologists in short supply.
- Vanilla:Natural extract sourcing and stability in UHT processing create supply concentration in Madagascar and Réunion supply chains.
- Strawberry:Fruit-based positioning aligns with clean-label trends but faces seasonal raw material cost volatility.
- Caramel:Indulgence positioning captures premium price points in convenience and foodservice channels.
Chocolate leads volume contribution, with Caramel showing the steepest expansion trajectory in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting processing investments toward jurisdictions where EFSA compliance costs and national quality-scheme burdens create tiered entry barriers, with German and Danish cooperatives exploiting infrastructure advantages while French and Italian processors navigate stricter substantiation requirements for health claims.
Germany
Private-label innovation and chilled dairy infrastructure concentration drive volume leadership across convenience and premium channels. The German g.g.A. quality scheme imposes geographic-origin documentation that favors Rhineland-based cooperatives with captive milk supply. Munich and Hamburg anchor retail distribution networks where functional beverage portfolios command expanded shelf space.
France
Probiotic and fermented drink demand concentrates in pharmacy and health store channels where personalized nutrition guidance justifies price premiums. The French AOP labeling system restricts terroir claims to designated production zones, compressing margin for non-compliant processors. The Île-de-France and Auvergne-Rhône-Alpes clusters host strain-specific documentation capabilities required for EFSA gut-health substantiation.
Denmark
Farmer-owned cooperative structures secure raw milk supply chains from Jutland processing hubs across extended-shelf-life beverage formats. REACH compliance for packaging materials adds material substitution costs that integrated players absorb more efficiently than independent entrants. Copenhagen anchors Nordic distribution while Aarhus processing investments target German and Swedish export markets.
Netherlands
High-pressure processing technology adoption concentrates among Dutch cooperatives seeking fresh-taste positioning without thermal degradation. The EU Green Deal farm-to-fork targets drive emission-reduction investments that secure preferential retail placement with sustainability-minded operators. Rotterdam logistics infrastructure enables rapid chilled distribution into Belgian and German convenience channels.
Poland
Chilled infrastructure gaps create first-mover advantages for ambient-stable functional formulations with localized flavor profiles. National dairy quality schemes remain less stringent than Western European equivalents, attracting reformulation investments from processors seeking regulatory-cost arbitrage. Warsaw and Kraków retail modernization programs expand modern-trade penetration for packaged beverage categories.
Europe Dairy Based Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional and clean-label positioning to bypass slotting-fee barriers. The market exhibits cooperative-dominated supply concentration alongside multinational scale players with diversified fermentation capabilities. Three archetypes prevail: farmer-owned cooperatives with captive raw milk, multinational dairy conglomerates with UHT and fresh logistics scale, and specialist probiotic portfolio operators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as processors seek to secure chilled distribution reach.
Within the cooperative archetype, Arla Foods amba and FrieslandCampina exemplify farmer-owned structures that anchor supply security across Jutland and Dutch processing clusters. Danone Groupe SA occupies a position representing the specialist tier, with probiotic and fermented drink portfolios commanding differentiated shelf space in French and Benelux pharmacy channels. Lactalis International exemplifies scale-driven positioning through UHT and fresh chilled logistics advantages that extend across multiple national markets.
| Leading Market Players |
|---|
| Arla Foods amba |
| Lactalis International |
| Nestle SA |
| Chobani Global Holdings LLC |
| Ornua Co-operative Limited |
| Danone Groupe SA |
| SODIAAL |
| Uelzena Group |
| FrieslandCampina |
| Others |
Supply & Pricing Matrix
Raw milk procurement costs in Jutland and the Rhineland cascade through farmer-owned cooperative structures into three distinct pricing tiers: premium AOP and g.g.A. certified lines, standard private-label offerings, and economy UHT formats. EFSA substantiation expenses for gut-health claims compress margins at the premium tier while REACH compliance for aseptic packaging materials elevates cost floors across extended-shelf-life segments.
Pricing Analysis
Retailer markup layers in French and German pharmacy channels absorb 40-60% premiums for HPP-processed functional shots over heat-treated equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain investment intensity. Pricing pressure stems from private-label expansion in German convenience retail, compressing branded player margins. Fitness enthusiasts demonstrate lowest price sensitivity for strain-documented probiotic portfolios, while children-oriented flavored milk segments face acute pressure from national school nutrition sugar caps.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand while health store and pharmacy distribution requires specialized cold-chain partnerships. Geographic supply concentration centers on Denmark, Germany, and the Netherlands for high-pressure processing capacity and extended-shelf-life infrastructure. Raw material dependencies include strain-specific probiotic cultures, aseptic packaging substrates, and Madagascar-sourced vanilla extracts. Single-source vulnerability in live culture supply creates reformulation bottlenecks when documentation gaps trigger EFSA claim rejections. Distribution runs through Rotterdam logistics hubs for rapid chilled penetration into Belgian and German convenience networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA compliance cost differentials between Western and Eastern European processing jurisdictions create geographic-arbitrage opportunities for ambient-stable functional formulations, with Poland and Romania offering lower substantiation burdens for market entry.
For Market Incumbents: Anticipate plant-based substitution pressure in Benelux and Scandinavian urban centers by securing captive raw milk supply through cooperative equity structures. Prioritize backward integration into high-pressure processing capacity to defend premium positioning against emerging clean-label specialists. Accelerate strain-specific documentation investments ahead of tightening EFSA gut-health claim enforcement in France and Italy. For New Entrants and Emerging Players: Direct-to-consumer subscription channels bypass slotting fee barriers and enable recurring revenue capture in protein-enriched recovery drink segments. Target underpenetrated Polish and Romanian markets with localized flavor profiles and ambient-stable formulations that circumvent chilled infrastructure gaps. Pursue health store practitioner education programs as the primary go-to-market angle for gut-health positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative processing capacity in Jutland and Dutch clusters faces margin compression from REACH packaging compliance costs. Long-term viability favors acquiring specialist probiotic portfolio operators with documented strain libraries and pharmacy channel relationships. Watch EFSA enforcement pattern harmonization across member states as the critical inflection signal for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Capacity Expansion | Dutch and German cooperatives justify 40-60% retail premiums through fresh-taste positioning without thermal degradation. |
| Strain-Specific Documentation Investment | French and Italian processors commission human intervention studies to secure remaining EFSA gut-health claim categories. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket slotting fees and capture recurring revenue in fitness enthusiast segments. |
| Backward Integration into Raw Milk Supply | Farmer-owned structures in Jutland and the Rhineland secure procurement against cooperative concentration risks. |
| Poland/Romania Market Entry | Ambient-stable functional formulations exploit chilled infrastructure gaps and lower national quality scheme burdens. |
Research Methodology
Direct dialogue with dairy processing executives, EFSA regulatory affairs specialists, French pharmacy category buyers, and German private-label innovation directors grounded qualitative findings in operational reality. Secondary validation drew from EU organic certification databases, EFSA health claim registers, national dairy quality scheme documentation, and customs trade records for aseptic packaging substrates. Bottom-up volume modeling triangulated against top-down value estimates from retail audit data and cooperative financial disclosures.
Bottom-up segmentation analysis modeled product type, distribution channel, end-user demographic, and flavor profile dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timing and channel shift velocities. Industry-specific forecast inputs included EFSA substantiation pipeline backlogs and high-pressure processing capacity expansion announcements from Dutch and German cooperatives.
The model assumes a particular technology adoption path; alternative pathways for ambient-stable aseptic processing would alter the outlook if HPP cost curves flatten faster than projected. Forecasts reflect base-case assumptions about EFSA enforcement harmonization and EU Green Deal farm-to-fork target adherence. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty and plant-based substitution velocity in urban markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Spreads Market
Dairy Products
Dairy Foods Market
Dairy Products
North America Casein Market
Dairy Products
Dairy Protein Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Skimmed Milk Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Milk Retentate Market
Dairy Products
Filled Cheese Market
Dairy Products
Gruyere Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Smoked Cheese Market