
 Spoonable Yogurt Market | 2026-2036
Spoonable Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Spoonable Yogurt Market Intelligence
USDA Organic certification is redrawing the competitive landscape for premium spoonable yogurt. Danone SA leverages its global manufacturing footprint to scale its organic and probiotic offerings. Chobani LLC differentiates with its focus on high-protein Greek yogurt, capturing a loyal consumer base. General Mills Inc. sustains its market presence through established brand recognition in the conventional yogurt segment.
Spoonable yogurt is a cultured dairy product created through the bacterial fermentation of milk, resulting in a viscous, semi-solid consistency. Its primary purpose is to serve as a convenient, nutrient-dense food source rich in probiotics. The Greek yogurt product type continues to lead in value, prized for its thicker texture and higher protein content. Concurrently, non-dairy yogurt made from almond, soy, or coconut milk is expanding rapidly to meet vegan and lactose-intolerant consumer needs.
Labeling and health claims are strictly governed by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). In parallel, standards for dairy product composition and safety are enforced by national regulators such as India's FSSAI. Success now depends on aligning product development with evolving consumer demands for clean labels and sustainable packaging materials.
Market Dynamics
The market's central dynamic is the push for functional food status, where scientifically validated health benefits, particularly for gut health and protein content, are becoming primary drivers of product development and consumer choice. This is reshaping competitive positioning.
Growth Catalysts
- Probiotic Validation:The EU's strict EFSA guidelines on health claims are compelling manufacturers to use scientifically proven probiotic strains, boosting consumer trust and creating a premium segment for validated functional yogurts.
- Wellness Trends:Demand for high-protein, low-sugar options in the United States, driven by health-conscious consumers, directly fuels the expansion of the Greek yogurt and related high-protein product categories.
- Plant-Based Innovation:Advances in fermentation techniques for non-dairy bases like almond and oat are unlocking market access to vegan and lactose-intolerant populations, diversifying the consumer base beyond traditional dairy.
Market Restraints
- Input Cost Volatility:Fluctuation in the price of raw milk, a primary input, creates significant margin pressure and production cost instability, especially for smaller, non-integrated producers.
- Regulatory Fragmentation:Navigating disparate labeling laws, such as the specific nutritional information mandates from India's FSSAI versus the FDA's requirements, complicates global product rollouts.
- Substitution Risk:The proliferation of alternative convenient health foods, including protein shakes, nutrition bars, and drinkable yogurts, directly competes for the same consumer meal occasions.
Strategic Opportunities
- Geographic Expansion:Markets in Southeast Asia and Latin America, where wellness trends are accelerating, represent significant white space for spoonable yogurt introduction beyond saturated Western markets.
- Culinary Applications:Developing and marketing savory yogurt profiles for use as a cooking ingredient in sauces, dips, and marinades opens a new channel in both food service and home cooking.
- Personalized Nutrition:Direct-to-consumer (DTC) models offering customized yogurt formulations based on individual dietary needs or health goals can create a high-margin, subscription-based revenue stream.
Industry Challenges
- Cold Chain Logistics:Ensuring an unbroken cold chain from factory to consumer is a major operational hurdle and cost center, particularly in regions with underdeveloped transportation and retail infrastructure.
- Certification Hurdles:The time and expense required to obtain and maintain certifications like USDA Organic or Non-GMO Project Verified create barriers to entry and can slow down innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spoonable Yogurt Market |
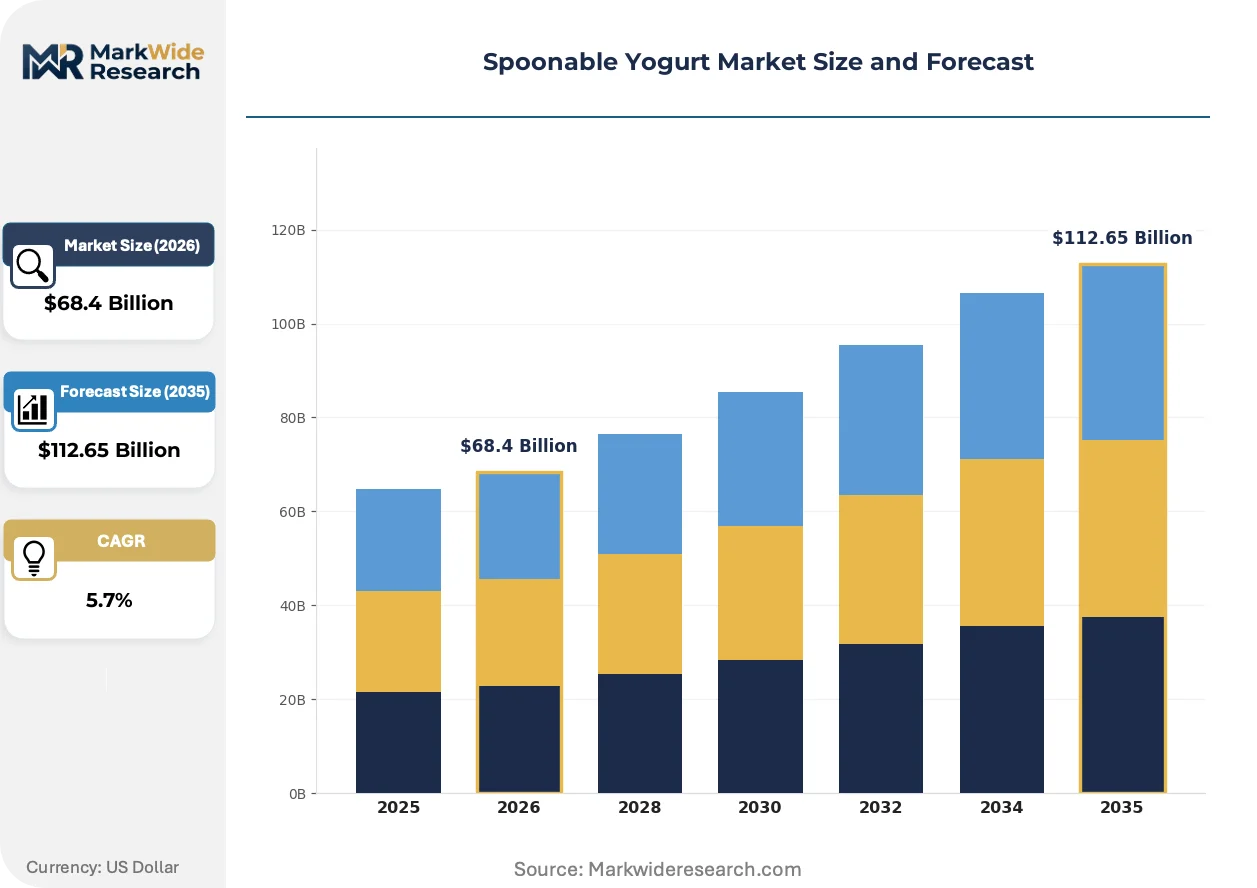
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Regular Yogurt, Organic Yogurt, Flavored Yogurt, Non-Dairy Yogurt Packaging Type: Plastic Cups, Glass Jars, Tetra Pak, Pouches, Aluminum Containers Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Food Service Customer Type: Health Conscious Consumers, Children & Teens, Elderly Population, Athletes, Weight Watchers |
| Companies Covered | Danone SA, FAGE USA Dairy Industry Inc., Nestle SA, Grupo LALA, Fonterra Co-operative Group, Chobani LLC, Arla Foods amba, Hain Celestial Group, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spoonable Yogurt Market Strategic Shifts & Innovations
Product formulation is moving beyond basic nutritional value toward delivering targeted health outcomes, a shift enabled by advances in food science and ingredient technology. Sustainable packaging and transparent sourcing are now integral components of brand value.
Precision fermentation technology allows for the development of specific, high-efficacy probiotic strains and novel non-dairy proteins. Food-tech companies and innovative yogurt brands are adopting these ingredients for products with verifiable health benefits. This advanced methodology is supplanting generic bacterial cultures with targeted ingredients that substantiate specific health claims.
The European Food Safety Authority's (EFSA) rigorous approval process for health claims is a defining regulatory force. This policy compels manufacturers to fund extensive clinical research to validate any functional benefit claims. The probiotic and fortified yogurt segments are most impacted, adjusting marketing and formulations to meet evidence-based standards.
Consumer preference is shifting toward brands demonstrating ethical sourcing and environmental responsibility. This behavioral change disrupts supply chains by favoring products with transparent labeling, such as USDA Organic or Fair Trade certifications. The trend is most pronounced among younger demographics in North America and Europe, who actively seek sustainable packaging.
Spoonable Yogurt Market Segmentation
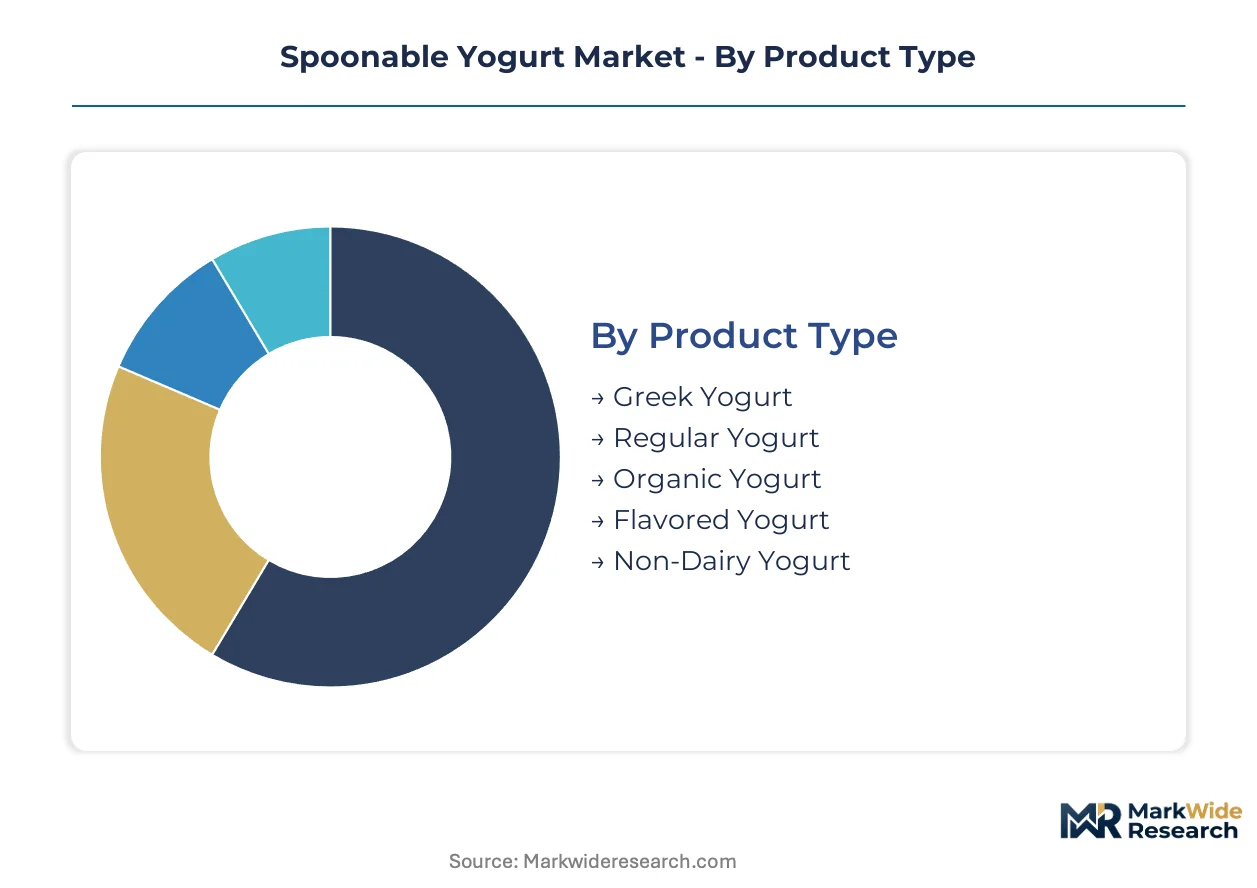
The spoonable yogurt market's segmentation reveals diverse consumer preferences and operational complexities. Understanding these categories allows manufacturers to tailor product development, optimize distribution strategies, and target specific demographic groups effectively. This granular view is essential for navigating competitive pressures and identifying growth opportunities.
Product Type:
Segments like Greek Yogurt and Regular Yogurt maintain strong domestic sales in established Western markets. Conversely, Non-Dairy Yogurt shows increasing export potential to regions with rising vegan populations and lactose intolerance.
- Greek Yogurt:This cultured dairy product undergoes straining to remove whey, resulting in a thicker texture and significantly higher protein content. Demand concentrates in the United States, driven by wellness trends emphasizing satiety and muscle health.
- Non-Dairy Yogurt:Formulated from plant-based milks such as almond, soy, or coconut, this category caters to vegan and lactose-intolerant consumers. Its expansion is rapid across European and North American markets, supported by innovative fermentation techniques.
- Regular Yogurt:Characterized by a less viscous consistency than Greek yogurt, this traditional fermented milk product remains a staple for daily consumption.
- Organic Yogurt:Produced from milk sourced from organically raised cows, this segment appeals to consumers prioritizing natural ingredients and sustainable farming practices.
- Flavored Yogurt:These yogurts incorporate fruit purees, sweeteners, or other flavorings to enhance palatability, particularly popular among younger demographics.
Regular Yogurt commands the established base. The steepest expansion runs through Non-Dairy Yogurt.
Packaging Type:
Packaging formats are primarily dictated by consumer convenience and shelf-life requirements across various retail environments.
- Plastic Cups:These individual or multi-serve containers are the most prevalent packaging solution due to their cost-effectiveness, versatility, and light weight. Demand is widespread, particularly in supermarket channels across all global regions, favored for everyday use.
- Pouches:Flexible, squeezable packaging designed for on-the-go consumption, often featuring resealable caps, targeting children and active adults. This format is gaining traction in North America and Western Europe, driven by convenience and reduced mess.
- Glass Jars:Offering a premium aesthetic and perceived environmental benefit, glass jars are used for artisanal or high-end yogurt products.
- Tetra Pak:Aseptic carton packaging extends shelf life without refrigeration, suitable for drinkable yogurts or larger format spoonable varieties in some markets.
- Aluminum Containers:Less common but used for specific premium or single-serve options, providing robust protection and recyclability.
Plastic Cups secure the largest installed base. Pouches are quickly gaining share in convenience-driven segments.
Distribution Channel:
Distribution channels reflect the varying retail infrastructure and consumer purchasing habits in different markets.
- Supermarkets:Large retail establishments offering a wide selection of products, serving as the primary sales channel for mass-market yogurt brands. These stores remain the dominant point of purchase across developed economies like Germany and Japan.
- Online Retailers:E-commerce platforms facilitating direct-to-consumer sales and home delivery, appealing to tech-savvy consumers seeking convenience. This channel experiences rapid adoption in urban centers across the United States and the United Kingdom.
- Convenience Stores:Smaller retail outlets providing quick access to essential items, catering to impulse purchases and immediate consumption needs.
- Specialty Stores:Boutiques focusing on organic, gourmet, or niche health food products, attracting consumers willing to pay a premium.
- Food Service:Supply to restaurants, cafes, hotels, and institutional settings where yogurt is used as an ingredient or served as part of a meal.
Supermarkets maintain foundational market reach. Online Retailers demonstrate the most dynamic expansion in purchasing pathways.
Customer Type:
Customer types are delineated by their primary motivations and specific dietary requirements for spoonable yogurt products.
- Health Conscious Consumers:Individuals actively seeking functional foods that offer specific health benefits, such as improved gut health or increased protein intake. This group drives demand for probiotic and low-sugar options in countries like Sweden and Canada.
- Athletes:Consumers requiring high-protein and nutrient-dense foods for muscle recovery and energy, often favoring Greek yogurt or fortified varieties. This segment shows strong demand in fitness-oriented societies such as Australia and Brazil.
- Children & Teens:Younger demographics consuming yogurt as a snack or breakfast item, often preferring flavored and convenient pouch formats.
- Elderly Population:Older individuals who consume yogurt for its ease of digestion, calcium content, and nutritional value, often seeking softer textures.
- Weight Watchers:Consumers focused on calorie control and satiety, opting for low-fat, low-sugar, and high-protein yogurt options as part of a managed diet.
Health Conscious Consumers form the largest purchasing bloc. Athletes are creating new demand for performance-oriented products.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Conscious Consumers form the largest purchasing bloc in the spoonable yogurt market, driving demand for functional food options. Demand is notably concentrating in the United States, propelled by wellness trends and product innovation. The European Union's stringent regulations on nutrition and health claims are shaping product formulation and marketing strategies across the continent.
United States
Consumer demand for high-protein, low-sugar options directly fuels the expansion of Greek yogurt and related high-protein product categories. The US Food and Drug Administration (FDA) strictly governs labeling and health claims, ensuring product transparency. Innovation in plant-based alternatives flourishes in California, where numerous food-tech startups develop novel non-dairy bases.
Germany
Consumers prioritize organic and clean-label products, driving growth in the premium spoonable yogurt segment. The European Food Safety Authority (EFSA) mandates rigorous scientific validation for any health claims, influencing product development. Munich serves as a hub for organic food manufacturers, focusing on sustainable packaging solutions.
India
Rising health awareness and urbanization are increasing the consumption of packaged functional dairy products. India's FSSAI enforces specific standards for dairy product composition and safety, ensuring consumer protection. The Delhi-NCR region sees significant investment in cold chain infrastructure, crucial for wider distribution of perishable goods.
Vietnam
Accelerating wellness trends and a growing middle class are expanding the market for convenient and nutritious food options. The country's Ministry of Health regulates food safety and quality, impacting product formulations. Ho Chi Minh City is experiencing a surge in demand for diversified yogurt offerings, including both traditional and innovative flavors.
Canada
Health-conscious consumers actively seek functional foods, particularly those with improved gut health or increased protein intake. Health Canada provides guidelines for nutrition labeling and health claims, influencing product marketing. Toronto's urban centers show strong adoption of plant-based and low-sugar yogurt varieties.
Spoonable Yogurt Market Key Industry Players
Player mix skews toward established dairy giants and specialized health-focused brands, creating a tiered market structure. Global conglomerates leverage their extensive distribution networks, while niche players differentiate through product innovation and targeted consumer segments. Portfolio diversification into plant-based options and geographic expansion into emerging markets represent dominant competitive moves.
Established dairy processors like Danone SA and Nestle SA exemplify the global conglomerate archetype, utilizing their vast manufacturing footprints to scale diverse offerings. Chobani LLC represents a specialized Greek yogurt player, capturing a loyal consumer base with its high-protein focus. General Mills Inc. maintains its market presence through established brand recognition in conventional yogurt segments, adapting its portfolio to evolving consumer demands.
| Leading Market Players |
|---|
| Danone SA |
| FAGE USA Dairy Industry Inc. |
| Nestle SA |
| Grupo LALA |
| Fonterra Co-operative Group |
| Chobani LLC |
| Arla Foods amba |
| Hain Celestial Group |
| General Mills Inc. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for raw milk lock in both supply access and price visibility for major spoonable yogurt producers. These contracts help stabilize input costs against market volatility.
Pricing Analysis
Cost-plus contract patterns with named indexation to dairy commodity futures underpin pricing for conventional spoonable yogurt. Price differentiation stems from USDA Organic certification and high protein content in Greek yogurt varieties. Pricing pressure stems from input cost volatility, particularly for raw milk. Health Conscious Consumers exhibit lower price sensitivity for functional benefits, while Children & Teens segments are highly sensitive to basic flavored yogurt prices.
Supply Chain Analysis
Inbound logistics costs, particularly cold chain infrastructure investment, pose a significant challenge for spoonable yogurt distribution in emerging markets. Supply concentration centers in dairy-rich regions like the United States and Germany, alongside rapidly expanding production in India. Raw material dependencies include fluid milk, plant-based milk alternatives, and specialized probiotic cultures. Cold chain logistics represent a structural risk. Distribution runs through established supermarket channels and rapidly expanding online retailers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spoonable yogurt market is experiencing a cyclical recovery, driven by renewed consumer focus on health and wellness post-pandemic. This trend encourages investment in functional and premium product lines.
For Market Incumbents: Consolidate manufacturing footprints to achieve economies of scale in raw material procurement and cold chain logistics. This strategy mitigates margin pressure from fluctuating input costs and competitive threats from agile plant-based innovators. Invest in precision fermentation technology to develop proprietary probiotic strains, enhancing product differentiation. Control key distribution channels to maintain shelf space dominance.
For New Entrants and Emerging Players: A service-layer gap exists in personalized nutrition platforms offering customized spoonable yogurt formulations based on individual dietary needs. Target the rapidly expanding direct-to-consumer channel in urban centers. White-space opportunities also exist in developing savory yogurt profiles for culinary applications. Go-to-market angles should emphasize unique ingredient sourcing and transparent health benefits.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized plant-based innovators with proprietary fermentation technologies or regional organic producers with strong local supply chains. Long-term viability hinges on companies demonstrating verifiable health claims and sustainable packaging solutions over a five-to-ten year window. A signal to watch is the regulatory harmonization of health claims across major economic blocs like the EU and US.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Portfolio Expansion | Diversifies product offerings to capture vegan and lactose-intolerant consumer segments, expanding total addressable market. |
| Precision Fermentation Investment | Enables development of targeted, scientifically validated probiotic strains, substantiating functional health claims for consumers. |
| Cold Chain Optimization | Reduces operational costs and extends product shelf life, particularly crucial for distribution in developing regional markets. |
| DTC Subscription Model Launch | Establishes direct customer relationships and facilitates personalized nutrition offerings, building high-margin recurring revenue. |
| Sustainable Packaging Transition | Aligns with younger demographics' environmental values, enhancing brand perception and reducing ecological footprint. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EFSA reports, USDA market data, and FSSAI guidelines. Interviews with R&D scientists, brand managers, retail buyers, and supply chain managers provided qualitative insights. This approach ensured bottom-up market dynamics were triangulated against top-down industry trends.
Segmentation dimensions modeled include product type, packaging type, distribution channel, customer type, and key geographic regions. Volume and value CAGRs were derived through a regression analysis of historical data and projected future trends over the projection horizon. Raw milk prices and consumer health spending served as key industry-specific forecast inputs.
Underlying assumptions cover stable regulatory environments and consistent consumer wellness trends, with deviation risk concentrated in raw material price volatility or new competitive threats. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Concentrate Market
Dairy Products
Condensed Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Europe Cheese Market
Dairy Products
Goat Milk Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Middle East Dairy Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Plain Yogurt Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Sheep Milk Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Lactic Butter Market