
 Singapore Plant-Based Food and Beverages Market | 2026-2036
Singapore Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Plant-Based Food and Beverages Market Outlook
The gap between premium plant-based dining and economy meat substitutes is expanding. High-end restaurants in Marina Bay and Dempsey Hill serve cell-cultured and precision-fermented proteins at price points that distance them from mass-market soy nuggets. Impossible Foods leverages its heme technology leadership to anchor premium burger placements across Singapore's hotel and casual dining sectors. OATSIDE sustains its oat milk dominance through café channel control and localized flavor development. FairPrice competes on private-label dairy alternatives that undercut imported brands in its island-wide supermarket network.
Singapore plant-based food and beverages encompass protein-rich formulations derived from soy, pea, oat, coconut, and cell-cultured matrices, processed through extrusion, fermentation, or precision biology to replicate sensory and nutritional profiles of animal-derived products. These formulations serve commercial foodservice, retail grocery, and direct-to-consumer channels seeking reduced environmental impact and cholesterol profiles. Dairy alternatives lead volume within the product type dimension, buoyed by oat and barista-format milk penetration across independent cafés and chain coffee outlets. Meat alternatives represent the fastest-growing product type as local brands like TurtleTree advance cultivated protein platforms toward commercial scale. The distribution channel structure concentrates margin pools in restaurants and online retail, where subscription models and direct brand relationships reduce price transparency.
Singapore's Health Promotion Board actively promotes plant-forward dietary guidelines through its My Healthy Plate framework, while the Singapore Food Agency governs novel food safety assessments including cultivated meat and precision fermentation products. The SFA's regulatory clarity on alternative proteins has attracted regional headquarters decisions from multiple international brands seeking ASEAN market access. Enterprise Singapore's standards development initiatives around plant-based protein labeling further shape product formulation and marketing claims. Stakeholders must monitor how the SFA evolves its novel food regulatory pathway as cultivated protein applications broaden beyond meat into dairy and seafood analogues.
Market Dynamics
The Singapore Food Agency's novel food regulatory framework is compressing product registration timelines for cultivated proteins while the Health Promotion Board's My Healthy Plate guidelines reshape institutional procurement specifications across foodservice channels.
Growth Catalysts
- Health Promotion Board guidelines:Institutional catering contracts in public hospitals and universities now mandate plant-forward menu ratios, creating guaranteed offtake volumes for certified suppliers.
- Precision fermentation:Local biotechnology infrastructure at Tuas Biomedical Park enables domestic production of whey and casein analogues without import dependency.
- Orchard Road hotel clusters:Premium foodservice demand concentrates in this district, where international chain properties compete on sustainability credentials through plant-based dining programs.
Market Restraints
- Oat protein concentrate imports:Supply concentrates among Nordic and North American processors, exposing local oat milk formulators to currency volatility and shipping cost spikes.
- Sensory replication limits:Extruded pea and soy textures fail to replicate the fibrous bite of whole-muscle cuts, constraining adoption in Chinese cuisine segments where mouthfeel is paramount.
- Novel food safety assessments:The Singapore Food Agency's pre-market approval pathway for cell-cultured proteins extends commercialization timelines by 18-24 months versus conventional food additives.
Strategic Opportunities
- Marina Bay Sands integrated resorts:High-volume banquet and convention catering within this precinct offers scalable penetration points for premium plant-based protein contracts.
- Singapore Food Agency regulatory clarity:ASEAN market access protocols allow approved domestic novel food manufacturers to export cultivated proteins into neighboring jurisdictions with mutual recognition arrangements.
- Direct-to-subscription models:Cold-chain logistics integration with Grab and Foodpanda platforms enables weekly plant-based meal kit delivery bypassing traditional supermarket markup layers.
Industry Challenges
- Cell culture scientist scarcity:Local talent pools lack depth in bioreactor operations and scaffold engineering, forcing reliance on foreign recruitment with visa processing friction.
- Halal certification timelines:Muis approval processes for precision-fermented ingredients lack precedent, creating uncertainty for Muslim-majority export markets.
- Café equipment retrofit costs:Independent coffee outlets face capital barriers when switching from dairy steam wands to oat milk-compatible systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Plant-Based Food and Beverages Market |
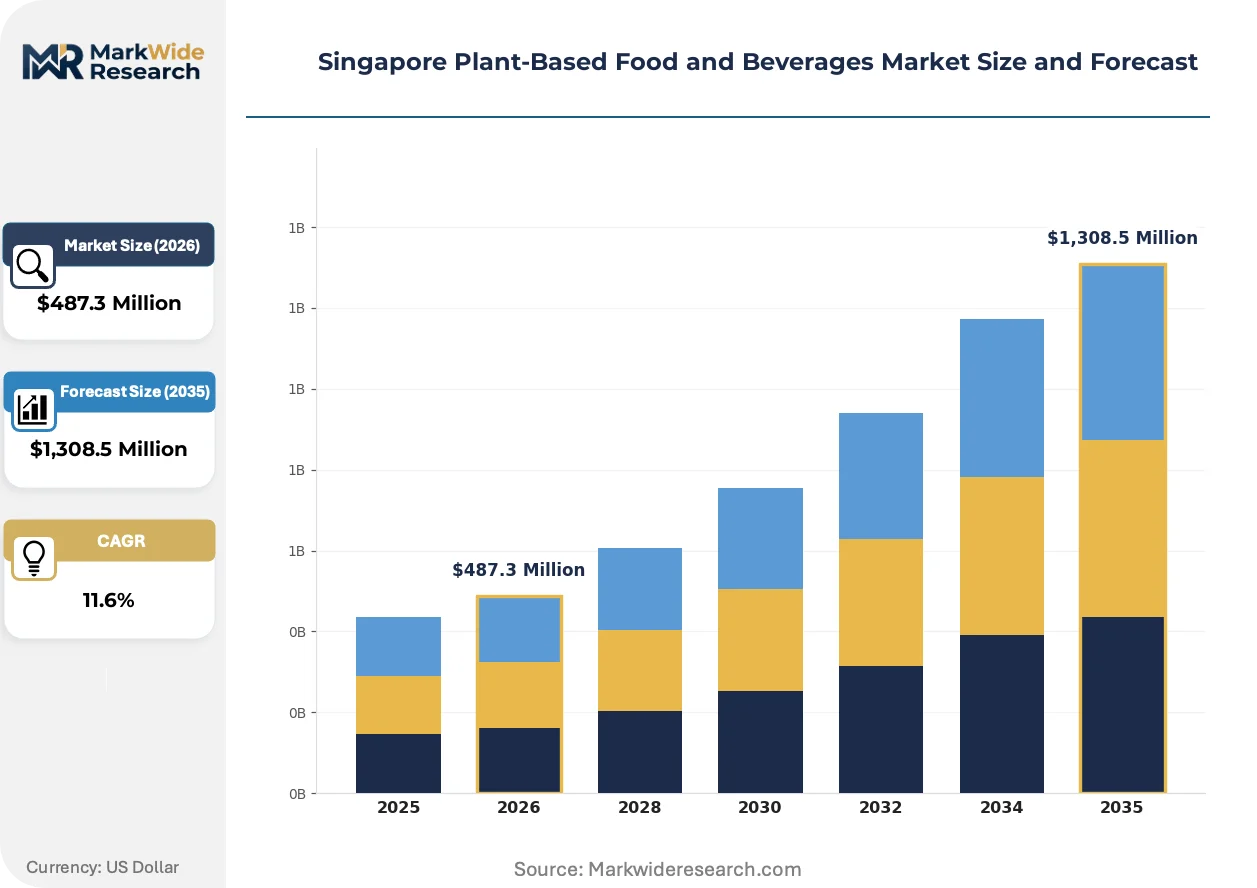
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snacks, Beverages Distribution Channel: Supermarkets, Online Retail, Health Stores, Restaurants Customer Type: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Danone SA, Yeo Hiap Seng, Impossible Foods, Co+Nut+Ink, FairPrice, Beyond Meat Inc., OATSIDE, TurtleTree, Vitasoy International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Plant-Based Food and Beverages Market Strategic Shifts
Biotechnology convergence with traditional food processing is collapsing the cost curve for functional protein ingredients while reshaping where value accrues in the supply chain.
Heme protein technology is integrating into plant-based patty formulations to replicate the Maillard reaction and bleeding cues of ground beef. Hotel and casual dining chains across the Central Business District are adopting these formulations at pace, replacing legacy vegetable-protein blends within 18-month menu cycles. This integration is compressing the performance gap between plant-based and conventional meat in high-heat cooking applications.
Singapore Food Agency guidelines on novel food safety assessments are formalizing toxicology data requirements for cultivated seafood and dairy analogues. The industrial consequence is a bifurcation between venture-backed firms with dedicated regulatory affairs teams and smaller entrants facing compliance cost barriers. Precision-fermented dairy proteins are responding fastest, leveraging existing GRAS-equivalent frameworks to accelerate market entry.
Flexitarian purchasing patterns are rotating demand toward hybrid products combining plant and cultivated protein fractions rather than pure analogues. Premium supermarket channels in Dempsey Hill and Tanglin are displacing conventional meat departments with blended-format merchandising. This behavioral shift is most visible among millennial households in private condominium clusters, where weekly grocery baskets now average three protein source categories versus historical single-source dominance.
Singapore Plant-Based Food and Beverages Market Segmentation
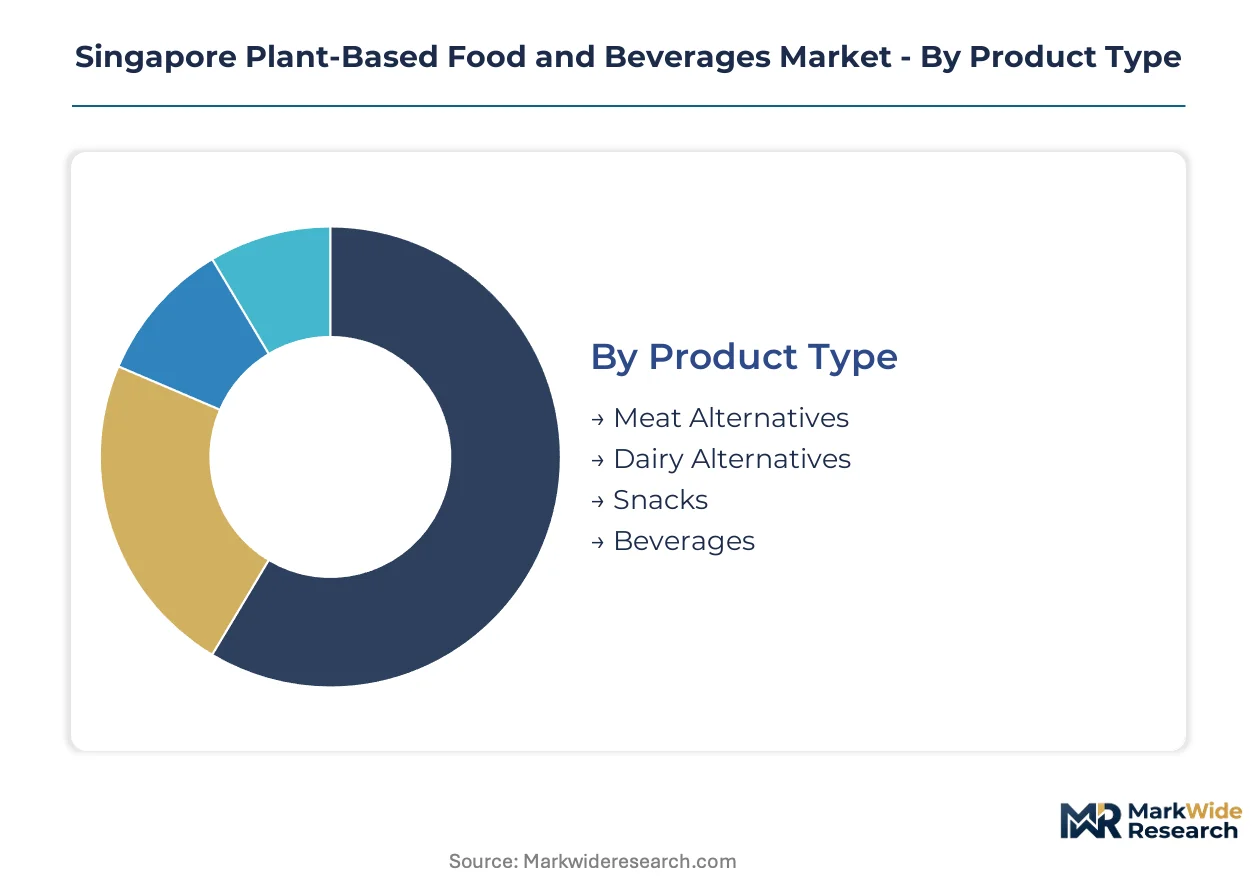
Segmentation in Singapore's plant-based market exposes how regulatory pathways and channel economics fragment commercial opportunity. Each dimension carries distinct certification burdens and margin structures that determine viable entry strategies.
Product Type:
Dairy alternatives require only standard food manufacturing licenses from the Singapore Food Agency, while meat alternatives face novel food assessments if incorporating cultivated protein fractions.
- Meat Alternatives:Extruded soy and pea protein formulations dominate current volume, with precision-fermented heme proteins gaining traction in foodservice applications. Demand concentrates in hotel banquet operations across Orchard Road, where sustainability procurement mandates now require plant-based protein quotas in catering contracts.
- Dairy Alternatives:Oat and barista-format milk formulations lead volume through café channel penetration. Independent coffee outlets in Tiong Bahru and Joo Chiat drive oat milk adoption, though equipment retrofit costs create friction for smaller operators switching from dairy steam systems.
- Snacks:Seaweed, mushroom, and legume-based formats occupy shelf-stable retail positioning with minimal regulatory overhead.
- Beverages:Ready-to-drink protein shakes and functional plant milks target convenience store and online subscription channels.
Dairy alternatives sit at the top of the volume ranking, with meat alternatives climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with direct-to-consumer models bypassing retail markup layers but absorbing cold-chain logistics costs.
- Supermarkets:NTUC FairPrice and Cold Storage dominate island-wide grocery distribution, with private-label dairy alternatives undercutting imported brands on price. Shelf placement fees and promotional slotting costs compress margins for emerging entrants.
- Online Retail:Shopee and Lazada platforms enable direct brand relationships with flexitarian households in private condominium clusters. Subscription models through RedMart and Amazon Singapore reduce customer acquisition costs for repeat-purchase categories like oat milk.
- Health Stores:Unity Pharmacy and specialized organic retailers serve premium-positioned products with certified organic or non-GMO claims.
- Restaurants:Quick-service chains and hotel foodservice operations concentrate demand in the Central Business District and Marina Bay precincts.
Supermarkets retain the largest volume share, though online retail is expanding most quickly.
Customer Type:
Customer classification reveals purchasing motivation heterogeneity that shapes product positioning and channel strategy.
- Flexitarians:This segment drives market expansion through hybrid consumption patterns, purchasing plant-based proteins alongside conventional meat. Weekly grocery baskets in Tanglin and Dempsey Hill now average three protein source categories, with flexitarian households willing to pay premium prices for sensory replication.
- Health-Conscious Consumers:Cholesterol reduction and cardiovascular health motivations dominate purchasing decisions, particularly among aging demographics in public housing estates. Health Promotion Board My Healthy Plate guidelines reinforce this behavioral pattern through institutional messaging.
- Vegetarians:Long-established dietary practice creates stable baseline demand through traditional Buddhist and Hindu communities.
- Vegans:Ethical and environmental motivations sustain premium price tolerance, though this remains the smallest addressable segment.
Flexitarians command the largest volume position, with health-conscious consumers gaining share fastest.
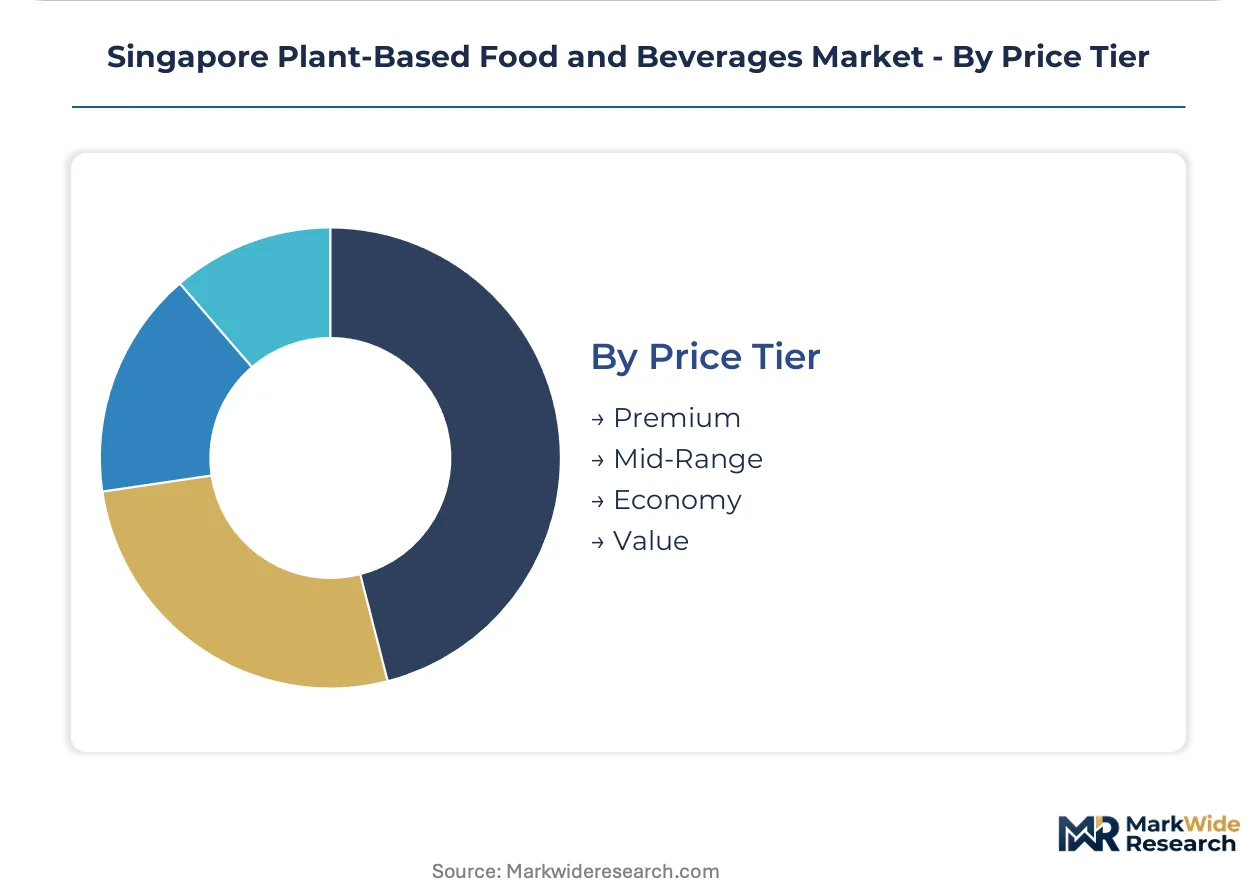
Price Tier:
Price stratification separates products by ingredient quality, certification level, and channel positioning rather than manufacturing scale alone.
- Premium:Cell-cultured and precision-fermented proteins occupy this tier, with heme technology formulations and novel food regulatory approvals justifying price multiples over conventional plant proteins. Marina Bay Sands integrated resorts and Dempsey Hill dining clusters anchor this segment.
- Mid-Range:Established oat milk brands and extruded pea protein products compete here, balancing sensory performance with accessible pricing for mass-market foodservice.
- Economy:Private-label soy milk and textured vegetable protein formats serve price-sensitive institutional catering and public hospital contracts.
- Value:Basic tofu and tempeh products maintain traditional positioning in wet markets and neighborhood provision shops.
Premium tier products generate the highest margins per unit, with mid-range formats scaling fastest in absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology talent clusters at Tuas Biomedical Park anchor Singapore's plant-based protein manufacturing capacity, drawing cell culture scientists from regional universities and multinational R&D centers.
Central Business District
Hotel banquet operations and quick-service chains drive premium plant-based protein procurement, with sustainability mandates from multinational corporate headquarters reshaping foodservice specifications. The Singapore Food Agency's novel food regulatory framework compresses product registration timelines for cultivated meat entrants. Marina Bay Sands integrated resorts anchor high-volume contract opportunities for precision-fermented protein suppliers.
Orchard Road
International chain properties compete on plant-forward dining credentials, creating concentrated demand for heme technology burger formulations and oat milk barista formats. Health Promotion Board procurement guidelines filter into institutional catering contracts across adjacent medical and educational facilities. Paragon and ION Orchard retail clusters host flagship plant-based dining concepts targeting flexitarian consumers.
Tiong Bahru
Independent café density drives oat milk adoption velocity, with equipment retrofit decisions by owner-operators determining brand-level market share outcomes. Enterprise Singapore standards development initiatives on plant-based protein labeling shape product claims visible in neighborhood retail. The heritage district's food culture incubates hybrid protein concepts blending traditional Southeast Asian preparations with cultivated seafood analogues.
Joo Chiat
Specialty coffee outlet expansion creates downstream demand for dairy alternative formulations optimized for high-heat steaming performance. Cold-chain logistics integration with Grab and Foodpanda platforms enables weekly plant-based meal kit delivery penetration. Peranakan culinary heritage intersects with precision-fermented protein development as local chefs experiment with cultured meat renditions of traditional dishes.
Tuas Biomedical Park
Precision fermentation infrastructure enables domestic whey and casein analogue production without import dependency on Nordic oat protein concentrate suppliers. Cell culture scientist scarcity constrains bioreactor operations scaling, forcing reliance on foreign recruitment pipelines. TurtleTree and venture-backed biotechnology firms cluster manufacturing and R&D functions within this precinct to exploit regulatory proximity to Singapore Food Agency technical assessors.
Singapore Plant-Based Food and Beverages Market Competitive Environment
Top-tier vendors anchor premium cultivated protein and precision-fermented dairy tiers, while mid-range extruded plant protein specialists and economy private-label manufacturers occupy volume positions below. The vendor base stratifies across heme technology leaders, oat milk format innovators, and supermarket private-label operators with island-wide distribution control. Biotechnology convergence archetypes compete against traditional food processing incumbents, with regulatory affairs capability separating venture-backed entrants from compliance-constrained smaller players. Dominant competitive moves include strategic partnerships between ingredient technology licensors and foodservice operators, plus capacity expansion into Tuas Biomedical Park fermentation infrastructure.
Among Singapore-headquartered biotechnology ventures, TurtleTree occupies a position representing cultivated dairy protein archetypes, while OATSIDE exemplifies oat milk format dominance through café channel control. Impossible Foods anchors the heme technology tier in premium foodservice placements. Danone SA and Beyond Meat Inc. represent multinational incumbent archetypes competing across retail and foodservice vectors with established brand equity and regulatory navigation resources. Yeo Hiap Seng and Vitasoy International occupy positions within traditional beverage manufacturer archetypes adapting portfolio mix toward plant-forward formulations. FairPrice exemplifies private-label operator archetypes with pricing leverage through island-wide supermarket network control.
| Leading Market Players |
|---|
| Danone SA |
| Yeo Hiap Seng |
| Impossible Foods |
| Co+Nut+Ink |
| FairPrice |
| Beyond Meat Inc. |
| OATSIDE |
| TurtleTree |
| Vitasoy International |
| Others |
Value Chain & Pricing Dynamics
Venture-backed biotechnology ventures with Singapore Food Agency novel food approvals command pricing premiums that cascade through distributor markups to foodservice operators. Their concentrated ownership structures enforce margin discipline while oat milk specialists with café channel lock-in resist price erosion through format exclusivity.
Pricing Analysis
The bundled service split separates ingredient supply contracts from technical advisory and menu development services. Three-tier pricing structure across premium, standard, and economy levels stratifies by Singapore Food Agency certification status and heme technology integration. Pricing pressure stems from private-label oat milk expansion through FairPrice's island-wide network compressing mid-tier margins. Institutional catering buyers in public hospitals exhibit highest price sensitivity while Marina Bay Sands integrated resorts tolerate premium multiples for cultivated protein novelty.
Supply Chain Analysis
Regional distribution centers at Tuas Biomedical Park anchor hub-and-spoke patterns radiating to Orchard Road hotel clusters and Central Business District foodservice nodes. Raw material sourcing draws from Nordic oat protein concentrate processors, North American pea protein isolate suppliers, and domestic precision fermentation infrastructure. Single-source vulnerability concentrates in heme protein ingredient licensing from US technology holders. Distribution runs through cold-chain logistics partnerships with Grab and Foodpanda platforms for direct-to-consumer subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Singapore's plant-based sector rests on precision fermentation cost curves collapsing faster than extruded protein commodity benchmarks, enabling premium-tier producers to capture widening spreads.
For Market Incumbents: Deploy regulatory affairs capacity as a defensive moat. TurtleTree and OATSIDE should deepen Singapore Food Agency relationship management to accelerate novel food approval timelines for competitors. Incumbents must secure exclusive heme technology licensing before multinational ingredient suppliers enter direct foodservice partnerships. Channel control through equipment financing programs for café steam wand retrofits locks out oat milk challengers. For New Entrants and Emerging Players: Precision-fermented dairy protein platforms offer the clearest technology-first wedge. White-space targets include Halal-certified precision fermentation for Muslim-majority ASEAN export markets and hybrid plant-cultured protein formats for Chinese cuisine mouthfeel requirements. New entrants should pursue direct-to-subscription models through RedMart partnership rather than supermarket slotting fee battles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-range extruded protein specialists facing margin compression from private-label competition. Long-term viability favors biotechnology convergence plays with in-house regulatory affairs teams and Tuas Biomedical Park manufacturing presence. Investors should monitor Singapore Food Agency novel food approval velocity as the inflection signal for cultivated protein commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Domestic whey analogue production at Tuas Biomedical Park eliminates Nordic import dependency. |
| Novel Food Regulatory Investment | Dedicated SFA liaison teams compress cultivated protein approval timelines versus generalist competitors. |
| Café Equipment Financing Program | Steam wand retrofit subsidies lock in oat milk format exclusivity across independent coffee outlets. |
| Halal Certification Precedent | Muis approval for precision-fermented ingredients opens Muslim-majority ASEAN export corridors. |
| Direct-to-Subscription Launch | Cold-chain integration with Foodpanda bypasses FairPrice markup layers for flexitarian households. |
Study Parameters
Bottom-up foodservice procurement modeling reconciled against top-down ingredient import tracking forms the analytical core of this study. Primary interviews with Singapore Food Agency regulatory assessors, hotel procurement directors, café owner-operators, and biotechnology R&D heads combined with secondary validation from SFA novel food safety assessment databases, Enterprise Singapore standards documentation, and Health Promotion Board My Healthy Plate institutional procurement records. Trade data from Nordic oat protein concentrate exporters and Tuas Biomedical Park facility registrations anchored supply-side triangulation.
Input-output matrices mapped product type, distribution channel, customer motivation, and price tier dimensions across the analysis window. CAGRs derived from segment-level volume build-ups reconciled against macroeconomic consumption elasticity assumptions. Forecast inputs incorporated Singapore Food Agency regulatory pathway evolution, precision fermentation yield improvement curves, and café channel equipment retrofit penetration rates.
The model holds under stable SFA novel food assessment timelines; deviation in Halal certification precedent establishment or heme protein import licensing restrictions would shift commercialization trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
China Rice Protein Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Canada Plant-Based Food and Beverages Market