
 Evaporated Filled Milk Market | 2026-2036
Evaporated Filled Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Evaporated Filled Milk Market Analysis
Vegetable oil is expanding its share as the dominant fat source in evaporated filled milk formulations, displacing butterfat on cost and shelf-stability grounds. FrieslandCampina leverages integrated dairy streams to preserve quality benchmarks across European markets. Arla Foods anchors its position through cooperative sourcing networks that stabilize skim milk solids supply. Promasidor dominates West African distribution corridors where evaporated filled milk serves as an affordable protein staple.
Evaporated filled milk denotes a recombined dairy product wherein skim milk solids are reconstituted with vegetable fats and homogenized to approximate the sensory and functional properties of full-cream evaporated milk, typically containing minimum milk protein levels and adjusted fat content between 7.5% and 15% depending on regional standards. The product serves primarily as a cooking and beverage ingredient in price-sensitive markets where fresh milk infrastructure remains underdeveloped. Whole milk formulations occupy the largest volume share among product types due to their direct substitutability for traditional evaporated milk in culinary applications. Cans retain dominance in packaging type as metal provides superior light and oxygen barriers for tropical shelf conditions, though Tetra Packs are gaining traction in urban retail channels where convenience and portion control matter.
FDA standards of identity in the United States govern compositional labeling for filled milk products, while EFSA and Codex Alimentarius frameworks shape permissible fat replacer categories and additive thresholds across European and export-oriented manufacturing bases. BIS fortification requirements in India mandate vitamin A and D enrichment that elevates production complexity for entrants lacking premix integration capabilities. Stakeholders must monitor evolving plant-oil sourcing regulations and regional dairy analogue definitions to preserve market access across fragmented national regimes.
Market Dynamics
Vegetable fat substitution for butterfat is compressing input costs while FSSAI fortification mandates in India and EU Farm to Fork standards are rewriting compositional compliance thresholds across manufacturing bases.
Growth Catalysts
- Philippines Demand Concentration:Alaska Milk Corporation and Promasidor anchor supply chains where evaporated filled milk serves as an affordable protein staple for reconstituted milk products.
- BIS Fortification Mandates:India's vitamin A and D enrichment requirements elevate production complexity but create captive demand for integrated premix capabilities among compliant manufacturers.
- Southeast Asia Bakery Absorption:Plant-based fat replacers gain formulation share as bakery applications across Thailand, Vietnam, and Indonesia absorb larger volumes for cost-optimized dairy analogues.
Market Restraints
- Palm Oil Price Volatility:Vegetable oil input costs fluctuate with Malaysian and Indonesian export policies, squeezing margin predictability for reformulated products.
- Skim Milk Solids Concentration:Cooperative sourcing networks in Northern Europe control premium-grade protein streams, limiting second-tier manufacturer access to consistent supply.
- FDA Standards of Identity:United States labeling requirements for filled milk products create formulation lock-in that resists rapid fat-source pivots.
Strategic Opportunities
- West African Distribution Corridors:Promasidor's established routes demonstrate scalable penetration potential where fresh milk infrastructure remains underdeveloped.
- Tetra Pack Channel Migration:Urban retail channels in Metro Manila and Jakarta favor convenience packaging over traditional cans for portion-controlled consumption.
- EU Green Deal Alignment:Sustainable palm oil certification requirements create differentiation premiums for supply chains meeting EFSA additive thresholds.
Industry Challenges
- Premix Integration Complexity:Vitamin fortification requires specialized blending equipment that extends capex recovery timelines for mid-scale entrants.
- Homogenization Precision Gap:Fat globule size distribution control demands process engineering expertise scarce outside established dairy technology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evaporated Filled Milk Market |
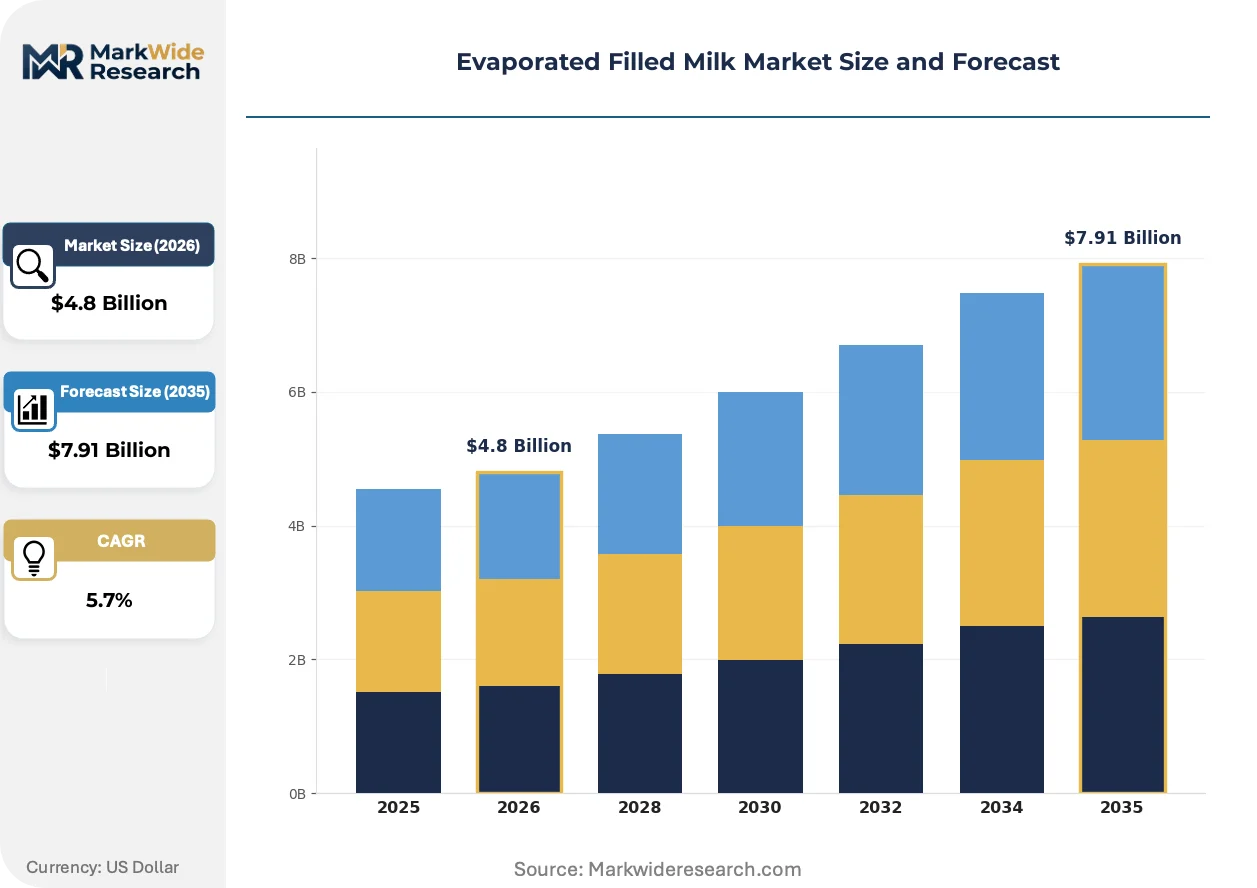
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened Condensed, Whole Milk, Low-Fat Milk, Non-Fat Milk Packaging Type: Cans, Tetra Packs, Bottles, Pouches End User: Food Service Industry, Retail Consumers, Bakeries, Creameries Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Distributors |
| Companies Covered | Fonterra, Alaska Milk Corporation, FrieslandCampina, Delta Food Industries, Dana Dairy Group, Nestlé, Fraser and Neave, Promasidor, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evaporated Filled Milk Market Emerging Trajectories
Formulation science and packaging engineering are converging to extend shelf stability while regulatory frameworks fragment across national dairy analogue definitions.
High-pressure homogenization systems are expanding into evaporated filled milk processing lines to achieve butterfat-mimetic mouthfeel without dairy lipids. Southeast Asian contract manufacturers adopt these units aggressively to meet bakery-sector texture specifications. The technology is expanding into mid-tier production facilities previously limited to conventional mixing equipment, compressing quality differentiation between regional and multinational suppliers.
EFSA's evolving stance on novel fat replacer categories is reshaping permissible additive portfolios for European export-oriented plants. Manufacturers must reformulate to meet tightened compositional standards under the EU's Farm to Fork Strategy sustainability benchmarks. Dairy analogue exporters to Germany and France face accelerated compliance timelines as notified bodies interpret Codex Alimentarius thresholds more stringently.
Urban convenience stores are displacing traditional sari-sari micro-retail as the dominant channel for single-serve evaporated filled milk in Philippine metropolitan zones. Younger households prioritize portion control and refrigeration-free storage over bulk can formats. This behavioral pivot concentrates volume in modern trade formats where Tetra Pak shelf presence determines brand visibility.
Evaporated Filled Milk Market Segmentation
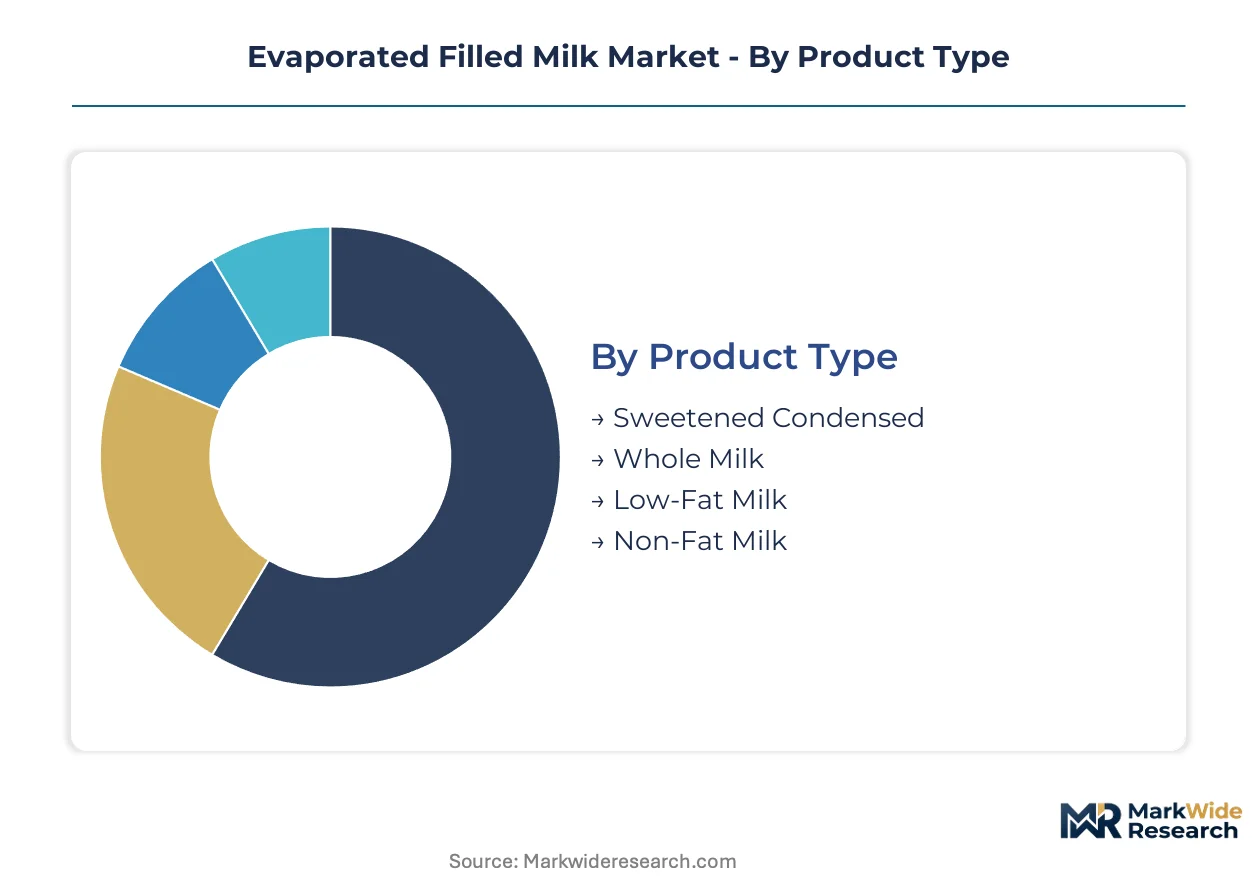
Evaporated filled milk manufacturers calibrate formulation density and packaging format against distinct price elasticities across household and institutional buyers. Segment boundaries sharpen where fortification mandates intersect with channel-specific shelf-life requirements.
Product Type:
Volume leadership concentrates in whole milk formulations while low-fat variants command premium positioning in health-conscious urban clusters.
- Whole Milk:Formulations containing 7.5% to 15% vegetable fat content replicate the mouthfeel and functional properties of traditional evaporated milk. Philippine households and Southeast Asian bakeries absorb the largest volumes where direct substitutability for full-cream evaporated milk drives procurement decisions.
- Sweetened Condensed:Higher sugar concentration extends shelf stability and reduces refrigeration dependency in tropical climates. West African distribution corridors favor this format where ambient storage infrastructure dominates and evaporated filled milk serves as an affordable protein staple.
- Low-Fat Milk:Reduced vegetable fat content meets FSSAI compositional thresholds for health-positioned dairy analogues in Indian metropolitan markets.
- Non-Fat Milk:Skim milk solids reconstituted without added vegetable fats targets institutional buyers with strict fat-content specifications.
Mature deployment sits with Whole Milk. Newer deployment is concentrated in Low-Fat Milk.
Packaging Type:
Barrier properties and unit economics diverge sharply between metal containers and flexible formats across ambient and cold chain channels.
- Cans:Metal packaging delivers superior light and oxygen barriers essential for tropical shelf conditions exceeding 24 months. Traditional sari-sari micro-retail in Philippine provinces and wholesale distributors across Indonesia rely on this format for bulk procurement and storage resilience.
- Tetra Packs:Aseptic carton technology enables portion-controlled single-serve formats favored by urban convenience stores in Metro Manila and Jakarta. Younger households prioritize refrigeration-free storage and visual shelf presence in modern trade formats.
- Bottles:Polymer containers target food service industry buyers requiring transparent stock visibility and easy-pour functionality.
- Pouches:Flexible film formats reduce material cost and shipping weight for price-sensitive retail consumers in rural distribution corridors.
Established supply chains anchor Cans. Channel migration is accelerating fastest into Tetra Packs.
End User:
Institutional procurement scales through contract manufacturing relationships while household demand fragments across traditional and modern retail.
- Food Service Industry:Restaurants, hotels, and institutional kitchens purchase evaporated filled milk in bulk formats for sauce bases, soups, and dessert preparations. Thai and Vietnamese food manufacturers specify high-pressure homogenized products to achieve butterfat-mimetic texture in cost-optimized formulations.
- Retail Consumers:Household reconstitution for direct consumption or tea and coffee whitening drives repeat purchase frequency. Philippine urban households increasingly favor Tetra Pack single-serve units over traditional cans.
- Bakeries:Plant-based fat replacers gain formulation share as Thailand, Vietnam, and Indonesia absorb larger volumes for cost-optimized dairy analogues in pastry and bread applications.
- Creameries:Ice cream and confectionery manufacturers source evaporated filled milk as a functional ingredient in frozen dessert formulations.
Contracted volume concentrates with Food Service Industry. Volume expansion is climbing the fastest among Bakeries.
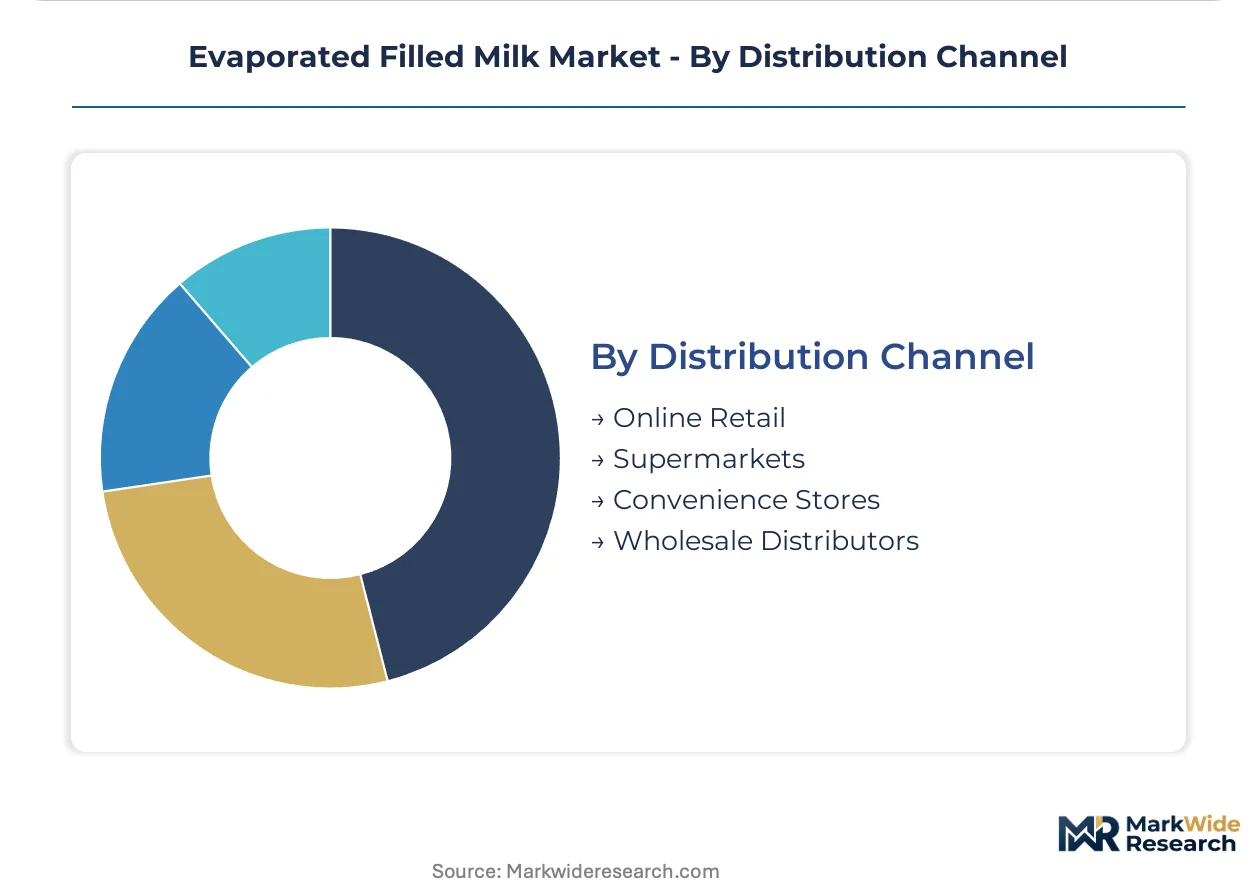
Distribution Channel:
Route-to-market economics separate high-frequency replenishment formats from bulk procurement relationships.
- Supermarkets:Organized retail chains in Philippine and Indonesian metropolitan zones stock multiple product types and packaging formats. Shelf space allocation favors brands with integrated premix capabilities meeting BIS fortification requirements.
- Wholesale Distributors:Aggregated procurement from manufacturers supplies traditional trade networks and institutional buyers across underdeveloped fresh milk infrastructure. Promasidor's established West African routes demonstrate scalable penetration potential.
- Convenience Stores:Urban proximity retail displaces sari-sari micro-retail for single-serve evaporated filled milk in Philippine metropolitan zones. Portion control and impulse purchase behavior concentrate volume in modern trade formats.
- Online Retail:E-commerce platforms aggregate niche product variants for diaspora consumers and specialty food service procurement.
Established penetration sits with Wholesale Distributors. Channel investment is expanding most quickly into Convenience Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine economic zones and Indonesian special economic corridors concentrate evaporated filled milk manufacturing through tax incentives on dairy reconstitution facilities. These zones attract multinational processors seeking tariff advantages on vegetable fat imports and skim milk solids aggregation.
Philippines
Household reconstitution demand and bakery-sector procurement absorb the largest regional volumes. FSSAI fortification mandates on vitamin A and D enrichment shape import standards for reconstituted milk products entering duty-free zones. Metro Manila and Cebu host the densest processing clusters where Alaska Milk Corporation and Promasidor operate integrated reconstitution facilities.
Indonesia
Urban convenience stores in Jakarta and Surabaya displace traditional wholesale channels for single-serve formats. BIS fortification requirements on dairy analogues elevate compliance costs for entrants lacking premix integration capabilities. The Batam free trade zone concentrates contract manufacturing for Southeast Asian bakery applications.
India
FSSAI mandates on vitamin A and D enrichment create captive demand for integrated premix capabilities among compliant manufacturers. BIS compositional standards govern minimum protein levels in reconstituted dairy products. Maharashtra and Gujarat host the primary reconstitution facilities serving metropolitan retail chains in Mumbai and Ahmedabad.
Thailand
Food service industry procurement and bakery-sector absorption drive institutional volume growth. EFSA additive thresholds shape export-oriented manufacturing for European-bound dairy analogues. Bangkok and Chonburi province concentrate high-pressure homogenization capacity for butterfat-mimetic texture production.
Vietnam
Ho Chi Minh City and Hanoi metropolitan zones favor Tetra Pack formats in modern trade channels. The country's national food safety regulator enforces compositional labeling standards for filled milk products. Da Nang and Hai Phong process reconstituted dairy for regional bakery and confectionery supply chains.
Evaporated Filled Milk Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational dairy cooperatives controlling premium-grade skim milk solids supply while regional processors dominate price-sensitive distribution corridors. Market structure concentrates around three strategic archetypes: cooperative-owned dairy giants with backward integration into milk powder sourcing, Southeast Asian specialists with entrenched sari-sari retail relationships, and Middle Eastern contract manufacturers serving African export markets. Competitive moves center on premix integration capabilities for fortification compliance and high-pressure homogenization technology licensing for texture differentiation.
Within the cooperative dairy tier, FrieslandCampina and Arla Foods exemplify European-sourced supply chain control through member-owned milk solids aggregation. Alaska Milk Corporation anchors Philippine market presence through Metro Manila retail penetration. Promasidor occupies a position exemplifying West African distribution corridor mastery where evaporated filled milk serves as an affordable protein staple.
| Leading Market Players |
|---|
| Fonterra |
| Alaska Milk Corporation |
| FrieslandCampina |
| Delta Food Industries |
| Dana Dairy Group |
| Nestlé |
| Fraser and Neave |
| Promasidor |
| Arla Foods |
| Others |
Supply Flow & Price Mechanics
Vegetable oil input costs transmit directly from Malaysian and Indonesian palm oil export policies through to wholesale pricing tiers, with integrated processors capturing margin buffers unavailable to toll manufacturers dependent on spot markets.
Pricing Analysis
Short lead-time premiums attach to Tetra Pack single-serve formats in Metro Manila convenience channels, while bulk can procurement through wholesale distributors commands spot-market discounts. Pricing stratifies across premium, standard, and economy tiers based on fortification certification status and high-pressure homogenization processing grade. Cost compression in economy-tier formulations is intensifying because palm oil price volatility squeezes margin predictability for non-integrated manufacturers. Food service industry buyers exhibit lowest price sensitivity due to contract manufacturing relationships, whereas rural retail consumers demonstrate highest elasticity to unit cost shifts.
Supply Chain Analysis
Skim milk solids supply rests on cooperative sourcing networks in Northern Europe, vegetable fat inputs draw from Malaysian and Indonesian plantation clusters, and premix integration capabilities concentrate in Indian pharmaceutical-grade blending facilities. Raw material dependencies span palm oil derivatives, spray-dried milk protein concentrates, and vitamin A/D premix formulations. Single-source vulnerability in premium-grade protein streams limits second-tier manufacturer access to consistent supply. Distribution runs through wholesale distributor networks in underdeveloped fresh milk infrastructure zones, with modern trade channels capturing urban volume migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure homogenization systems are displacing conventional mixing equipment as the dominant processing technology, compressing quality differentiation between established multinationals and emerging regional processors.
For Market Incumbents: Deploy premix integration capabilities as a defensive moat against FSSAI and BIS fortification compliance requirements that elevate production complexity for non-integrated entrants. Anchor backward integration into skim milk solids sourcing through cooperative membership structures that preserve supply priority during protein stream shortages. Channel control investments in Tetra Pack production lines capture urban convenience store volume migration away from traditional sari-sari micro-retail. For New Entrants and Emerging Players: Capture West African distribution corridor white space where Promasidor's established routes demonstrate scalable penetration potential in underdeveloped fresh milk infrastructure. Target Vietnamese and Indonesian bakery-sector contract manufacturing as the most penetrable application segment, where plant-based fat replacer formulation demand absorbs volume without incumbent brand loyalty barriers. Pursue toll manufacturing partnerships with Southeast Asian high-pressure homogenization facility operators to bypass capex-intensive equipment requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Philippine and Indonesian processors with stranded Tetra Pack capacity and established modern trade shelf presence in Metro Manila and Jakarta. Long-term viability over the projection horizon hinges on regulatory compliance technology positioning rather than commodity margin capture. Monitor EFSA additive threshold interpretations and EU Farm to Fork Strategy enforcement timelines as the critical inflection signal for European export-oriented manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Homogenization Technology Licensing | Thai and Vietnamese contract manufacturers adopt these units aggressively to meet bakery-sector texture specifications. |
| Premix Integration Capability Buildout | Indian reconstitution facilities serving FSSAI-mandated vitamin A and D enrichment create captive demand concentration. |
| Tetra Pack Channel Migration Investment | Urban convenience stores in Philippine metropolitan zones displace traditional sari-sari micro-retail for single-serve consumption. |
| Sustainable Palm Oil Certification Program | EU Green Deal alignment creates differentiation premiums for supply chains meeting EFSA additive thresholds. |
| West African Distribution Corridor Expansion | Promasidor's established routes demonstrate scalable penetration where evaporated filled milk serves as affordable protein staple. |
Methodological Framework
Document review covered FSSAI regulatory filings, BIS compositional standards, EFSA additive threshold notifications, and customs trade data on skim milk solids and vegetable fat imports, complemented by interviews with dairy reconstitution plant managers, procurement leads at Southeast Asian bakery manufacturers, distribution channel partners in Philippine wholesale networks, and regulatory affairs specialists navigating Codex Alimentarius frameworks. Secondary validation drew from cooperative annual reports, dairy industry association statistics, and food safety regulator enforcement disclosures. Bottom-up volume aggregation across product type, packaging format, end user, and distribution channel segments was triangulated against top-down market sizing from trade flow analysis.
Segment-level outputs reflect modeled interactions between fortification mandate compliance costs, high-pressure homogenization technology adoption curves, and channel format migration patterns across the projection horizon. Analytical framework incorporated vegetable oil price volatility scenarios, cooperative sourcing network capacity constraints, and urban retail modernization trajectories. CAGRs were derived from regression analysis of historical volume relationships against macroeconomic indicators and regulatory implementation timelines. Forecast inputs included FSSAI enforcement intensity projections and Tetra Pack penetration rate assumptions in Southeast Asian metropolitan zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palm oil export policy shifts, EFSA novel fat replacer category rulings, and cooperative network restructuring in Northern Europe. Assumptions reflect current regulatory trajectories and technology cost curves. A small set of named triggers—Malaysian biodiesel mandate revisions, EU dairy analogue definition harmonization, and Philippine convenience store format consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Milk Protein Market
Dairy Products
Global Butter Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Blue Cheese Market
Dairy Products
Halal Cheese Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Global Yogurt Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
North America Yogurt Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Organic Cheese Powder Market