
 Dairy Spreads Market | 2026-2036
Dairy Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Spreads Market Analysis
A capital-intensity divergence between artisanal creamery operations and industrial-scale margarine plants is bifurcating competitive dynamics in dairy spreads. Arla Foods leverages its cooperative milk sourcing structure to sustain cost advantages across Northern European markets. Lactalis anchors its position through backward integration into dairy farming, controlling raw milk quality for premium butter output. FrieslandCampina differentiates via specialized fat-blending technology that extends shelf stability in tropical distribution corridors.
Dairy spreads encompass emulsified fat-based products formulated from milk solids, vegetable oils, or hybrid compositions, typically containing 60-82% fat content depending on regional standards and intended spreadability at refrigeration temperatures. Manufacturers employ churning, emulsification, or cultured fermentation processes to achieve specific texture profiles for direct consumption or food processing applications. Butter and cream cheese command the dominant value share within product type segmentation, though nutrient-enriched and organic formulations capture expanding margin pools as health-conscious households redirect purchases. Online retailers represent the fastest-growing distribution channel, while specialty stores concentrate artisanal premium volumes in urban clusters.
FDA standards for trans-fat labeling and nutrient content claims directly constrain margarine formulation strategies in the United States, while EU F-Gas Regulation and REACH compliance shape processing equipment investments across European production facilities. EFSA health claim assessments determine whether nutrient-enriched spreads qualify for functional positioning in European markets. Stakeholders must monitor evolving clean-label certification thresholds and carbon-footprint disclosure requirements as procurement criteria tighten across retail and food service channels.
Market Dynamics
Clean-label certification thresholds and carbon-footprint disclosure mandates are restructuring procurement criteria across retail and food service channels, forcing reformulation investments and supplier qualification protocols.
Growth Catalysts
- EU REACH compliance:Clean-label formulation requirements under EU REACH are accelerating premium butter and cream cheese development as manufacturers eliminate artificial additives to meet retailer certification standards.
- Food service menu expansion:Operators across Germany, France, and the United States are broadening premium butter applications into artisanal bread programs and pastry innovation, sustaining volume pull-through.
- Cultured fermentation processes:Advances in controlled fermentation technology are enabling texture precision in spreadable cream cheese, supporting functional positioning in nutrient-enriched categories.
Market Restraints
- Milk solids input volatility:Raw milk price fluctuations in Northern European cooperative sourcing regions compress margin predictability for butter-dominant portfolios.
- FDA trans-fat labeling constraints:Nutrient content claim restrictions in the United States limit margarine formulation flexibility, constraining hybrid product innovation pipelines.
- Plant-based fat substitutes:Oat and almond spread alternatives are capturing shelf space in urban retail clusters, displacing conventional dairy spread volumes in health-conscious household segments.
Strategic Opportunities
- EFSA health claim pathway:Nutrient-enriched spreads qualifying under EFSA functional food assessments command premium positioning in European markets with validated cardiovascular or digestive benefits.
- Online retailer channel expansion:Direct-to-consumer platforms represent underpenetrated distribution infrastructure for artisanal creamery products requiring cold-chain precision outside traditional retail footprints.
- Tropical shelf stability:Specialized fat-blending technology enabling ambient distribution in Southeast Asian and Middle Eastern corridors opens geographic white space for European exporters.
Industry Challenges
- Clean-label certification timelines:Multi-month organic and non-GMO verification processes delay product launches and tie up working capital in inventory holding.
- Legacy equipment retrofitting:F-Gas Regulation compliance in European facilities requires refrigeration system replacement, demanding capital deployment amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Spreads Market |
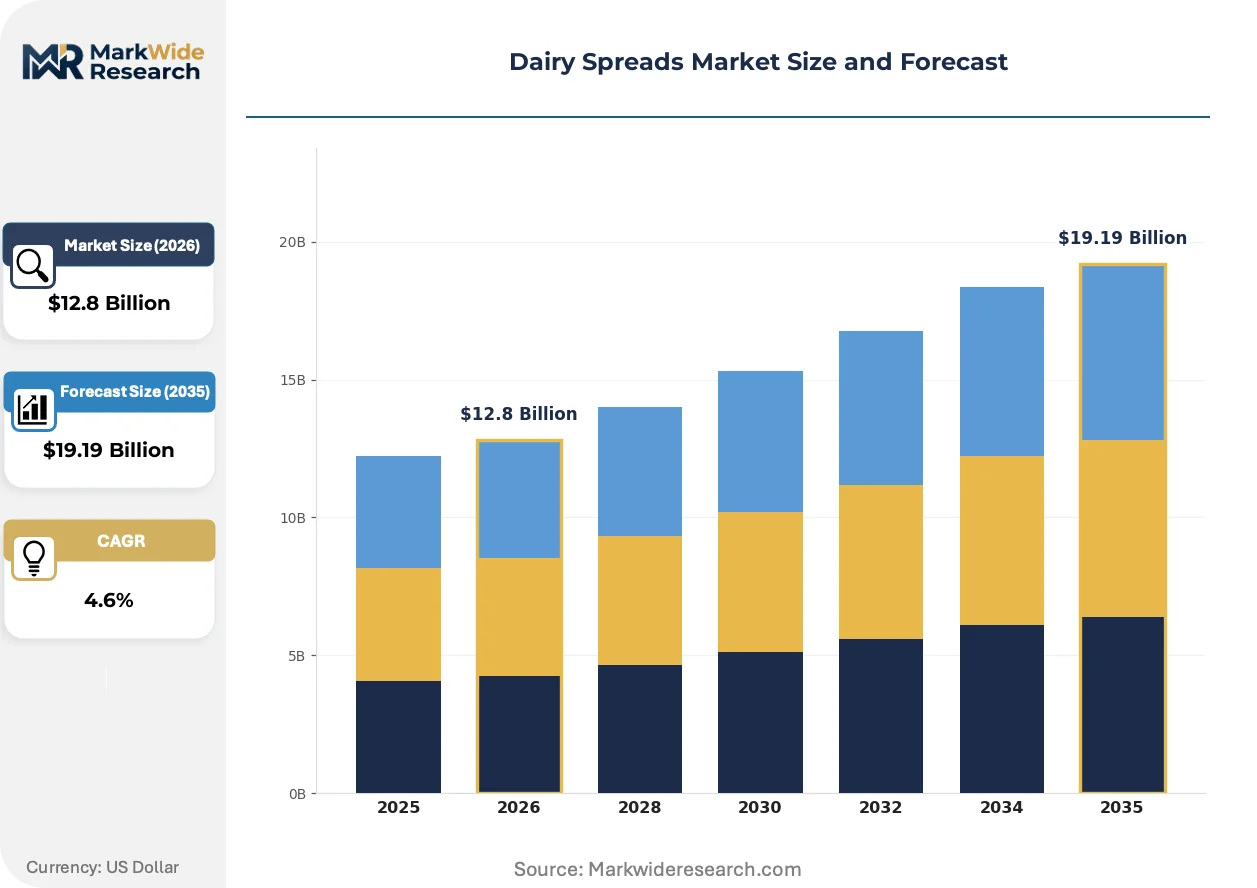
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Cream Cheese, Soft Cheese Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Formulation: With Added Flavor, Organic, Low-Fat, Nutrient-Enriched Customer Type: Households, Food Services, Retailers, Manufacturers |
| Companies Covered | Arla Foods, Savencia, Lactalis, Sodiaal, Müller, Nestlé, FrieslandCampina, Emmi, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Spreads Market Emerging Trajectories
Formulation science and distribution infrastructure are converging to reshape competitive advantage in dairy spreads, with technology-enabled texture control and regulatory-driven transparency requirements defining the next investment cycle.
Precision fermentation for dairy protein synthesis is decomposing traditional reliance on animal-derived milk solids, enabling spreadable fat matrices with identical functional properties. Biotech ingredient suppliers are scaling production capacity to serve premium creamery and industrial margarine manufacturers simultaneously. This technology is decomposing cost structures in high-margin organic segments where input traceability commands price premiums.
EU F-Gas Regulation phase-down schedules are mandating refrigeration equipment replacement across European production facilities, accelerating capital rotation toward low-global-warming-potential cooling systems. Processing plant operators in Germany and France face compressed retrofit timelines to maintain operational licenses. Margarine and hybrid spread producers with tropical export exposure face the steepest compliance burdens due to extended cold-chain requirements.
Direct-to-consumer subscription models for artisanal butter and cultured cream cheese are disrupting traditional wholesale-to-retail distribution in urban United States markets. Specialty food e-commerce platforms are capturing household pantry replenishment cycles previously dominated by supermarket dairy aisles. This channel rotation is most pronounced in metropolitan clusters across California, New York, and Texas where delivery logistics density supports margin-sustainable cold-chain fulfillment.
Dairy Spreads Market Segmentation
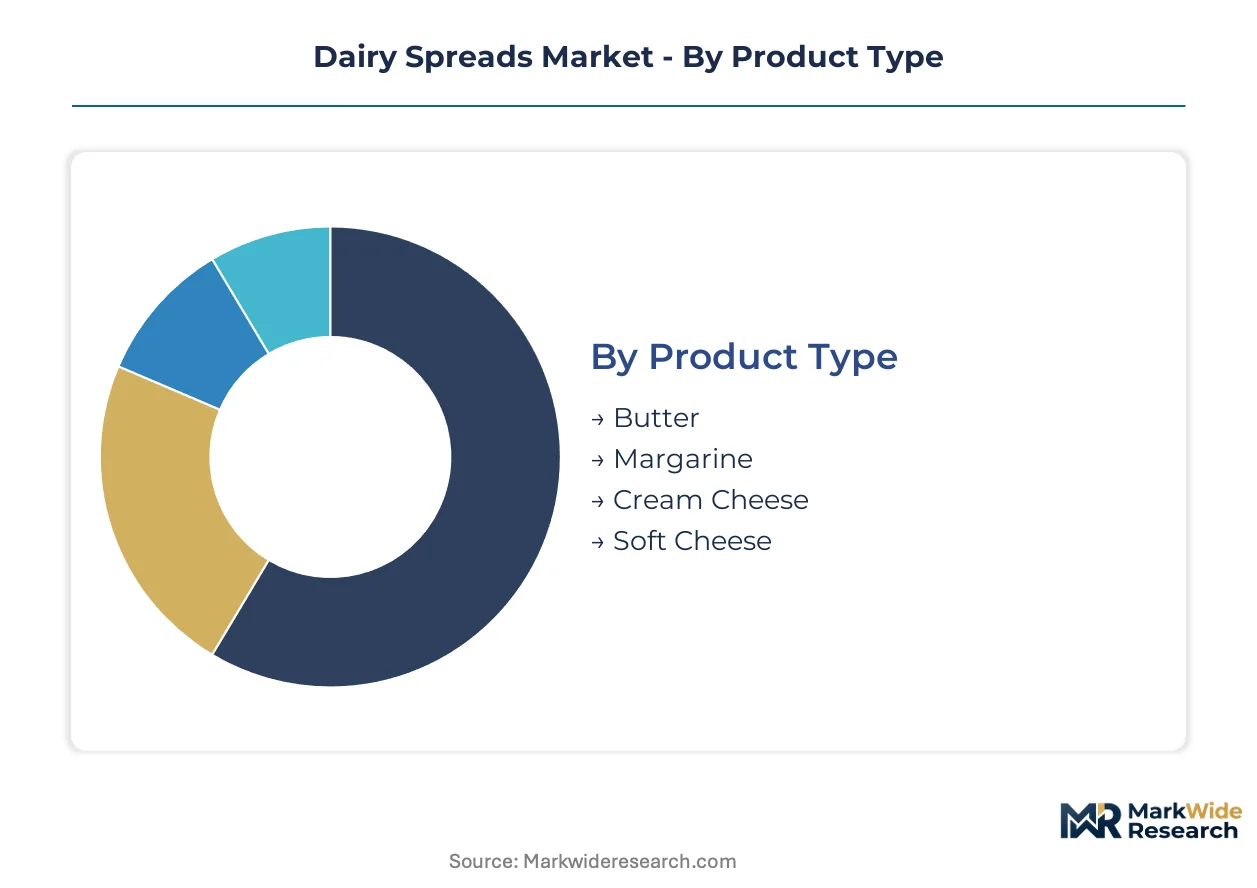
Dairy spreads manufacturers configure product portfolios around four intersecting dimensions that determine pricing power and channel access. Each segmentation axis carries distinct regulatory burdens and margin profiles that reshape competitive positioning across export corridors.
Product Type:
Export-led segments dominate premium positioning in tropical distribution networks, while domestic-focused categories anchor volume stability in European cooperative sourcing regions.
- Butter:Churned cream with 80-82% milk fat content delivers firm texture at refrigeration temperatures. Demand concentrates in German and French artisanal bread programs where clean-label certification commands shelf space premiums. EU REACH compliance requirements on additive elimination sustain reformulation investments.
- Cream Cheese:Cultured fresh cheese with 33-55% moisture content achieves spreadable consistency through controlled fermentation. Food service operators in the United States expand pastry and bagel applications, pulling volume through specialty distributors. Texture precision technology enables functional positioning in nutrient-enriched subcategories.
- Margarine:Emulsified vegetable oil formulations with 80% fat content compete on price in household segments. FDA trans-fat labeling constraints limit formulation flexibility in North American markets.
- Soft Cheese:Fresh curd products with variable moisture profiles serve regional taste preferences. Local creameries dominate supply in France and Italy where protected designation of origin rules apply.
Butter holds the largest share; momentum sits with cream cheese as fermentation technology advances expand food service applications.
Distribution Channel:
Cost-tier stratification separates premium cold-chain-dependent channels from mass-market ambient distribution, with margin structures reflecting inventory risk and shelf-life requirements.
- Online Retailers:Direct-to-consumer platforms with temperature-controlled logistics capture urban household replenishment cycles. California, New York, and Texas metropolitan clusters support margin-sustainable fulfillment density for artisanal creamery products.
- Specialty Stores:Curated assortments in urban retail clusters concentrate premium butter and cultured cream cheese volumes. Germany and France sustain highest per-store throughput for organic and non-GMO certified lines.
- Supermarkets:High-volume self-service dairy aisles drive margarine and standard butter penetration in suburban household segments. Private-label compression limits branded margin expansion.
- Convenience Stores:Limited assortment formats prioritize single-serve and extended-shelf-life SKUs for immediate consumption occasions. Grab-and-go positioning favors portion-controlled packaging.
Supermarkets anchor volume concentration; online retailers are climbing the fastest as subscription models disrupt traditional wholesale-to-retail flows.
Formulation:
Application-driven segmentation separates direct-consumption occasions from ingredient-in-manufacturing uses, with certification requirements determining channel eligibility.
- Organic:Certified milk solids from pasture-based dairy farming command price premiums in German and French retail. Multi-month verification timelines delay product launches and tie up working capital.
- Nutrient-Enriched:Vitamin D, omega-3, or probiotic fortification targets functional food positioning. EFSA health claim assessments determine European market eligibility for cardiovascular or digestive benefit messaging.
- With Added Flavor:Herb, spice, or sweet inclusions expand usage occasions in food service and household segments. Clean-label requirements constrain artificial flavoring options under EU standards.
- Low-Fat:Reduced-fat formulations with adjusted water-in-fat emulsions compete in health-conscious household segments. Plant-based substitutes capture overlapping demand in urban clusters.
Organic formulations dominate premium shelf positioning; nutrient-enriched lines show steepest expansion trajectory as EFSA validation pathways mature.
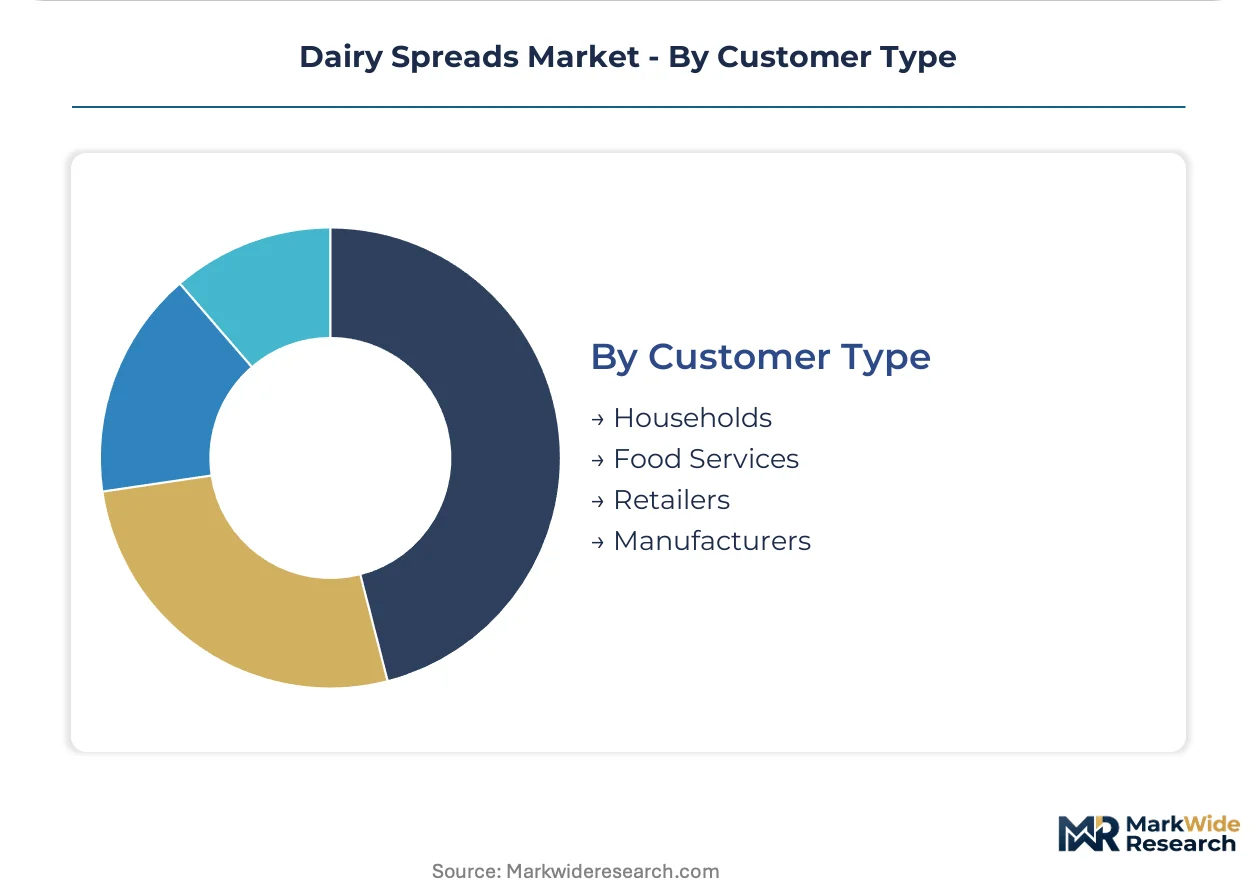
Customer Type:
Supply concentration patterns align with customer scale, from fragmented household demand to consolidated food service procurement with precise specification requirements.
- Food Services:Restaurant, bakery, and catering operators specify fat content, spreadability, and shelf stability for menu applications. Germany, France, and the United States drive premium butter volume through artisanal bread and pastry innovation.
- Households:Individual consumers purchase through retail channels with brand loyalty varying by occasion and price sensitivity. Health-conscious segments redirect toward plant-based alternatives in urban markets.
- Retailers:Supermarket and specialty store buyers negotiate slotting allowances and promotional support for private-label and branded lines. Clean-label certification thresholds determine supplier qualification.
- Manufacturers:Industrial processors incorporate dairy spreads as ingredients in baked goods, confectionery, and prepared foods. Tropical export corridors demand specialized fat-blending technology for ambient distribution.
Food services command highest per-unit margins; households provide volume foundation with expanding direct-to-consumer bypass options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across markets. German and French buyers absorb premium pricing for artisanal butter with minimal volume contraction, while price-sensitive segments in emerging markets drive rapid substitution toward plant-based alternatives at marginal cost increases.
United States
Food service operators in California, New York, and Texas metropolitan clusters expand artisanal bread and pastry applications for premium butter. FDA trans-fat labeling constraints limit margarine formulation flexibility, compressing innovation pipelines for hybrid spreads. Direct-to-consumer subscription models disrupt traditional wholesale-to-retail distribution in urban coastal markets.
Germany
Artisanal creamery demand concentrates in Bavaria and Baden-Württemberg where organic certification commands shelf space premiums. EU F-Gas Regulation mandates refrigeration system replacement across production facilities, accelerating capital deployment toward low-global-warming-potential cooling systems. Berlin-Brandenburg clusters drive highest per-store throughput for clean-label butter lines in specialty retail.
France
Protected designation of origin rules anchor soft cheese production in Auvergne-Rhône-Alpes and Normandy, sustaining regional creamery concentration. EFSA health claim assessments determine eligibility for functional positioning in nutrient-enriched spreads. Paris metropolitan specialty stores capture premium volumes for cultured cream cheese with validated digestive benefit messaging.
United Kingdom
London and Southeast England retail clusters sustain demand for organic and non-GMO certified spreads amid clean-label certification tightening. The Competition and Markets Authority monitors supplier qualification protocols for carbon-footprint disclosure compliance. Midlands manufacturing bases face margin pressure from multi-month organic verification timelines delaying product launches.
India
Rapid urbanization in Maharashtra and Karnataka drives household penetration of processed cheese spreads through modern retail expansion. FSSAI labeling standards constrain artificial additive formulations, pushing reformulation investments. Delhi-NCR food service procurement concentrates volume for bakery and QSR applications requiring extended tropical shelf stability.
Dairy Spreads Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cooperative structures and proprietary sourcing networks creating durable cost advantages. Northern European players leverage backward integration into dairy farming to control raw milk quality, while technology-enabled fat-blending specialists capture export corridors requiring ambient distribution. Strategic archetypes include cooperative-integrated giants, fermentation-technology specialists, and regional creamery collectives. Dominant competitive moves center on cold-chain infrastructure expansion and clean-label certification acceleration.
Within the cooperative-integrated tier, Arla Foods and FrieslandCampina exemplify structures that sustain cost advantages across Northern European sourcing regions. Lactalis anchors a position through upstream control over dairy farming operations. These three entities represent distinct approaches to managing input volatility: cooperative milk pooling, specialized fat-blending technology, and captive supply integration.
| Leading Market Players |
|---|
| Arla Foods |
| Savencia |
| Lactalis |
| Sodiaal |
| Müller |
| Nestlé |
| FrieslandCampina |
| Emmi |
| Danone |
| Others |
Supply Flow & Price Mechanics
Industrial-scale margarine plants achieve 40% lower unit costs than artisanal creamery operations, compressing price floors in mass-market segments while cooperative milk pooling in Northern Europe sustains premium butter premiums through input traceability advantages.
Pricing Analysis
After-sales revenue from food service technical support and formulation consulting drives lifetime value for specialized fat-blending suppliers. Three-tier pricing structure across premium artisanal, standard industrial, and economy private-label levels separates butter categories by certification grade and geographic origin. Pricing pressure stems from plant-based oat and almond spread alternatives capturing urban retail shelf space. Household segments in metropolitan clusters show highest price sensitivity, while food service operators in Germany and France absorb premiums for clean-label certified lines with minimal volume contraction.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability on Asia-Europe trade lanes, compressing margin predictability for tropical export-dependent producers. Supply concentrates in Germany, France, and the Netherlands for premium butter, while palm oil and shea fat inputs for margarine draw from Southeast Asian and West African sourcing regions. Single-source vulnerability in cultured starter cultures for cream cheese fermentation creates formulation continuity risk. Distribution runs through temperature-controlled wholesale networks for artisanal products and ambient retail logistics for shelf-stable margarine lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation technology and clean-label certification infrastructure represent scarce capabilities that concentrate competitive advantage among cooperative-integrated processors with captive dairy farming networks.
For Market Incumbents: Consolidate backward integration into pasture-based milk sourcing to secure organic certification pipelines against multi-month verification delays. Expand cold-chain infrastructure in California and Texas metropolitan clusters to defend subscription-model customer relationships from direct-to-consumer entrants. Prioritize EFSA health claim validation investments to capture functional spread premiums before nutrient-enriched positioning saturates European retail. For New Entrants and Emerging Players: EU organic certification fast-track programs through recognized control bodies enable accelerated shelf access in German and French specialty retail. Target online retailer channel expansion for artisanal cream cheese in underserved Southeast Asian urban corridors where tropical shelf stability technology creates white space. Pursue white-label manufacturing partnerships with established dairy cooperatives to bypass capital-intensive milk sourcing infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-technology specialists with precision culture control capabilities over commodity margarine processors facing plant-based substitution pressure. Long-term viability hinges on clean-label certification asset ownership and direct-to-consumer channel infrastructure. Acquisition targets should demonstrate validated EFSA health claim pathways or proprietary fat-blending technology for ambient distribution. Watch for inflection signals in FSSAI labeling standard enforcement accelerating reformulation investment requirements in Indian urban markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Farming | Captive milk supply secures organic certification traceability for EU REACH compliance. |
| EFSA Health Claim Validation Investment | Validated cardiovascular messaging unlocks premium positioning in French and German retail. |
| Cold-Chain Infrastructure Expansion | Temperature-controlled logistics enable direct-to-consumer subscription models in Texas and California. |
| Precision Fermentation Technology Deployment | Controlled culture processes achieve texture precision for nutrient-enriched cream cheese lines. |
| Tropical Shelf Stability Formulation Development | Specialized fat-blending technology opens Southeast Asian and Middle Eastern export corridors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, food service procurement managers, specialty retail category buyers, and cooperative sourcing directors; and secondary validation through EU dairy trade statistics, FDA food additive petition filings, EFSA health claim register entries, and cold-chain logistics provider capacity disclosures. Bottom-up volume modeling triangulated against top-down value estimates from customs records and retail audit data.
Across the projection horizon, the analytical framework modeled product type, distribution channel, formulation certification tier, and customer segment dimensions with regional regulatory cluster overlays. CAGRs derived from historical trajectory analysis adjusted for clean-label certification penetration curves and food service menu expansion rates. Forecast inputs incorporated milk solids price volatility indices and plant-based substitute shelf space capture rates in urban retail clusters.
Underlying assumptions cover sustained EU REACH compliance timelines and FDA trans-fat labeling stability, with deviation risk concentrated in F-Gas Regulation phase-down acceleration or FSSAI labeling standard enforcement tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Recombined Milk Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Yogurt Drink Market
Dairy Products
South America Yogurt Market
Dairy Products
Dairy Foods Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Germany Dairy Market
Dairy Products
Canada Dairy Market
Dairy Products
Cheese Crumbles Market