
 Gruyere Market | 2026-2036
Gruyere Market Size, Share, and Industry Trends Forecast 2026-2036
Gruyere Market Foresight
Alpine cellar automation is tilting gruyere production toward precision-controlled humidity and temperature systems that replicate traditional cave conditions at scale. Bergkäserei Vorderfultigen leverages vertical integration from raw milk collection to 12-month aging to sustain export-grade consistency. Emmi Roth anchors North American supply through licensed production protocols that compete with direct European imports. Fromagerie Moille specializes in small-batch summer milk gruyere that differentiates within premium retail channels.
Gruyere denotes a hard, cooked-curd cow's milk cheese with a dense, slightly granular paste and minimum 45% fat in dry matter, aged 5 to 18 months in humidity-controlled environments for nutty, complex flavor development. The cheese wheel format dominates artisan procurement and aging economics, while shredded cheese captures food service volume through operational efficiency in commercial kitchens. Online retail channels are gaining traction as direct-to-consumer logistics mature, though specialty stores retain margin concentration through curated aging programs and staff expertise.
EU PDO enforcement through the European Commission's agricultural quality schemes dictates labeling legitimacy and geographic exclusivity for "Gruyère" designation. Swiss AOP regulations administered by the Federal Office for Agriculture reinforce cross-border protection and inspection protocols for alpine-origin product. FDA import standards in the United States govern raw milk cheese aging requirements and pathogen thresholds. Stakeholders must monitor evolving trade alignment between European origin boards and third-country import regimes as premium positioning hinges on verified provenance claims.
Market Dynamics
Alpine cellar scarcity and PDO enforcement are compressing legitimate gruyere supply into a shrinking pool of certified producers, forcing buyers to compete for verified-origin inventory while automation spreads among remaining authorized creameries.
Growth Catalysts
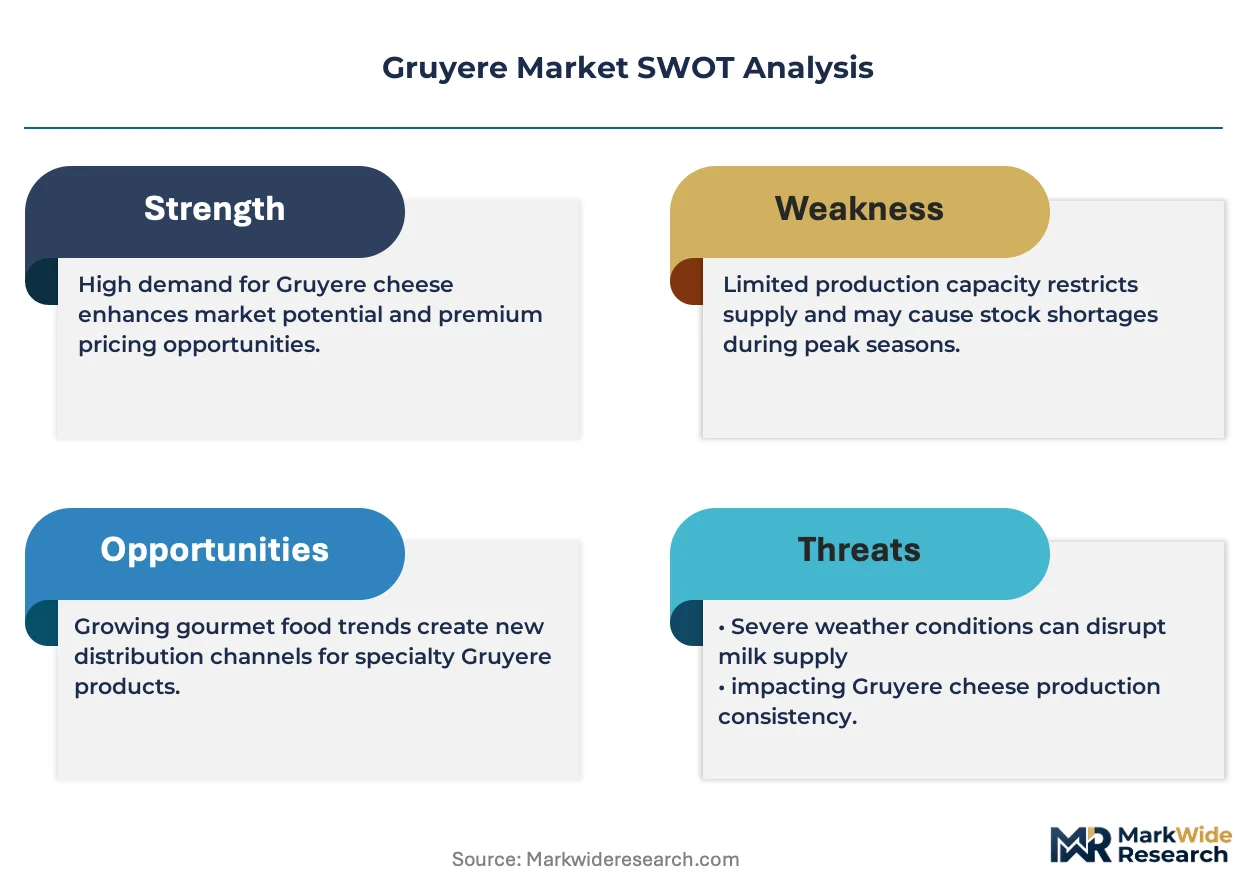
- EU PDO enforcement:The European Commission's agricultural quality schemes tighten geographic exclusivity for "Gruyère" labeling, eliminating counterfeit competition and protecting price premiums for certified producers.
- Specialty food retail expansion:Curated cheese counters at premium grocers are expanding SKU depth for aged European imports, creating shelf space for 12-month and reserve-grade wheels.
- Alpine automation:Precision-controlled humidity and temperature systems replicate traditional cave conditions at scale, enabling consistent export-grade output from Swiss cooperatives.
Market Restraints
- Raw milk input volatility:Alpine meadow grazing cycles constrain summer milk availability, limiting small-batch production from seasonal creameries in the Swiss Prealps.
- Supply concentration risk:Aging cellar capacity concentrates in historic Savoie and Fribourg facilities, creating bottlenecks for extended-reserve inventory.
- Regulatory friction:FDA import standards impose 60-day minimum aging requirements on raw milk cheeses, excluding younger gruyere expressions from US market entry.
Strategic Opportunities
- Direct-to-consumer channels:Maturing cold-chain logistics enable creameries to bypass import distributors and capture margin through subscription-based aged cheese programs.
- Summer milk differentiation:Alpine flower-grazed milk produces distinct flavor profiles that command retail premiums in specialty channels seeking terroir narratives.
- Licensed production protocols:Swiss AOP frameworks permit controlled foreign replication, opening pathways for compliant domestic aging in third-country markets facing import barriers.
Industry Challenges
- Affineur skill scarcity:Traditional cellar masters with 15-plus years of wheel-turning and mold-management experience are retiring faster than apprenticeship pipelines replenish.
- Certification timeline compression:PDO audit cycles and documentation requirements for alpine-origin verification are extending time-to-market for new cooperative entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gruyere Market |
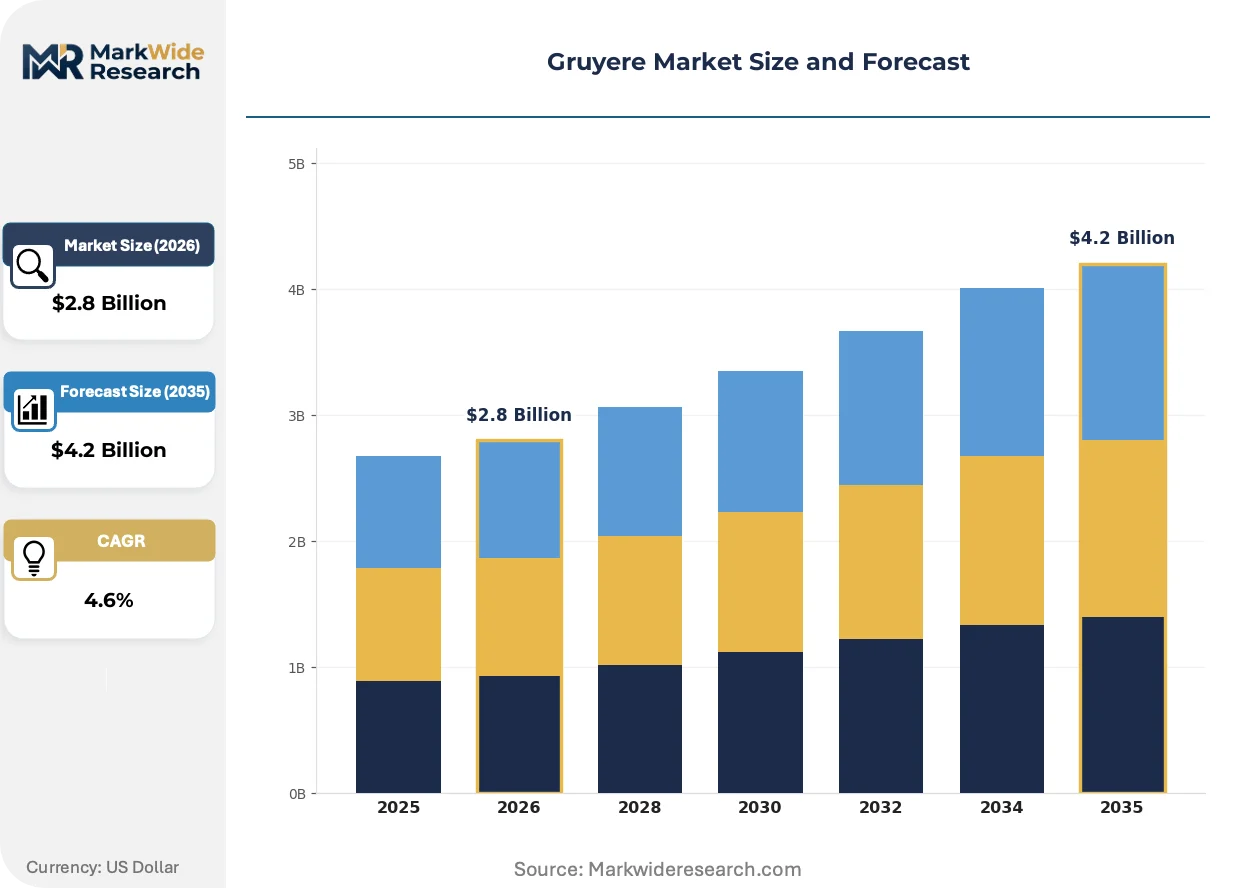
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese Wheel, Shredded Cheese, Sliced Cheese, Block Cheese Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Restaurants, Households, Catering Services, Bakeries Packaging Type: Vacuum Sealed, Plastic Wrap, Glass Jar, Bulk Packaging |
| Companies Covered | Bergkäserei Vorderfultigen, Emmi Roth, Fromagerie Moille, Fromagerie Perrenoud, Laiterie Cooperative Pringy-Fillinges, Cooperative Laitiere de Pringy, Fromagerie Alpina, Cooperative Laitiere de Taninges, Fromagerie Cooperative de Morzine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gruyere Market Shifts & Advancements
Digital replication of sensory evaluation and blockchain-based provenance tracking are reshaping how gruyere quality is authenticated and how supply chain transparency is communicated to premium buyers.
Sensor arrays paired with machine learning algorithms are virtualizing the role of human affineurs in monitoring wheel development, analyzing rind microbiome activity and paste texture through non-invasive scanning. Large Swiss cooperatives are deploying these systems across multi-cellar operations to standardize quality outcomes. The technology is virtualizing decades of tacit expertise into reproducible protocols that reduce reliance on individual cellar masters.
Swiss AOP regulations administered by the Federal Office for Agriculture are tightening cross-border inspection protocols and digital traceability requirements for alpine-origin product. Creameries must now submit geotagged milk collection records and aging location documentation for each wheel. Small-batch producers in Fribourg and Vaud are investing in compliance infrastructure to maintain export eligibility under the reinforced framework.
Restaurant procurement is consolidating around pre-cut and pre-portioned formats that reduce kitchen labor and waste, displacing whole-wheel purchasing among mid-tier food service operators. Distributors are responding with programmable shredding and slicing equipment positioned at regional dairy hubs. This shift is most visible in North American metropolitan markets where labor costs and speed-of-service pressures are acute.
Gruyere Market Segmentation
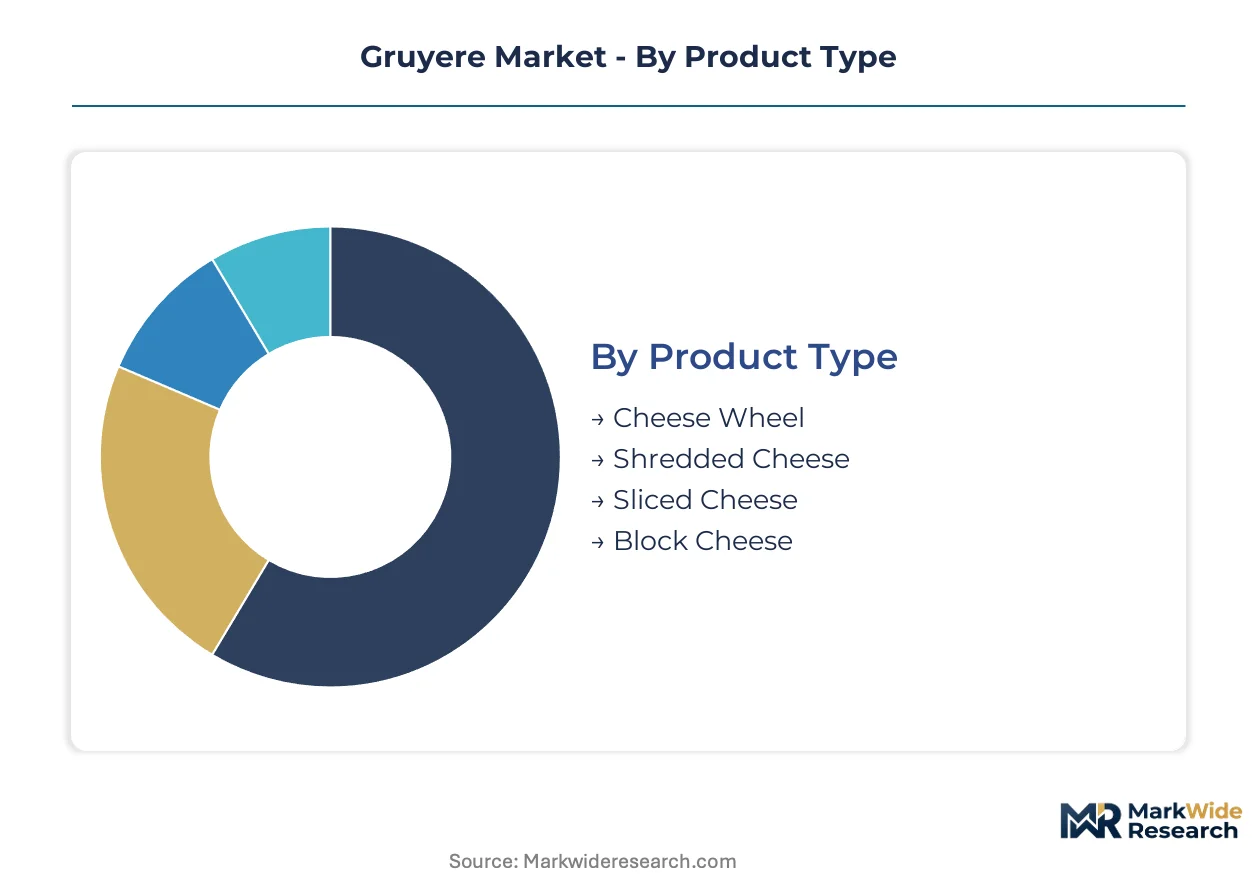
Gruyere's value chain fragments across aging formats, procurement channels, and end-use applications that each carry distinct margin profiles and regulatory requirements. Understanding these divides reveals where PDO-certified supply concentrates and which segments absorb automation investments.
Product Type:
Cost tier differentiation separates artisan wheel formats from industrialized cuts, with aging duration and labor intensity driving price stratification.
- Cheese Wheel:Whole-format wheels aged 5 to 18 months in humidity-controlled cellars carry the full PDO certification premium. Swiss alpine cooperatives and French Savoie creameries concentrate supply here, as wheel-turning expertise and extended affineur labor create barriers to entry.
- Shredded Cheese:Pre-grated formats target food service velocity, with Emmi Roth and licensed North American producers capturing institutional procurement through operational efficiency. This segment sacrifices provenance narrative for kitchen labor reduction.
- Sliced Cheese:Deli-counter portions serve retail convenience demand with shorter shelf-life requirements.
- Block Cheese:Commercial kitchen formats balance portion flexibility with reduced per-unit handling costs.
Cheese wheel holds installed capacity. Shredded cheese is rotating up the share rankings.
Distribution Channel:
Customer type determines whether procurement prioritizes staff expertise, price transparency, or operational throughput.
- Specialty Stores:Curated cheese counters with affineur-trained staff command margin through reserve-grade wheels and aging program narratives. These channels concentrate demand from consumers seeking verified-origin Swiss AOP product.
- Online Retail:Direct-to-consumer logistics are maturing for subscription-based aged cheese programs, with cold-chain investments enabling creameries to bypass import distributors and capture margin.
- Supermarkets:Mass retail moves volume through standardized cuts with reduced provenance documentation.
- Food Service:Restaurant procurement consolidates around pre-portioned formats that reduce kitchen labor and waste.
Specialty stores hold installed capacity. Online retail is rotating up the share rankings.
End User:
Application requirements range from melted consistency in hot preparations to table cheese presentation, shaping format and aging specifications.
- Restaurants:Fine-dining establishments procure reserve-grade wheels for cheese course presentation, while casual operators prioritize pre-cut formats. French and Swiss gastronomy traditions sustain demand for authentic alpine-origin product.
- Households:Premium retail consumers in metropolitan markets seek PDO-verified gruyere for home entertaining, with specialty store proximity driving purchase decisions.
- Catering Services:Event-scale procurement favors shredded and block formats for operational efficiency.
- Bakeries:Gruyere incorporation into viennoiserie and savory applications demands consistent melt behavior.
Restaurants hold installed capacity. Households is rotating up the share rankings.
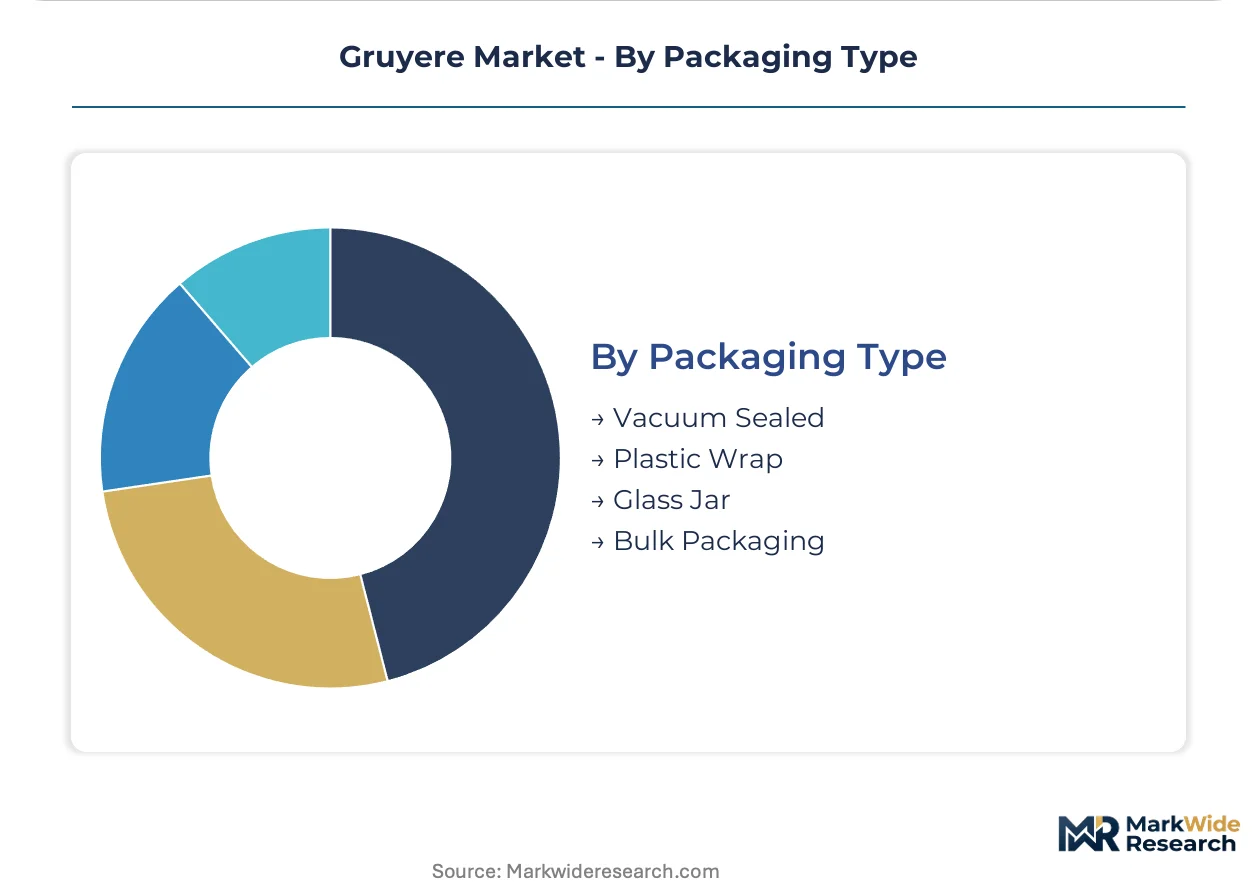
Packaging Type:
Volume and shelf-life requirements dictate material selection, with premium positioning favoring barrier technologies that extend aging potential.
- Vacuum Sealed:Oxygen-exclusion technology preserves wheel integrity during extended aging and international transport, enabling Swiss and French exporters to maintain quality across cold-chain distribution.
- Plastic Wrap:Cost-efficient barrier for shorter-rotation retail cuts in high-velocity channels.
- Glass Jar:Premium presentation format for gift and specialty retail positioning.
- Bulk Packaging:Food service and industrial processing inputs minimize per-unit material costs.
Vacuum sealed holds installed capacity. Plastic wrap is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss alpine cooperatives export aged wheels through established cold-chain corridors into United States and French metropolitan markets, with Fribourg and Vaud facilities anchoring transatlantic distribution flows.
Switzerland
Fine-dining procurement and specialty retail expansion sustain import demand for AOP-certified wheels. The Federal Office for Agriculture enforces cross-border inspection protocols and digital traceability requirements for alpine-origin product. Fribourg creameries concentrate extended-reserve aging capacity as cellar automation spreads through cooperative networks.
France
Gastronomy traditions in Paris and Lyon sustain restaurant demand for Savoie-origin gruyere. The European Commission's agricultural quality schemes tighten geographic exclusivity for PDO labeling through reinforced audit cycles. Creameries in Haute-Savoie cluster around historic Morzine aging facilities facing capacity constraints from affineur skill scarcity.
United States
Metropolitan specialty grocers in New York and San Francisco expand curated cheese counter SKU depth for European imports. FDA import standards impose 60-day minimum aging requirements on raw milk cheeses, filtering eligible product. Emmi Roth operates licensed production protocols in Wisconsin that compete with direct Swiss imports.
Germany
Discount retail consolidation and premium gastronomy segments split procurement between standardized cuts and reserve-grade wheels. EFSA guidelines on dairy pathogen thresholds align with EU-wide quality scheme enforcement. Munich and Frankfurt distribution hubs channel alpine product into Central European food service networks.
Japan
Department store food halls and European-themed restaurants in Tokyo sustain niche demand for verified-origin cheese. METI import regulations govern dairy product sanitary certifications and labeling requirements. Osaka-based importers specialize in small-lot procurement from Swiss summer milk production cycles.
Gruyere Market Competitive Landscape
On the supply side, the industry is consolidating around PDO-certified alpine cooperatives with captive aging infrastructure, while licensed foreign producers capture volume in import-restricted markets. Three archetypes dominate: Swiss AOP cooperatives with vertical control from milk collection through extended aging, licensed third-country replicators operating under protocol agreements, and French Savoie creameries emphasizing terroir differentiation through seasonal production. Competitive moves center on cellar capacity expansion and direct-to-consumer channel development bypassing traditional import distributors.
Among Swiss cooperative structures, Bergkäserei Vorderfultigen and Cooperative Laitiere de Pringy exemplify the integrated alpine model with controlled supply chains from raw milk through export-grade aging. Emmi Roth occupies a position as the licensed replicator archetype, anchoring North American supply through protocol-based production outside traditional origin zones. These three entities represent the dominant competitive configurations shaping procurement access and pricing formation across premium and mass-market channels.
| Leading Market Players |
|---|
| Bergkäserei Vorderfultigen |
| Emmi Roth |
| Fromagerie Moille |
| Fromagerie Perrenoud |
| Laiterie Cooperative Pringy-Fillinges |
| Cooperative Laitiere de Pringy |
| Fromagerie Alpina |
| Cooperative Laitiere de Taninges |
| Fromagerie Cooperative de Morzine |
| Others |
Supply & Pricing Matrix
Alpine cellar concentration in Swiss Fribourg and French Savoie creameries funnels margin capture toward affineur-controlled aging tiers, while downstream buyers absorb transport and certification premiums for verified-origin inventory. PDO enforcement compresses legitimate supply into certified cooperatives, amplifying pricing power for wheel-format reserves against commoditized shredded alternatives.
Pricing Analysis
Aging-duration pricing gaps separate 5-month young wheels from 12-month reserves and 18-month extended expressions, with each tier commanding exponential premiums for affineur labor and cellar occupancy. Three-tier pricing structure across reserve, standard, and economy levels stratifies by AOP certification status, seasonal milk provenance, and direct-to-consumer channel access. Pricing pressure intensifies in shredded formats as licensed North American producers compete on food service contracts, eroding provenance premiums. Household procurement through specialty stores shows lowest price sensitivity, while institutional food service buyers drive cost compression in pre-portioned segments.
Supply Chain Analysis
Cooperative concentration among Swiss alpine dairies and French Savoie creameries holds captive aging capacity, with Bergkäserei Vorderfultigen and Cooperative Laitiere de Pringy anchoring upstream wheel production. Raw milk sourcing draws from summer alpine meadow grazing cycles and winter barn-fed herds, with humidity-controlled cellar infrastructure and affineur expertise constituting critical bottlenecks. Single-source vulnerability concentrates in historic Morzine and Fribourg aging facilities facing skill scarcity and capacity constraints. Distribution runs through cold-chain corridors into metropolitan specialty retail and direct-to-consumer subscription channels, bypassing traditional import distributors for margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gruyere's value chain is approaching a platform-economics inflection as blockchain provenance tracking and sensor-based quality authentication create interoperability standards between alpine cooperatives and premium retail channels.
For Market Incumbents: Build certification moats through accelerated Swiss AOP and EU PDO audit investments that extend compliance documentation to individual wheel geotagging, defending against licensed foreign replicators eroding origin premiums. Deepen backward integration into summer milk collection networks to secure terroir-differentiated supply, while deploying cellar automation to offset affineur skill scarcity threatening extended-reserve capacity. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting metropolitan households in North American and Asian markets, where import distributor bypass enables margin capture unavailable through wholesale channels. White-space concentration sits in summer milk gruyere with documented alpine flower grazing provenance, leveraging terroir narratives for premium positioning against standardized licensed production. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated cellar infrastructure and digital traceability compliance, favoring scaled cooperative structures over fragmented artisan operations. Acquisition targets should prioritize Fribourg and Vaud creameries with captive aging capacity and export certification status, with monitoring cadence focused on Swiss Federal Office for Agriculture inspection protocol tightening as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AOP Certification Investment | Swiss Federal Office for Agriculture protocols protect geographic exclusivity against licensed foreign competition. |
| Cellar Automation Deployment | Sensor arrays and machine learning algorithms replicate affineur expertise at scale across multi-cellar operations. |
| Direct-to-Consumer Channel Launch | Cold-chain logistics enable cooperatives to bypass import distributors and capture subscription-based margin pools. |
| Summer Milk Provenance Program | Alpine flower-grazed milk documentation commands retail premiums through terroir differentiation narratives. |
| Licensed Production Protocol Expansion | Swiss AOP frameworks permit controlled foreign replication in import-restricted third-country markets. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with affineurs, cooperative managers, specialty retail buyers, and import distributors; and secondary validation through Swiss Federal Office for Agriculture inspection records, EU agricultural quality scheme documentation, FDA import compliance filings, and trade flow databases. Primary fieldwork captured tacit expertise in cellar management and aging protocols, while customs data and cold-chain logistics records anchored volume triangulation. Bottom-up wheel production estimates from Fribourg and Savoie cooperatives were cross-referenced against top-down consumption patterns in metropolitan retail channels.
Forecast inputs incorporated aging duration segmentation, distribution channel evolution, and end-use application shifts across the projection horizon. The analytical framework modeled cheese wheel, shredded, sliced, and block formats against specialty store, online retail, supermarket, and food service procurement channels. CAGRs were derived from supply-constrained growth trajectories in PDO-certified production and demand elasticity in premium household segments. Alpine meadow grazing cycles, affineur skill pipeline constraints, and digital traceability compliance costs shaped scenario boundaries.
Stress conditions across raw milk input volatility, cellar capacity bottlenecks, and regulatory friction in transatlantic trade were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cooperative automation adoption and licensed production protocol expansion. Quarterly review of Swiss AOP inspection tightening, FDA raw milk cheese policy evolution, and direct-to-consumer logistics maturity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Flavoured Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Cheese Color Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Sour Cream Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Skimmed Milk Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Japan Casein Market