
 North America Dairy Beverages Market | 2026-2036
North America Dairy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Beverages Market Analytics
Oat extract is pivoting toward cost parity with conventional dairy bases in flavored milk production. Chobani leverages its Greek yogurt expertise to anchor a growing functional beverage portfolio. Lactalis American Group sustains scale advantages through backward integration into fluid milk supply across the Upper Midwest. Organic Valley differentiates via cooperative ownership and certified organic sourcing that commands shelf-space premiums in natural retail channels.
North America dairy beverages comprise processed fluid milk, cultured products, and value-added formulations containing minimum milk solids and standardized fat content, typically pasteurized at 72°C for 15 seconds to ensure pathogen elimination while preserving nutritional integrity. These products serve hydration, protein delivery, and meal-replacement functions across consumer and commercial settings. Milk retains the largest volume footprint within the product type dimension, though flavored milk captures margin expansion through premium positioning in convenience retail. The packaging type dimension shows cartons maintaining dominance in retail grocery while pouches gain traction in foodservice portion control. Supermarkets within the distribution channel dimension remain the primary volume gatekeeper, though online retail is capturing incremental growth in subscription-based organic milk delivery.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen thresholds and interstate shipment eligibility, while USDA Organic certification governs label claims that command price premiums in household and retailer segments. Health Canada and the Canadian Food Inspection Agency maintain parallel dairy compositional standards that affect cross-border product harmonization and import access. Stakeholders must monitor evolving plant-based labeling disputes and state-level extended producer responsibility mandates for packaging recovery that will reshape cost structures and format selection.
Market Dynamics
The FDA's updated nutrition labeling requirements for added sugars are compressing reformulation timelines across fluid milk and flavored beverage portfolios, forcing processors to accelerate clean-label transitions while maintaining cost structures.
Growth Catalysts
- Clean-label menu expansion:Foodservice operators across the United States are broadening dairy beverage selections to capture health-conscious consumers. This pull is accelerating demand for minimally processed fluid milk and cultured products in commercial channels.
- Extended Producer Responsibility mandates:State-level packaging recovery regulations in California and New York are incentivizing format innovation. Carton-to-pouch transitions are gaining regulatory tailwinds that reduce lifecycle environmental footprints.
- Northeast corridor demand concentration:Fluid milk processing infrastructure intersects with premium yogurt consumption clusters across Massachusetts, Vermont, and New York. This geographic density reduces logistics costs and enables rapid SKU rotation.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings directly compress dairy processor margins. Input cost pass-through mechanisms remain constrained by retailer pricing power in fluid milk categories.
- Upper Midwest supply concentration:Lactalis American Group and cooperative networks dominate fluid milk sourcing across Wisconsin and Minnesota. This upstream consolidation limits negotiating leverage for mid-sized beverage formulators.
- Plant-based substitution acceleration:Oat extract formulations are approaching cost parity in flavored milk applications. Dairy processors face share erosion in convenience retail channels where alternative bases command shelf space.
Strategic Opportunities
- Functional beverage white space:Greek yogurt expertise is migrating into high-protein drinkable formats. Chobani's portfolio expansion signals untapped demand for meal-replacement dairy beverages in fitness and convenience segments.
- Subscription organic delivery:Online retail channels are capturing incremental volume in household milk replenishment. Natural retail cooperatives in the Pacific Northwest and New England are piloting direct-to-consumer models.
- USDA Organic certification arbitrage:Certified organic sourcing commands shelf-space premiums in natural retail channels. Cooperative ownership structures enable smaller processors to access premium pricing without captive supply investments.
Industry Challenges
- Reformulation timeline compression:FDA added-sugar disclosure requirements demand accelerated R&D cycles. Technical teams must rebalance sweetness profiles while maintaining microbial stability through 72°C pasteurization protocols.
- Cross-border harmonization friction:Health Canada and the Canadian Food Inspection Agency maintain parallel dairy compositional standards. US exporters face label adaptation costs and inspection delays at Ontario and Quebec entry points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Beverages Market |
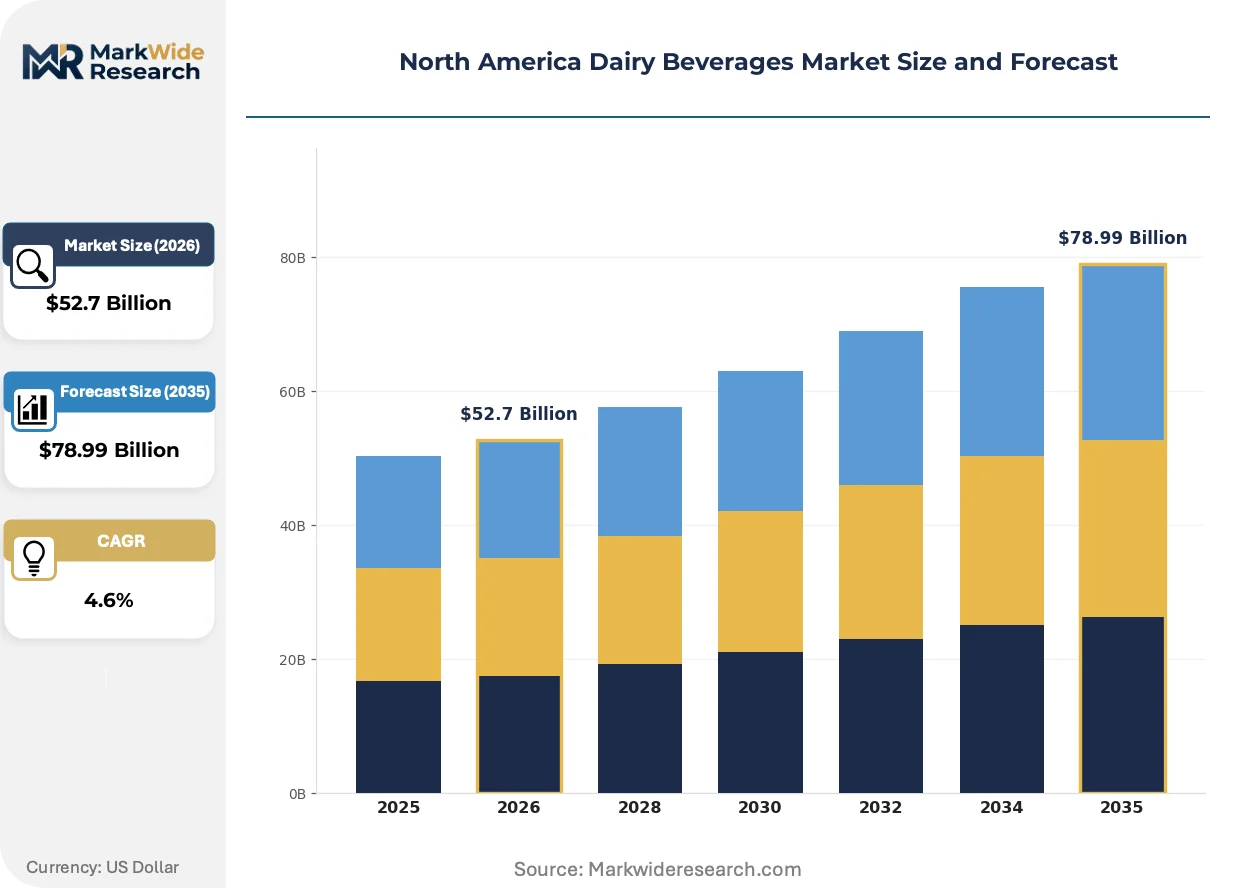
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $78.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Flavored Milk, Cream End User: Households, Foodservice, Retailers, Cafes Packaging Type: Bottles, Cartons, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | Agropur Dairy Cooperative, The Kraft Heinz Company, Dairy Farmers of America Inc, Organic Valley, Prairie Farms Dairy Inc, Nestlé USA, Lactalis American Group, Chobani, Saputo Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Beverages Market Evolving Landscape
Aseptic processing architectures and enzymatic modification techniques are rewriting cost curves for extended-shelf-life dairy beverages. These advances are compressing the gap between ambient-stable and refrigerated supply chains.
High-pressure processing technology is modularizing production footprints for regional dairy processors. Mid-sized cooperatives in Wisconsin and upstate New York are adopting compact HPP units to manufacture clean-label extended-shelf-life milk without centralized UHT infrastructure. This distributed processing model is compressing distribution radii and enabling direct-store-delivery economics previously reserved for national brands.
The FDA's Grade A Pasteurized Milk Ordinance enforcement is tightening pathogen threshold documentation for interstate fluid milk shipments. Processors must now maintain enhanced lot-tracking systems to demonstrate 15-second holding compliance at 72°C. Small and mid-sized operators in Texas and Florida are responding by consolidating under cooperative inspection umbrellas to spread compliance audit costs.
Buyer procurement patterns in foodservice channels are rotating toward portion-controlled pouch formats over traditional carton supply. K-12 nutrition directors and convenience store operators are specifying single-serve dairy beverages to reduce waste and enable grab-and-go merchandising. This format shift is most visible in the Mid-Atlantic corridor where urban school districts and transit-hub retail overlap.
North America Dairy Beverages Market Segmentation
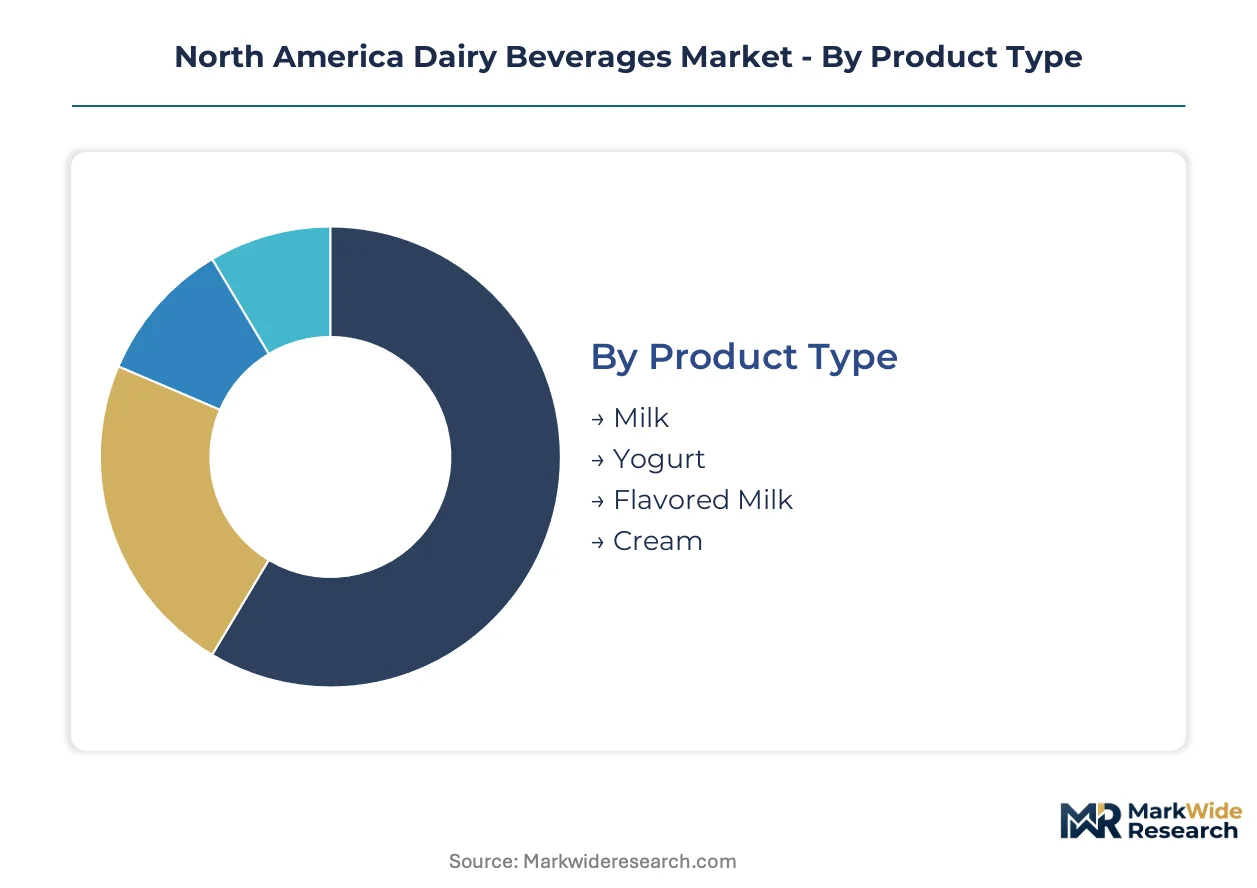
Segmentation in dairy beverages reveals how capital deployment, regulatory exposure, and channel economics fragment strategic priorities across processors. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across fluid milk infrastructure versus cultured product fermentation systems, with aseptic processing investments separating commodity players from value-added specialists.
- Milk:Standardized at minimum milk solids and pasteurized at 72°C for 15 seconds, fluid milk demands extensive cold-chain infrastructure. Northeast corridor processing plants in Massachusetts and Vermont absorb the bulk of Grade A compliance investments due to proximity to premium consumption clusters.
- Yogurt:Fermentation vessels and live culture maintenance require specialized clean-room environments. Greek yogurt expertise at Chobani anchors expanding functional beverage portfolios targeting fitness and meal-replacement demand.
- Flavored Milk:Reformulation timelines compress under FDA added-sugar disclosure mandates. Sweetness profile rebalancing without microbial stability compromise drives R&D spend concentration.
- Cream:Higher fat content standardization and specialized separation equipment characterize production. Foodservice operators specify portion-controlled formats for commercial baking and beverage applications.
Milk absorbs the bulk of installed capacity; yogurt is expanding most quickly.
End User:
Customer-type segmentation exposes divergent price elasticity and procurement sophistication, with institutional buyers leveraging volume concentration against fragmented household replenishment patterns.
- Households:Subscription-based organic milk delivery pilots in Pacific Northwest and New England cooperatives reshape replenishment economics. Direct-to-consumer models bypass traditional retail gatekeepers.
- Foodservice:Clean-label menu expansion across United States operators accelerates demand for minimally processed fluid milk. K-12 nutrition directors specify single-serve pouches to reduce waste.
- Retailers:Supermarket chains maintain volume gatekeeper status with captive shelf-space negotiations. Private-label pressure compresses branded processor margins in fluid categories.
- Cafes:Specialty coffee chains drive premium cream and flavored milk specifications. Barista-grade texture requirements demand higher fat content and homogenization precision.
Foodservice absorbs the bulk of installed capacity; households are climbing the fastest.
Packaging Type:
Format selection increasingly reflects state-level extended producer responsibility mandates rather than pure cost optimization, with California and New York regulations accelerating material transitions.
- Bottles:HDPE and PET formats dominate refrigerated retail shelves with established recycling streams. Higher material costs and weight logistics constrain foodservice adoption.
- Cartons:Gable-top and aseptic carton systems retain retail grocery dominance. Lifecycle environmental footprint pressures mount under emerging packaging recovery regulations.
- Pouches:Single-serve flexible formats gain traction in foodservice portion control. Mid-Atlantic urban school districts and transit-hub retail specify grab-and-go merchandising compatibility.
- Tetra Packs:Aseptic brick formats enable ambient-stable distribution without refrigerated infrastructure. Extended-shelf-life milk penetration depends on consumer acceptance of non-refrigerated storage.
Cartons absorb the bulk of installed capacity; pouches are gaining share fastest.
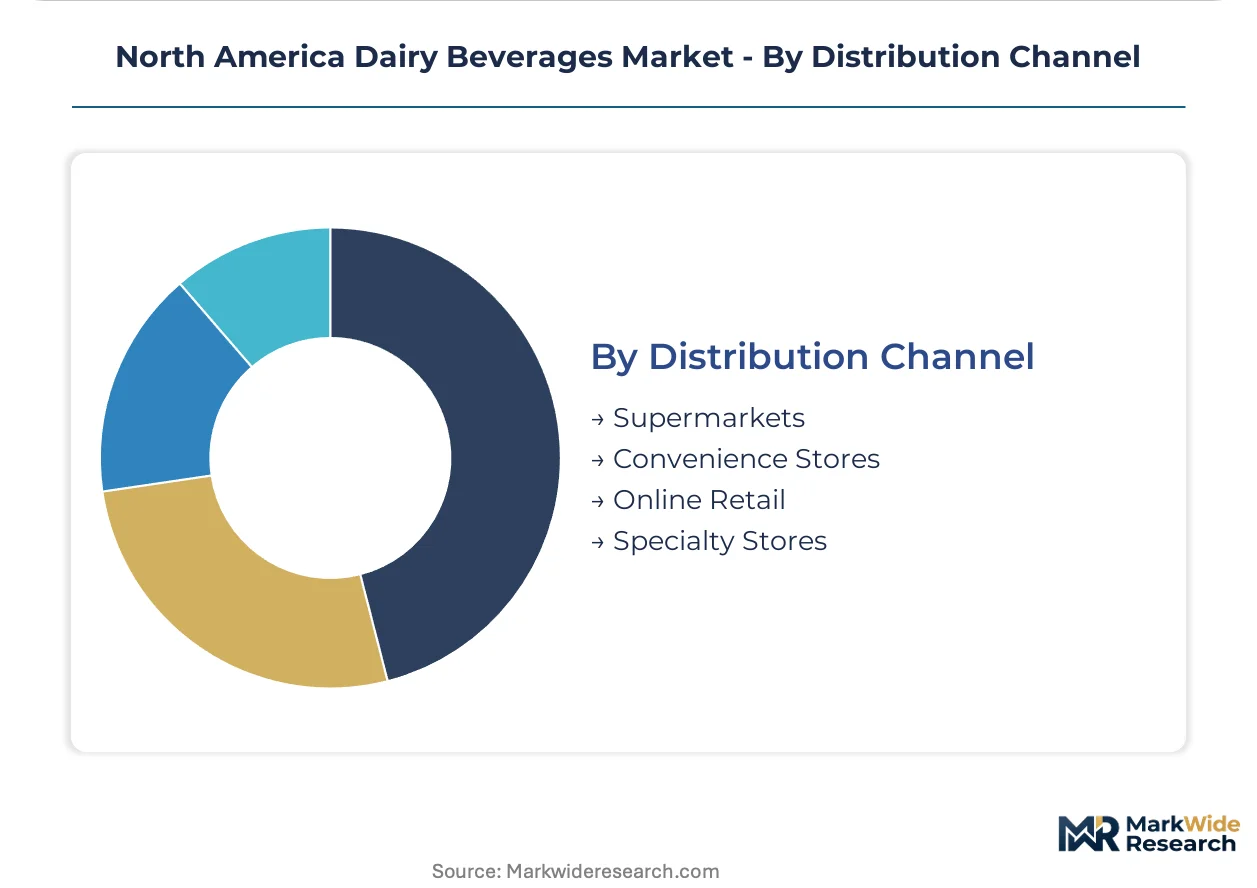
Distribution Channel:
Channel economics fragment between high-volume supermarket negotiations and emerging digital replenishment models, with logistics radius determining viable processor scale.
- Supermarkets:Primary volume gatekeepers with centralized distribution centers demanding consistent supply security. Northeast corridor density enables rapid SKU rotation for premium yogurt clusters.
- Convenience Stores:Grab-and-go merchandising drives single-serve and flavored milk concentration. Oat extract cost parity pressures dairy shelf-space allocation in this channel.
- Online Retail:Subscription organic delivery captures incremental household volume. Natural retail cooperatives pilot direct replenishment bypassing traditional wholesale tiers.
- Specialty Stores:Certified organic sourcing commands shelf-space premiums. Cooperative ownership structures enable smaller processors to access premium pricing without captive supply investments.
Supermarkets absorb the bulk of installed capacity; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Northeast corridor where fluid milk processing infrastructure intersects with premium yogurt consumption clusters. This geographic density reduces logistics costs and enables rapid SKU rotation for processors serving Massachusetts, Vermont, and New York markets.
United States
Foodservice operators across the country are expanding clean-label dairy beverage menus to capture health-conscious consumers. The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen thresholds and interstate shipment eligibility. Wisconsin and Minnesota host concentrated fluid milk supply networks where cooperative structures dominate upstream sourcing.
Canada
Health Canada and the Canadian Food Inspection Agency maintain parallel dairy compositional standards that affect cross-border product harmonization. Supply management systems stabilize farmgate pricing but limit import access for US exporters. Ontario and Quebec entry points generate label adaptation costs and inspection delays for American processors.
Mexico
Growing middle-class consumption drives demand for value-added dairy formulations in urban centers. The country's national food safety regulator enforces standards aligned with international Codex guidelines. Mexico City Metro anchors distribution networks for pasteurized fluid milk reaching central and southern regions.
Northeast Corridor
Premium yogurt consumption clusters in Massachusetts and Vermont absorb specialized fermentation capacity investments. State-level extended producer responsibility mandates in New York accelerate packaging format transitions. Boston and New York City retail density enables direct-store-delivery economics for organic milk subscription pilots.
Pacific Northwest
Natural retail cooperatives in Washington and Oregon pilot direct-to-consumer organic milk delivery models. Environmental regulations prioritize sustainable packaging recovery systems. Seattle and Portland metropolitan areas concentrate demand for certified organic sourcing that commands shelf-space premiums.
North America Dairy Beverages Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cooperative ownership structures occupying distinct competitive terrain from corporate processors. The vendor base organizes around three strategic archetypes: large-scale diversified dairy conglomerates, cooperative-owned organic specialists, and Greek yogurt-derived functional beverage innovators. M&A activity concentrates among fluid milk processors seeking geographic consolidation, while portfolio diversification drives investments in high-protein drinkable formats and extended-shelf-life technologies.
Within the cooperative tier, Organic Valley and Dairy Farmers of America exemplify ownership structures that enable premium pricing without captive supply investments. Chobani occupies a position bridging cultured product expertise and functional beverage expansion. Lactalis American Group anchors the scale-driven segment with backward integration advantages across Upper Midwest fluid milk supply.
| Leading Market Players |
|---|
| Agropur Dairy Cooperative |
| The Kraft Heinz Company |
| Dairy Farmers of America Inc |
| Organic Valley |
| Prairie Farms Dairy Inc |
| Nestlé USA |
| Lactalis American Group |
| Chobani |
| Saputo Inc |
| Others |
Value Network & Pricing Analysis
Feed cost volatility in corn and soybean meal cascades through fluid milk pricing tiers, compressing processor margins before cost pass-through mechanisms activate at retail gatekeepers. Grade A Pasteurized Milk Ordinance compliance investments concentrate in Northeast corridor plants, embedding regulatory overhead into premium yogurt and extended-shelf-life product pricing.
Pricing Analysis
Volume concentration in fluid milk commoditizes returns while yogurt and functional beverages capture margin expansion through certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified supply from conventional Grade A and private-label economy tiers. Pricing pressure stems from oat extract approaching cost parity in flavored milk applications, forcing sweetness profile rebalancing without microbial stability compromise. Foodservice operators exhibit lowest price sensitivity due to clean-label menu premiums, while convenience retail channels face highest sensitivity from plant-based substitution.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Vermont, and New York anchor hub-and-spoke patterns that compress logistics radii for premium consumption clusters. Fluid milk processing infrastructure concentrates in Wisconsin and Minnesota, with fermentation capacity clustering in upstate New York and Vermont. Raw material dependencies rest on corn and soybean meal inputs from Upper Midwest agricultural networks, coupled with live culture supply from specialized fermentation laboratories. Single-source vulnerability characterizes cooperative-dominated upstream sourcing, where Lactalis American Group and Dairy Farmers of America control fluid milk access. Distribution runs through supermarket centralized distribution centers with direct-store-delivery economics emerging in organic subscription pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid milk processing capacity constraints in the Northeast corridor prop pricing power for processors with compliant infrastructure. Upper Midwest supply concentration limits negotiating leverage for mid-sized formulators without cooperative membership.
For Market Incumbents: Anticipate plant-based substitution acceleration by accelerating clean-label reformulation timelines ahead of FDA added-sugar disclosure mandates. Defend share through backward integration into certified organic supply chains that command shelf-space premiums in natural retail channels. Prioritize aseptic processing investments to compress cost curves for extended-shelf-life formats. For New Entrants and Emerging Players: Begin with functional beverage white space targeting fitness and meal-replacement demand where Greek yogurt expertise migrates into high-protein drinkable formats. Pacific Northwest and New England subscription organic delivery pilots offer lowest competitive density. Pursue cooperative ownership structures to access premium pricing without captive supply investments. For Investors and Strategic Acquirers: FDA enforcement tightening on Grade A Pasteurized Milk Ordinance pathogen documentation is the leading indicator that compliance audit cost consolidation will accelerate cooperative acquisition activity. Five-to-ten year viability favors processors with distributed high-pressure processing footprints enabling regional clean-label production. Target mid-sized cooperatives in Wisconsin and upstate New York with compact HPP unit adoption. Watch state-level extended producer responsibility mandate expansion as signal for packaging format transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Supply | USDA Organic certification arbitrage commands shelf-space premiums in natural retail channels. |
| Aseptic Processing Capacity Addition | Extended-shelf-life technology compresses cost curves between ambient-stable and refrigerated supply chains. |
| Direct-to-Consumer Subscription Launch | Pacific Northwest cooperatives pilot organic milk delivery bypassing traditional wholesale tiers. |
| High-Pressure Processing Unit Adoption | Mid-sized Wisconsin and New York processors enable clean-label production without centralized UHT infrastructure. |
| Cooperative Consolidation Under Inspection Umbrellas | Texas and Florida operators spread Grade A compliance audit costs across member processors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with dairy processors, foodservice procurement directors, and retail category buyers. FDA Grade A Pasteurized Milk Ordinance documentation, USDA Organic certification databases, and Health Canada dairy compositional standards provided regulatory validation. Bottom-up volume modeling triangulated against top-down expenditure analysis across product type, end user, packaging format, and distribution channel dimensions.
Reconciliation of production volume data from state agriculture departments, fluid milk sales records from cooperative associations, and retail scanner data established baseline calibration. Segmentation modeling captured milk, yogurt, flavored milk, and cream categories across household, foodservice, retailer, and cafe end users. CAGRs derived from trend extrapolation adjusted for feed cost volatility, plant-based substitution rates, and regulatory timeline compression. Forecast inputs incorporated FDA added-sugar disclosure implementation pace and state-level extended producer responsibility mandate adoption curves.
Underlying measurement precision varies by segment; fluid milk and supermarket channel data carry tighter precision than emerging online retail and functional beverage categories. Forecasts reflect documented assumptions regarding pasteurization protocol compliance, interstate shipment eligibility thresholds, and cross-border harmonization friction. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Probiotic Beverage Market
Beverages
Tonic Water Market
Beverages
Italy Probiotic Drinks Market
Beverages
Cold Pressed Juice Market
Beverages
Bottled Air Market
Beverages
North America Fruit Juice Market
Beverages
Electrolyte Mixes Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Orange Juice Market
Beverages
Soy Drinks Market
Beverages
Cactus Water Market
Beverages
Apple Cider Vinegar Market
Beverages
Europe Beverage Market
Beverages
Spring Water Market
Beverages
Canned Beverages Market
Beverages
Beverage Cooler Market