
 Milk Retentate Market | 2026-2036
Milk Retentate Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Retentate Market Foresight
The capital-intensity divergence between membrane filtration infrastructure and traditional evaporative concentration is bifurcating competitive tiers in milk retentate supply. Fonterra Co-operative Group leverages its New Zealand grass-fed milk pool to anchor premium protein concentrate output. Arla Foods amba sustains integrated operations across Northern Europe, controlling whey retentate flows from farm to ingredient. Lactalis Ingredients dominates Southern European supply through specialized cream retentate production for industrial bakeries.
Milk retentate denotes the concentrated solids fraction remaining after membrane separation removes permeate water, typically achieving total solids of 18-36% depending on ultrafiltration or reverse osmosis configuration, and serves as the foundational input for standardized dairy ingredients in processed foods. The concentrated milk and cream categories within product type capture mature volume pools tied to beverage and bakery manufacturing, while dairy powder retentate concentrates faster growth through extended shelf-life logistics and infant formula application demand. Food processing anchors application volume through cheese standardization and yogurt fortification, yet nutraceuticals extracts expanding margin pools as bioactive protein fractions command ingredient premiums from pharmaceutical and sports nutrition formulators.
EU REACH and EFSA frameworks govern residual processing aid thresholds and protein content claims across European dairy ingredient trade, while FDA Grade A Pasteurized Milk Ordinance standards shape US import eligibility and product safety benchmarks for cross-border retentate shipments. China's SAMR and evolving GB dairy standards increasingly determine market access terms for foreign concentrate suppliers seeking infant formula ingredient qualification. Stakeholders must monitor regulatory divergence between jurisdictions on protein identity preservation and processing method disclosure as formulation specifications tighten across end-use segments.
Market Dynamics
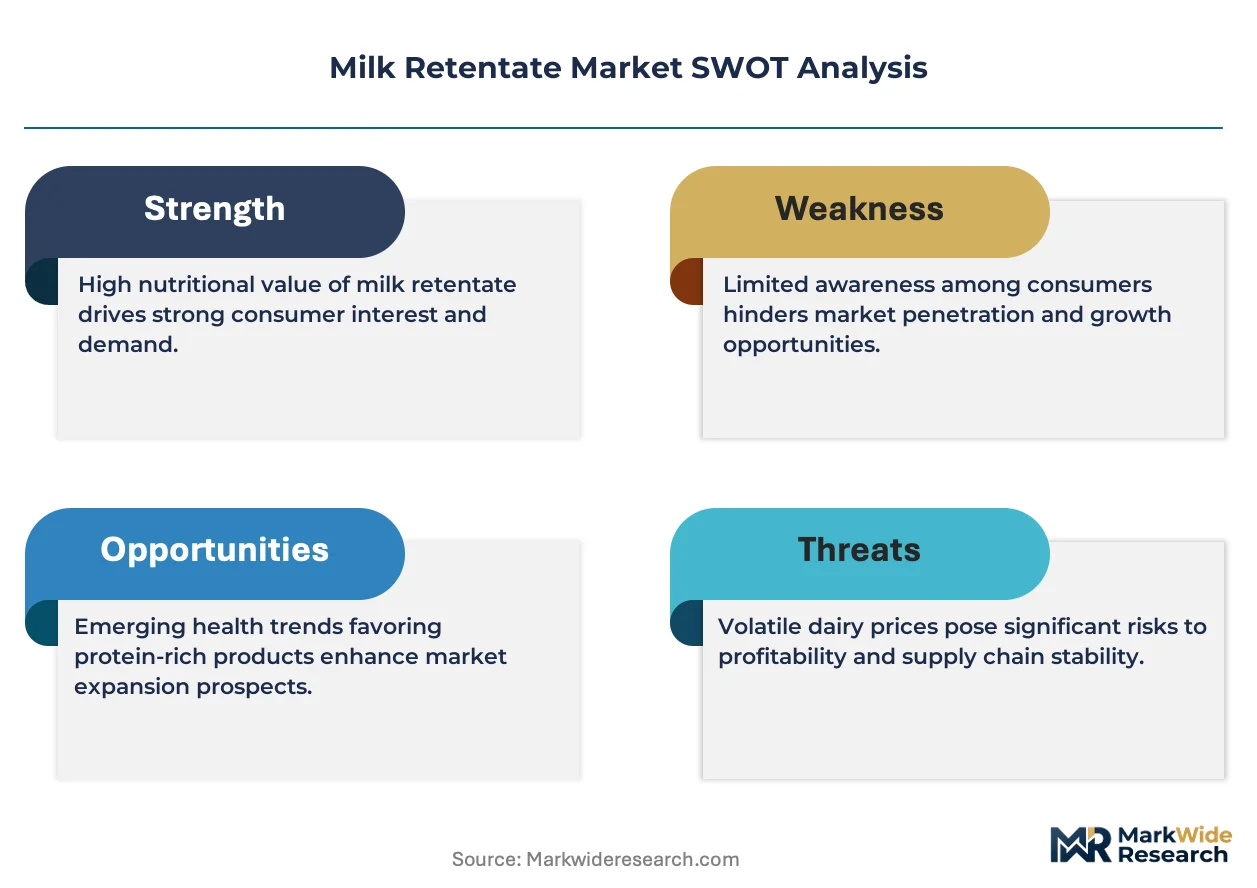
Membrane filtration infrastructure investment is splitting competitive tiers in milk retentate supply, separating capital-rich integrated processors from toll-dependent operators. This capital divergence reshapes pricing power and procurement relationships across dairy ingredient value chains.
Growth Catalysts
- Clean-label ingredient mandates:Food manufacturers in Germany and France now require processing method disclosure on protein concentrates. EFSA protein content claim frameworks validate retentate-derived ingredients for infant formula qualification.
- Extended shelf-life logistics:Dairy powder retentate concentrates enable ambient distribution to Southeast Asian beverage plants. Reverse osmosis configurations reduce water activity without thermal degradation.
- REACH chemical safety compliance:EU processing aid threshold reductions favor membrane-based concentration over evaporative methods. Retentate producers meeting ECHA residual limits capture bakery and confectionery contracts.
Market Restraints
- Skim milk powder price volatility:Input cost swings from New Zealand auction cycles compress retentate processor margins. Fonterra's GDT pricing transmits directly to European concentrate economics.
- Permeate disposal constraints:Environmental discharge permits for lactose-rich permeate tighten in the Netherlands and Denmark. Membrane operators face rising wastewater treatment capex.
- Infant formula regulatory friction:China's SAMR GB standard revisions delay foreign supplier qualification timelines. Protein identity preservation requirements exclude non-integrated traders.
Strategic Opportunities
- Sports nutrition bioactive fractions:Ultrafiltration diafiltration enables beta-lactoglobulin isolation for pharmaceutical formulators. Whey retentate processors in Bavaria already supply peptide ingredient houses.
- Carbon border adjustment positioning:EU CBAM implementation favors grass-fed milk pools with verified lower methane intensity. New Zealand suppliers gain credentialing advantage over intensive European operations.
- Direct-to-bakery channel development:Cream retentate producers bypass dairy traders by contracting industrial bakeries in Northern Italy. Specialized fat standardization commands ingredient premiums.
Industry Challenges
- Membrane fouling expertise scarcity:Ceramic and polymeric module maintenance requires specialized technicians. Dairy engineering programs in Lower Saxony and Wisconsin report insufficient graduate pipeline.
- Legacy evaporative asset stranding:Traditional concentration plants face accelerated depreciation against membrane alternatives. Multi-effect evaporator operators confront stranded cost write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Retentate Market |
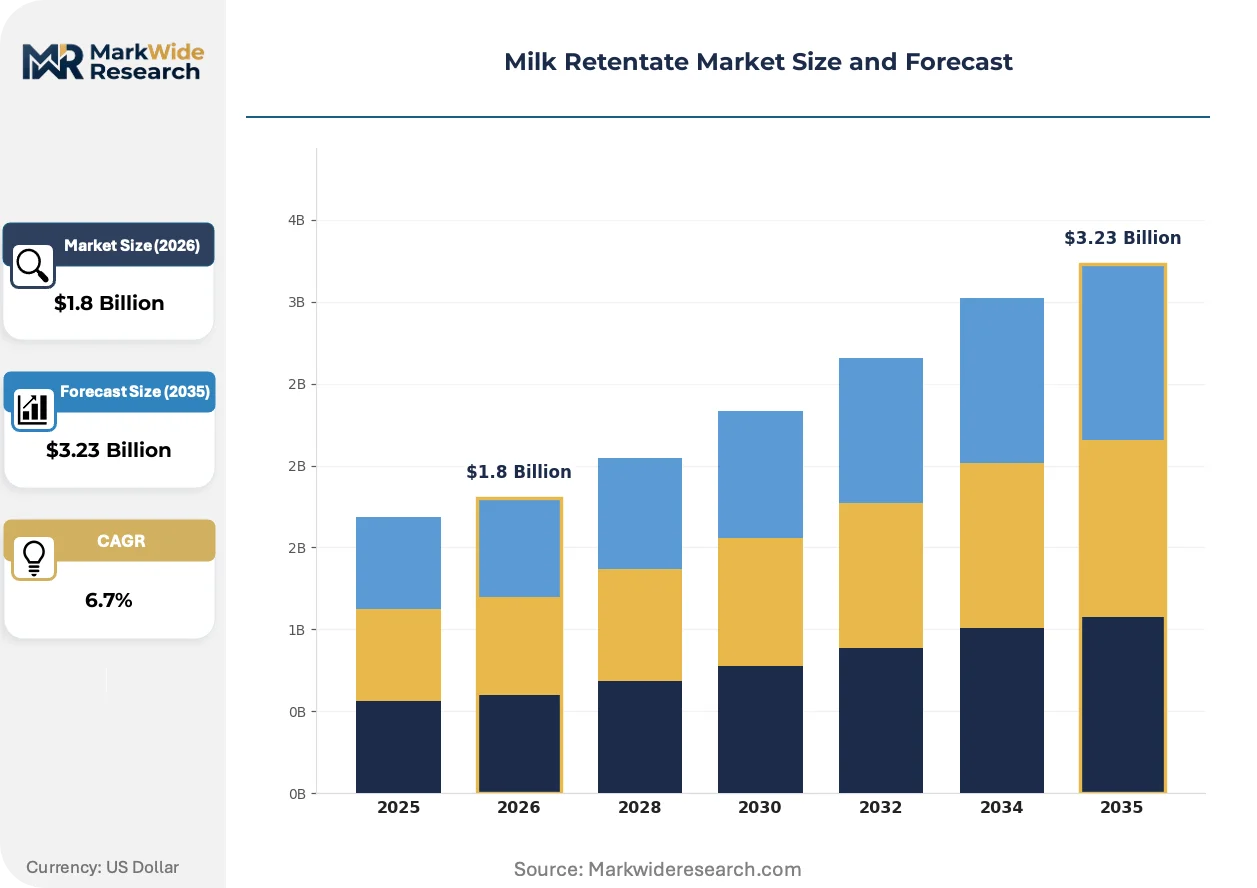
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Milk, Cream, Dairy Powder, Cheese Application: Food Processing, Nutraceuticals, Infant Formula, Dietary Supplements End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Retailers Distribution Channel: Online Retail, Wholesalers, Supermarkets, Specialty Stores |
| Companies Covered | Fonterra Co-operative Group, Arla Foods amba, Saputo Inc., Lactalis Ingredients, FrieslandCampina N.V., Glanbia plc, DMK Group, Valio Ltd., Agropur Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Retentate Market Shifts & Advancements
Advanced membrane configurations and protein fractionation technologies are redrawing technical boundaries between commodity concentrates and specialty ingredients. These developments compress legacy equipment lifecycles while opening premium application channels.
Spiral-wound ultrafiltration modules with modified polysulfone membranes now achieve 99.5% protein transmission at 50°C operating temperatures. Infant formula ingredient houses in Ireland and the Netherlands adopt these systems to reduce thermal denaturation. The technology is bifurcating the retentate market into heat-labile premium streams and commodity standard grades.
EU F-Gas Regulation phase-down schedules are accelerating adoption of ammonia-based refrigeration in membrane concentration plants. German dairy processors around Muenster retrofit cascade systems to replace hydrofluorocarbon chillers. Cold-chain dependent retentate logistics now face refrigerant compliance audits across Bavarian processing corridors.
Bakery procurement teams increasingly specify retentate solids content and mineral profiles rather than standardized commodity grades. Industrial manufacturers in Belgium and northern France negotiate direct supply agreements with membrane operators. This specification-driven purchasing compresses trader margins while rewarding processors with analytical certification capabilities.
Milk Retentate Market Segmentation
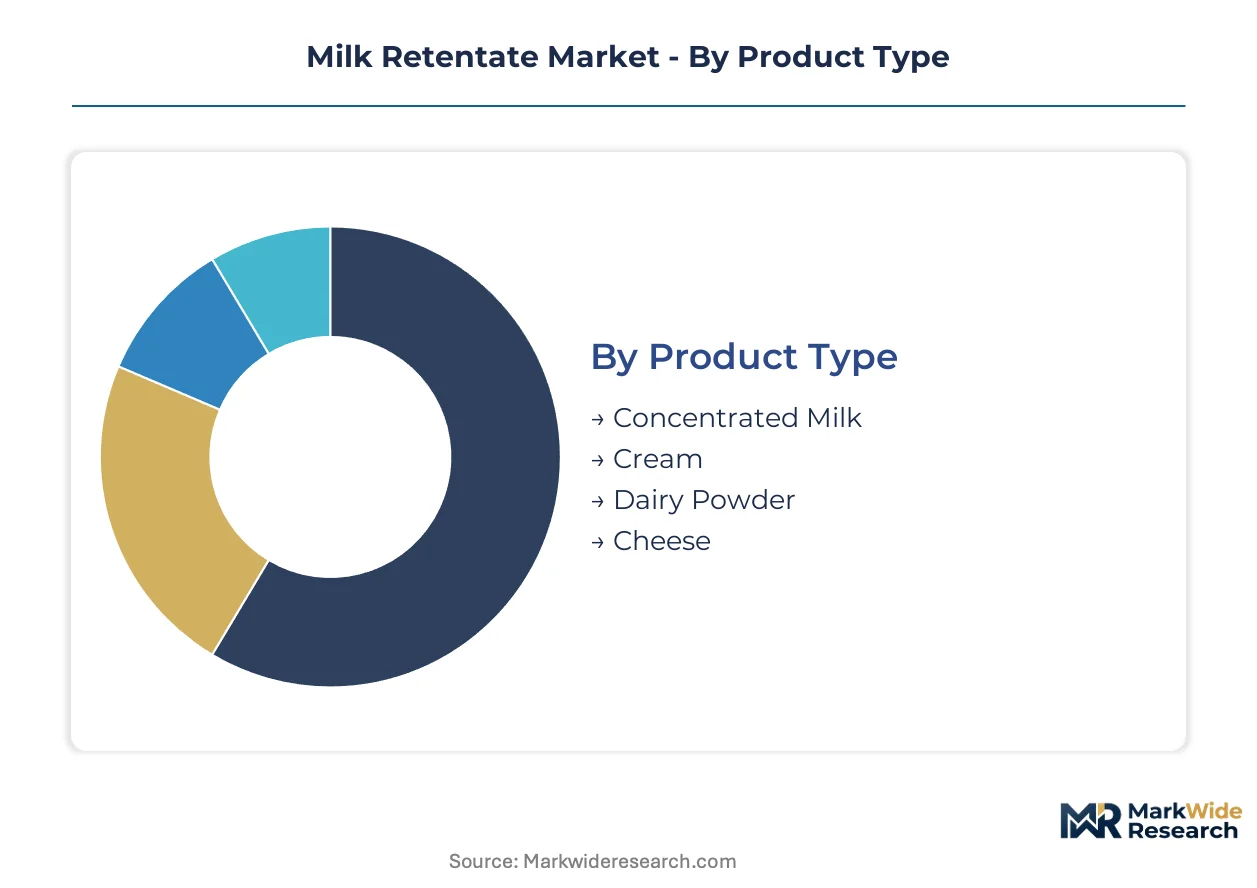
Milk retentate segmentation reflects divergent supply chain configurations across membrane filtration tiers. Product type and application splits determine whether processors serve domestic dairy standardization or export-oriented ingredient channels.
Product Type:
Geographic demand patterns split sharply between domestic fresh retentate consumption and export-destined powder concentrates. European membrane operators around Muenster and Bavaria anchor concentrated milk and cream supply for nearby food manufacturing, while New Zealand and Irish processors dominate dairy powder retentate flows to Asian infant formula markets.
- Concentrated Milk:Ultrafiltration concentrates achieving 18-22% total solids serve beverage standardization and yogurt fortification. German dairy processors in Lower Saxony deploy this grade for clean-label bakery applications, though permeate disposal constraints in the Netherlands and Denmark compress regional operator margins.
- Dairy Powder:Reverse osmosis and spray-dried concentrates enable ambient logistics to Southeast Asian beverage plants. Extended shelf-life specifications from China's SAMR GB standards drive qualification investments among Irish and Dutch infant formula ingredient houses.
- Cream:Fat-standardized retentate serves industrial bakery and confectionery manufacturing across Northern Italy and Belgium.
- Cheese:Protein-adjusted retentate supports mozzarella and processed cheese standardization in Wisconsin and Bavaria.
Concentrated milk commands the established base. The steepest expansion runs through dairy powder retentate.
Application:
Cost-tier stratification separates commodity food processing volumes from premium nutraceutical and infant formula qualification requirements. Membrane configuration investments bifurcate processors between standard-grade supply and bioactive fraction capabilities.
- Food Processing:Cheese standardization and yogurt fortification absorb mature retentate volumes across German and French dairy manufacturing. EFSA protein content claim frameworks validate membrane-derived ingredients for clean-label positioning, though Fonterra's GDT pricing transmits directly to European concentrate economics through skim milk powder input volatility.
- Infant Formula:Protein identity preservation requirements under China's SAMR GB standards exclude non-integrated traders. Ultrafiltration diafiltration systems in Ireland and the Netherlands achieve 99.5% protein transmission at reduced thermal exposure for peptide-sensitive formulations.
- Nutraceuticals:Beta-lactoglobulin isolation for sports nutrition commands ingredient premiums from pharmaceutical formulators in Bavaria.
- Dietary Supplements:Bioactive whey fractions target sports nutrition and clinical nutrition applications through specialized peptide ingredient houses.
Food processing anchors volume throughput. Infant formula qualification captures the steepest margin expansion trajectory.
End User:
Customer-type concentration shapes procurement relationships, with integrated dairy processors bypassing traders for direct bakery and beverage contracts. Specification-driven purchasing compresses intermediary margins while rewarding analytical certification capabilities.
- Food Manufacturers:Industrial bakeries in Belgium and northern France negotiate direct supply agreements with membrane operators for specified solids content and mineral profiles. Cream retentate producers in Northern Italy command premiums through specialized fat standardization.
- Beverage Companies:Southeast Asian plants source dairy powder retentate for ambient distribution, with reverse osmosis configurations reducing water activity without thermal degradation.
- Pharmaceutical Firms:Sports nutrition and clinical peptide formulators in Bavaria procure beta-lactoglobulin isolates from ultrafiltration diafiltration processors.
- Retailers:Private-label dairy ingredient sourcing concentrates among German and French supermarket chains with clean-label mandates.
Food manufacturers dominate procurement volume. Pharmaceutical firms drive the fastest margin capture through bioactive fraction premiums.
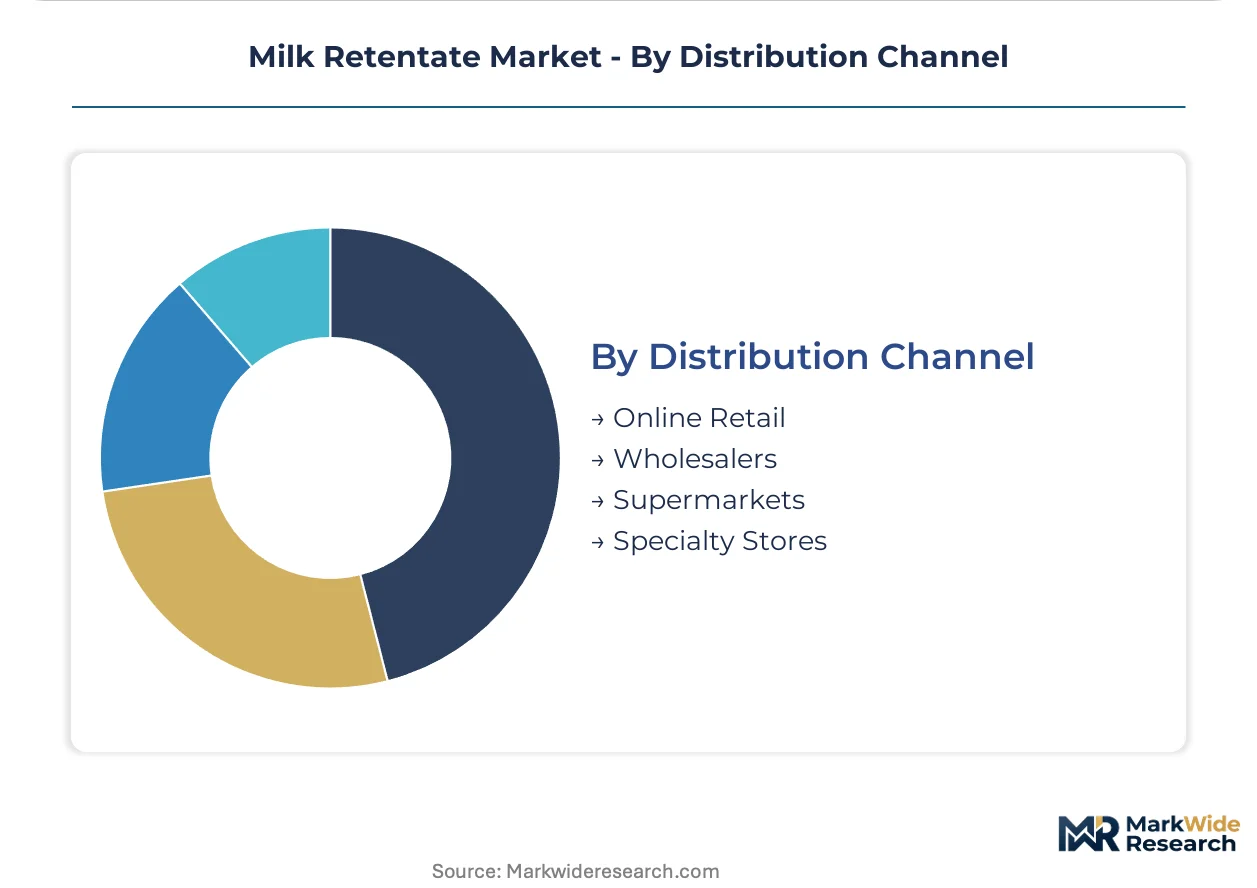
Distribution Channel:
Supply concentration in membrane filtration corridors determines channel efficiency, with Bavarian and Lower Saxony processors leveraging established dairy logistics networks against emerging direct-to-bakery contracting.
- Wholesalers:Traditional dairy ingredient traders face margin compression as industrial buyers specify analytical certification and processing method disclosure. Established networks around Muenster and Bavaria retain commodity-grade flows.
- Online Retail:Specialty protein concentrates and sports nutrition ingredients reach small-scale formulators through B2B platforms, though cold-chain requirements limit ambient powder categories.
- Supermarkets:Private-label dairy ingredient sourcing concentrates among French and German retail chains with EFSA-compliant clean-label positioning.
- Specialty Stores:Artisan bakery and confectionery supply channels in Belgium and Northern Italy procure specified cream retentate grades.
Wholesalers retain commodity volume dominance. Direct contracting through online platforms gains share fastest among specialty ingredient buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European membrane operators command ingredient premiums through EFSA-compliant certification, while New Zealand suppliers leverage grass-fed credentialing to offset freight costs into Asian infant formula channels.
Germany
Clean-label bakery mandates from industrial manufacturers in Lower Saxony and Bavaria drive ultrafiltration concentrate demand. EU REACH processing aid thresholds favor membrane-based concentration over legacy evaporative methods. The Muenster dairy processing corridor anchors concentrated milk supply for nearby beverage standardization plants.
China
Infant formula ingredient qualification requirements under SAMR GB standards create procurement concentration among integrated foreign suppliers. Protein identity preservation rules exclude non-integrated traders from pharmaceutical and clinical nutrition channels. Yangtze River Delta ingredient houses invest in ultrafiltration diafiltration systems to achieve reduced thermal exposure specifications.
United States
FDA Grade A Pasteurized Milk Ordinance standards shape import eligibility for cross-border retentate shipments from Canadian and Mexican processors. Cheese standardization demand in Wisconsin absorbs mature protein-adjusted retentate volumes. The Upper Midwest membrane filtration corridor faces technician scarcity as dairy engineering programs report insufficient graduate pipelines.
Netherlands
Environmental discharge permits for lactose-rich permeate tighten operational economics for membrane operators around Friesland. ECHA residual limits processing aid thresholds determine bakery and confectionery contract capture. Irish and Dutch infant formula ingredient houses dominate dairy powder retentate flows to Southeast Asian markets through extended shelf-life logistics.
New Zealand
EU Carbon Border Adjustment Mechanism implementation favors verified lower methane intensity from grass-fed milk pools. Fonterra's Global Dairy Trade pricing transmits directly to European concentrate economics through skim milk powder input volatility. Canterbury and Waikato processing clusters anchor premium protein concentrate output for Asian pharmaceutical formulators.
Milk Retentate Market Competitive Landscape
Concentration sits with integrated dairy cooperatives controlling membrane filtration infrastructure from farm to ingredient. Three structural tiers separate capital-rich operators with proprietary milk pools from toll-dependent processors and regional traders. Strategic differentiation runs through backward integration into grass-fed supply chains and forward integration into infant formula qualification channels. Capacity expansion in ultrafiltration diafiltration capabilities and direct-to-bakery contracting represent the dominant competitive vectors.
Within the cooperative archetype, Fonterra Co-operative Group and Arla Foods amba exemplify geographic milk pool anchoring strategies, while Lactalis Ingredients occupies a position representing specialized cream retentate production for industrial bakery channels. These three entities sit within distinct competitive vectors—Southern Hemisphere grass-fed credentialing, Northern European integrated operations, and Southern European fat standardization—each commanding ingredient premiums through divergent membrane configuration investments and end-use qualification capabilities.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Arla Foods amba |
| Saputo Inc. |
| Lactalis Ingredients |
| FrieslandCampina N.V. |
| Glanbia plc |
| DMK Group |
| Valio Ltd. |
| Agropur Cooperative |
| Others |
Supply & Pricing Matrix
Membrane filtration displacement of evaporative concentration is redrawing supply geography and pricing economics in milk retentate. Fonterra's grass-fed milk pools in New Zealand command credential premiums against European intensive operations, while EU REACH compliance costs bifurcate processors into certified premium tiers and standard commodity supply.
Pricing Analysis
The customization-premium spread separates configured-to-order ultrafiltration diafiltration output from standardized commodity concentrates. Contract-based long-term offtake dominates infant formula ingredient channels, with price differentiation resting on EFSA protein identity certification and SAMR GB qualification status. Cost compression in standard-grade concentrated milk intensifies as Fonterra's GDT pricing transmits skim milk powder volatility directly to European processor margins. Industrial bakeries in Belgium demonstrate highest price sensitivity through direct contracting, while pharmaceutical peptide formulators in Bavaria absorb premium spreads for bioactive fraction isolation.
Supply Chain Analysis
Germany, New Zealand, and the Netherlands anchor membrane filtration infrastructure for differentiated retentate output. Ceramic and polysulfone membrane modules, grass-fed milk pool access, and ECHA-compliant processing chemistry constitute critical input dependencies. Single-source vulnerability concentrates in New Zealand's Canterbury cluster, where Fonterra's integrated operations control premium protein concentrate flows to Asian pharmaceutical channels. Distribution runs through established dairy ingredient wholesalers around Muenster and Bavaria, though direct-to-bakery contracting in Northern Italy and Belgium compresses trader margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against plant-based protein isolate substitution in sports nutrition and infant formula channels. Regulatory qualification timelines and clean-label credentialing separate defensible premium positions from commodity exposure.
For Market Incumbents: Consolidate membrane filtration capacity in Lower Saxony and Bavaria to capture EFSA-compliant bakery contracts. Backward integration into verified grass-fed milk pools hedges EU Carbon Border Adjustment exposure against New Zealand competitors. Arla Foods amba's integrated Northern European operations demonstrate the procurement control required to exclude non-integrated traders from SAMR GB-qualified infant formula supply.
For New Entrants and Emerging Players: EFSA protein content claim fast-tracking opens white-space in German clean-label bakery procurement. Target industrial manufacturers in northern France specifying mineral profile certification rather than standardized commodity grades. Direct contracting with membrane operators bypasses established wholesale networks, capturing margin pools through analytical certification capabilities.
For Investors and Strategic Acquirers: China's SAMR GB standard revision reshapes the acquisition landscape toward integrated processors with infant formula qualification capabilities. Long-term viability favors operators controlling ultrafiltration diafiltration assets and proprietary milk pool access. The signal to watch is peptide-sensitive formulation demand from Bavarian pharmaceutical formulators, indicating bioactive fraction premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrafiltration Diafiltration Capacity Expansion | Enables 99.5% protein transmission for EFSA-compliant infant formula ingredients in Ireland. |
| Grass-Fed Milk Pool Backward Integration | Secures verified lower methane intensity credentials under EU CBAM implementation. |
| Direct-to-Bakery Channel Development | Bypasses dairy traders by contracting Belgian industrial manufacturers for specified solids content. |
| EFSA Protein Identity Certification Investment | Qualifies membrane-derived ingredients for clean-label positioning in German yogurt fortification. |
| Ammonia Refrigeration Retrofit Partnership | Replaces hydrofluorocarbon chillers to meet EU F-Gas Regulation phase-down schedules in Muenster. |
Research Methodology
The analysis maps concentrated milk, dairy powder, cream, and cheese retentate segments, each validated through membrane plant engineers, dairy procurement managers at industrial bakeries, infant formula ingredient qualification specialists, and EFSA regulatory affairs consultants. Primary interviews triangulate against customs trade data, Fonterra GTD auction records, ECHA processing aid threshold documentation, and SAMR GB standard filings. Bottom-up membrane capacity modeling and top-down dairy ingredient demand estimation cross-validate volume outputs.
Consistency checks against external benchmarks confirm analytical framework integrity across the projection horizon. Segmentation dimensions include product type, application tier, membrane configuration, and regional regulatory cluster. CAGRs derive from installed membrane filtration capacity expansion trajectories and infant formula ingredient qualification pipeline velocity. Forecast inputs incorporate EU REACH compliance cost curves and China's SAMR foreign supplier approval timelines.
Underlying assumptions cover EFSA protein claim framework stability and EU CBAM implementation trajectory, with deviation risk concentrated in SAMR GB standard revision timing and New Zealand GDT price volatility. Recalibration cycles align with material shifts in membrane technology cost curves and clean-label procurement mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Goat Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Ricotta Market
Dairy Products
Dairy Products Market
Dairy Products
Blue Cheese Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Dairy Blends Market