
 Europe Clinical Trials Market | 2026-2036
Europe Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clinical Trials Market Intelligence
The Europe clinical trials landscape is consolidating around a sharp split between premium, complex therapeutic studies and commoditized, routine trial execution services. IQVIA leverages its integrated data and site network to dominate high-value oncology and rare disease protocols across Western Europe. Parexel anchors its position through deep regulatory consulting capabilities that navigate EMA and national agency requirements. ICON competes on decentralized trial infrastructure, differentiating its technology-enabled delivery model from traditional site-dependent operators.
Clinical trials constitute regulated biomedical research studies that systematically evaluate safety, efficacy, and pharmacokinetic profiles of investigational drugs, biologics, or medical devices in human subjects under Good Clinical Practice (GCP) protocols with defined endpoints, inclusion criteria, and statistical powering. Their primary purpose generates evidence for regulatory marketing authorization and informs clinical guideline development. Oncology commands the largest share of initiated studies in Europe due to pipeline concentration in immuno-oncology and cell therapy, while Phase III trials absorb the greatest value given their scale, duration, and site infrastructure requirements. Pharmaceutical company funding drives the majority of trial volume, though government-supported investigator-initiated studies sustain academic medical center participation.
The European Medicines Agency (EMA) oversees centralized marketing authorization procedures, while the EU Clinical Trials Regulation (CTR) and GDPR impose stringent data integrity and patient privacy standards that shape protocol design and cross-border data transfer. National competent authorities in Germany, France, and Italy enforce Good Clinical Practice inspections that determine site qualification and trial approval timelines. Sponsors must monitor how the EU AI Act intersects with algorithm-driven patient recruitment and adaptive trial designs, as this regulatory boundary will influence technology investment decisions and partnership structures.
Market Dynamics
The EU Clinical Trials Regulation (CTR) harmonizes submission processes across member states while compressing approval timelines, fundamentally restructuring how sponsors allocate site networks and regulatory resources across Western Europe.
Growth Catalysts
- Oncology pipeline concentration:Immuno-oncology and cell therapy development is pulling sponsor investment toward Phase I/II investigator sites in Germany and the United Kingdom.
- EU CTR harmonization:The unified portal and database reduces redundant national submissions, accelerating multi-country trial activation across France, Italy, and Spain.
- Real-world evidence integration:EMA's expanded guidance on external control arms is enabling synthetic control methodologies that reduce placebo-arm recruitment burdens.
Market Restraints
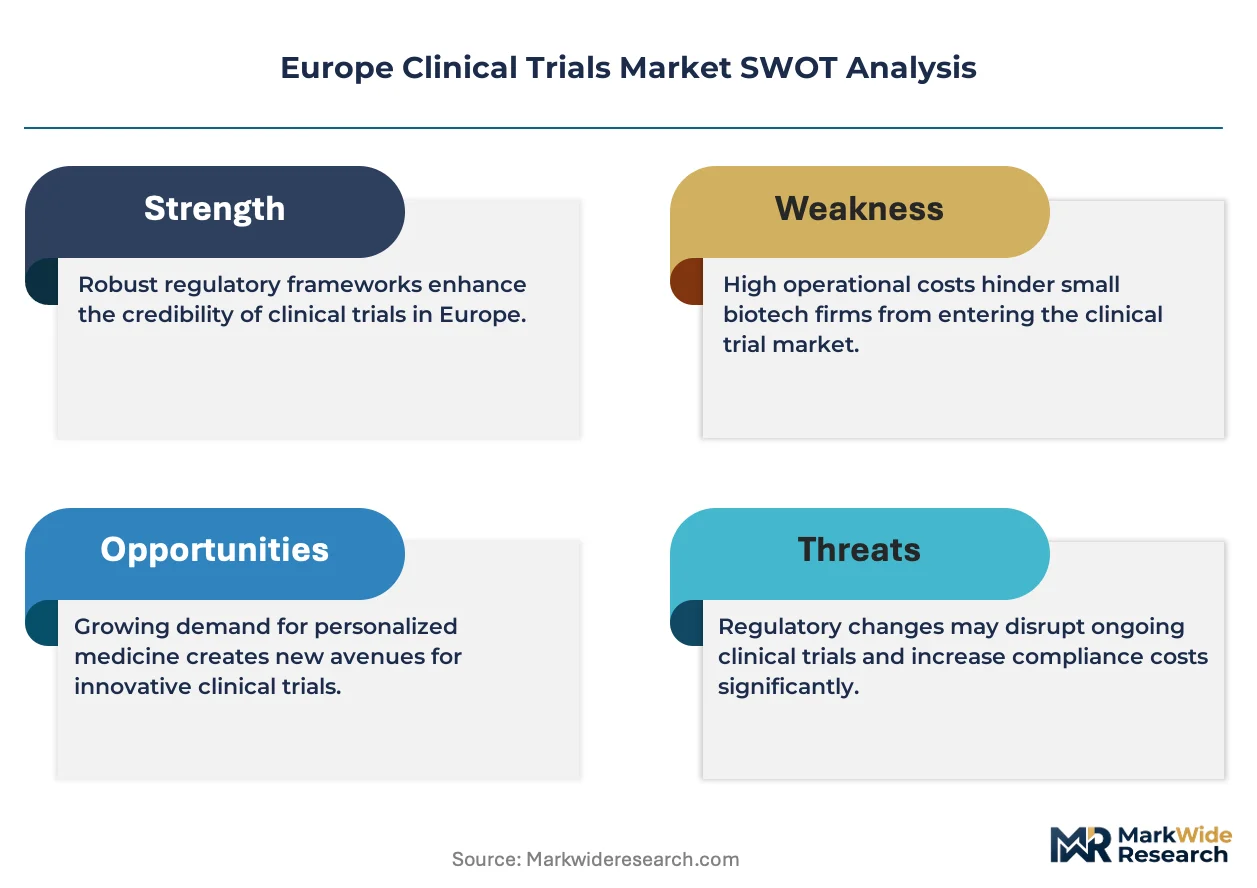
- GDPR compliance architecture:Cross-border data transfer requirements impose technical and legal infrastructure costs that disadvantage mid-sized academic sponsors without dedicated privacy offices.
- Investigator site concentration:Western European site density leaves Central and Eastern Europe structurally underrepresented in high-complexity protocols.
- Qualified personnel scarcity:Clinical research associate and data manager talent pools in the United Kingdom and Netherlands cannot absorb current demand expansion.
Strategic Opportunities
- Decentralized trial infrastructure:Direct-to-patient delivery models and remote monitoring technologies open site-agnostic recruitment across Poland, Hungary, and Czech Republic.
- EU AI Act alignment:Algorithm-driven patient stratification and adaptive design platforms gain regulatory clarity, creating first-mover advantage for technology-enabled contract research organizations.
- Rare disease networks:ERN (European Reference Networks) integration offers pre-qualified patient registries and biomarker-ready cohorts for orphan drug developers.
Industry Challenges
- Legacy system integration:Electronic data capture platforms from the CT Directive era require costly middleware to interface with the EU CTR portal.
- Good Clinical Practice inspectorate divergence:National competent authorities in Italy and Spain maintain divergent documentation expectations that complicate centralized quality management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clinical Trials Market |
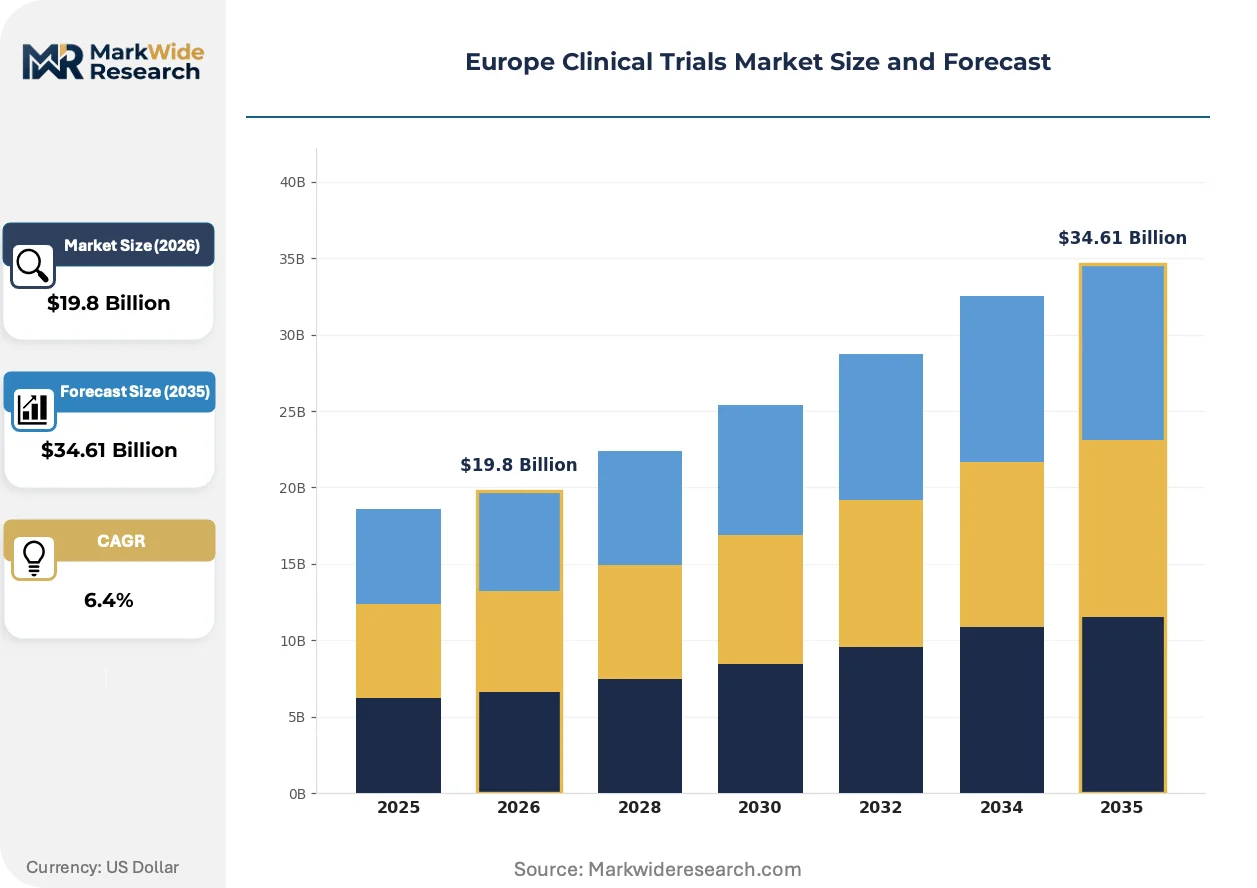
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Study Phase: Phase I, Phase II, Phase III, Phase IV Therapeutic Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Trial Design: Randomized Controlled, Observational, Open-label, Double-blind Funding Source: Government, Pharmaceutical Companies, Nonprofits, Private Investors |
| Companies Covered | IQVIA, Parexel, ICON, Syneos Health, Thermo Fisher Scientific, Novartis, AstraZeneca, F. Hoffmann-La Roche, Novo Nordisk, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clinical Trials Market Strategic Shifts & Innovations
Digital biomarker capture and federated analytics are compressing traditional site-dependent models while regulatory frameworks race to codify acceptable evidence standards for decentralized methodologies.
Distributed ledger technology for clinical data provenance is converging with immutable audit trails, creating tamper-evident chain-of-custody records that satisfy EMA inspection requirements. Mid-sized biotech sponsors in the Netherlands and Belgium are piloting these architectures for Phase II oncology studies. The structural consequence is a compression of query resolution cycles and source data verification burdens that previously consumed 15-20% of monitoring budgets.
The EU AI Act's risk classification framework for medical device software is forcing algorithm developers to restructure patient recruitment tools as bounded rather than autonomous decision systems. Sponsors deploying machine learning for eligibility screening must now embed human-in-the-loop checkpoints and explicability documentation. France's national competent authority, ANSM, is issuing early guidance that treats predictive enrollment forecasting as high-risk AI, requiring conformity assessments before deployment.
Hospital procurement departments in Germany and the United Kingdom are unbundling clinical trial management from traditional research contracting, creating separate vendor categories for data management, patient recruitment, and regulatory submission services. Academic medical centers now run competitive tenders for each function rather than awarding sole-source contracts to full-service contract research organizations. This fragmentation is most visible in the National Health Service's new framework agreements, which separate digital health technology assessments from clinical protocol execution.
Europe Clinical Trials Market Segmentation
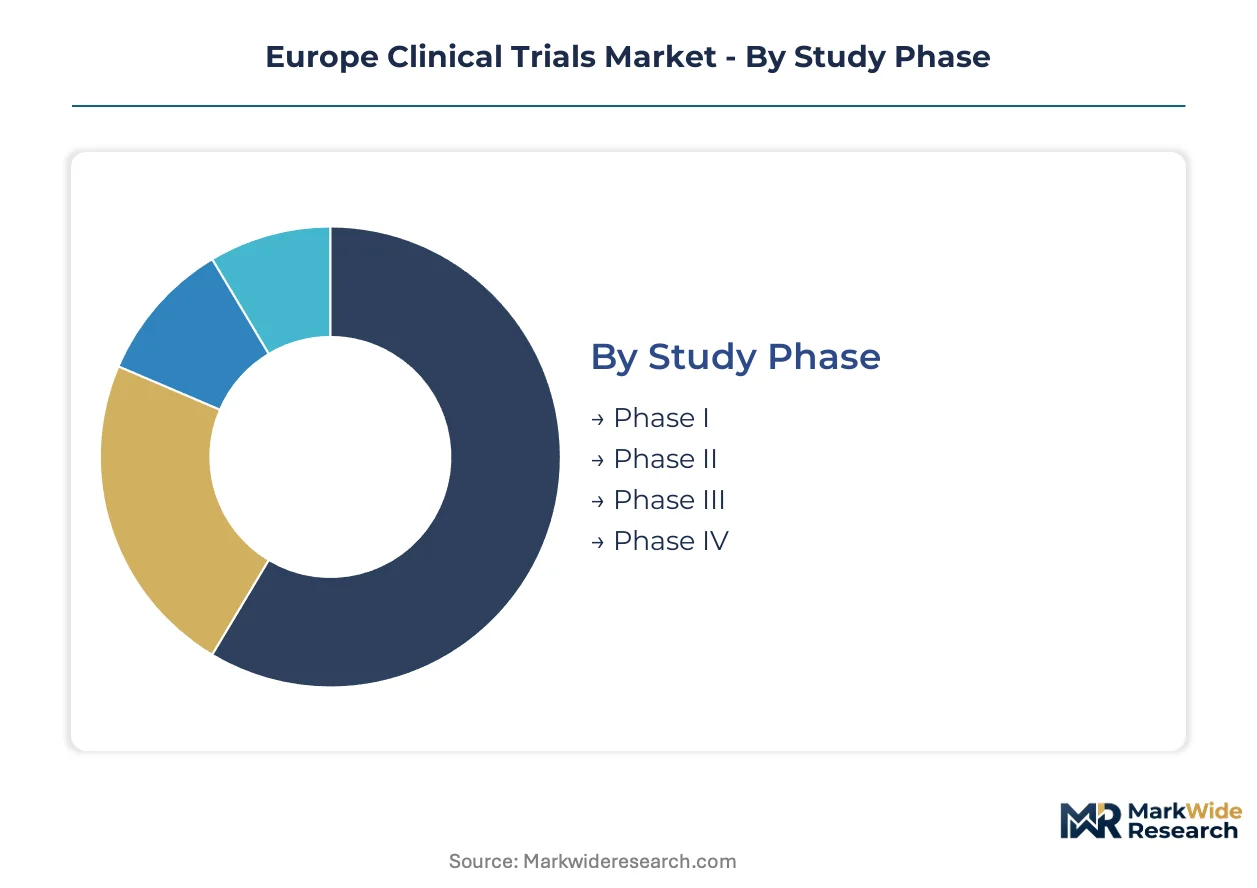
Segmentation in the Europe clinical trials market reveals where capital deployment concentrates and where regulatory complexity escalates. Pharmaceutical sponsors allocate budgets differently across study phases and therapeutic areas, with EMA pathway requirements and national competent authority inspections shaping investment returns.
Study Phase:
Capital intensity escalates dramatically from early-phase exploratory work through confirmatory trials, with site infrastructure and patient recruitment costs scaling non-linearly.
- Phase I:First-in-human and dose-escalation studies demand specialized clinical pharmacology units with intensive monitoring capabilities. Germany's dedicated Phase I facilities in Berlin and Munich absorb substantial sponsor investment due to experienced investigator pools and rapid ethics committee turnaround.
- Phase III:Large-scale confirmatory trials require multi-country site networks, extensive data management infrastructure, and lengthy regulatory follow-up. France and the United Kingdom concentrate the greatest Phase III value given their combined patient access and EMA rapporteur experience.
- Phase II:Proof-of-concept and dose-ranging studies occupy a middle tier of capital requirements with emphasis on biomarker validation and adaptive statistical designs.
- Phase IV:Post-marketing surveillance studies operate at lower per-patient cost but require broad primary care networks and real-world data integration capabilities.
Most installed capacity flows through Phase III. Expansion is steepest in Phase I.
Therapeutic Area:
Oncology commands disproportionate resources due to biomarker complexity and the prevalence of basket and umbrella trial designs requiring molecular screening infrastructure.
- Oncology:Immuno-oncology and cell therapy protocols drive the highest per-patient costs in European trials. The United Kingdom's Experimental Cancer Medicine Centres and Germany's National Center for Tumor Diseases anchor sponsor investment through integrated biobanking and genomic characterization capabilities.
- Neurology:Alzheimer's and Parkinson's disease trials face recruitment challenges and lengthy observation periods that inflate total study expenditure. France's hospital-based memory clinics and the Netherlands' brain bank networks concentrate specialized site capacity for neurodegenerative indications.
- Cardiovascular:Large endpoint-driven trials with hard clinical outcomes require extensive primary care integration and long-term follow-up infrastructure.
- Infectious Diseases:Antimicrobial resistance and vaccine development protocols vary widely in cost structure depending on controlled human infection model availability.
Most installed capacity flows through Oncology. Neurology is gaining share fastest.
Trial Design:
Methodological rigor directly determines regulatory acceptance probability and subsequent commercial value, with randomization and blinding requirements shaping operational budgets.
- Randomized Controlled:The gold standard for regulatory submission pairs random allocation with predefined statistical analysis plans. Spain's network of academic hospitals and Italy's regional health systems provide the balanced site distribution necessary for robust randomization across Southern Europe.
- Double-blind:Concealed treatment allocation eliminates performance and detection bias but demands complex drug supply chains and independent safety monitoring. Belgium's pharmaceutical packaging specialists and Switzerland's clinical trial material logistics hubs support intricate blinding requirements.
- Open-label:Unmasked designs reduce operational complexity for terminal illnesses or surgical interventions where blinding proves infeasible.
- Observational:Non-interventional studies leverage existing healthcare data with minimal per-patient cost but require sophisticated epidemiological methodology and registry access.
Most installed capacity flows through Randomized Controlled designs. Observational methodologies are expanding most quickly.
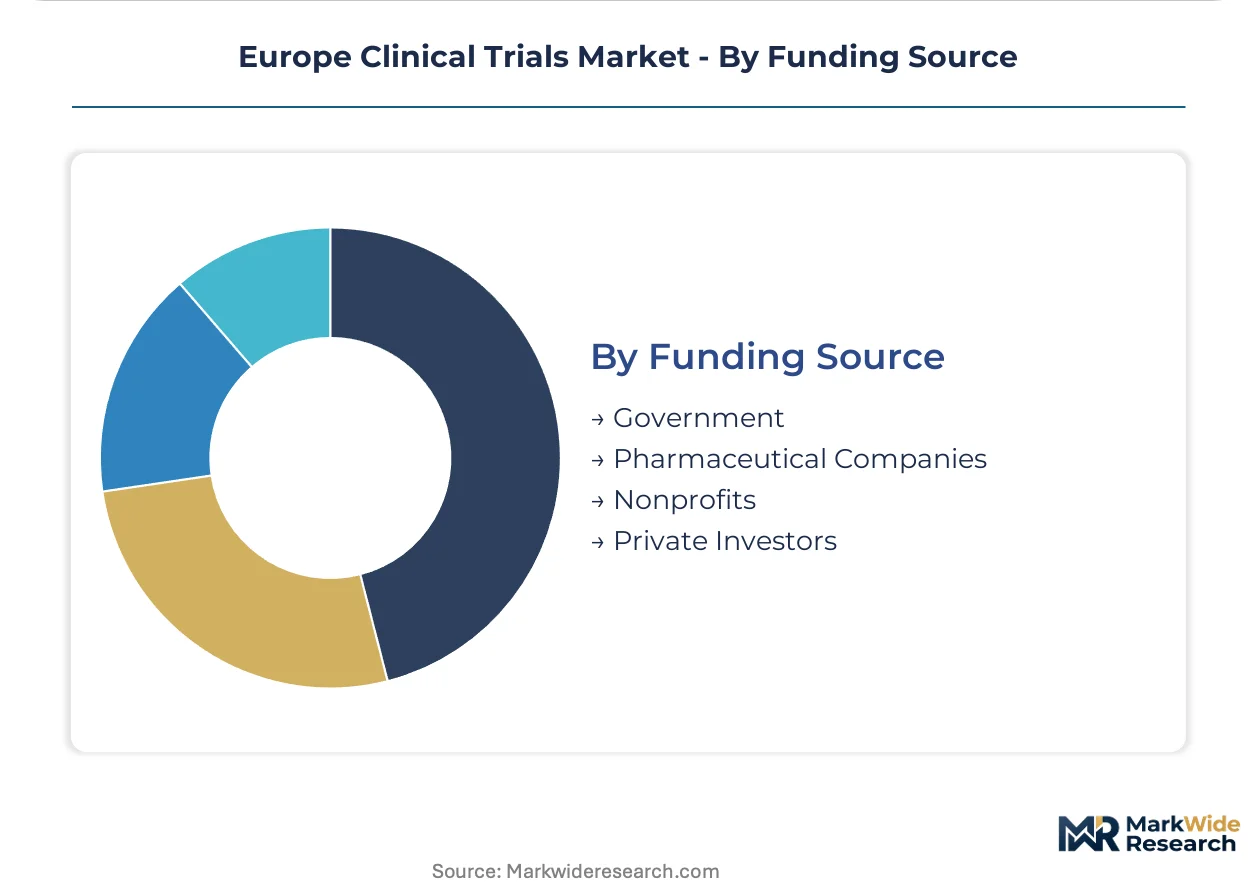
Funding Source:
Sponsor type determines budget flexibility, timeline pressure, and tolerance for regulatory risk across European jurisdictions.
- Pharmaceutical Companies:Fully funded commercial development programs command the largest absolute budgets with aggressive milestone timelines. Swiss and Danish mid-cap biotechs increasingly co-develop with larger partners to share Phase III costs across European site networks.
- Government:Horizon Europe and national research council grants sustain academic medical center participation with longer horizons but stricter audit requirements. Sweden's governmental innovation agency and Finland's research funding instruments exemplify public investment in investigator-initiated studies.
- Nonprofits:Disease foundation funding targets specific indications with patient advocacy engagement but limited total capital availability.
- Private Investors:Venture capital and private equity backing concentrates in platform technologies and novel modalities with clear European commercialization pathways.
Most installed capacity flows through Pharmaceutical Companies. Government funding is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's investigator site density outpaces France's regulatory throughput, while the United Kingdom maintains distinct competitive advantages in early-phase oncology infrastructure despite post-Brexit divergence from EMA centralized procedures.
Germany
Phase I clinical pharmacology units in Berlin and Munich attract immuno-oncology sponsors seeking rapid dose-escalation capabilities. The Federal Institute for Drugs and Medical Devices enforces GCP inspections that determine site qualification timelines. The National Center for Tumor Diseases in Heidelberg anchors genomic characterization infrastructure for basket trial designs.
United Kingdom
Experimental Cancer Medicine Centres concentrate early-phase immuno-oncology investment through integrated biobanking networks. The Medicines and Healthcare products Regulatory Agency operates parallel assessment pathways post-Brexit. London and Manchester host specialized cell therapy manufacturing facilities that support autologous treatment protocols.
France
Hospital-based memory clinics in Paris and Lyon sustain neurodegenerative disease recruitment for lengthy Alzheimer's observation studies. ANSM issues early guidance on AI-driven patient stratification tools under the EU AI Act risk classification framework. The Île-de-France region concentrates Phase III EMA rapporteur experience for centralized marketing authorization procedures.
Spain
Academic hospital networks in Barcelona and Madrid provide balanced site distribution for robust randomization across Southern Europe. The Spanish Agency for Medicines and Health Products maintains divergent documentation expectations that complicate centralized quality management. Andalusia's regional health system expands patient access infrastructure for cardiovascular endpoint trials.
Netherlands
Brain bank networks and specialized neurology centers in Amsterdam and Rotterdam concentrate neurodegenerative indication expertise. The Central Committee on Research Involving Human Subjects streamlines multi-center ethics approvals through a unified national framework. Leiden's biotech corridor houses contract research organizations specializing in adaptive statistical designs.
Europe Clinical Trials Market Key Industry Players
Top-tier vendors anchor integrated data and site network capabilities, while mid-tier operators compete on decentralized trial infrastructure and regulatory consulting specialization. The market structure reflects consolidation around full-service contract research organizations with EMA rapporteur experience. Three archetypes dominate: technology-enabled delivery platforms, regulatory consulting specialists, and rare disease network integrators. Competitive moves center on strategic partnerships for AI-driven patient recruitment and geographic expansion into Central and Eastern European site networks.
Among North American-headquartered service providers, IQVIA, Parexel, and ICON occupy positions across different competitive vectors. IQVIA exemplifies the integrated data archetype through its site network dominance in Western European oncology protocols. Parexel represents regulatory consulting specialization with deep EMA and national agency navigation capabilities. ICON sits within the technology-enabled tier, differentiating through decentralized trial infrastructure that reduces site-dependent operational constraints.
| Leading Market Players |
|---|
| IQVIA |
| Parexel |
| ICON |
| Syneos Health |
| Thermo Fisher Scientific |
| Novartis |
| AstraZeneca |
| F. Hoffmann-La Roche |
| Novo Nordisk |
| Others |
Cost & Logistics Intelligence
Captive site network ownership among IQVIA and Parexel anchors both supply security and pricing power in high-complexity oncology protocols across Germany and the United Kingdom. This vertical integration into investigator infrastructure insulates premium service tiers from commoditization pressures affecting mid-tier contract research organizations.
Pricing Analysis
Capacity additions in Central and Eastern Europe are reshaping price floors for routine trial execution services while premium oncology and rare disease protocols sustain project-based pricing with extensive biomarker validation. Three-tier pricing structure across premium, standard, and economy levels separates full-service EMA navigation from modular data management and site-only contracting. Cost compression in the standard tier intensifies because Polish and Hungarian entrants compete on per-patient costs. Academic sponsors and mid-cap biotechs exhibit greatest price sensitivity, while large pharmaceutical companies prioritize regulatory throughput over unit economics.
Supply Chain Analysis
Freight costs for temperature-sensitive investigational products and cell therapy materials concentrate supply planning around Belgium's clinical trial logistics hubs and Switzerland's packaging specialists. Germany, the United Kingdom, and France anchor investigator site capacity, while Italy and Spain provide secondary site networks for cardiovascular endpoint studies. Supply chain risk centers on single-source vulnerability for specialized Phase I clinical pharmacology units in Berlin and Munich. Distribution runs through centralized depot networks with regional satellite facilities for direct-to-patient delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe clinical trials market compounds steadily as biopharmaceutical pipeline concentration in oncology and rare diseases sustains sponsor investment regardless of macroeconomic cycles.
For Market Incumbents: Hedge regulatory consulting margin erosion by embedding AI-driven patient stratification tools ahead of EU AI Act conformity deadlines. Acquire adaptive statistical design capabilities in the Netherlands and Belgium to defend against technology-enabled entrants. Prioritize investigator site exclusivity arrangements in Germany's National Center for Tumor Diseases network. For New Entrants and Emerging Players: Launch via decentralized trial infrastructure partnerships in Poland, Hungary, and Czech Republic where site-agnostic recruitment meets unmet demand. Target Phase II proof-of-concept studies for neurology indications where France's hospital-based memory clinics and Netherlands brain bank networks concentrate specialized capacity. Differentiate through real-world evidence integration and synthetic control methodologies. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regulatory consulting specialists because national competent authority divergence in Italy and Spain fragments quality management capabilities. Five-to-ten year viability hinges on EMA rapporteur experience and ERN network integration. Monitor EU AI Act enforcement patterns as the inflection signal for technology-enabled contract research organization valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU CTR Portal Integration | Harmonized submission processes compress multi-country trial activation timelines across France, Italy, and Spain. |
| Decentralized Trial Infrastructure | Direct-to-patient delivery models unlock recruitment in Central and Eastern European underpenetrated markets. |
| AI-Driven Patient Stratification | Algorithmic eligibility screening gains regulatory clarity under EU AI Act risk classification frameworks. |
| ERN Network Partnership | European Reference Networks integration provides pre-qualified rare disease patient registries for orphan drug developers. |
| Real-World Evidence Platform | Synthetic control methodologies reduce placebo-arm recruitment burdens per expanded EMA guidance. |
Research Approach
Bottom-up therapeutic area modeling reconciled against top-down sponsor budget tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at EMA and national competent authorities, hospital procurement managers, and contract research organization business development directors combined with secondary validation from ClinicalTrials.gov, EMA submission databases, and national ethics committee approval records. Top-down triangulation against pharmaceutical R&D expenditure disclosures and investigator site capacity surveys ensures coverage completeness.
Historical trendline analysis of initiated study counts and per-patient cost trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include study phase, therapeutic area, trial design methodology, and funding source archetype. CAGRs derive from sponsor budget allocation patterns and site infrastructure expansion rates. Forecast inputs incorporate EU CTR implementation pace and decentralized trial technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GDPR enforcement escalation or EU AI Act reclassification of predictive enrollment tools. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
India Preclinical CRO Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
North America Contract Research Organization Market