
 Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market | 2026-2036
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market Insights
Oncology trial demand is shifting toward decentralized models that reduce patient travel burden. Marken leverages its specialized cell-and-gene therapy network to anchor high-complexity shipments. Thermo Fisher Scientific sustains R&D intensity across clinical supply chain automation. World Courier dominates temperature-controlled transport for Phase III biologics.
Clinical trial logistics and direct-to-patient delivery platforms encompass the coordinated movement of investigational drugs, biological samples, and patient kits between sponsors, clinical sites, and residential endpoints under validated cold chain conditions with real-time visibility. These systems employ IoT-enabled temperature loggers, GPS tracking, and cloud-based chain-of-custody documentation to maintain GxP compliance across ambient, refrigerated, frozen, and cryogenic ranges. Service type segmentation shows temperature-controlled transport capturing the largest revenue pool due to biologic proliferation, while patient enrollment support represents the fastest-expanding category as sponsors compete for rare-disease populations. Technology segmentation reveals cold chain monitoring as the established margin center, with blockchain adoption accelerating for immutable audit trails in multi-site trials.
FDA oversight through 21 CFR Part 11 and the Drug Supply Chain Security Act governs electronic records and serialization requirements for investigational products. EMA's EU Clinical Trials Regulation and GDP guidelines for investigational medicinal products establish harmonized standards across member states, while Japan's PMDA enforces strict import licensing for foreign-sourced trial materials. Stakeholders must monitor evolving regulator expectations around direct-to-patient distribution models, as FDA draft guidance on decentralized trials and EMA qualification opinions for digital health technologies signal forthcoming compliance frameworks that will reshape operational requirements.
Market Dynamics
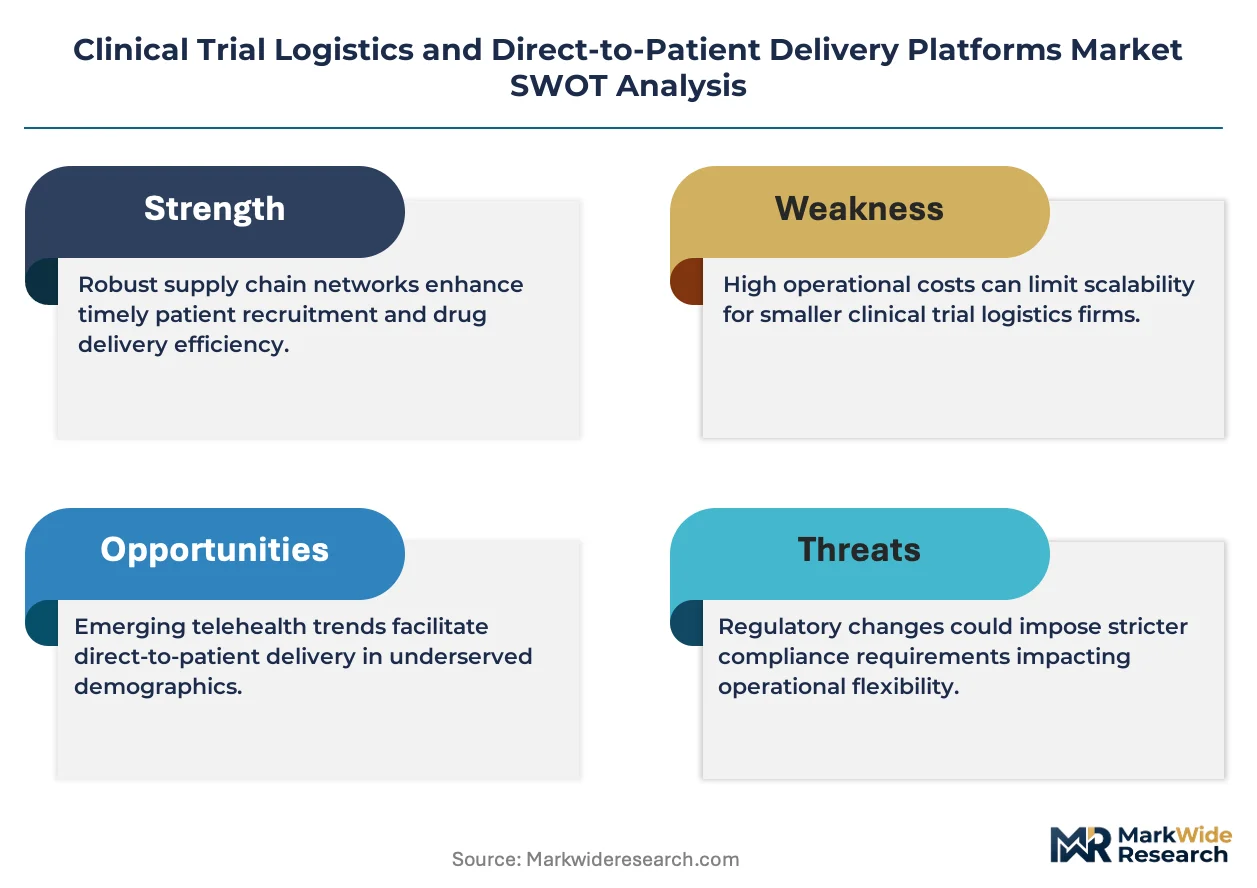
The FDA's risk-based monitoring framework and EU MDR requirements for investigational medicinal products are compressing sponsor timelines while elevating documentation burdens across decentralized trial protocols.
Growth Catalysts
- Oncology Trial Complexity:Cell-and-gene therapy proliferation demands validated cryogenic logistics chains that only specialized providers can construct. Sponsors now mandate direct-to-patient delivery for immuno-oncology protocols.
- 21 CFR Part 11:FDA electronic records requirements drive cloud-based chain-of-custody platform adoption. Compliance automation reduces audit preparation cycles from months to weeks.
- Rare-Disease Patient Recruitment:Geographic dispersion of trial participants forces sponsors into home-based drug delivery models. Japan's PMDA import licensing pathways for foreign-sourced materials now accommodate patient-resident endpoints.
Market Restraints
- Qualified Personnel Scarcity:GDP-certified logistics coordinators command premium compensation in Germany and Switzerland. Training pipelines cannot match biologic shipment volume expansion.
- Single-Source Cold Chain Equipment:Cryogenic dewar manufacturing concentrates among three European suppliers. Lead times for validated containers now exceed eighteen months.
- EU Clinical Trials Regulation Harmonization Gaps:Member-state implementation timelines vary by eighteen to thirty-six months. Sponsors face duplicate documentation requirements in France and Italy.
Strategic Opportunities
- Blockchain Audit Trails:Immutable ledger technology converges with IoT temperature loggers. Multi-site trials in the United States now pilot decentralized verification.
- India's CDSCO Streamlined Approvals:Investigational medicinal product import licensing timelines compressed from ninety to forty-five days. Western sponsors establish regional distribution hubs in Mumbai and Hyderabad.
- Digital Health Technology Qualification:EMA qualification opinions create regulatory tailwind for remote patient monitoring integration. Wearable-enabled adherence tracking expands addressable trial populations.
Industry Challenges
- Legacy ERP Integration:Sponsor inventory management systems lack API connectivity to logistics visibility platforms. Custom middleware development consumes six to nine months per deployment.
- Certified Depot Capacity:GMP-compliant storage for temperature-sensitive biologics requires specialized infrastructure. Construction timelines for new facilities extend thirty-six to forty-eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market |
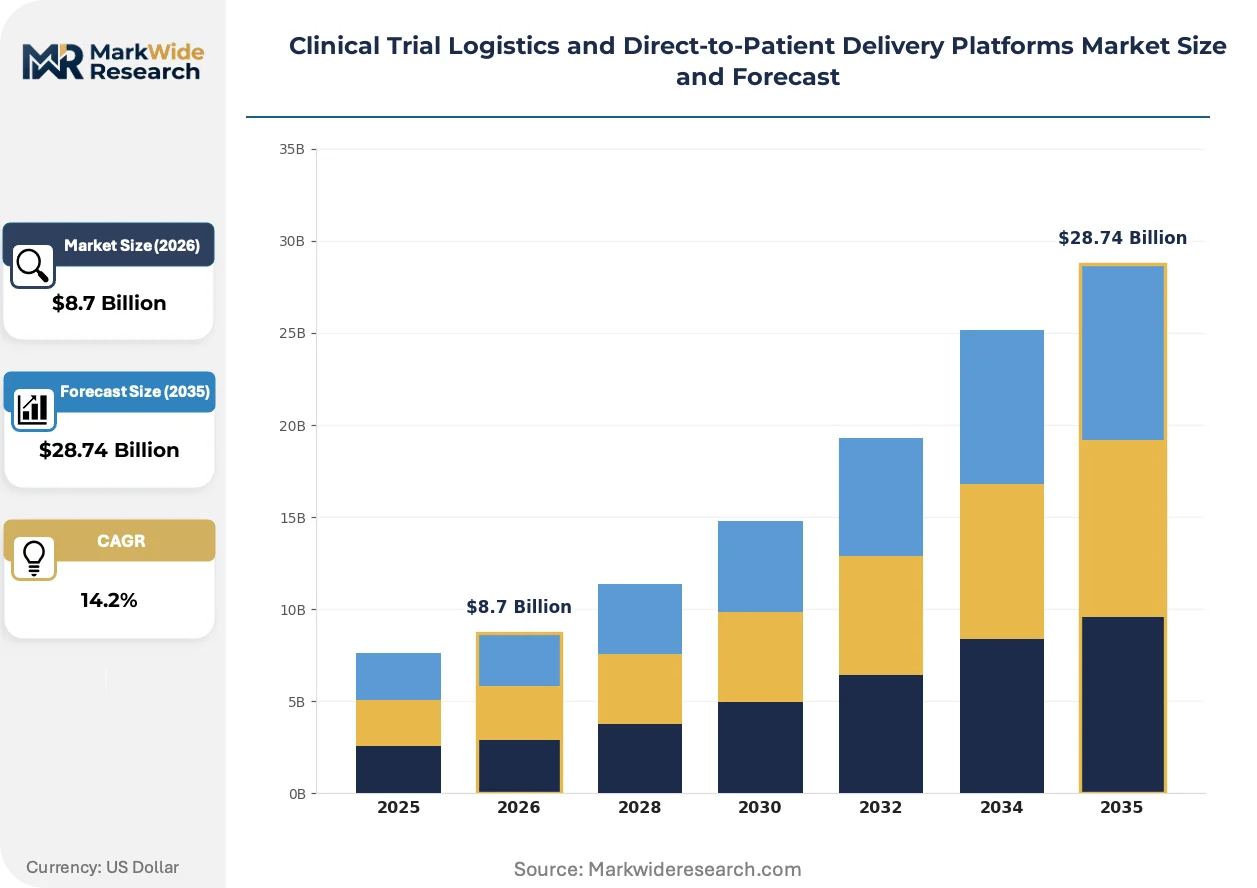
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
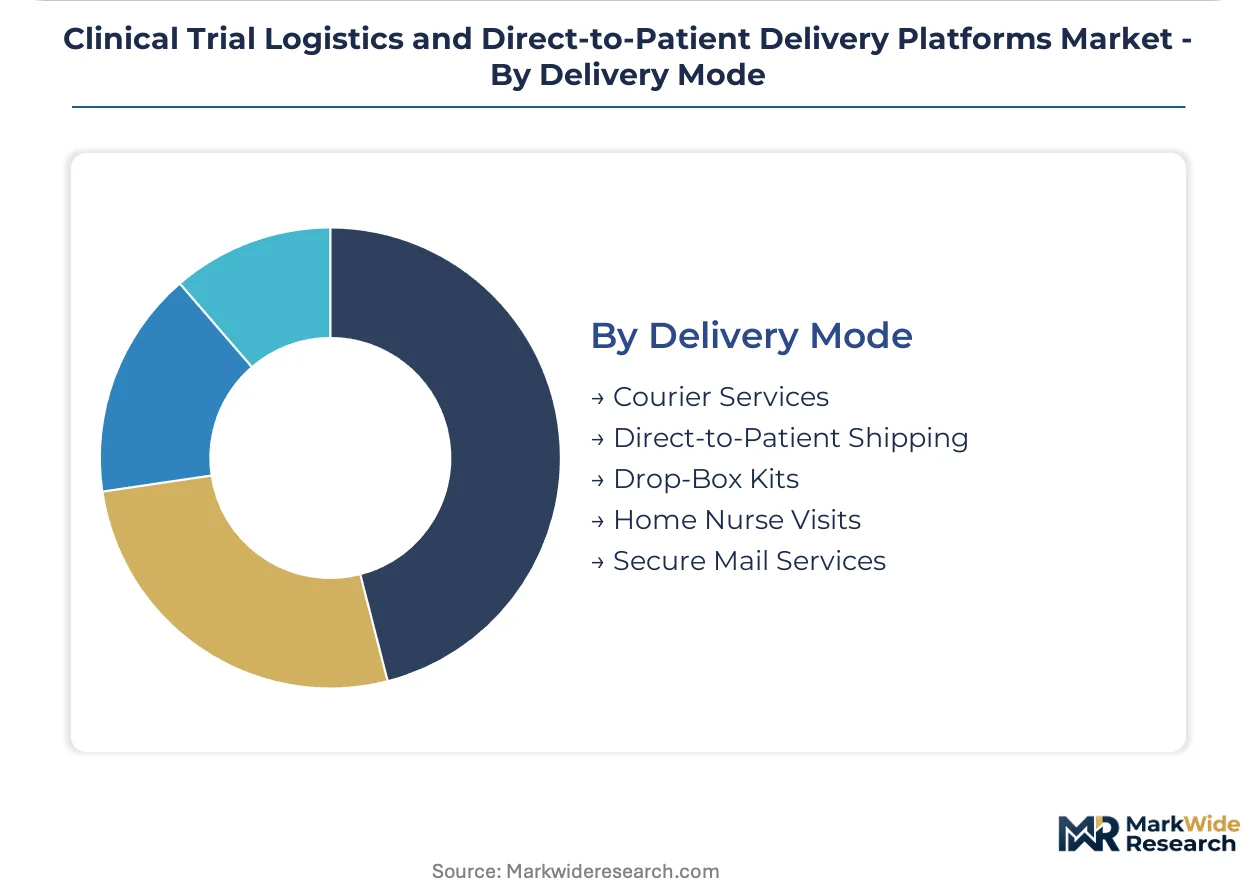
| Segmentation | Service Type: Temperature-Controlled Transport, Inventory Management, Order Fulfillment, Patient Enrollment Support, Sample Collection Coordination Technology: Cold Chain Monitoring, Real-Time Tracking, Blockchain, IoT Sensors, Cloud-Based Platforms End User: Pharmaceutical Sponsors, Contract Research Organizations, Clinical Sites, Home Healthcare Providers, Specialty Pharmacies Delivery Mode: Courier Services, Direct-to-Patient Shipping, Drop-Box Kits, Home Nurse Visits, Secure Mail Services |
| Companies Covered | Marken, World Courier, Thermo Fisher Scientific, DHL Group, Almac Group, PCI Pharma Services, Parexel, FedEx, Kuehne+Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market Trends and Innovations
Real-time visibility infrastructure and decentralized protocol design are collapsing the traditional site-centric trial model into patient-resident logistics networks.
Reusable smart packaging embedded with cellular-enabled temperature loggers is modularizing cold chain asset deployment across Phase II and III studies. Mid-size biotechnology sponsors now lease validated container fleets rather than purchasing capital equipment. This shift compresses per-shipment costs while fragmenting supplier relationships across regional logistics networks.
EMA's EU Clinical Trials Regulation harmonization mandates single-submission portals across member states. Sponsors restructure regulatory affairs teams to centralize documentation preparation in Belgium and the Netherlands. Germany's national competent authority processes now align with EMA timelines, reducing duplicate filings for multi-country protocols.
Site-less trial procurement models disintermediate traditional clinical site contracts. Contract research organizations now bundle patient enrollment, home nursing, and direct drug delivery under unified service agreements. This consolidation is most visible in rare-disease studies across the United States, where patient travel burden previously drove forty percent screen-failure rates.
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market Segmentation
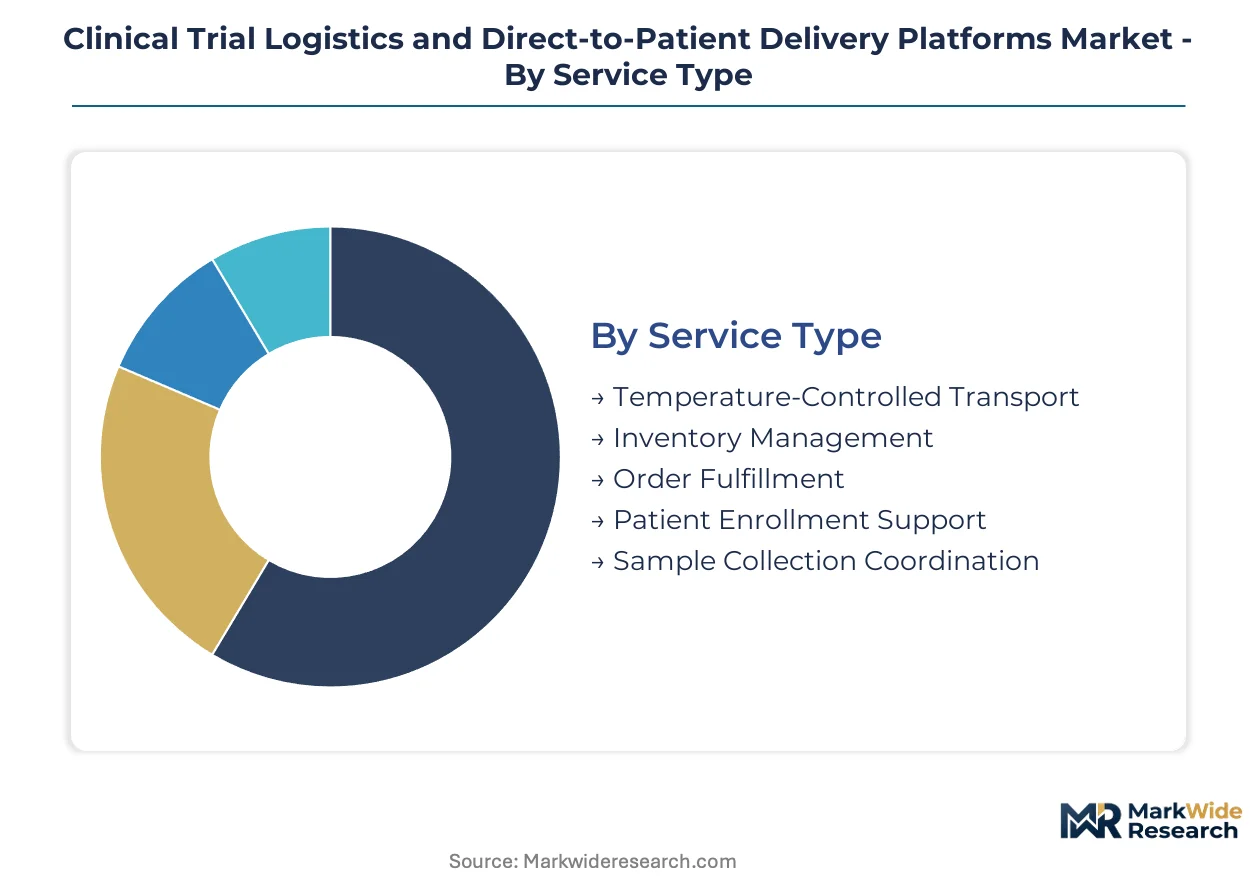
Clinical trial logistics segmentation reflects divergent compliance burdens across service tiers. Technology choices determine which regulators impose documentation requirements. End-user concentration shapes pricing power and contract duration.
Service Type:
FDA's 21 CFR Part 11 and EU GDP guidelines impose distinct validation requirements across service tiers, with cryogenic transport demanding the most intensive qualification protocols.
- Temperature-Controlled Transport:Validated cold chain infrastructure spans ambient through cryogenic ranges with continuous thermal mapping. Demand concentrates in the United States and Germany as oncology sponsors shift cell-and-gene therapies toward direct-to-patient models. The FDA's risk-based monitoring framework mandates redundant temperature logging for biologics in Phase III trials.
- Patient Enrollment Support:Geographic patient identification and home-based protocol onboarding reduce screen-failure rates in rare-disease studies. Sponsors in Japan leverage PMDA's streamlined import licensing for foreign-sourced materials to reach dispersed trial participants. EMA qualification opinions for digital health technologies accelerate remote consent and eligibility verification.
- Inventory Management:GMP-compliant depot operations with serialized tracking across investigational medicinal product lots.
- Order Fulfillment:Kit assembly and distribution with just-in-time delivery windows to clinical sites and residential endpoints.
- Sample Collection Coordination:Biological specimen logistics with chain-of-custody documentation for central laboratory analysis.
Leading the category by volume: Temperature-Controlled Transport. Growing fastest: Patient Enrollment Support.
Technology:
Technology adoption stratifies by deployment cost and regulatory acceptance, with mature monitoring systems commanding premium pricing against emerging ledger architectures.
- Cold Chain Monitoring:IoT-enabled temperature loggers with cellular connectivity provide real-time alerts across refrigerated and frozen ranges. Pharmaceutical sponsors in Switzerland and the Netherlands prioritize validated monitoring for EMA multi-site trials. EU MDR requirements for investigational medicinal products now mandate continuous thermal documentation.
- Blockchain:Distributed ledger technology creates immutable audit trails for multi-site chain-of-custody verification. Pilot programs in the United States test decentralized verification against FDA draft guidance on electronic records. EMA harmonization timelines create regulatory uncertainty for cross-border deployment.
- Real-Time Tracking:GPS-enabled visibility platforms with geofencing alerts for shipment deviation.
- IoT Sensors:Modular sensor arrays for shock, humidity, and light exposure monitoring beyond temperature.
- Cloud-Based Platforms:Centralized data repositories with API connectivity to sponsor ERP systems.
Highest margin capture: Cold Chain Monitoring. Steepest expansion trajectory: Blockchain.
End User:
Contract structures vary sharply across end-user categories, with pharmaceutical sponsors demanding integrated solutions while clinical sites prefer modular service procurement.
- Pharmaceutical Sponsors:Integrated logistics procurement spanning clinical supply chain automation and direct-to-patient delivery. Top-20 biotechnology companies in the United States consolidate vendor relationships under master service agreements with volume commitments. FDA's Drug Supply Chain Security Act serialization requirements drive sponsor investment in track-and-trace infrastructure.
- Contract Research Organizations:Bundled service offerings combining patient enrollment, home nursing, and drug delivery under unified contracts. CROs in Germany and Belgium centralize regulatory documentation for EMA single-submission portals. Site-less trial models disintermediate traditional clinical site relationships.
- Clinical Sites:Local inventory holding with on-demand replenishment from regional depots.
- Home Healthcare Providers:Nurse-administered dosing with patient-resident storage and waste management protocols.
- Specialty Pharmacies:Dispensing coordination with reimbursement navigation and adherence monitoring.
Dominant contract value: Pharmaceutical Sponsors. Fastest-growing procurement segment: Contract Research Organizations.
Delivery Mode:
Delivery mode selection reflects patient mobility constraints and therapy complexity, with home nurse visits reserved for parenteral administration requiring clinical oversight.
- Courier Services:Same-day and next-day validated transport with specialized handling for temperature-sensitive biologics. Networks in the United States and Japan maintain redundant cold chain capacity for oncology protocol contingencies. PMDA import licensing pathways now accommodate patient-resident endpoints for foreign-sourced materials.
- Direct-to-Patient Shipping:Residential delivery with patient-managed storage and self-administration protocols. Rare-disease trials across Germany and France adopt this model to reduce travel burden and screen-failure rates. EU Clinical Trials Regulation harmonization gaps create documentation duplication in France and Italy.
- Drop-Box Kits:Pre-positioned supply caches for patient pickup at convenient locations.
- Home Nurse Visits:Clinical administration with adverse event monitoring and real-time data capture.
- Secure Mail Services:Standardized packaging for ambient and refrigerated products with signature confirmation.
Highest shipment volume: Courier Services. Most rapid adoption: Direct-to-Patient Shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore and Ireland concentrate pharmaceutical logistics investment through tax-advantaged structures. These jurisdictions attract sponsor regional headquarters and depot infrastructure. Cold chain validation requirements vary sharply across national competent authorities.
United States
Oncology biologics and cell-and-gene therapies drive demand for cryogenic logistics networks. FDA's risk-based monitoring framework under 21 CFR Part 11 mandates redundant temperature logging for Phase III trials. The Greater Boston corridor anchors specialized cold chain infrastructure for immuno-oncology protocols.
Germany
GDP-certified logistics coordinators command premium compensation amid qualified personnel scarcity. EMA's EU Clinical Trials Regulation harmonization aligns national competent authority processes with centralized timelines. The Rhine-Main cluster around Frankfurt maintains validated depot capacity for temperature-sensitive biologics.
Japan
PMDA streamlined import licensing pathways now accommodate patient-resident endpoints for foreign-sourced trial materials. Geographic dispersion of rare-disease participants forces sponsors into home-based drug delivery models. The Kanto region around Tokyo concentrates clinical supply chain automation investment.
India
CDSCO compressed investigational medicinal product import licensing timelines from ninety to forty-five days. Western sponsors establish regional distribution hubs in Mumbai and Hyderabad to serve South Asian trial populations. These facilities leverage cost-advantaged GDP-certified personnel pools.
Switzerland
Swissmedic enforces strict serialization requirements for investigational products transiting Alpine logistics corridors. Pharmaceutical sponsors prioritize the Basel-Zurich corridor for its mature regulatory pathways and established cold chain infrastructure. Specialized providers construct validated cryogenic logistics chains for high-complexity shipments.
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with temperature-controlled transport consolidating around established cold chain networks while patient enrollment support fragments across regional providers. The vendor base stratifies into three tiers: integrated life-science conglomerates with captive logistics arms, pure-play clinical trial specialists with validated cryogenic capabilities, and diversified freight forwarders adapting GDP protocols for pharmaceutical verticals. M&A activity concentrates on acquiring specialized cell-and-gene therapy networks, while capacity expansion focuses on certified depot construction for GMP-compliant biologic storage.
Among integrated life-science conglomerates, Thermo Fisher Scientific occupies a position exemplifying clinical supply chain automation investment across R&D-intensive portfolios. Within the pure-play specialist tier, Marken and World Courier represent archetypes of high-complexity shipment handling, with the former anchoring cell-and-gene therapy network specialization and the latter dominating temperature-controlled transport for Phase III biologics. These named entities sit within a broader competitive set where service differentiation converges on validated cold chain infrastructure and real-time visibility platforms.
| Leading Market Players |
|---|
| Marken |
| World Courier |
| Thermo Fisher Scientific |
| DHL Group |
| Almac Group |
| PCI Pharma Services |
| Parexel |
| FedEx |
| Kuehne+Nagel |
| Others |
Pricing and Supply Chain Analysis
Reusable smart packaging embedded with cellular-enabled temperature loggers is modularizing cold chain asset deployment across Phase II and III studies, compressing per-shipment costs while fragmenting supplier relationships across regional logistics networks. This technology shift simultaneously reduces capital equipment burdens for mid-size biotechnology sponsors and concentrates pricing power among specialized providers with validated container fleets in the United States, Germany, and Japan.
Pricing Analysis
Premium pricing for cryogenic dewar availability within eighteen-month lead times dominates contract negotiations, while spot inventory of ambient-validated containers trades at discounts. Three-tier pricing structure across premium cryogenic, standard refrigerated, and economy ambient levels differentiates service tiers. Cost compression in standard refrigerated transport is intensifying because GDP-certified logistics coordinators command premium compensation in Germany and Switzerland. Small biotechnology sponsors exhibit highest price sensitivity, while top-20 pharmaceutical sponsors prioritize compliance assurance over unit cost.
Supply Chain Analysis
GDP certification and GMP-compliant depot qualification gate entry into validated clinical trial logistics, concentrating supply among providers with regulatory approval in the United States, Germany, and Switzerland. Cryogenic dewar manufacturing draws from three European suppliers, while IoT-enabled temperature logger production rests on semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability for validated container equipment creates structural risk. Distribution runs through sponsor-regional depot-clinical site networks with direct-to-patient shipping as the fastest-expanding downstream channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified depot capacity scarcity props pricing across temperature-controlled transport, with construction timelines for GMP-compliant biologic storage extending thirty-six to forty-eight months. This capacity bottleneck sustains margin premiums for incumbents with existing infrastructure.
For Market Incumbents: Deepen vertical integration into cryogenic container manufacturing to reduce lead-time exposure from European single-source suppliers. Expand certified depot capacity in the Rhine-Main corridor and Greater Boston to capture oncology biologics demand. Invest in blockchain-enabled audit trail platforms ahead of FDA final guidance on decentralized trials. For New Entrants and Emerging Players: Launch via direct-to-patient shipping specialization targeting rare-disease trials in Japan and India where PMDA and CDSCO regulatory pathways now accommodate patient-resident endpoints. Penetrate the patient enrollment support segment fastest-expanding category by bundling home nursing with drug delivery under unified service agreements. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play clinical trial specialists possessing validated cryogenic capabilities given EMA harmonization timelines creating regulatory tailwind for centralized documentation providers. Acquisition target archetype: regional logistics networks with GDP-certified personnel pools and established cold chain infrastructure. Watch FDA final guidance on decentralized trials as inflection indicator for direct-to-patient delivery platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Network Expansion | Validates cell-and-gene therapy shipment capacity for immuno-oncology protocols in Greater Boston. |
| Blockchain Audit Trail Deployment | Creates immutable chain-of-custody documentation aligned with FDA 21 CFR Part 11 requirements. |
| Regional Depot Construction | Secures GMP-compliant biologic storage capacity in the Rhine-Main corridor amid thirty-six-month build timelines. |
| Direct-to-Patient Platform Launch | Captures rare-disease trial demand in Japan through PMDA-accommodated patient-resident endpoints. |
| GDP Certification Investment | Qualifies personnel pools in India for CDSCO-compressed import licensing timelines. |
Research Methodology
Independent corroboration across regulatory affairs leads at contract research organizations, clinical supply chain directors at top-20 biotechnology sponsors, GDP-certified logistics coordinators in Germany and Switzerland, and home healthcare nursing managers underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 11 guidance documents, EMA EU Clinical Trials Regulation implementation timelines, PMDA import licensing pathway updates, ClinicalTrials.gov protocol registries, and customs trade data for cryogenic equipment imports. Bottom-up service provider capacity assessments and top-down sponsor procurement spend estimates were triangulated.
Comparable-period anchoring to historical clinical trial logistics expenditure patterns informed the projection horizon. Segmentation modeling spanned service type, technology deployment, end-user procurement structure, and delivery mode complexity. CAGRs were derived from regression analysis against oncology trial volume expansion and cell-and-gene therapy protocol proliferation. Forecast inputs incorporated qualified personnel scarcity indices and cryogenic equipment lead-time trajectories.
Regulatory harmonization delays, cryogenic container manufacturing bottlenecks, and sponsor ERP integration failures are the dominant revision risks. Forecasts reflect assumptions around EMA single-submission portal adoption rates and FDA decentralized trials guidance finalization. A model refresh is warranted upon material change in qualified GDP-certified personnel availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
India CRO Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
US Clinical Trials Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
North America Clinical Trials Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
HIV Clinical Trials Market