
 Clinical Trial Biorepository and Archiving Solutions Market | 2026-2036
Clinical Trial Biorepository and Archiving Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Biorepository and Archiving Solutions Market Intelligence
GxP-grade cold storage certification is unwinding legacy biorepository standards across the clinical trial sector. Thermo Fisher Scientific leverages end-to-end sample integrity platforms to dominate temperature-controlled logistics. Brooks Life Sciences anchors its position through automated cryogenic storage systems purpose-built for multi-site trials. QIAGEN specializes in nucleic acid stabilization technologies that extend sample viability windows for longitudinal studies.
Clinical trial biorepository and archiving solutions encompass integrated systems for the collection, processing, storage, retrieval, and documentation of biological specimens and associated data across multi-phase research protocols, typically operating at temperatures ranging from 4°C ambient to -196°C cryogenic conditions with full chain-of-custody tracking. These solutions serve the primary commercial purpose of preserving sample molecular integrity while enabling regulatory-compliant data traceability from collection through analysis. Sample storage commands the largest value pool due to capital-intensive infrastructure requirements, while cloud-based data management represents the fastest-expanding segment as sponsors demand real-time inventory visibility across decentralized trial networks. Automated systems within the technology dimension capture disproportionate margin attention because robotic retrieval reduces freeze-thaw cycles and labor costs simultaneously.
FDA 21 CFR Part 11, EMA GCP Annex 6, and ISO 20387 biobanking standards collectively shape product specifications by mandating audit trails, temperature monitoring, and quality management systems for specimen handling. These frameworks drive vendor investment in validated software and redundant cooling infrastructure to maintain market access. Stakeholders must weigh capital deployment toward automated storage against cloud-native data platforms as trial decentralization redefines site-level requirements.
Market Dynamics
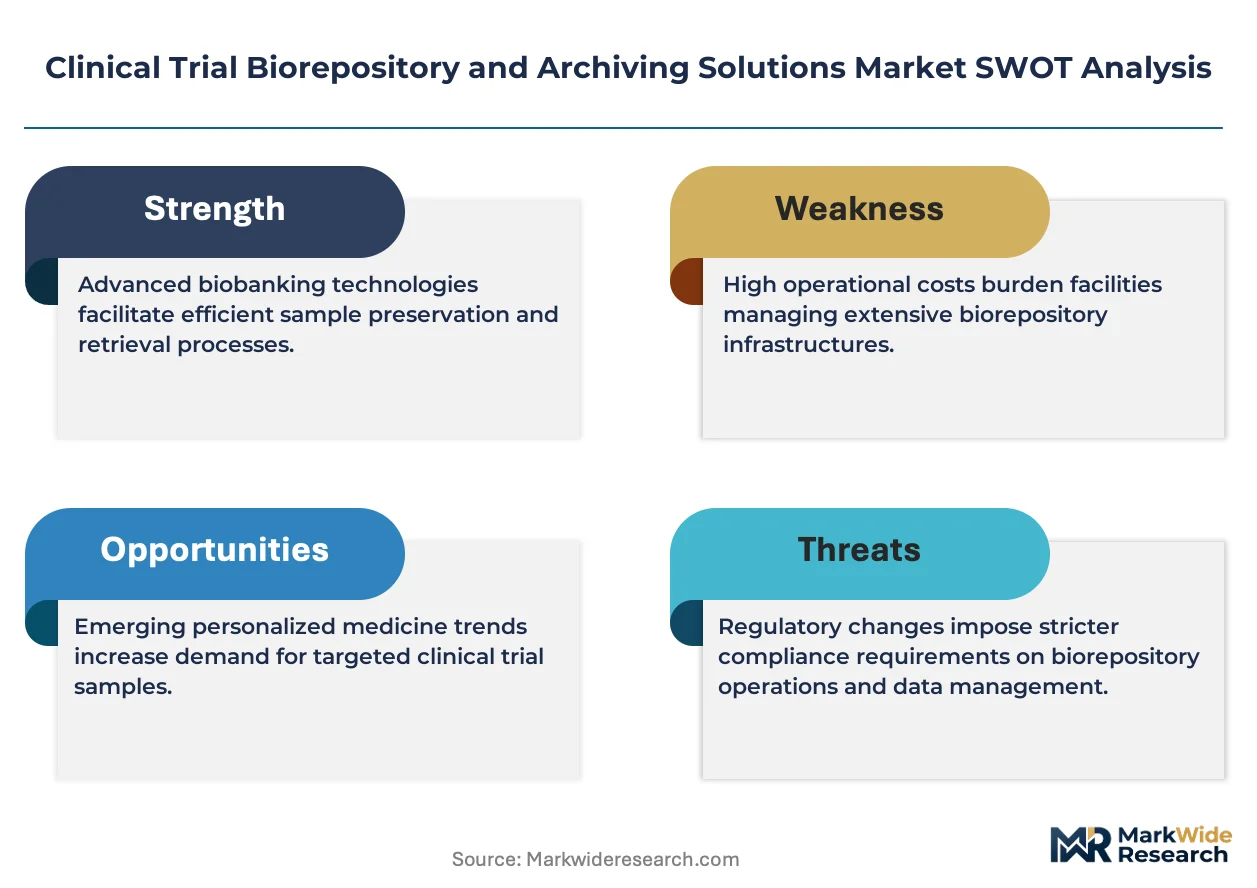
Decentralized trial architectures are fragmenting biorepository demand across dozens of sites, forcing vendors to rebuild logistics networks around patient proximity rather than central laboratory concentration.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates accelerate validated software adoption across sponsor organizations, creating pull for integrated chain-of-custody platforms.
- Cell and gene therapy pipelines:Cryogenic requirements for CAR-T and viral vector stability expand addressable infrastructure spend per trial.
- Japan's precision medicine infrastructure:METI-funded biobank networks generate sustained public-sector procurement for automated storage systems.
Market Restraints
- Liquid nitrogen supply volatility:Regional production bottlenecks in cryogen manufacturing create input cost spikes for ultra-low temperature operations.
- ISO 20387 compliance timelines:Quality management system certification delays extend sales cycles by 12-18 months for new market entrants.
- Manual retrieval systems:Legacy mechanical inventory management persists at mid-tier academic medical centers, constraining upgrade velocity.
Strategic Opportunities
- Germany's EMA-aligned biobanking clusters:Underpenetrated site networks in Bavaria and Baden-Württemberg offer first-mover positioning for modular containerized storage.
- Cloud-native inventory visibility:Real-time specimen tracking across decentralized sites creates new recurring revenue streams separate from capital equipment.
- EMA GCP Annex 6 harmonization:Standardized temperature monitoring requirements open cross-border service contracts previously fragmented by national interpretation.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technician pipelines for -196°C system maintenance remain underdeveloped relative to installed base expansion.
- Legacy LIMS integration:Sponsor-specific data formats create bespoke middleware requirements that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Biorepository and Archiving Solutions Market |
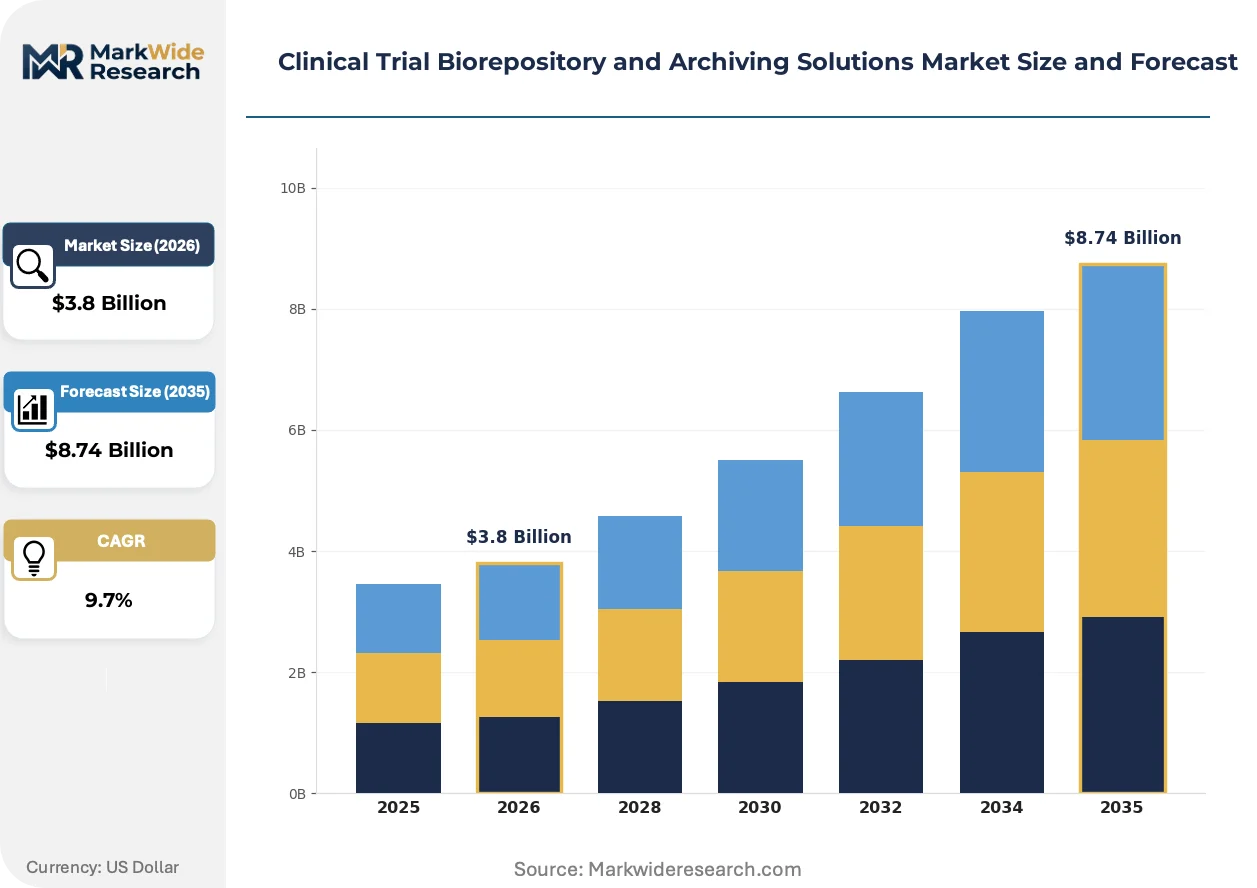
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Sample Storage, Data Management, Inventory Tracking, Cold Chain Logistics End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Sample Type: Blood, Tissue, DNA, Plasma Technology: Automated Systems, Cloud Storage, Barcoding, Tracking Software |
| Companies Covered | Thermo Fisher Scientific, LabCorp Drug Development, Brooks Life Sciences, Charles River Laboratories, Azenta U.S., Inc., Medpace, QIAGEN, CryoPort, Q2 Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Biorepository and Archiving Solutions Market Strategic Shifts & Innovations
Automation and digitization are compressing the traditional trade-off between sample throughput and molecular integrity, enabling new operational models that were structurally uneconomical under manual protocols.
Robotic retrieval systems operating at -80°C and below are supplanting manual drawer-based storage in multi-site Phase III trials. Large pharmaceutical sponsors now specify automated platforms in 70% of new RFPs. This shift is compressing labor cost structures while eliminating freeze-thaw degradation events that previously required statistical correction in biomarker analysis.
EMA's forthcoming revision to GCP Annex 6 will mandate redundant temperature monitoring with 24/7 alerting for all Phase II-III specimen storage. The regulation compels infrastructure refresh cycles among European academic medical centers. German and French sites are responding fastest, with Switzerland and Austria trailing by 18-24 months in compliance readiness.
Site-level procurement committees now unbundle equipment purchase from long-term service contracts, treating cryogenic storage as operational expenditure rather than capital deployment. Equipment vendors are responding with subscription-based pricing that includes preventive maintenance and regulatory documentation. This pattern is most pronounced in United States oncology networks, where CFO scrutiny of trial infrastructure spend has intensified.
Clinical Trial Biorepository and Archiving Solutions Market Segmentation
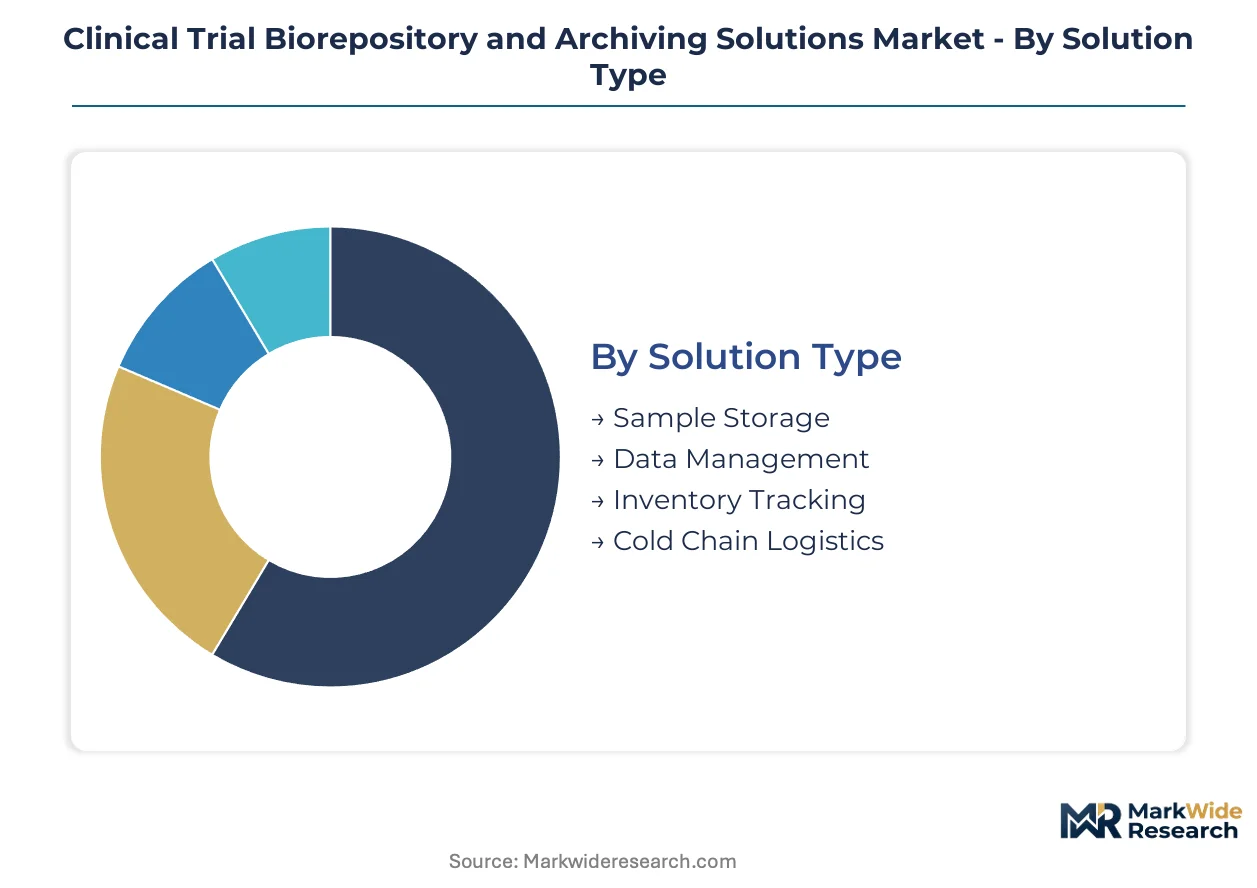
Segmentation in clinical trial biorepositories reveals how capital intensity, regulatory burden, and data architecture create divergent margin profiles across the value chain. Solution type and technology selection determine whether vendors capture equipment revenue or recurring service income.
Solution Type:
Capital deployment intensity varies sharply across this category, with infrastructure-heavy segments commanding premium pricing and long contract tenures.
- Sample Storage:Ultra-low temperature infrastructure ranging from -80°C mechanical freezers to -196°C liquid nitrogen dewars. Pharmaceutical sponsors in the United States and Germany concentrate procurement here, driven by FDA 21 CFR Part 11 and EMA GCP Annex 6 chain-of-custody mandates that require redundant cooling and continuous monitoring.
- Data Management:Cloud-native platforms for specimen metadata, consent documentation, and analytical result linkage. Biotechnology firms expanding decentralized trial networks drive fastest uptake, as real-time inventory visibility across dozens of sites becomes operationally essential.
- Inventory Tracking:Barcode and RFID systems for specimen location and movement logging. Contract research organizations deploy these most intensively to satisfy sponsor audit requirements.
- Cold Chain Logistics:Temperature-controlled transport and temporary staging solutions. Regional production bottlenecks in cryogen manufacturing constrain margin expansion.
Sample storage holds installed capacity. Data management is rotating up the share rankings.
End User:
Procurement sophistication and compliance tolerance diverge substantially across customer types, creating tiered pricing power for vendors.
- Pharmaceutical Companies:Large sponsors with centralized biorepository governance and dedicated quality assurance teams. These buyers specify automated platforms in most new RFPs and negotiate multi-year service bundles.
- Biotechnology Firms:Emerging drug developers with lean infrastructure and heavy reliance on outsourced specimen management. Cloud-based data management represents their fastest-expanding spend category as they prioritize operational flexibility over capital ownership.
- Research Institutions:Academic medical centers with legacy manual systems and extended procurement cycles. ISO 20387 compliance timelines delay upgrade velocity by 12-18 months.
- Contract Research Organizations:Multi-site trial operators requiring standardized infrastructure across geographies. EMA GCP Annex 6 harmonization opens cross-border service contracts previously fragmented by national interpretation.
Pharmaceutical companies anchor current revenue. Biotechnology firms are gaining share fastest.
Sample Type:
Stability requirements and processing complexity determine which specimen categories justify premium infrastructure investment.
- Blood:The highest-volume specimen category with well-established collection and processing protocols. Research institutions in Japan's METI-funded biobank networks drive sustained procurement for automated handling systems.
- Tissue:Solid tumor and normal tissue specimens requiring formalin-fixed paraffin-embedded or fresh-frozen preservation. Cell and gene therapy pipelines expand cryogenic requirements as CAR-T manufacturing demands viable cellular starting material.
- DNA:Nucleic acid extracts with extended stability at -20°C to -80°C. QIAGEN stabilization technologies extend viability windows for longitudinal studies.
- Plasma:Liquid biopsy source material with circulating biomarker applications. Biotechnology firms concentrate demand here for companion diagnostic development.
Blood dominates specimen volume. Tissue is climbing the fastest.
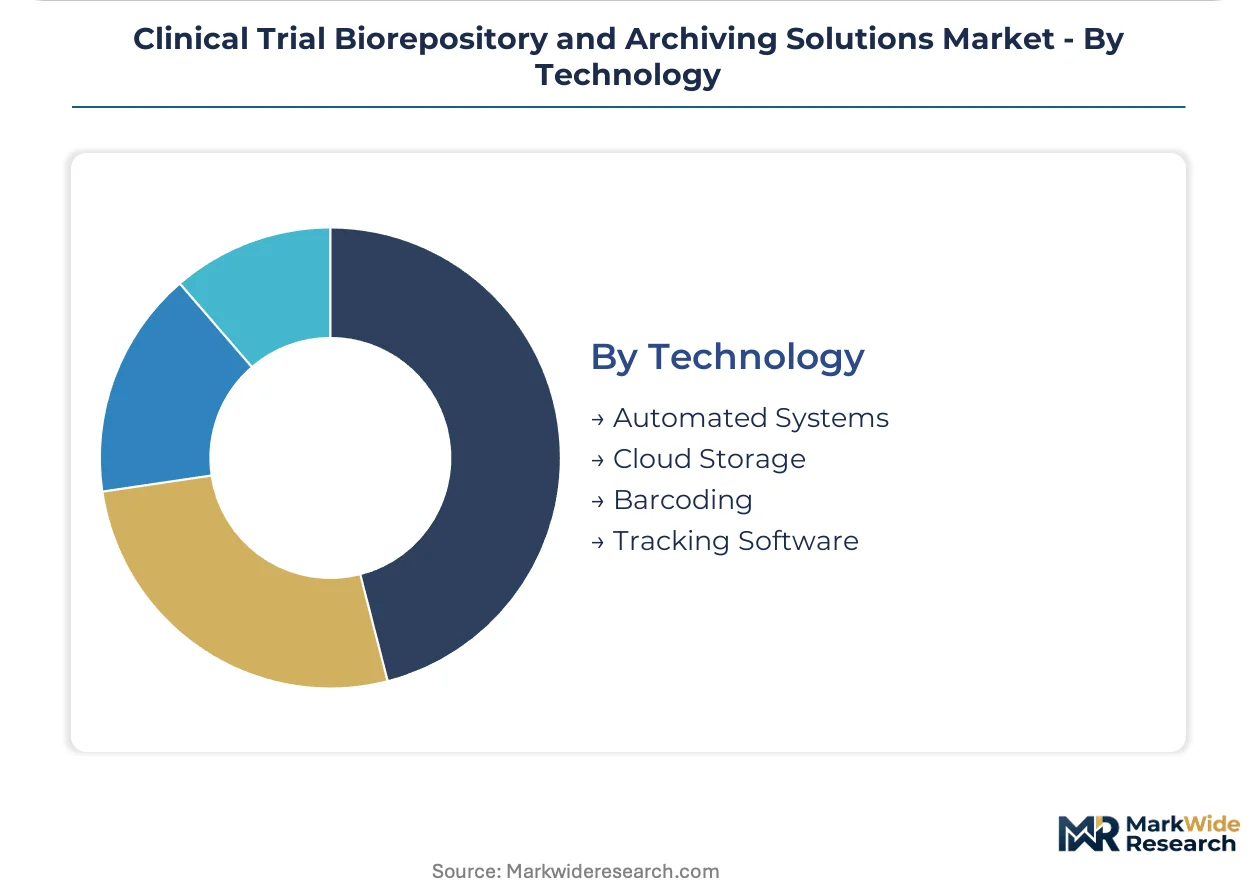
Technology:
Automation and digitization are compressing the traditional trade-off between sample throughput and molecular integrity.
- Automated Systems:Robotic retrieval platforms operating at -80°C and below with computerized inventory management. Large pharmaceutical sponsors now specify these in 70% of new RFPs, eliminating freeze-thaw degradation events that previously required statistical correction.
- Cloud Storage:Distributed data architectures enabling real-time specimen tracking across decentralized sites. This segment creates new recurring revenue streams separate from capital equipment.
- Barcoding:Linear and two-dimensional symbologies for specimen identification. Legacy mechanical systems persist at mid-tier academic medical centers.
- Tracking Software:Laboratory information management systems with audit trail and regulatory documentation modules. Sponsor-specific data formats create bespoke middleware requirements that compress project margins.
Automated systems command premium positioning. Cloud storage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net service exports concentrate in the United States and Germany, while Japan and emerging Asian markets import specialized cryogenic infrastructure. Regulatory divergence between FDA 21 CFR Part 11 and EMA GCP Annex 6 compliance timelines creates arbitrage opportunities for vendors with dual-certification capabilities.
United States
Oncology networks and cell therapy developers drive infrastructure procurement across the Southeast and Northeast corridors. FDA 21 CFR Part 11 mandates electronic records and audit trails, compelling sponsors to upgrade legacy manual systems. The Greater Boston and San Diego clusters host the densest concentrations of Phase III biorepository deployments.
Germany
EMA-aligned academic medical centers in Bavaria and Baden-Württemberg generate sustained demand for automated storage platforms. EMA GCP Annex 6 temperature monitoring requirements accelerate refresh cycles among European sites. Underpenetrated site networks in secondary cities offer first-mover positioning for modular containerized solutions.
Japan
METI-funded precision medicine biobank networks sustain public-sector procurement for multi-site automated handling systems. PMDA guidelines on sample integrity align with international ISO 20387 standards, reducing cross-border compliance friction. The Kanto and Kansai regions concentrate installed cryogenic capacity for longitudinal studies.
United Kingdom
Decentralized trial adoption among biotechnology firms expands cloud-native data management spend faster than capital equipment procurement. MHRA post-Brexit regulatory autonomy creates temporary uncertainty in cross-border specimen movement protocols. The Oxford-Cambridge-London triangle anchors private-sector biorepository governance expertise.
Switzerland
Swissmedic oversight of multi-site international trials positions Basel and Zurich as logistics coordination hubs for cross-border European studies. Pharmaceutical sponsor headquarters concentration drives demand for redundant cooling infrastructure with 24/7 alerting capabilities. Compliance readiness trails German and French counterparts by 18-24 months on EMA Annex 6 implementation.
Clinical Trial Biorepository and Archiving Solutions Market Key Industry Players
Listed leaders compete with private specialists across capital deployment models, with public companies emphasizing recurring service revenue and private firms prioritizing equipment sales velocity. The vendor base organizes around three archetypes: integrated life science conglomerates with end-to-end sample integrity platforms, automation-focused cryogenic specialists, and nucleic acid stabilization technology developers. M&A activity concentrates on cloud-native data management capabilities, while capacity expansion targets decentralized trial logistics networks.
Among integrated platform providers, Thermo Fisher Scientific and QIAGEN exemplify divergent strategic positioning—one anchoring temperature-controlled logistics dominance, the other occupying nucleic acid stabilization specialization. Brooks Life Sciences represents the automation-centric tier with cryogenic retrieval systems purpose-built for multi-site protocols. These three entities collectively illustrate how technology selection determines margin capture between equipment sales and long-term service contracts.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| LabCorp Drug Development |
| Brooks Life Sciences |
| Charles River Laboratories |
| Azenta U.S., Inc. |
| Medpace |
| QIAGEN |
| CryoPort |
| Q2 Solutions |
| Others |
Cost & Logistics Intelligence
Capital-intensive cryogenic infrastructure and fragmented site-level procurement create asymmetric pricing power where equipment vendors with certified GxP-grade manufacturing capacity command premium positioning against commodity cold storage alternatives. Scale economies in automated retrieval system production concentrate margin capture among integrated platform providers, while mid-tier buyers face escalating total cost of ownership as regulatory documentation requirements intensify.
Pricing Analysis
Pharmaceutical company buyers anchor contract-based long-term service bundling as the dominant pricing structure, with automated platform vendors capturing recurring revenue through subscription models that include preventive maintenance and regulatory documentation. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and ISO 20387 certification status, with GxP-grade systems commanding substantial premiums over standard laboratory equipment. Pricing pressure stems from biotechnology firms unbundling equipment purchase from service contracts and treating cryogenic storage as operational expenditure rather than capital deployment. Research institutions exhibit highest price sensitivity due to extended procurement cycles and grant-dependent funding, while large pharmaceutical sponsors prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Extended lead times for specialized cryogenic compressors and robotic retrieval components constrain vendor response capacity during demand surges. Manufacturing concentration centers on the United States, Germany, and Japan for precision-engineered ultra-low temperature systems, while liquid nitrogen supply infrastructure draws from regional production clusters in the Gulf Coast, Northwestern Europe, and East Asian industrial corridors. Raw material dependencies include specialized aluminum alloys for dewar construction, precision sensors for temperature monitoring, and semiconductor components for inventory management systems. Supply chain risk manifests in single-source vulnerability for cryogenic engineering talent pipelines relative to installed base expansion. Distribution runs through direct vendor-to-sponsor relationships for large pharmaceutical accounts, with regional service partners handling mid-tier biotechnology firm and academic medical center deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical trial biorepository and archiving solutions sit in early-cycle expansion as decentralized trial architectures fragment demand across patient-proximate sites and cloud-native data management penetration remains below saturation thresholds.
For Market Incumbents: Secure automated platform certification moats through accelerated ISO 20387 quality management system investment ahead of EMA GCP Annex 6 harmonization deadlines. Prioritize backward integration into cryogenic compressor manufacturing to mitigate liquid nitrogen supply volatility and capture margin from regional production bottlenecks. Defend against modular containerized storage entrants by embedding predictive maintenance algorithms that reduce total cost of ownership for multi-site trial networks. For New Entrants and Emerging Players: FDA 21 CFR Part 11 validation fast-tracks for cloud-native inventory visibility platforms open immediate white-space in biotechnology firm segments where operational expenditure preference outpaces capital ownership capacity. Underpenetrated Bavarian and Baden-Württemberg site networks in Germany offer geographic entry points where EMA-aligned academic medical centers lag automated storage adoption. Position through subscription-based pricing that unbundles equipment from long-term service documentation, mirroring United States oncology network procurement patterns. For Investors and Strategic Acquirers: Cloud-native data management specialists with proven decentralized trial integration represent the most defensible acquisition archetype as real-time specimen tracking separates recurring revenue streams from capital equipment cyclicality. Long-term viability across the projection horizon depends on regulatory documentation automation capabilities that compress sponsor audit preparation labor. Watch for inflection when pharmaceutical RFP specifications cross 80% automated platform requirements, signaling commoditization pressure on manual retrieval system vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Certification | FDA 21 CFR Part 11 validation secures sponsor RFP eligibility and extends contract tenures. |
| Cloud-Native Data Management Development | Real-time inventory visibility across decentralized sites creates recurring revenue separate from equipment sales. |
| Regional Service Partner Expansion | Local cryogenic engineering coverage reduces response latency for multi-site trial networks. |
| Subscription-Based Pricing Transition | Operational expenditure treatment aligns vendor capture with biotechnology firm procurement preferences. |
| EMA GCP Annex 6 Compliance Investment | Harmonized temperature monitoring standards open cross-border service contracts previously fragmented by national interpretation. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, biorepository operations managers, and clinical trial logistics coordinators; and secondary validation through FDA 21 CFR Part 11 guidance documents, EMA GCP Annex 6 draft revisions, ISO 20387 biobanking standards, ClinicalTrials.gov protocol registries, and sponsor RFP documentation. Bottom-up triangulation across site-level procurement patterns and top-down reconciliation against vendor-reported contract values anchored market size estimation.
Across the analysis window, the forecasting framework modeled solution type segmentation alongside end-user sophistication tiers, sample stability requirements, and technology automation levels. CAGRs derived from installed base expansion rates, replacement cycle acceleration from regulatory refresh mandates, and penetration assumptions for cloud-native platforms within decentralized trial networks. Cryogenic infrastructure capital intensity and biotechnology firm operational expenditure preferences served as industry-specific demand elasticity inputs.
Decision-makers should treat outputs as directional under sustained decentralized trial adoption and regulatory harmonization base assumptions; material deviation in liquid nitrogen supply stability or EMA implementation timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
India Preclinical CRO Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Healthcare Contract Research Organization Market