
 Humanized Mice Model Market | 2026-2036
Humanized Mice Model Market Size, Share, and Industry Trends Forecast 2026-2036
Humanized Mice Model Market Foresight
Subscription-based colony management and software-defined breeding protocols is hardening as the dominant commercial layer in this market. The Jackson Laboratory leverages its vast repository of genetically defined strains to sustain long-term research partnerships. Charles River Laboratories anchors its position through integrated contract research services that bundle model supply with toxicology testing. Taconic Biosciences differentiates through specialized immunodeficient and humanized lines tailored to immuno-oncology workflows.
Humanized mice models are laboratory rodents engrafted with human cells, tissues, or genes to simulate human physiological responses, typically requiring SCID or NOD-scid gamma genetic backgrounds to permit human hematopoietic cell engraftment without graft-versus-host rejection. These models serve as critical preclinical substrates for evaluating human drug metabolism, immune responses, and tumor progression before human trials. Immunodeficient mice command the largest volume share among product types due to their foundational role as engraftment hosts, while xenogenic applications in oncology research represent the fastest-expanding segment as CAR-T and bispecific antibody pipelines multiply. Genome editing technologies, particularly CRISPR-Cas9 systems, concentrate margin pools by enabling precise human gene knock-ins that command premium pricing over conventional transgenic approaches.
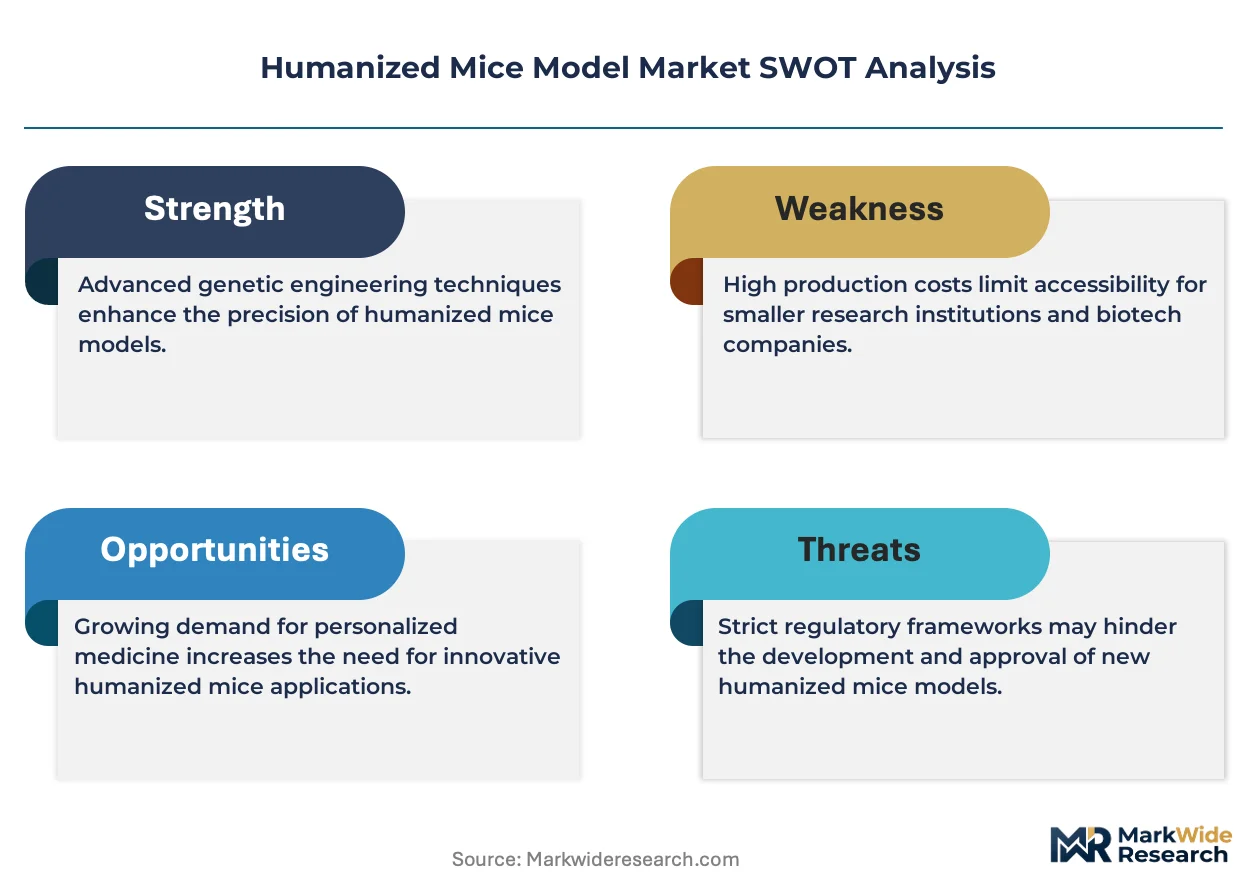
The FDA and EMA enforce stringent Good Laboratory Practice standards that dictate documentation, animal welfare, and data reproducibility requirements for studies submitted in IND and NDA packages. Japan's PMDA maintains similarly rigorous protocols for preclinical pharmacology and safety assessment, creating a harmonized but demanding regulatory triad for model suppliers. The EU Green Deal and REACH frameworks are incrementally restricting certain chemical reagents used in model maintenance, pushing facilities toward alternative husbandry materials. Stakeholders must monitor evolving cross-border alignment between these regulators on humanized model qualification standards, as divergence would fragment approval pathways and inflate compliance costs for multinational pharmaceutical sponsors.
Market Dynamics
CRISPR-Cas9 genome editing is compressing breeding cycles and enabling precise human gene knock-ins, forcing suppliers to upgrade technical capabilities or surrender margin to specialized gene-editing houses. This technological inflection is reshaping competitive positioning across the entire value chain.
Growth Catalysts
- Immuno-oncology pipeline expansion:CAR-T and bispecific antibody development programs at major pharmaceutical sponsors are multiplying demand for patient-derived xenograft hosts.
- REACH framework evolution:The EU Green Deal is incrementally restricting chemical reagents used in model maintenance, accelerating facility upgrades toward alternative husbandry materials.
- Japan PMDA harmonization:Preclinical pharmacology standards alignment with FDA and EMA protocols is streamlining multinational IND submissions for Japanese sponsors.
Market Restraints
- SCID/NOD-scid gamma breeding concentration:Foundational immunodeficient strain supply concentrates among three major repository networks, creating single-source vulnerability for engraftment hosts.
- Specialized technical labor scarcity:Hematopoietic stem cell engraftment surgery and immune monitoring require veterinary pathologists with human immunology cross-training.
- Biocontainment facility capex:Germ-free and specific-pathogen-free housing infrastructure demands seven-figure capital commitments with decade-long depreciation horizons.
Strategic Opportunities
- Organoid-humanized hybrid models:Convergence of 3D organoid culture with immunodeficient mouse engraftment opens patient-specific tumor microenvironment replication.
- Subscription colony management:Software-defined breeding protocols and just-in-time delivery contracts lock in multi-year research partnerships with academic medical centers.
- India CDSCO pathway development:Emerging domestic biotechnology clusters in Hyderabad and Bangalore are building preclinical capacity requiring qualified humanized model supply.
Industry Challenges
- Human tissue sourcing compliance:Informed consent documentation and donor traceability for hematopoietic stem cell procurement spans multiple institutional review board jurisdictions.
- Graft-versus-host disease variability:Batch-to-batch engraftment consistency requires rigorous quality control metrics that extend breeding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humanized Mice Model Market |
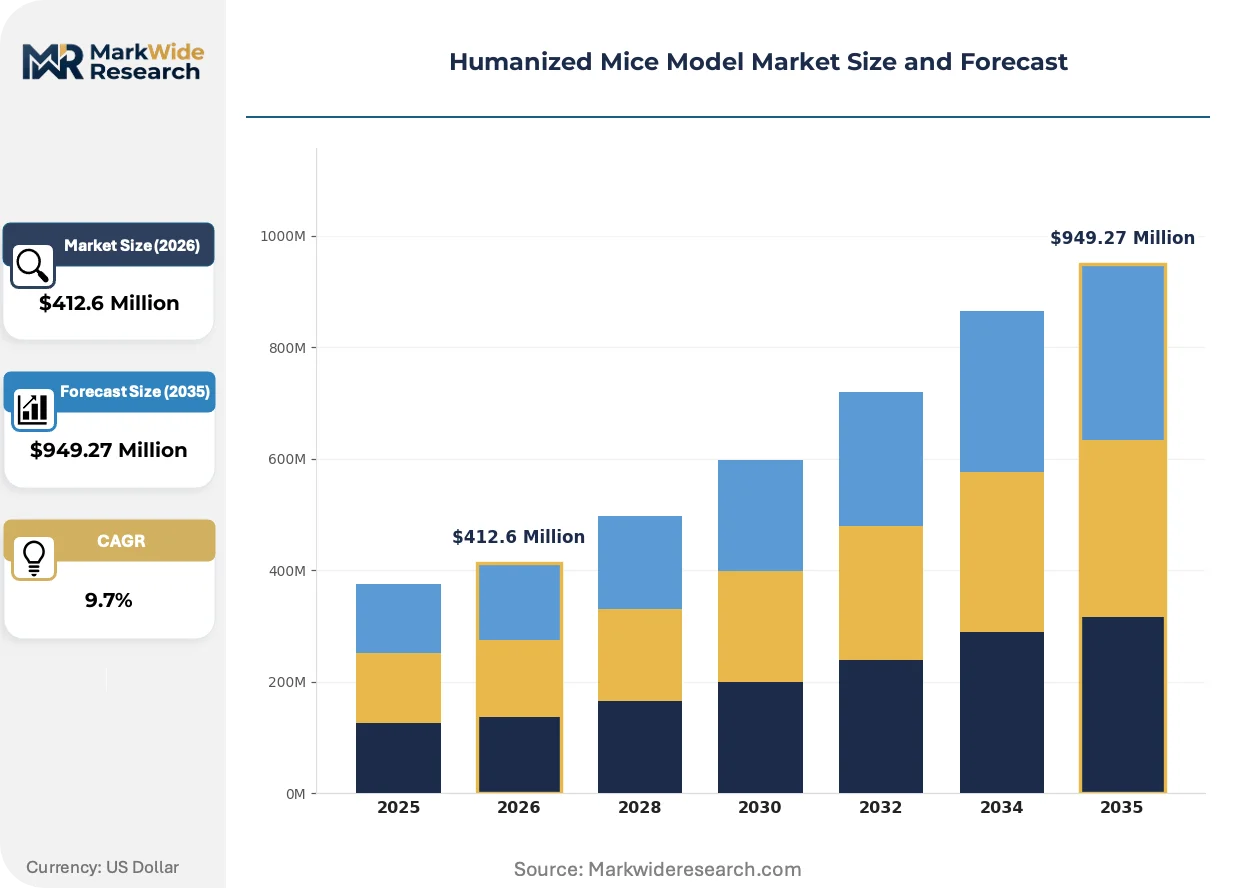
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transgenic Mice, Knockout Mice, Xenogenic Mice, Immunodeficient Mice Application: Oncology Research, Immunology Studies, Infectious Disease Research, Drug Discovery End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms Technology: Genome Editing, Molecular Cloning, Stem Cell Technology, Tissue Engineering |
| Companies Covered | The Jackson Laboratory, Charles River Laboratories, Inotiv, Taconic Biosciences, genOway, Crown Bioscience, Ingenious Targeting Laboratory, Horizon Discovery Group, Champions Oncology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humanized Mice Model Market Shifts & Advancements
Gene-editing precision and regulatory data quality mandates are compressing traditional transgenic timelines while elevating documentation standards. These forces are simultaneously enabling new model architectures and raising operational barriers to entry.
CRISPR-Cas9 knock-in technology is overtaking conventional pronuclear microinjection for human gene insertion. Pharmaceutical toxicology groups are adopting CRISPR-edited lines for drug metabolism studies within eighteen-month qualification windows. This acceleration is compressing the premium pricing window for first-generation transgenic models.
EMA Good Laboratory Practice documentation requirements are tightening traceability standards for engraftment cell sourcing. European contract research organizations now face expanded audit scopes covering human tissue donor consent chains. Immunodeficient model suppliers serving EMA jurisdictions are investing in blockchain-based lineage tracking systems.
Academic medical centers are consolidating procurement through master service agreements with integrated model-and-testing bundles. Charles River Laboratories and Taconic Biosciences are capturing volume through multi-year colony management contracts that displace spot purchasing. This consolidation is most visible in Boston and San Francisco biotech corridors where institutional purchasing offices centralize vendor selection.
Humanized Mice Model Market Segmentation
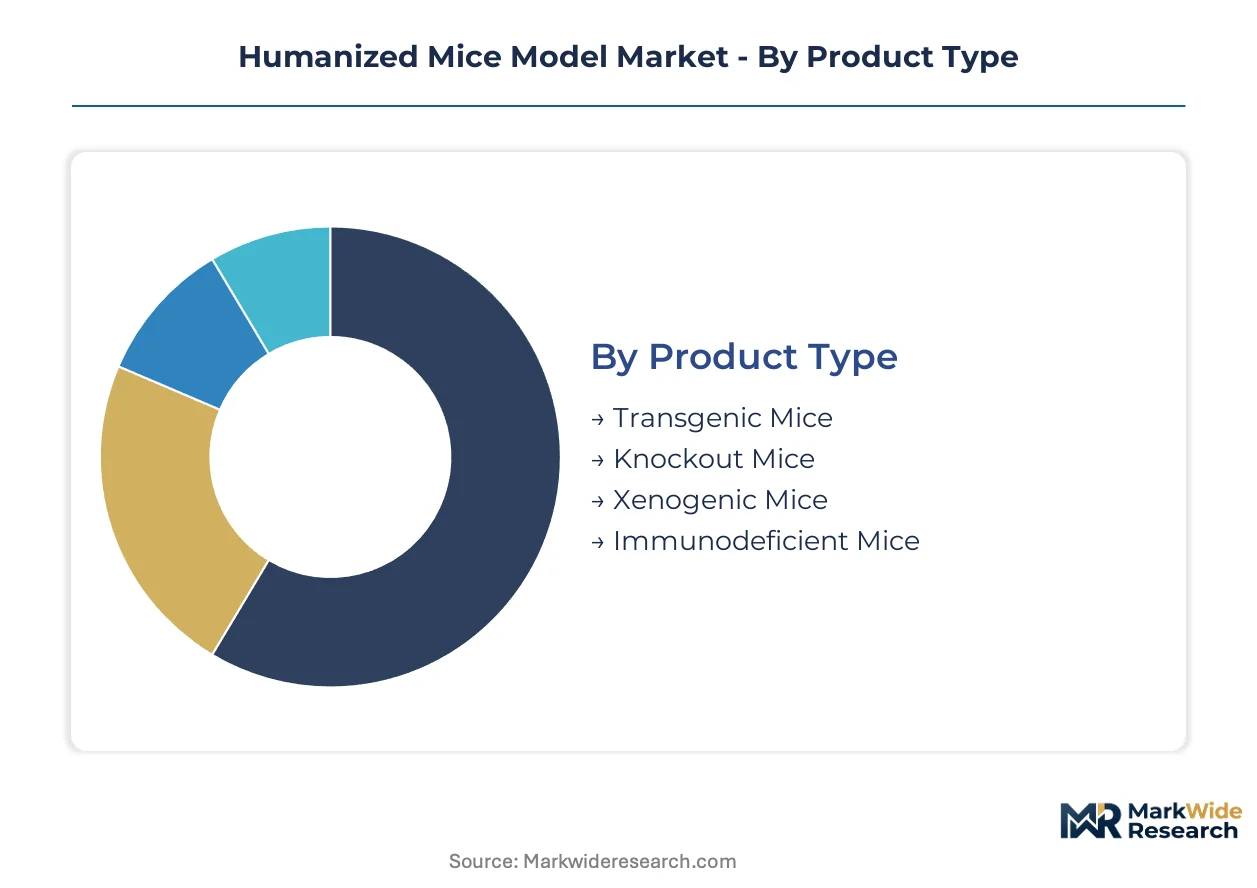
Humanized mice model segmentation reflects divergent technical complexity and regulatory qualification requirements across product architectures. Each category demands distinct procurement patterns, with pharmaceutical sponsors prioritizing validated strains while academic laboratories optimize for experimental flexibility.
Product Type:
The customization-vs-standardization spectrum spans foundational immunodeficient hosts at one extreme and precision-edited transgenic lines at the other, with cost and qualification timelines expanding proportionally.
- Immunodeficient Mice:SCID and NOD-scid gamma strains serve as engraftment hosts for human hematopoietic cells, requiring specific-pathogen-free breeding conditions. Demand concentrates among contract research organizations in Massachusetts and North Rhine-Westphalia serving CAR-T development programs, constrained by limited repository network capacity.
- Xenogenic Mice:Patient-derived tumor xenograft hosts replicate individual cancer microenvironments for immuno-oncology screening. Sponsors in Basel and Tokyo are expanding procurement of these models for bispecific antibody validation, driving fastest segment expansion.
- Transgenic Mice:Random-integration human gene carriers support toxicology and metabolism studies with established regulatory qualification histories.
- Knockout Mice:Targeted gene deletion lines enable specific pathway interrogation for mechanistic pharmacology research.
Leading the category by volume: Immunodeficient Mice. Growing fastest: Xenogenic Mice.
Application:
Clinical translation timelines and therapeutic modality pipelines determine application-level demand concentration, with oncology commanding premium pricing due to commercialization urgency.
- Oncology Research:Tumor engraftment models support checkpoint inhibitor and cell therapy development, requiring immune-humanized architectures. Demand clusters at NCI-designated cancer centers and immuno-oncology biotechs in San Francisco and Cambridge, pressured by FDA expedited pathway timelines.
- Drug Discovery:Pharmacokinetic and toxicity screening employs humanized metabolic models to predict first-in-human dosing. Major pharmaceutical sponsors in New Jersey and Basel are consolidating procurement through multi-year master service agreements, displacing spot purchasing.
- Immunology Studies:Autoimmune and inflammatory disease modeling utilizes human immune system reconstitution for therapeutic antibody validation.
- Infectious Disease Research:Pathogen-specific humanized hosts enable HIV, hepatitis, and emerging virus therapeutic evaluation under enhanced biocontainment.
Oncology Research captures the largest revenue share. Drug Discovery exhibits steepest expansion trajectory as toxicology groups accelerate humanized model adoption.
End User:
Procurement scale and qualification rigor separate institutional buyer tiers, with pharmaceutical sponsors demanding GLP-compliant documentation that academic laboratories rarely require.
- Pharmaceutical Companies:Integrated toxicology and pharmacology groups mandate validated model lines with complete lineage documentation for IND submissions. Sponsors in Basel, Tokyo, and New Jersey are driving demand for CRISPR-edited humanized strains, constrained by EMA and PMDA audit scope expansion.
- Academic Institutions:Principal investigators prioritize experimental flexibility and cost efficiency over regulatory qualification. Medical centers in Boston and Heidelberg are consolidating vendor selection through institutional purchasing offices, favoring subscription colony management contracts.
- Biotechnology Firms:Venture-funded immuno-oncology developers require rapid model access for investor milestone achievement.
- Research Organizations:Government and nonprofit laboratories support reference standard development and comparative validation studies.
Pharmaceutical Companies dominate absolute spending. Biotechnology Firms are expanding procurement fastest as cell therapy pipelines multiply.
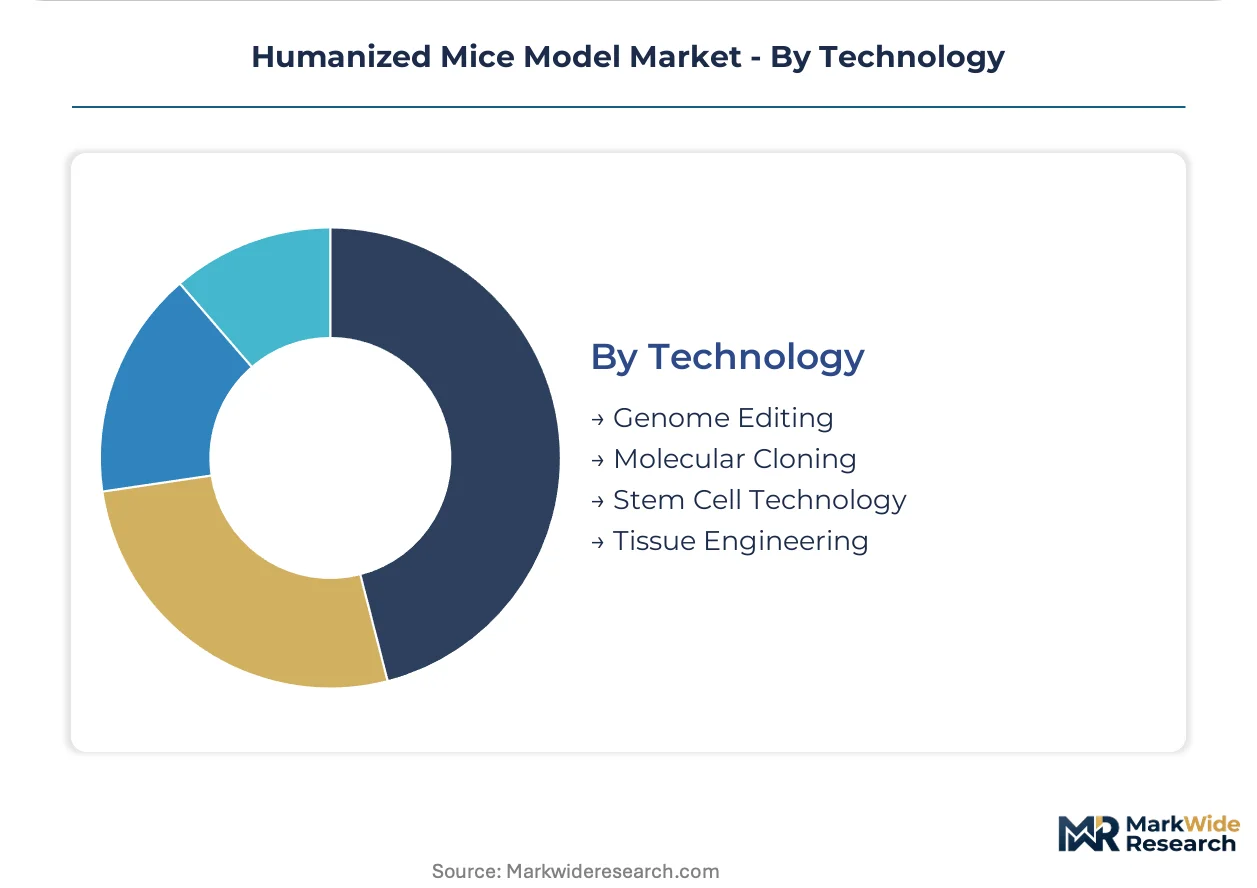
Technology:
Technical sophistication and capital intensity stratify supplier capabilities, with genome editing concentrating margin among specialized providers.
- Genome Editing:CRISPR-Cas9 knock-in systems enable precise human gene insertion with compressed breeding timelines. Gene-editing houses in California and Massachusetts are capturing premium pricing from toxicology groups requiring eighteen-month qualification windows, displacing conventional transgenic approaches.
- Stem Cell Technology:Hematopoietic stem cell engraftment protocols demand specialized surgical and immune monitoring expertise. CD34+ cell sourcing complexity constrains batch consistency, requiring rigorous quality control metrics that extend breeding timelines.
- Molecular Cloning:Traditional transgenic construction via pronuclear microinjection retains cost advantages for simple reporter line generation.
- Tissue Engineering:Organoid-humanized hybrid architectures merge 3D culture with immunodeficient hosts for patient-specific microenvironment replication.
Genome Editing leads technology investment. Stem Cell Technology commands highest operational complexity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of immunodeficient foundation strains concentrates in specialized breeding facilities across three continents, while consumption clusters at pharmaceutical development hubs in the United States, Germany, and Japan. This geographic split creates complex logistics networks for temperature-sensitive biological materials.
United States
FDA IND submission volumes drive demand for GLP-compliant humanized models at NCI-designated cancer centers and Boston-Cambridge biotech clusters. The agency's expedited pathway timelines compress preclinical qualification windows. Charles River Laboratories and Taconic Biosciences anchor supply relationships through multi-year colony management contracts with institutional purchasing offices in Massachusetts and California.
Germany
EMA Good Laboratory Practice documentation requirements tighten traceability standards for engraftment cell sourcing across contract research organizations in North Rhine-Westphalia. The EU Green Deal restricts chemical reagents used in model maintenance, accelerating facility upgrades. Heidelberg and Munich academic medical centers consolidate procurement through master service agreements with integrated model-and-testing bundles.
Japan
PMDA harmonization with FDA and EMA protocols streamlines multinational IND submissions for Tokyo and Osaka-based pharmaceutical sponsors. Preclinical pharmacology standards alignment reduces duplicate qualification studies. Yokohama biotech corridors expand CRISPR-edited humanized strain procurement for cell therapy pipelines.
United Kingdom
Horizon Discovery Group anchors genome editing capabilities serving toxicology groups requiring compressed breeding timelines. The Medicines and Healthcare products Regulatory Agency enforces lineage documentation standards for IND-supporting studies. London-Oxford-Cambridge golden triangle concentrates demand for patient-derived xenograft hosts in immuno-oncology development.
India
CDSCO pathway development accelerates as Hyderabad and Bangalore biotechnology clusters build preclinical pharmacology capacity. Domestic contract research organizations expand qualified humanized model supply relationships. Stem cell engraftment expertise scarcity constrains batch consistency, requiring technology transfer partnerships with established repository networks.
Humanized Mice Model Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates foundational strain supply among three major repository networks. The competitive terrain separates integrated service bundlers from specialized genetic editors and regional breeding operations. Two strategic archetypes dominate: subscription-based colony managers capturing multi-year research partnerships, and precision genome editing houses commanding premium pricing for CRISPR-Cas9 human gene knock-ins. Dominant competitive moves include backward integration into captive breeding capacity and geographic expansion through facility certification in additional regulatory jurisdictions.
Among repository-network anchors, The Jackson Laboratory exemplifies the strain-archival archetype through its genetically defined line collections, while Charles River Laboratories occupies a position within the integrated service tier combining model supply with toxicology testing. Taconic Biosciences represents the specialized-application vector, anchoring differentiated positioning through immunodeficient and humanized lines configured for specific therapeutic workflows. These three entities collectively illustrate how technical capability depth and regulatory qualification breadth determine competitive position in this market.
| Leading Market Players |
|---|
| The Jackson Laboratory |
| Charles River Laboratories |
| Inotiv |
| Taconic Biosciences |
| genOway |
| Crown Bioscience |
| Ingenious Targeting Laboratory |
| Horizon Discovery Group |
| Champions Oncology |
| Others |
Supply & Pricing Matrix
CRISPR-Cas9 knock-in protocols are displacing conventional pronuclear microinjection as the dominant production method, compressing breeding timelines from thirty-six to eighteen months while concentrating margin among specialized gene-editing houses in California and Massachusetts. This technological transition simultaneously elevates capital requirements for precision editing infrastructure and fragments pricing power away from legacy transgenic breeders toward CRISPR-capable suppliers with captive colony management platforms.
Pricing Analysis
Margin tightening in CRISPR-edited humanized strains reflects accelerated qualification windows demanded by FDA toxicology groups. Three-tier pricing structure across premium, standard, and economy levels stratifies by genetic complexity and regulatory documentation depth. Pharmaceutical sponsors in Basel and New Jersey exhibit lowest price sensitivity due to IND submission urgency, while academic laboratories in Boston and Heidelberg drive cost-down pressure through consolidated institutional purchasing.
Supply Chain Analysis
Specific-pathogen-free certification gates access to engraftment-ready immunodeficient hosts, with breeding capacity anchored in the United States, Germany, and Japan. Germ-free housing infrastructure and CD34+ hematopoietic stem cell sourcing draw from specialized repository networks and institutional tissue procurement chains. Single-source vulnerability concentrates in SCID/NOD-scid gamma foundation strain supply. Distribution runs through temperature-controlled logistics partnerships serving NCI-designated cancer centers and contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive breeding capacity and in-house CRISPR editing capabilities determine margin capture. Players are pursuing upstream control over foundation strain supply to secure engraftment host availability.
For Market Incumbents: Extend colony management subscription contracts through multi-year master service agreements with institutional purchasing offices at academic medical centers. Defend against specialized gene-editing houses by acquiring CRISPR technical capabilities or forming exclusive licensing partnerships with California and Massachusetts editing shops. Lock in CD34+ cell sourcing relationships to secure hematopoietic stem cell traceability for EMA audit compliance.
For New Entrants and Emerging Players: Digital colony management platforms offer the most penetrable entry vector, enabling software-defined breeding protocol subscriptions that displace spot purchasing at mid-tier biotechnology firms. Target India CDSCO pathway development as Hyderabad and Bangalore clusters build preclinical capacity without established supplier relationships. Lead with organoid-humanized hybrid model architectures to differentiate from incumbent immunodeficient host commoditization.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated contract research organizations seeking captive model supply. Long-term viability hinges on regulatory qualification breadth across FDA, EMA, and PMDA jurisdictions. Watch for PMDA harmonization completion as the inflection signal accelerating Japanese sponsor procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Editing Capability Acquisition | Precision human gene knock-ins command premium pricing over conventional transgenic approaches at toxicology groups. |
| Subscription Colony Management Contracts | Multi-year agreements with Boston and San Francisco biotech corridors displace transactional spot purchasing. |
| India CDSCO Facility Certification | Hyderabad and Bangalore preclinical capacity expansion creates qualified supply relationships for domestic biotechnology clusters. |
| Blockchain Lineage Tracking Implementation | EMA Good Laboratory Practice documentation requirements tighten engraftment cell sourcing traceability standards. |
| Organoid-Humanized Hybrid Development | Patient-specific tumor microenvironment replication opens differentiation from standard xenograft host commoditization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across laboratory animal science directors, contract research organization procurement leads, regulatory affairs specialists at pharmaceutical sponsors, and veterinary pathologists with human immunology cross-training. FDA IND submission databases, EMA Good Laboratory Practice inspection reports, PMDA preclinical pharmacology guidelines, and institutional purchasing office contract disclosures provided segmentation validation. Bottom-up colony capacity estimates and top-down pharmaceutical R&D spending allocations were triangulated against repository network production disclosures.
Segmentation granularity modeled product type at the strain architecture level, application at the therapeutic modality pipeline stage, end user at the procurement centralization tier, and technology at the gene-editing platform sophistication level across the analysis window. CAGRs derived from time-series regression of repository network capacity expansion, pharmaceutical sponsor preclinical spending patterns, and cell therapy pipeline multiplication rates. Forecast inputs incorporated CRISPR qualification timeline compression and EMA audit scope expansion.
The model holds under continued regulatory harmonization across FDA, EMA, and PMDA protocols; deviation in cross-border alignment on humanized model qualification standards would shift competitive positioning toward regionally specialized suppliers. A model refresh is warranted upon material change in genome editing regulatory classification or germ-free facility capital cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Preclinical CRO Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Clinical Trial Logistics Market