
 Global in Vivo Toxicology Market | 2026-2036
Global in Vivo Toxicology Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Vivo Toxicology Market Foresight
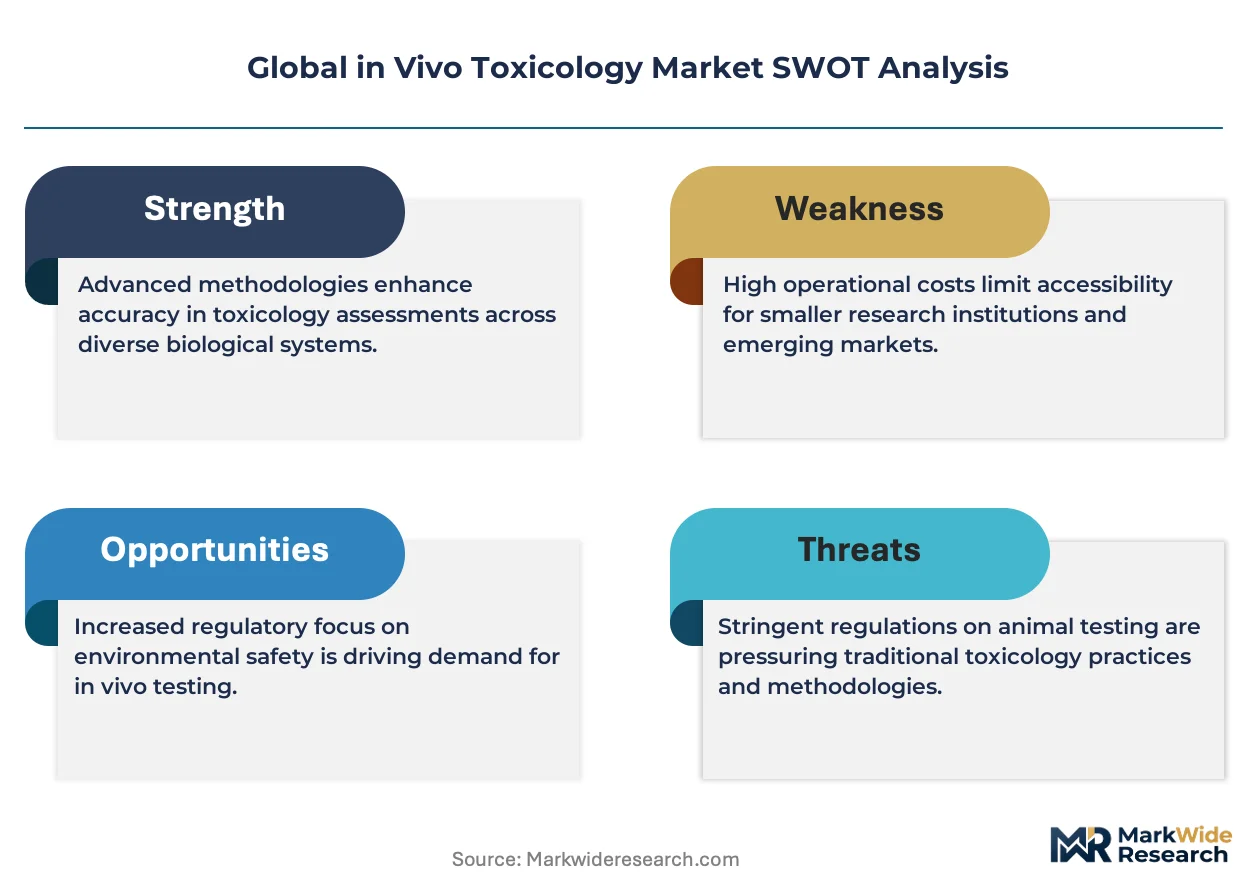
A widening capability gap between fully integrated model developers and assay-only providers is redrawing competitive boundaries in preclinical services. Charles River Laboratories leverages its captive breeding infrastructure across North America and Europe to control lead times on genetically modified strains. Thermo Fisher Scientific anchors its position through in-house production of molecular probes paired with analytical instrumentation. Envigo competes on scale in conventional rodent supply, though its limited gene-editing footprint leaves it exposed in high-margin custom model segments.
In vivo toxicology encompasses the study of adverse biological effects in living organisms, typically employing rodent and non-rodent species to characterize dose-response relationships, organ toxicity, and carcinogenic potential through histopathological examination and clinical pathology endpoints. Animal models remain the dominant product category, with humanized transgenic strains capturing expanding share in immuno-oncology safety evaluation where standard strains fail to predict cytokine release syndromes. Contract research organizations represent the fastest-growing end user segment as pharmaceutical sponsors outsource IND-enabling packages to access specialized pathology expertise without fixed cost burdens.
FDA's Good Laboratory Practice regulations and EMA's REACH-aligned chemical safety mandates compel standardized study designs that elevate demand for accredited testing facilities with OECD-compliant quality systems. EPA pesticide registration requirements and Japan's PMDA preclinical guidance further fragment compliance obligations across jurisdictions, favoring CROs with multi-regulatory track records. Stakeholders must weigh the capital requirements of internal toxicology infrastructure against the flexibility of outsourced partnerships as regulatory data package expectations intensify.
Market Dynamics
CRISPR-edited animal model production is concentrating among specialized breeders in the United States, creating supply bottlenecks that extend IND-enabling study timelines for pharmaceutical sponsors without captive breeding infrastructure.
Growth Catalysts
- FDA IND Study Requirements:Tightened preclinical safety data packages for investigational new drug applications are expanding toxicology study volumes across pharmaceutical pipelines.
- Immuno-oncology Pipeline Expansion:Humanized transgenic strains for cytokine release syndrome prediction are displacing standard rodent models in biologics safety evaluation.
- EMA REACH Chemical Mandates:Registration, Evaluation, Authorization and Restriction of Chemicals obligations are elevating demand for OECD-compliant chronic toxicity studies in European contract research facilities.
Market Restraints
- Gene-edited Rodent Supply Concentration:CRISPR-modified strain production clusters among United States-based specialized breeders, extending lead times for European and Asian sponsors.
- Specialized Pathologist Scarcity:Board-certified veterinary pathologists with GLP study director experience represent a constrained talent pool, inflating CRO staffing costs.
- Alternative Method Substitution:Organ-on-chip and in silico toxicology platforms are capturing early-stage screening share from rodent acute toxicity studies.
Strategic Opportunities
- China NMPA Preclinical Demand:Domestic innovative drug development is accelerating, creating unmet need for IND-enabling toxicology capacity within Chinese contract research organizations.
- Japan PMDA Harmonization:International Council for Harmonisation alignment is streamlining multi-regional study acceptance, favoring CROs with dual FDA-PMDA inspection histories.
- AI-enabled Histopathology:Machine learning image analysis convergence with digital slide scanning is compressing pathology report turnaround times for high-volume carcinogenicity studies.
Industry Challenges
- Multi-regulatory GLP Certification:Maintaining simultaneous FDA, EMA, and OECD Good Laboratory Practice compliance across facilities demands redundant quality systems and audit preparation cycles.
- Legacy Data Migration:Transitioning decades of paper-based study archives to electronic data capture formats compatible with SEND standards requires substantial validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Vivo Toxicology Market |
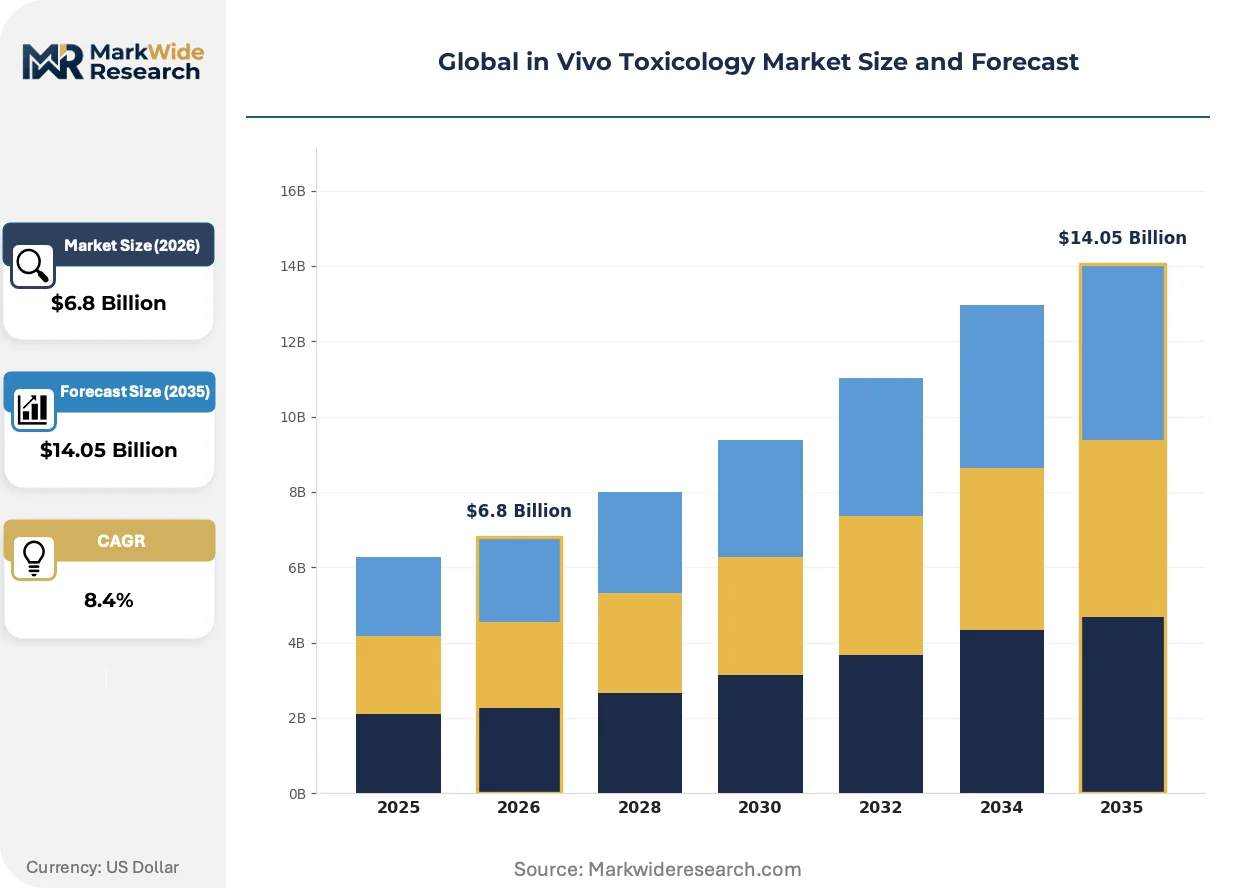
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Models, Cell-Based Assays, Molecular Probes, Diagnostic Kits, Imaging Agents Application: Drug Safety Evaluation, Environmental Toxicity Testing, Chemical Risk Assessment, Cosmetic Testing, Pesticide Analysis End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Firms, Regulatory Agencies Technology: Histopathology, Biochemical Assays, Genotoxicity Testing, Behavioral Analysis, Immunohistochemistry |
| Companies Covered | Charles River Laboratories, The Jackson Laboratory, Envigo, Taconic Biosciences, Janvier Labs, Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Vivo Toxicology Market Shifts & Advancements
Preclinical toxicology workflows are fragmenting between high-complexity custom model development and commoditized safety screening, with technology investments diverging accordingly across service provider tiers.
Humanized immune system mouse models are bifurcating the oncology toxicology segment. Large-molecule biopharma sponsors now specify these strains for immune-related adverse event prediction. Standard immunocompetent rodent demand is compressing into small-molecule and generic safety packages where cytokine release risk remains minimal.
EMA's revision of carcinogenicity testing guidelines is reducing two-year rodent bioassay requirements for certain pharmaceutical classes. The industrial consequence shifts resource allocation toward transgenic rasH2 and p53+/- short-term models. Biologics developers in Europe are accelerating adoption of these alternatives to compress development timelines.
Sponsor procurement of toxicology services is consolidating toward integrated IND-enabling packages rather than discrete study outsourcing. Mid-tier biotechnology companies are displacing fragmented vendor management with single-CRO master service agreements. This pattern is most visible among Boston-Cambridge and San Francisco Bay Area clusters where sponsor density enables preferred provider negotiations.
Global in Vivo Toxicology Market Segmentation
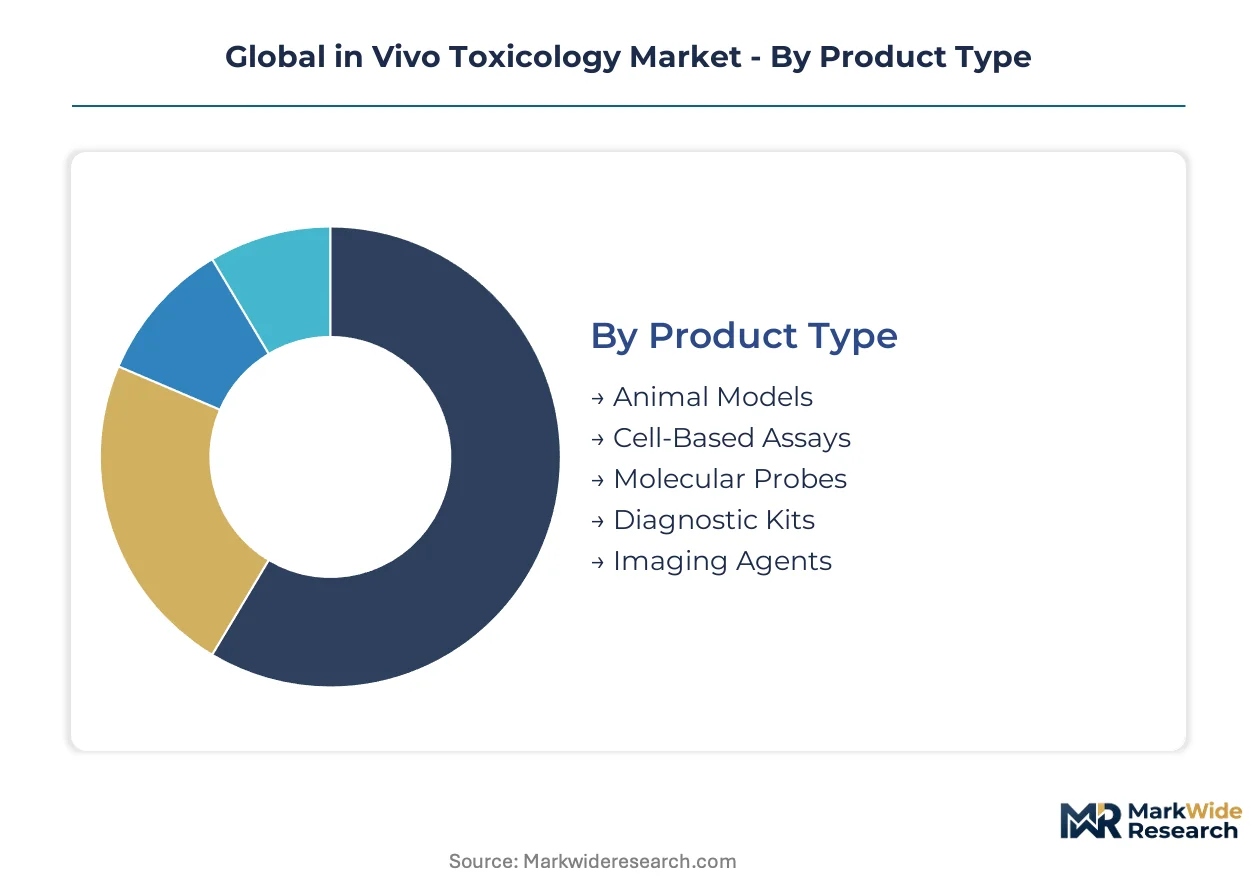
Segmentation in in vivo toxicology reveals how specialized capabilities concentrate across product tiers and customer channels. Pharmaceutical sponsors route high-complexity studies through integrated CROs while commodity screening flows to assay-only providers.
Product Type:
Animal models and molecular probes flow through captive breeding networks and analytical instrument channels respectively, with gene-edited strains commanding premium distribution through specialized United States-based breeders.
- Animal Models:Genetically modified rodents, humanized transgenic strains, and conventional outbred stocks constitute the foundational substrate for IND-enabling safety studies. Demand concentrates among pharmaceutical sponsors developing biologics, where humanized immune system mice predict cytokine release syndromes that standard strains miss.
- Molecular Probes:Fluorescent and radiolabeled detection reagents enable biomarker visualization across organ toxicity endpoints. Biotechnology firms in Boston-Cambridge and San Francisco Bay Area clusters drive probe procurement for mechanistic toxicology investigations.
- Cell-Based Assays:Hepatocyte and cardiomyocyte platforms provide early hepatotoxicity and cardiotoxicity signals before rodent studies.
- Diagnostic Kits:Preconfigured clinical pathology panels standardize biomarker measurement across GLP facilities.
- Imaging Agents:Contrast reagents for MRI and PET applications support non-invasive toxicity monitoring in large animal models.
By volume, Animal Models leads. By growth pace, Molecular Probes is gaining share fastest as multiplex detection demands intensify.
Application:
Cost tier separation distinguishes regulatory-mandated pharmaceutical safety packages from discretionary environmental and cosmetic screening budgets.
- Drug Safety Evaluation:GLP-compliant repeat-dose toxicity, carcinogenicity, and reproductive toxicology studies form the revenue core for contract research organizations. FDA IND requirements and EMA marketing authorization mandates ensure sustained sponsor investment regardless of pipeline cyclicality.
- Chemical Risk Assessment:Industrial chemical registration under EPA TSCA and ECHA REACH obligations drives chronic toxicity and ecotoxicology study demand. European contract research facilities capture disproportionate share given REACH's data-intensive authorization processes.
- Environmental Toxicity Testing:Aquatic and terrestrial organism studies support pesticide and industrial chemical registration.
- Cosmetic Testing:Regulatory bans on animal testing in Europe and select United States jurisdictions have shifted this segment toward in vitro alternatives and residual non-rodent requirements.
- Pesticide Analysis:EPA registration mandates require tiered toxicity packages for active ingredient approval.
Drug Safety Evaluation commands the highest absolute spending. Chemical Risk Assessment shows the steepest expansion trajectory as REACH authorization deadlines accumulate.
End User:
Customer type determines procurement structure, with large pharmaceutical companies negotiating master service agreements while biotechnology firms purchase discrete study packages.
- Contract Research Organizations:Specialized toxicology service providers aggregate pathology expertise and regulatory track records that pharmaceutical sponsors cannot replicate economically. Charles River Laboratories and Envigo compete for integrated IND-enabling package contracts spanning multiple study types.
- Pharmaceutical Companies:Multinational sponsors maintain selective internal toxicology capabilities while outsourcing specialized studies to access gene-edited model platforms and board-certified veterinary pathologists.
- Biotechnology Firms:Venture-backed developers lack capital for captive infrastructure and represent price-sensitive demand for rapid turnaround screening.
- Academic Institutions:Non-GLP mechanistic studies support publication objectives rather than regulatory submissions.
- Regulatory Agencies:Government laboratories conduct method validation and reference standard development.
Contract Research Organizations lead by study volume. Biotechnology Firms are climbing the fastest as innovative drug development accelerates beyond large pharmaceutical pipeline capacity.
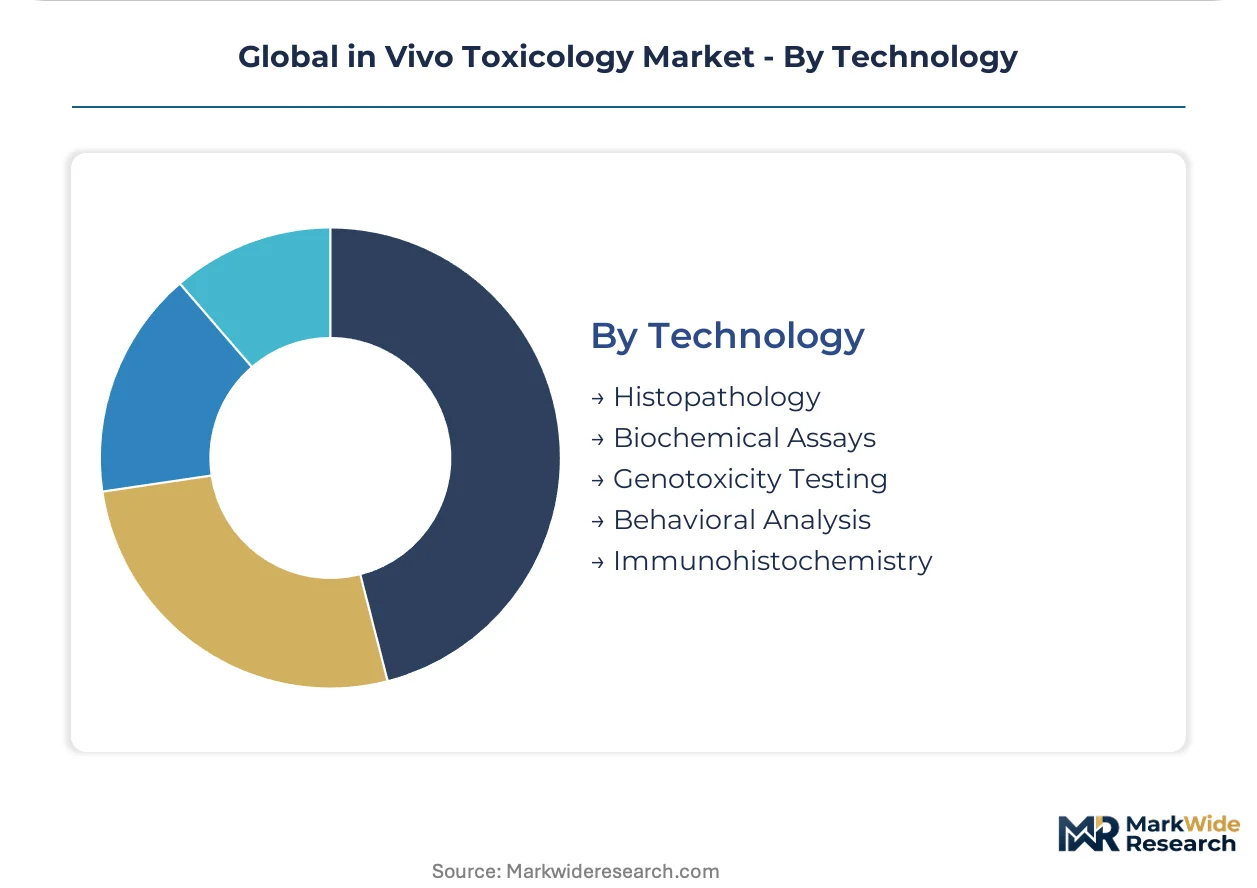
Technology:
Supply concentration in specialized expertise separates high-margin histopathology from commoditized biochemical screening.
- Histopathology:Tissue sectioning, staining, and microscopic evaluation by board-certified veterinary pathologists remains the definitive endpoint for organ toxicity determination. Scarcity of GLP-experienced pathologists concentrates this capability among established CROs with dedicated recruitment pipelines.
- Genotoxicity Testing:Ames assays, micronucleus tests, and chromosomal aberration studies provide regulatory-mandated mutagenicity data. Standardized OECD protocols enable method transfer across facilities, compressing differentiation potential.
- Biochemical Assays:Enzyme and metabolite quantification supports mechanistic toxicity investigations.
- Immunohistochemistry:Antibody-based protein detection enables cell-specific toxicity localization.
- Behavioral Analysis:Functional observation batteries and locomotor assessments support neurotoxicity evaluation.
Histopathology dominates revenue contribution. Genotoxicity Testing is expanding most quickly as gene therapy and cell therapy products require expanded mutagenicity characterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in toxicology procurement varies sharply by geography. United States sponsors absorb premium pricing for gene-edited model access, while Chinese and Indian buyers prioritize cost efficiency in conventional screening packages.
United States
FDA IND submission volumes drive sustained demand for GLP-compliant repeat-dose studies. The agency's tightened preclinical safety data requirements compress development timelines for biotechnology sponsors. Boston-Cambridge and San Francisco Bay Area clusters concentrate sponsor headquarters, creating dense procurement networks for integrated IND-enabling packages.
Germany
ECHA REACH authorization deadlines accumulate for industrial chemical registrants, elevating chronic toxicity study demand. The country's federal chemicals regulator maintains stringent OECD compliance expectations for contract research facilities. Rhine-Ruhr and Bavarian biotech corridors host specialized toxicology CROs serving European pharmaceutical sponsors.
China
Domestic innovative drug development accelerates beyond local toxicology capacity, creating import dependence for complex studies. NMPA preclinical guidance alignment with ICH standards elevates quality expectations for IND submissions. Shanghai and Suzhou biotech parks attract multinational CRO investments to capture unmet sponsor demand.
Japan
PMDA's ICH harmonization streamlines multi-regional study acceptance for pharmaceutical exporters. The regulator's preclinical guidance emphasizes carcinogenicity alternatives to two-year rodent bioassays. Tokyo-Osaka pharmaceutical corridors concentrate sponsor R&D spending on transgenic short-term models.
United Kingdom
EMA-aligned marketing authorization requirements sustain toxicology outsourcing despite regulatory divergence post-Brexit. The Medicines and Healthcare products Regulatory Agency maintains GLP inspection reciprocity with continental European facilities. Cambridge and Oxford life science clusters concentrate gene therapy development, driving specialized safety study demand.
Global in Vivo Toxicology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the toxicology services landscape. Fully integrated model developers command premium positioning through captive gene-editing infrastructure, while assay-only providers compete on throughput pricing for standardized screening. Three archetypes dominate: specialized breeders with CRISPR capabilities, analytical instrumentation conglomerates with molecular probe production, and scale-focused conventional rodent suppliers. Consolidation through acquisition of pathology expertise and geographic expansion into Chinese NMPA markets represent the dominant competitive vectors.
Among North American-based integrated service providers, Charles River Laboratories exemplifies the vertically consolidated archetype with transcontinental breeding infrastructure. Thermo Fisher Scientific anchors the analytical-instrumentation tier through in-house reagent production paired with detection platforms. Envigo occupies a position within the scale-driven conventional supply segment, though its limited gene-editing footprint exposes vulnerability in high-margin custom model markets.
| Leading Market Players |
|---|
| Charles River Laboratories |
| The Jackson Laboratory |
| Envigo |
| Taconic Biosciences |
| Janvier Labs |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Humanized transgenic strain substitution for conventional rodent models simultaneously redistributes supply geography toward United States-based CRISPR specialists and inflates pricing premiums for biotechnology sponsors lacking captive breeding infrastructure. FDA IND submission timelines compress as sponsors absorb elevated costs for cytokine release syndrome prediction capabilities unavailable from standard strain suppliers.
Pricing Analysis
After-sales pathology service contracts and extended study director retainers drive lifetime value for contract research organizations beyond initial model procurement. Three-tier pricing structure across premium gene-edited strains, standard outbred stocks, and economy screening packages separates sponsor tiers by therapeutic modality complexity. Price differentiation rests on GLP certification grade and board-certified veterinary pathologist availability. Cost compression in conventional rodent screening intensifies as organ-on-chip platforms capture early-stage acute toxicity share. Biotechnology firms in Boston-Cambridge and San Francisco Bay Area clusters exhibit lowest price sensitivity for humanized immune system models, while generic pharmaceutical sponsors in India and China prioritize cost efficiency in repeat-dose packages.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive genetically modified rodent shipments from United States breeding facilities to European and Asian contract research sites elevate total landed costs through specialized courier networks and extended quarantine protocols. Geographic supply concentration clusters in the United States, Germany, and China for CRISPR-edited strain production, conventional rodent breeding, and expanding toxicology capacity respectively. Raw material dependencies center on specific pathogen-free feed formulations, molecular probe reagents, and veterinary pharmaceutical inputs. Single-source vulnerability in board-certified veterinary pathologist talent pools threatens study execution timelines across multi-regional GLP facilities. Distribution runs through captive breeding networks for animal models and analytical instrument channels for molecular probes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-edited model proliferation and FDA IND data package expansion constitute a high-growth disruption reshaping competitive boundaries in preclinical toxicology services.
For Market Incumbents: Shield core revenue streams by deepening captive gene-editing infrastructure against specialized breeder supply bottlenecks, and secure board-certified veterinary pathologist pipelines through academic partnerships to offset talent scarcity-driven staffing inflation. GLP certification maintenance across multi-regulatory jurisdictions remains essential for integrated IND-enabling package retention. For New Entrants and Emerging Players: Anchor in Chinese NMPA preclinical capacity gaps as domestic innovative drug development accelerates beyond local toxicology infrastructure, and exploit AI-enabled histopathology automation to compress carcinogenicity study turnaround times against established pathology-heavy incumbents. White-space concentration favors dual FDA-PMDA inspection track records for multi-regional pharmaceutical exporters. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated model developers with transcontinental breeding footprints and pathology expertise. Long-term viability across the projection horizon hinges on gene-edited strain production capabilities and OECD-compliant quality systems. Acquisition target archetypes include mid-scale contract research organizations with underutilized GLP capacity in Asia-Pacific regulatory clusters. The signal to watch is NMPA IND submission volume acceleration as domestic Chinese biotechnology funding cycles mature.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Model Production Scale-Up | Captive gene-editing infrastructure controls lead times for cytokine release syndrome prediction studies. |
| Multi-Regulatory GLP Certification | Simultaneous FDA, EMA, and OECD compliance enables integrated IND-enabling package competitiveness. |
| AI-Enabled Histopathology Investment | Machine learning image analysis compresses pathology report turnaround for high-volume carcinogenicity studies. |
| China NMPA Capacity Expansion | Domestic toxicology infrastructure addresses unmet preclinical demand from accelerating innovative drug development. |
| Veterinary Pathologist Pipeline Development | Academic partnerships secure constrained board-certified talent for GLP study director roles. |
Research Methodology
Desk research of FDA IND submission databases, EMA marketing authorization filings, and OECD GLP inspection records preceded structured interviews with pharmaceutical development executives, contract research organization operations directors, regulatory affairs leads, and biotechnology venture capital investors. Secondary validation drew from ClinicalTrials.gov toxicology study registrations, SEC 10-K CRO segment disclosures, and national pharmaceutical regulator preclinical guidance documents. Bottom-up toxicology service revenue modeling and top-down pharmaceutical R&D spending allocation triangulation anchored market size estimation.
Variance decomposition across product type, application, end user, and technology segmentation dimensions shaped analytical framework construction throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate pharmaceutical pipeline expansion and regulatory study volume trends. Forecast inputs incorporated gene-edited rodent demand trajectories, REACH authorization deadline accumulation effects, and NMPA preclinical capacity development timelines.
Material uncertainties — regulatory study requirement modifications, alternative method substitution acceleration, and geopolitical trade restriction impacts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ICH harmonization progression and GLP inspectorate resource availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Preclinical CRO Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Clinical Trial Investigative Site Network Market