
 Global Clinical Trial Management Systems Market | 2026-2036
Global Clinical Trial Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trial Management Systems Market Foresight
Enterprise software procurement for clinical operations is tilting toward cloud-native architectures with embedded compliance layers. Veeva Systems leverages its vault platform to anchor life-science workflows across trial planning and execution. Oracle competes through database-to-application integration that sustains incumbent relationships with large pharmaceutical sponsors. Medidata differentiates via its unified platform for data capture and trial management, occupying a specialized position in complex oncology and rare-disease studies.
A clinical trial management system constitutes an integrated software platform that orchestrates study planning, site management, patient enrollment, regulatory documentation, and data collection across multi-site protocols, typically operating through validated electronic data capture with audit trails and role-based access controls. Its primary commercial purpose is to compress trial timelines, reduce protocol deviations, and generate submission-ready documentation for health authorities. Cloud-based deployment leads in new installations as sponsors prioritize remote site access and elastic infrastructure, while regulatory compliance modules within solution offerings command premium pricing due to mandatory validation requirements. Patient recruitment functionality grows fastest among solution categories as decentralized trial models expand, though data management retains the deepest margin pools given integration complexity and long-term contract structures.
FDA 21 CFR Part 11, EMA ICH E6(R2) Good Clinical Practice, and GDPR data-protection standards collectively shape product roadmaps, forcing vendors to embed audit trails, consent management, and cross-border data-governance tools at the platform layer. Japan's PMDA and South Korea's MFDS impose additional localization requirements that filter market access for non-compliant foreign suppliers. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to algorithmic patient-matching and predictive enrollment tools before committing to platform architectures.
Market Dynamics
Cloud-native architectures with embedded FDA 21 CFR Part 11 validation layers are restructuring vendor competitive positions by collapsing the traditional separation between trial operations software and compliance infrastructure.
Growth Catalysts
- Decentralized trial expansion:Remote patient monitoring technologies enable direct-to-patient data capture, eliminating site visit dependencies. Sponsors in oncology and rare-disease studies deploy these models to expand geographic reach.
- EMA ICH E6(R2) harmonization:The guideline's risk-based quality management mandates drive demand for integrated quality-by-design platforms. Vendors embed risk assessment tools directly into protocol design modules.
- Real-world evidence integration:FDA guidance on RWE submissions pushes sponsors to link CTMS platforms with external data lakes. This convergence creates new workflow requirements for data lineage documentation.
Market Restraints
- Validation cost structure:Computerized system validation for FDA 21 CFR Part 11 compliance consumes 18-24 months and substantial professional services expenditure. Mid-tier biotech sponsors defer upgrades due to resource constraints.
- Data localization mandates:China's NMPA and Russia's data sovereignty requirements fragment cloud architectures. Vendors must maintain separate infrastructure instances, duplicating operational overhead.
- Legacy system entrenchment:Oracle Clinical and older on-premise installations persist at top-20 pharmaceutical sponsors. Migration complexity and revalidation risk freeze procurement cycles.
Strategic Opportunities
- India's CDSCO trial expansion:The regulator's streamlined clinical trial approval pathways attract multinational sponsors. Local CTMS deployment partnerships capture emerging site management demand.
- EU AI Act algorithmic governance:Risk-classification frameworks for patient-matching AI create compliance tooling gaps. Vendors embedding algorithmic audit capabilities command premium positioning.
- API-first platform architecture:Modular interoperability between CTMS, EDC, and eCOA systems replaces monolithic suites. Sponsors assemble best-of-breed stacks through standardized data exchange protocols.
Industry Challenges
- Clinical data science talent scarcity:Hybrid skill requirements spanning biostatistics, regulatory science, and cloud architecture outpace supply. Sponsors compete for platform configuration specialists.
- Multi-regulatory validation synchronization:Simultaneous FDA, EMA, and PMDA system qualification demands divergent documentation standards. Project timelines extend to accommodate sequential rather than parallel submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trial Management Systems Market |
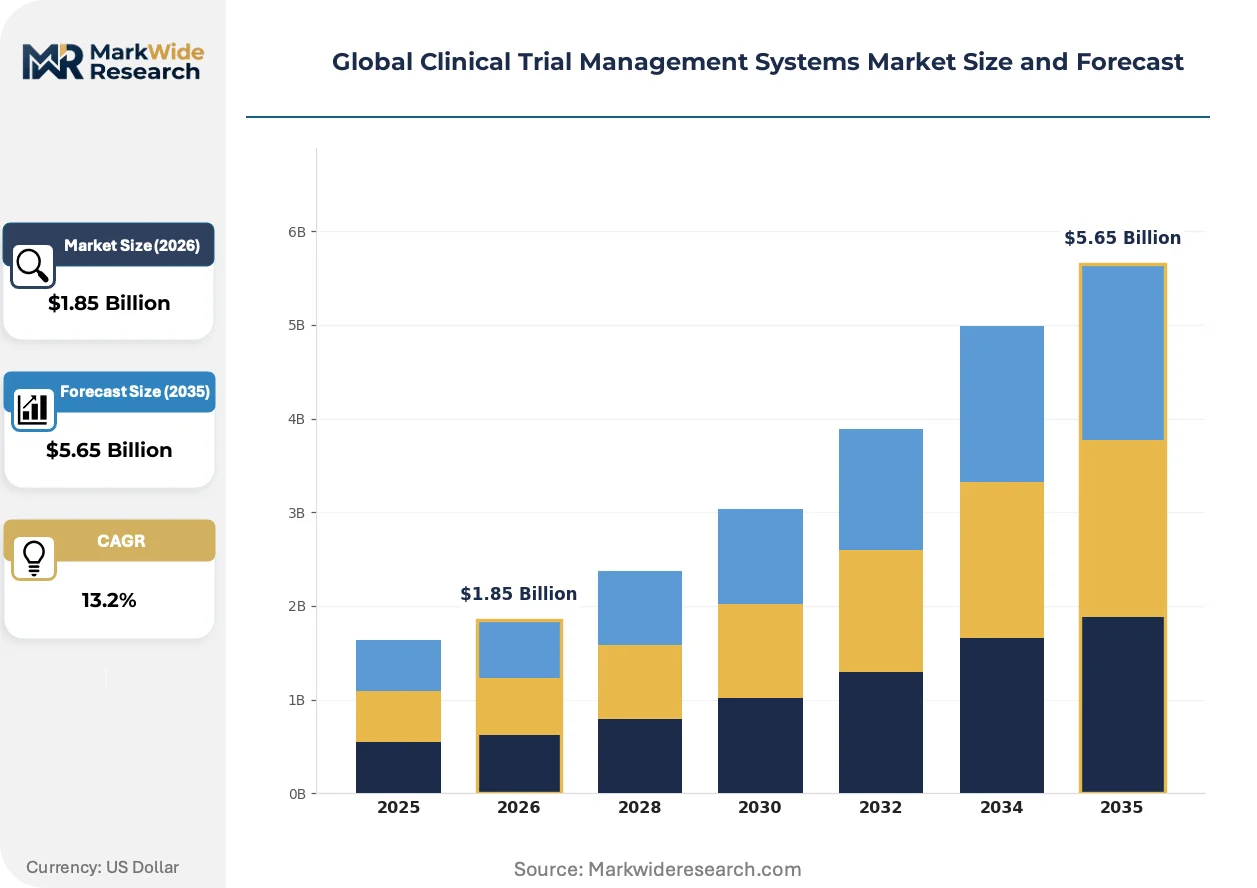
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Solution Offering: Patient Recruitment, Data Management, Monitoring, Regulatory Compliance, Reporting Tools Application: Pharmaceutical Studies, Biotech Research, Medical Device Trials, Academic Research, Contract Research Organization End User: Pharmaceutical Companies, Biotech Firms, Medical Research Institutes, Contract Research Organizations |
| Companies Covered | Veeva Systems, Oracle, Medidata, IQVIA, Parexel International, Advarra, IBM, Clinion, RealTime Software Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trial Management Systems Market Shifts & Advancements
Artificial intelligence is compressing traditional trial timelines by automating protocol deviation detection and predictive enrollment modeling. This shift demands rearchitected data pipelines and new governance frameworks.
Distributed ledger technology for clinical data provenance is collapsing the multi-day reconciliation cycles between sponsors and contract research organizations. Mid-size biotechs in the United States and Germany pilot these implementations for investigational product supply chain tracking. The structural consequence eliminates intermediary audit steps and compresses query resolution from weeks to hours.
Japan's PMDA revised data integrity guidelines now mandate timestamp granularity and electronic signature standards that exceed FDA baseline requirements. Domestic vendors adapt platform configurations specifically for this jurisdiction. Multinational sponsors operating in Japan face parallel validation tracks that complicate global system deployments.
Site payment automation through embedded financial workflows displaces manual invoice reconciliation processes. Research institutions in the United Kingdom and Netherlands demand real-time grant allocation visibility within trial management interfaces. This behavioral shift forces vendors to integrate with institutional ERP systems rather than maintaining standalone payment modules.
Global Clinical Trial Management Systems Market Segmentation
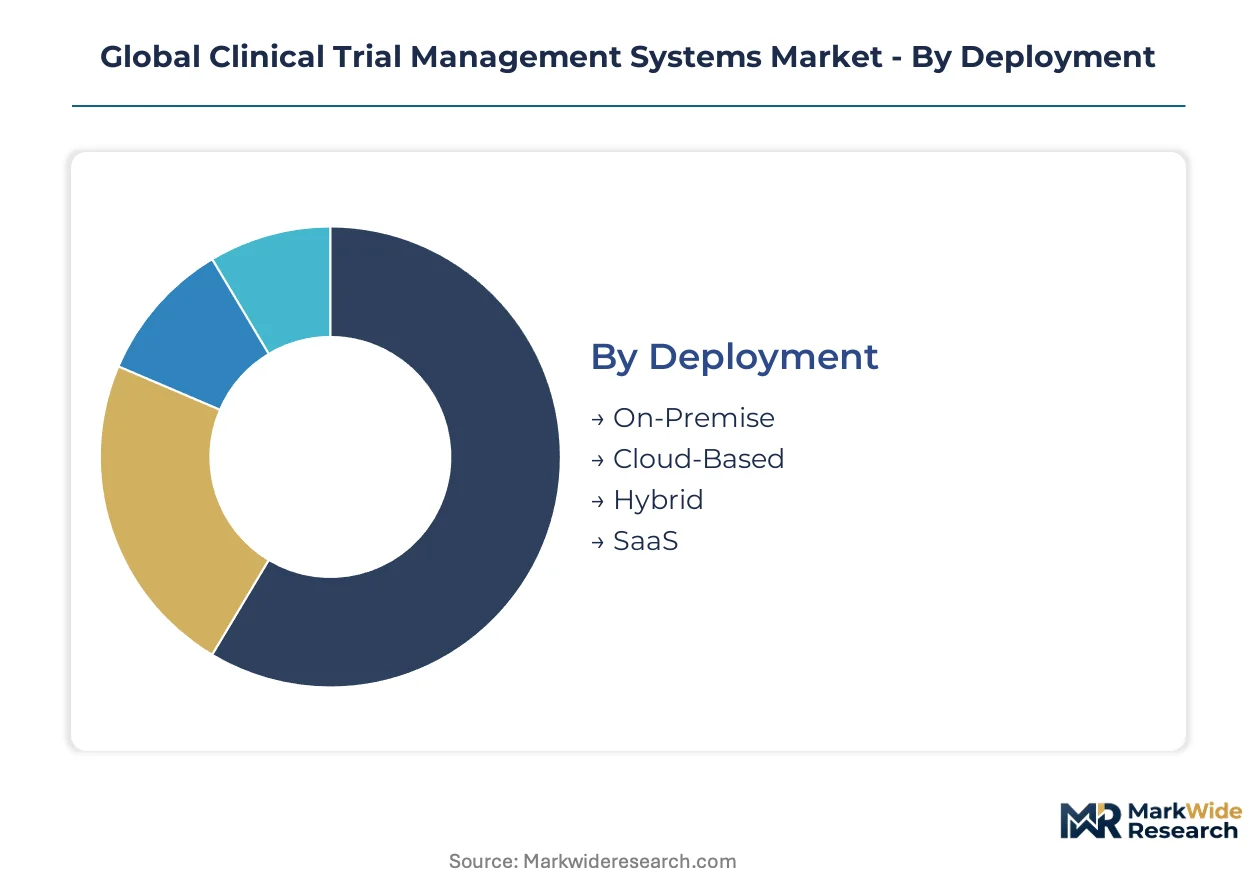
Clinical trial management systems fragment across deployment architectures, functional modules, study types, and sponsor categories. Each segmentation axis reveals distinct procurement patterns, pricing dynamics, and vendor competitive positioning.
Deployment:
Mature on-premise installations coexist with emerging cloud-native architectures as sponsors navigate validation timelines and data sovereignty constraints.
- On-Premise:Legacy infrastructure maintained behind sponsor firewalls with full hardware control. Large pharmaceutical sponsors in Germany and Japan retain these deployments due to PMDA and EMA data localization requirements that complicate cross-border cloud transfers.
- Cloud-Based:Elastic infrastructure with remote site access and automatic software updates. Mid-tier biotech sponsors in the United States adopt these models to compress startup timelines and eliminate capital expenditure on server hardware.
- Hybrid:Split architectures keeping sensitive patient data on-premise while leveraging cloud analytics layers. Sponsors running multi-regional oncology studies deploy this model to satisfy GDPR residency requirements while enabling real-time monitoring.
- SaaS:Subscription-based delivery with vendor-managed validation documentation and shared infrastructure costs. Academic research institutes and emerging biotechs in India select this tier for predictable operational expenditure and reduced IT staffing needs.
Cloud-Based handles the majority of new procurement cycles; SaaS is expanding most quickly among cost-constrained sponsors.
Solution Offering:
Functional modules vary in margin depth based on integration complexity and regulatory validation burden.
- Patient Recruitment:Algorithmic matching tools and decentralized enrollment platforms that connect sponsors with underrepresented populations. Demand concentrates in oncology and rare-disease studies where geographic dispersion of eligible patients requires direct-to-patient outreach models.
- Data Management:Electronic data capture with audit trails, query management, and statistical programming interfaces. This module commands the deepest contract values due to FDA 21 CFR Part 11 validation requirements and multi-year data retention obligations.
- Monitoring:Risk-based site oversight tools with remote source data verification capabilities. CROs in the United States and United Kingdom deploy these to reduce travel-intensive on-site monitoring while maintaining ICH E6(R2) compliance.
- Regulatory Compliance:Embedded validation documentation, electronic signature workflows, and submission-ready reporting packages. Vendors price this module at premium tiers due to mandatory qualification for FDA, EMA, and PMDA inspections.
- Reporting Tools:Real-time dashboards and safety signal detection for investigator meetings and DSMB reviews. Medical device sponsors prioritize these capabilities for accelerated PMA and 510(k) submission timelines.
Data Management captures the largest share of contract value; Patient Recruitment is climbing the fastest as decentralized models expand.
Application:
Study complexity and regulatory intensity shape platform configuration requirements across therapeutic domains.
- Pharmaceutical Studies:Phase I-III drug development with extensive biomarker integration and adaptive protocol designs. Large sponsors in the United States and Switzerland deploy these configurations for complex immunology and neuroscience programs.
- Biotech Research:Early-phase and proof-of-concept studies with lean operational structures and rapid site activation. Emerging sponsors in Boston and San Diego clusters favor modular platforms that scale from single-site to multi-regional without revalidation.
- Medical Device Trials:PMA, 510(k), and CE mark studies with distinct endpoint capture and adverse event reporting workflows. Vendors embed ISO 14155 compliance layers specifically for this segment's quality system requirements.
- Academic Research:Investigator-initiated studies with limited budgets and grant-dependent procurement cycles. University medical centers in the Netherlands and Sweden select open-source or heavily discounted SaaS tiers.
- Contract Research Organization:Multi-sponsor platform deployments requiring tenant isolation and sponsor-specific branding. Global CROs headquartered in the United States and Ireland negotiate enterprise licenses spanning hundreds of concurrent studies.
Pharmaceutical Studies generates the deepest contract pools; Biotech Research is gaining share fastest among emerging sponsors.
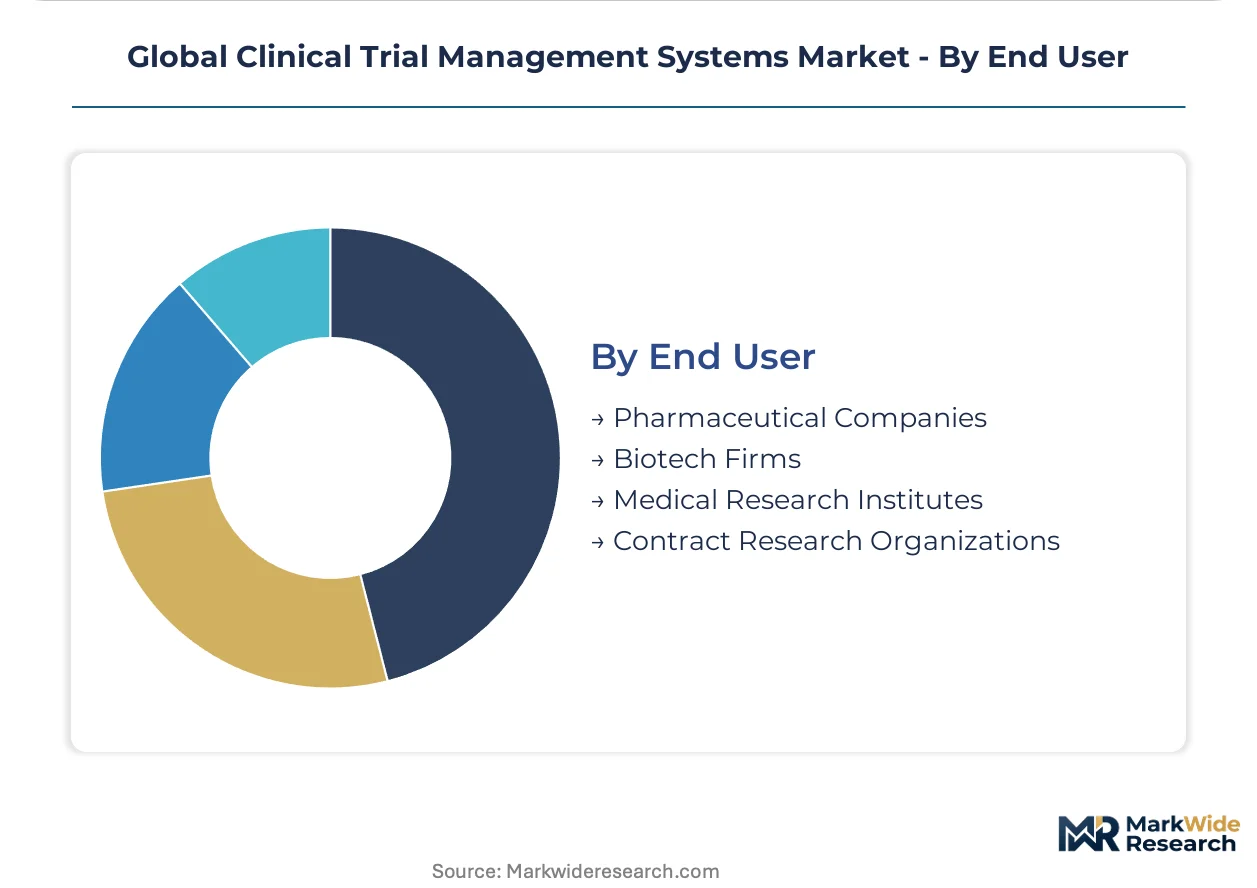
End User:
Procurement sophistication varies sharply between capital-rich incumbents and resource-constrained innovators.
- Pharmaceutical Companies:Top-20 sponsors with dedicated clinical informatics teams and multi-year enterprise agreements. These buyers negotiate custom validation packages and demand API-first architectures for best-of-breed system integration.
- Biotech Firms:Venture-backed and publicly traded developers with lean operational models and rapid scaling needs. Sponsors in Cambridge, Massachusetts and South San Francisco prioritize platforms with pre-configured FDA and EMA validation documentation.
- Medical Research Institutes:Academic medical centers and government research hospitals with dual clinical and research missions. Institutions in Germany and Japan face institutional review board complexities that extend platform configuration timelines.
- Contract Research Organizations:Full-service and niche providers managing outsourced trials for multiple sponsors simultaneously. CROs in India and Eastern Europe select platforms with multi-tenant architectures and automated sponsor-specific reporting pipelines.
Pharmaceutical Companies anchor the largest contract values; Biotech Firms are expanding most quickly as venture funding concentrates in precision medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the densest fiber-optic backbone connecting major research corridors, underwriting its position as the primary demand center for clinical trial infrastructure. Germany's high-speed rail network links pharmaceutical clusters across its federal states, enabling rapid site activation and investigator mobility. Japan's undersea cable systems to Asia-Pacific markets support cross-border data synchronization for multi-regional studies.
United States
FDA 21 CFR Part 11 enforcement drives enterprise software procurement across the Boston-Cambridge and San Francisco Bay Area biotech corridors. The FDA's digital health guidance for decentralized trials accelerates cloud-native platform adoption. Massachusetts and California house the highest concentration of emerging sponsors deploying patient recruitment modules for oncology studies.
Germany
EMA ICH E6(R2) harmonization mandates reshape vendor priorities for risk-based quality management tools. The country's data protection authority enforces GDPR clinical data standards that exceed baseline European requirements. Bavaria and Baden-Württemberg host established pharmaceutical sponsors maintaining hybrid cloud deployments for multi-regional immunology programs.
Japan
PMDA data integrity guidelines with enhanced timestamp granularity requirements filter market access for foreign CTMS suppliers. METI's pharmaceutical industry digitalization subsidies support domestic platform development. The Kanto region around Tokyo concentrates site management demand for rare-disease studies requiring specialized enrollment protocols.
India
CDSCO streamlined trial approval pathways attract multinational sponsors expanding geographic reach for infectious disease studies. The regulator's pharmacovigilance data submission mandates create validation documentation demand for local CROs. Maharashtra and Karnataka emerge as primary deployment locations for SaaS-based site management platforms serving contract research organizations.
United Kingdom
NHS digital transformation funding embeds trial management systems within academic medical center workflows. MHRA post-Brexit regulatory divergence from EMA standards forces parallel validation tracks for global sponsors. The Greater London and Oxford-Cambridge arc concentrates real-world evidence integration demand linking CTMS platforms with national health data lakes.
Global Clinical Trial Management Systems Market Competitive Landscape
On the supply side, the industry is consolidating around platform vendors with embedded compliance architectures that collapse traditional separations between trial operations and regulatory infrastructure. Tiered competitive dynamics separate enterprise-grade suite providers from modular specialists and regional service integrators. Dominant strategic moves include API-first architecture investments enabling best-of-breed system interoperability, and pre-configured validation packages compressing FDA, EMA, and PMDA qualification timelines.
Within the cloud-native platform tier, Veeva Systems and Oracle occupy positions anchoring life-science workflow standardization. Medidata exemplifies the specialized data-capture archetype with unified platform positioning in complex therapeutic domains. These three vendors represent divergent competitive vectors: vault-centric ecosystem expansion, database-to-application incumbent leverage, and oncology-focused functional depth.
| Leading Market Players |
|---|
| Veeva Systems |
| Oracle |
| Medidata |
| IQVIA |
| Parexel International |
| Advarra |
| IBM |
| Clinion |
| RealTime Software Solutions |
| Others |
Supply & Pricing Matrix
Boston-Cambridge's dense concentration of biotech sponsors shapes downstream pricing power for CTMS vendors, as proximity to venture capital and FDA review centers compresses procurement cycles and elevates willingness-to-pay for validated platforms. Cloud-native architectures with embedded compliance layers command premium positioning against legacy on-premise alternatives, while data localization requirements in Germany and Japan fragment pricing coherence across regional deployments.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with top-20 pharmaceutical sponsors negotiating multi-year agreements that embed professional services and validation documentation. Price differentiation hinges on FDA 21 CFR Part 11 certification grade and customization depth for multi-regional study configurations. Pricing pressure stems from mid-tier biotech sponsors deferring upgrades due to validation cost burdens. Academic research institutes exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Upstream feedstock for CTMS platforms draws from specialized software engineering talent pools concentrated in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in hyperscaler data center networks. Critical components include HIPAA-compliant hosting environments, cryptographic modules for electronic signatures, and API middleware for EDC integration. Single-source vulnerability concentrates in validation documentation services, where qualified professionals span regulatory science and software quality assurance. Distribution runs through direct enterprise sales teams and CRO channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
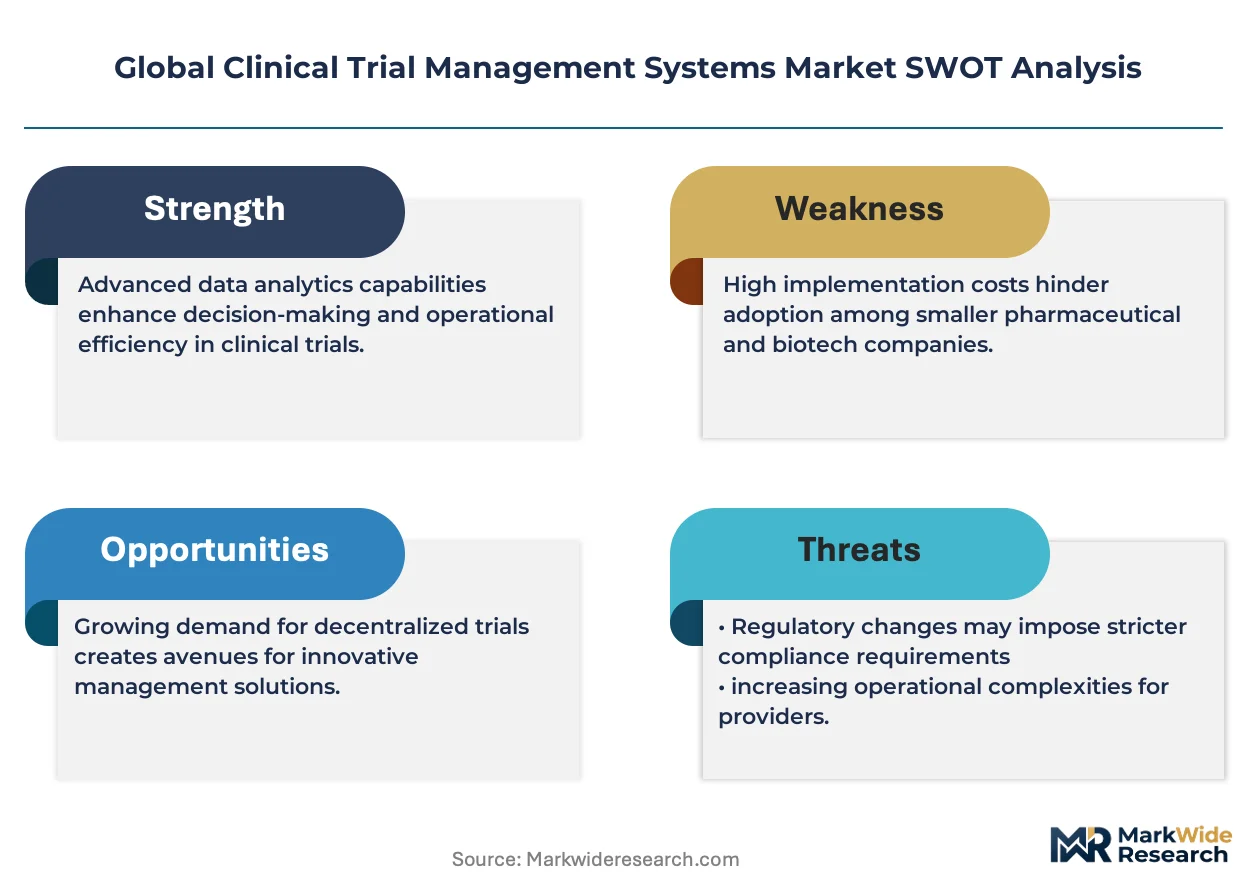
The CTMS market is entering a cyclical recovery phase driven by sponsor digitization mandates following pandemic-era trial disruptions. Venture funding concentration in precision medicine creates sustained demand for scalable platform architectures.
For Market Incumbents: Build switching-cost moats through deep EDC and eCOA system integration that locks sponsors into unified data workflows. Incumbents should acquire specialized patient recruitment AI firms to neutralize emerging modular competitors, while expanding professional services capacity in Germany and Japan to capture localization-driven revalidation demand. Threat vectors include API-first challengers disaggregating monolithic suites and mid-tier biotech sponsor budget constraints freezing upgrade cycles. For New Entrants and Emerging Players: India's CDSCO trial expansion offers underpenetrated site management demand as multinational sponsors diversify geographic risk. New entrants should target SaaS tiers for academic research institutes in the Netherlands and Sweden, where grant-dependent procurement favors predictable operational expenditure models. A specialized go-to-market angle centers on pre-configured validation packages for rare-disease study protocols, compressing PMDA qualification timelines for domestic Japanese sponsors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with multi-tenant architectures serving CROs. Long-term viability across the five-to-ten year window favors vendors embedding EU AI Act algorithmic governance capabilities ahead of enforcement. Acquisition targets should demonstrate proven FDA 21 CFR Part 11 validation documentation and established site management deployments in oncology or rare-disease verticals. The signal to watch is CDSCO approval pathway volume as an indicator of emerging market platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CTMS, EDC, and eCOA workflows to eliminate data reconciliation cycles between sponsors and CROs. |
| Regulatory Approval Pathway | Pre-configured FDA, EMA, and PMDA validation packages compress system qualification timelines for multi-regional studies. |
| Geographic Expansion | Local CDSCO partnerships in Maharashtra and Karnataka capture emerging site management demand from multinational sponsors. |
| Acquisition of Specialist Firm | Patient recruitment AI capabilities address decentralized trial expansion in oncology and rare-disease therapeutic domains. |
| Product Launch | Embedded EU AI Act algorithmic audit tools command premium positioning for predictive enrollment modules. |
Research Methodology
Cross-validation between primary interviews with clinical operations executives and secondary analysis of FDA 483 inspection observations anchors the qualitative findings in documented compliance patterns. Stakeholder engagement spanned drug development executives at top-20 pharmaceutical sponsors, regulatory affairs leads managing multi-regional submissions, CRO platform configuration specialists, and academic research institute IT procurement officers. Secondary sources included ClinicalTrials.gov protocol registries, EMA inspection outcome reports, CDSCO approval pathway disclosures, and hyperscaler healthcare cloud compliance certifications. Bottom-up site activation data and top-down enterprise software spending estimates were reconciled through iterative calibration.
Calibration approaches stress-tested segment-level growth assumptions against historical trial startup velocity and regulatory submission volume trends across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution module category, study phase and therapeutic area, sponsor size tier, and regional regulatory cluster complexity. CAGRs were derived from slope-consistent trajectory fitting validated against vendor-reported booking patterns and sponsor procurement cycle surveys. Forecast inputs incorporated PMDA data integrity guideline enforcement intensity and decentralized trial technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by Oracle or Veeva would shift competitive dynamics and vendor selection outcomes. Material shifts in FDA 21 CFR Part 11 enforcement posture or EU AI Act risk classification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
India CRO Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Global Clinical Trials Matching Software Market