
 India Preclinical CRO Market | 2026-2036
India Preclinical CRO Market Size, Share, and Industry Trends Forecast 2026-2036
India Preclinical CRO Market Insights
AI-driven predictive toxicology is reshaping how preclinical safety data is generated and interpreted for regulatory submissions. Syngene International Limited anchors large-molecule discovery services through its integrated campus in Bangalore. Jubilant Biosys Ltd. specializes in integrated chemistry and biology platforms for early-stage pharma programs. Eurofins Advinus leverages its GLP-certified facilities to compete in regulatory toxicology outsourcing.
Preclinical CROs execute non-clinical safety and efficacy studies on drug candidates before human trials, encompassing pharmacokinetic profiling, toxicology assessment, and biomarker validation in GLP-compliant environments. In vivo testing commands premium pricing due to higher regulatory scrutiny and specialized vivarium infrastructure requirements. Bioanalytical services are expanding fastest as complex biologics and biosimilars drive demand for sophisticated assay development across the pharmaceutical and biotechnology verticals.
CDSCO mandates GLP compliance for preclinical data supporting IND applications, while the country's national pharmaceutical regulator enforces OECD-adopted study protocols for export-oriented submissions. The PLI scheme for pharmaceuticals indirectly stimulates CRO demand by expanding domestic R&D manufacturing capacity. Stakeholders must monitor how evolving BIS standards for laboratory equipment and digital data integrity reshape compliance costs and competitive positioning.
Market Dynamics
Pharmaceutical sponsors are consolidating discovery outsourcing around integrated CRO platforms that combine medicinal chemistry, DMPK, and GLP toxicology under single accountability structures, compressing vendor rosters and elevating contract values for full-service providers.
Growth Catalysts
- CDSCO IND Pathway Streamlining:The regulator's accelerated review mechanisms for investigational new drug applications are shortening preclinical-to-clinic timelines, prompting sponsors to expand outsourced study programs in India.
- Biologics Pipeline Expansion:Biosimilar and antibody-drug conjugate development is displacing small-molecule dominance, creating specialized demand for large-molecule bioanalytical capabilities and primate toxicology services.
- Karnataka-Telangana Corridor Concentration:Bangalore-Hyderabad biotech clusters aggregate GLP-certified vivarium infrastructure, PhD-level toxicologists, and OECD-mutual recognition arrangements, reducing sponsor due diligence burdens.
Market Restraints
- Primate Import Dependence:Cynomolgus monkey and beagle sourcing relies on Southeast Asian breeding networks and transcontinental logistics, exposing toxicology programs to wildlife trade restrictions and IATA live-animal transport capacity constraints.
- GLP Facility Capital Intensity:OECD-compliant study execution requires purpose-built vivariums, environmental monitoring systems, and archival infrastructure that lock up capital for seven-to-ten-year depreciation cycles.
- Specialized Talent Scarcity:Board-certified veterinary pathologists and GLP study directors command compensation premiums that compress operating margins for mid-scale CROs competing against multinational anchor facilities.
Strategic Opportunities
- AI-Augmented Predictive Toxicology:Machine learning platforms trained on legacy study datasets are compressing dose-range finding timelines and enabling virtual patient stratification for first-in-human dosing.
- PLI Scheme R&D Spillover:The production-linked incentive scheme for active pharmaceutical ingredients is expanding domestic formulation R&D capacity, creating captive preclinical service demand from beneficiary manufacturers.
- Gene Therapy Vector Assessment:AAV and lentiviral vector biodistribution studies represent underpenetrated service lines where Indian CROs can leverage non-human primate access against Western capacity constraints.
Industry Challenges
- Archival Data Integrity Enforcement:BIS standards for laboratory equipment calibration and electronic data capture systems are extending compliance audit preparation cycles and elevating quality assurance headcount requirements.
- Cross-Functional Integration Complexity:Sponsor demand for seamless chemistry-biology-DMPK handoffs strains CRO organizational design, requiring investment in LIMS harmonization and program management capabilities that smaller operators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Preclinical CRO Market |
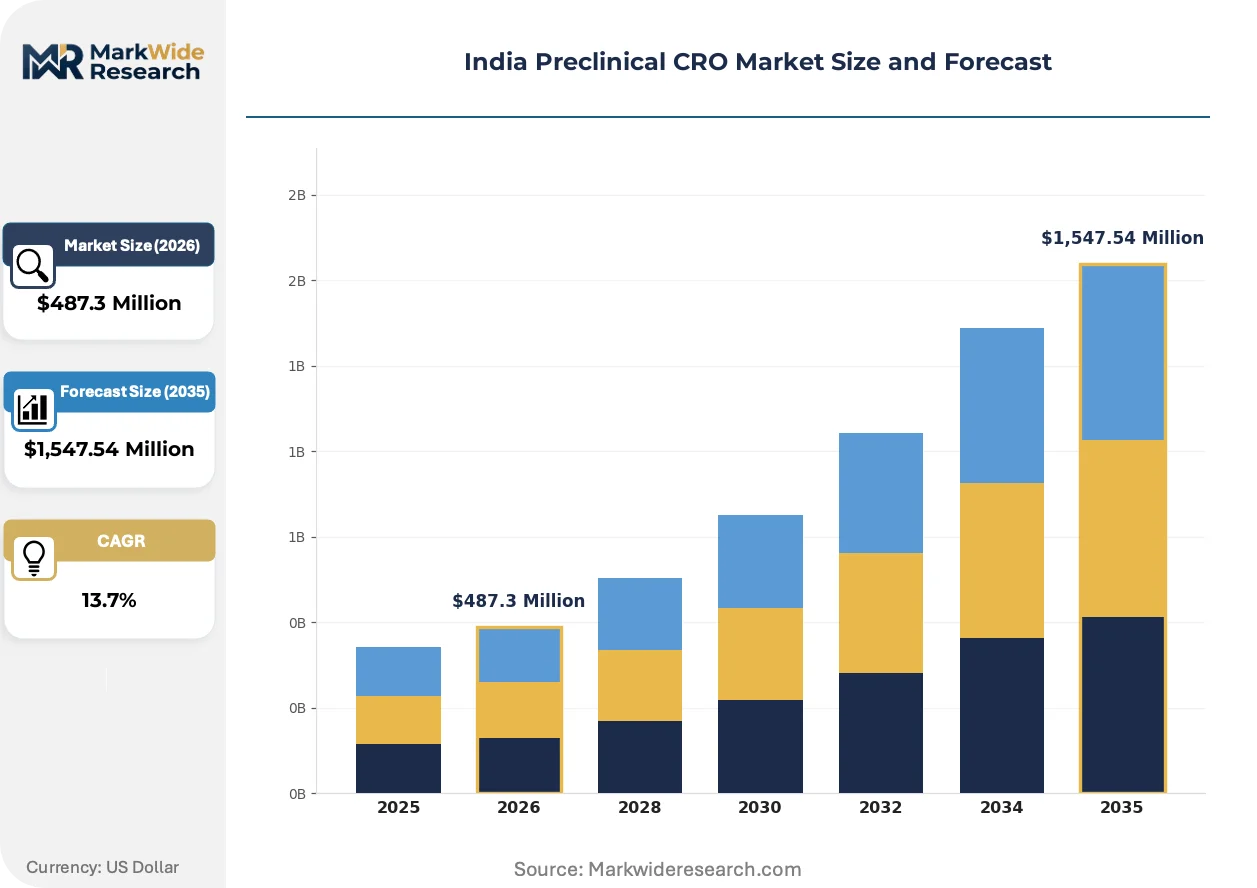
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,547.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In Vitro Testing, In Vivo Testing, Toxicology Studies, Pharmacokinetics Technology: Cell Culture, Molecular Imaging, High-Throughput Screening, Bioanalytical Industry Vertical: Biotechnology, Pharmaceutical, Agricultural, Chemical End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Dabur Research, Sugen Life Sciences, Syngene International Limited, JSS Medical Research, Vipragen, Jubilant Biosys Ltd., Veeda Clinical Research Limited, Aragen Life Sciences Ltd., Eurofins Advinus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Preclinical CRO Market Trends and Innovations
Preclinical research execution is converging around digitally instrumented study workflows that compress reporting timelines and enable real-time sponsor visibility into in-life data generation.
Organ-on-chip microphysiological systems are hybridizing traditional two-dimensional cell culture with perfused tissue architectures that replicate organ-level pharmacokinetics. Biotechnology sponsors in immuno-oncology and rare disease programs are piloting these platforms for mechanistic safety assessment prior to animal model selection. This technology is hybridizing the discovery-to-IND timeline by enabling human-relevant data generation that reduces reliance on exploratory toxicology studies.
CDSCO's adoption of OECD GLP principles with India-specific inspection protocols is harmonizing domestic data acceptance standards with US FDA and EMA mutual recognition frameworks. Multinational pharmaceutical sponsors now treat Indian GLP certifications as equivalent to Western jurisdictions for global IND submissions. This regulatory alignment is most affecting regulatory toxicology outsourcing decisions, with sponsors expanding India-based pivotal study placement previously reserved for North American or European facilities.
Sponsor procurement functions are consolidating vendor relationships around master service agreements that bundle discovery chemistry, safety pharmacology, and regulatory toxicology under volume-commitment pricing. Large pharmaceutical companies are displacing transactional project-by-project contracting with preferred-provider frameworks that guarantee capacity allocation and prioritize queue positioning. This behavior shift is most visible among US and European headquartered sponsors with established India-based alliance management infrastructure.
India Preclinical CRO Market Segmentation
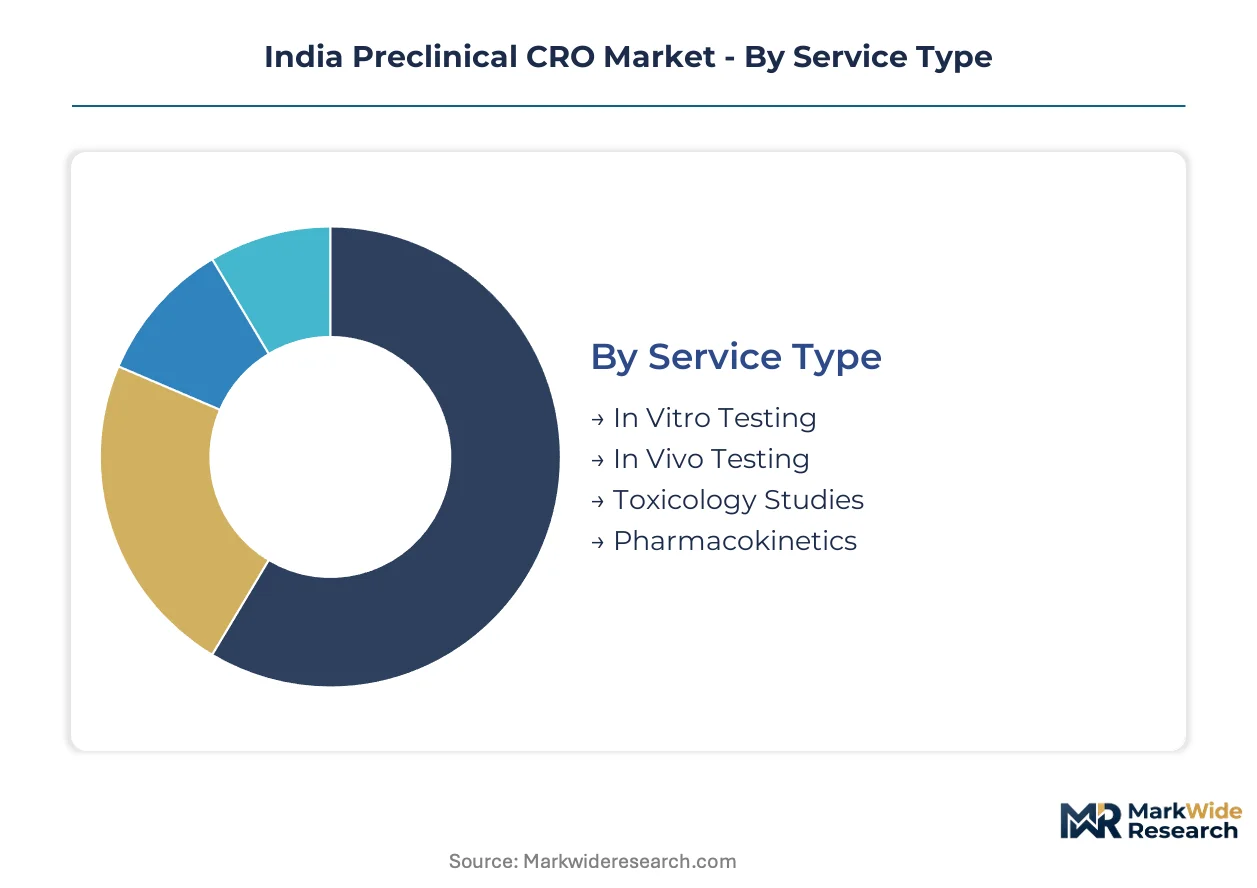
Preclinical CRO service portfolios fragment across specialized technical capabilities and sponsor organizational types, with each segment exhibiting distinct margin profiles and regulatory intensity. Understanding these divisions clarifies where capital deployment concentrates and which service lines attract premium pricing.
Service Type:
Mature toxicology and pharmacokinetic services anchor revenue stability, while emerging in vitro platforms reshape early-stage discovery economics.
- In Vivo Testing:Live-animal pharmacology and safety studies execute in GLP-certified vivariums with specialized veterinary pathology oversight. Karnataka's Bangalore-Hyderabad corridor concentrates this capacity due to OECD-mutual recognition arrangements and primate access logistics.
- Toxicology Studies:Regulatory safety assessment for IND submissions demands board-certified study directors and archival data systems compliant with CDSCO-adopted OECD protocols. CDSCO's streamlined review mechanisms are expanding sponsor placement of pivotal studies previously reserved for Western CROs.
- In Vitro Testing:Cell-based assays and organ-on-chip platforms reduce animal use while accelerating mechanistic safety data generation.
- Pharmacokinetics:ADME profiling and bioanalytical method development support dose selection for first-in-human trials.
In Vivo Testing handles the majority of throughput; In Vitro Testing is expanding most quickly on share.
Technology:
Technology deployment stratifies between high-capital imaging infrastructure and scalable screening platforms.
- Bioanalytical:Ligand-binding assays and mass spectrometry quantification support biologics and biosimilar development programs. Bangalore-based CROs are investing in specialized large-molecule capabilities to capture antibody-drug conjugate pipeline expansion.
- High-Throughput Screening:Automated compound profiling accelerates hit-to-lead timelines for medicinal chemistry programs.
- Molecular Imaging:PET and optical imaging systems visualize disease progression and therapeutic response in living models.
- Cell Culture:Two-dimensional and three-dimensional cellular models provide early mechanistic safety data prior to animal studies.
Bioanalytical commands premium pricing due to specialized large-molecule expertise scarcity; High-Throughput Screening scales fastest on volume.
Industry Vertical:
Vertical demand concentrates in human therapeutics, with agricultural and chemical applications following distinct regulatory pathways.
- Pharmaceutical:Small-molecule and biologic developers outsource non-clinical safety packages for CDSCO IND submissions. The PLI scheme for active pharmaceutical ingredients is expanding domestic R&D manufacturing capacity and creating captive preclinical demand.
- Biotechnology:Gene therapy and cell therapy sponsors require specialized vector biodistribution and immunogenicity assessment capabilities.
- Chemical:Industrial and agrochemical toxicity testing follows REACH-aligned protocols for export market access.
- Agricultural:Crop protection and veterinary product safety studies serve domestic and export registration requirements.
Pharmaceutical sponsors generate the dominant contract value; Biotechnology is climbing the fastest on pipeline investment.
End User:
End-user procurement patterns diverge between centralized pharmaceutical outsourcing and fragmented institutional research.
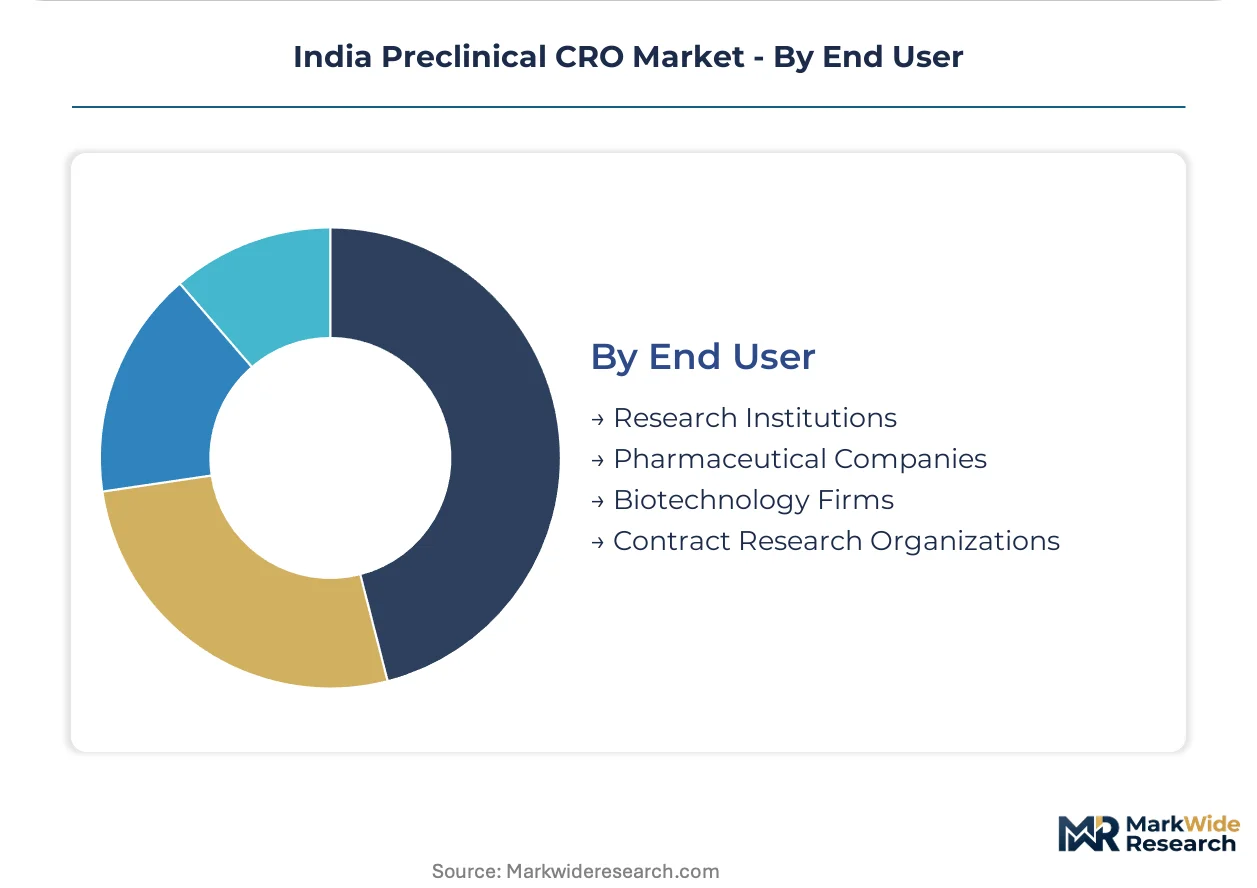
- Pharmaceutical Companies:Multinational and domestic sponsors consolidate vendor relationships around integrated discovery-to-IND platforms with master service agreement pricing. Procurement functions are displacing transactional contracting with preferred-provider frameworks guaranteeing capacity allocation.
- Biotechnology Firms:Venture-funded developers prioritize speed and flexibility over scale, favoring CROs with rapid study initiation.
- Research Institutions:Academic and government laboratories access CRO capabilities through collaborative grants and fee-for-service arrangements.
- Contract Research Organizations:Subcontracting relationships enable specialized capability access without capital investment.
Pharmaceutical Companies anchor contract value concentration; Biotechnology Firms are gaining share fastest on venture deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian preclinical CRO services flow primarily toward North American and European pharmaceutical sponsors seeking cost-efficient GLP-compliant study execution. The Karnataka-Telangana corridor anchors export-oriented capacity, while Maharashtra and Gujarat sustain domestic formulation R&D spillover demand. CDSCO's regulatory alignment with OECD standards enables data acceptance across US FDA and EMA jurisdictions.
Karnataka
GLP-certified vivarium infrastructure and primate toxicology capacity concentrate in Bangalore's biotech clusters. CDSCO's streamlined IND review mechanisms attract multinational sponsors to locate pivotal safety studies here. The Bangalore-Hyderabad corridor aggregates PhD-level toxicologists and OECD-mutual recognition arrangements that reduce sponsor due diligence burdens.
Telangana
Hyderabad's life sciences parks host integrated discovery-to-IND platforms serving biologics and biosimilar developers. Genome Valley infrastructure supports large-molecule bioanalytical method development for antibody-drug conjugate programs. PLI scheme beneficiaries in active pharmaceutical ingredient manufacturing generate captive preclinical demand from adjacent formulation R&D facilities.
Maharashtra
Mumbai-Pune pharmaceutical manufacturing belts sustain demand for regulatory toxicology supporting domestic IND submissions. BIS laboratory equipment standards enforcement elevates compliance investment requirements for CROs serving export-oriented sponsors. The region's chemical synthesis heritage feeds medicinal chemistry outsourcing from multinational discovery programs.
Gujarat
Ahmedabad-Vadodara industrial corridors specialize in agrochemical and veterinary product safety assessment following REACH-aligned protocols. CDSCO-adopted OECD study protocols enable data package reuse for EU export registrations. The state's pharmaceutical manufacturing expansion under PLI incentives creates parallel preclinical service demand from beneficiary firms.
Tamil Nadu
Chennai-based research institutions access CRO capabilities through collaborative grants and fee-for-service arrangements. Academic medical centers pilot organ-on-chip microphysiological systems for mechanistic safety assessment prior to animal model selection. The state's biotechnology policy incentives attract contract research capacity to serve immuno-oncology and rare disease program sponsors.
India Preclinical CRO Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated campus operators anchor the premium tier with bundled chemistry-biology-DMPK-GLP toxicology accountability structures. Mid-scale specialists occupy the efficiency tier through focused toxicology or bioanalytical service lines. Emerging platform players leverage AI-augmented predictive toxicology to compress dose-range finding timelines. Capacity expansion and strategic partnerships dominate competitive moves, with preferred-provider framework negotiations displacing transactional project contracting.
Among India-anchored integrated service providers, Syngene International Limited exemplifies the full-service campus archetype with Bangalore-based large-molecule discovery capabilities. Jubilant Biosys Ltd. represents the chemistry-biology platform specialist segment serving early-stage pharma programs. Eurofins Advinus occupies a position within the regulatory toxicology tier through GLP-certified facility operations. These three entities collectively illustrate how geographic clustering, service integration depth, and regulatory compliance infrastructure differentiate positioning across sponsor procurement evaluations.
| Leading Market Players |
|---|
| Dabur Research |
| Sugen Life Sciences |
| Syngene International Limited |
| JSS Medical Research |
| Vipragen |
| Jubilant Biosys Ltd. |
| Veeda Clinical Research Limited |
| Aragen Life Sciences Ltd. |
| Eurofins Advinus |
| Others |
Pricing and Supply Chain Analysis
Primate import dependence from Southeast Asian breeding networks determines both pricing tier spreads and supply chain shape in the India preclinical CRO market. Cynomolgus monkey sourcing constraints compress margins for mid-scale operators while elevating premium pricing for GLP-certified facilities with captive vivarium infrastructure.
Pricing Analysis
The technology-generation pricing gap between legacy two-dimensional cell culture platforms and organ-on-chip microphysiological systems is widening contract value spreads. Project-based pricing dominates regulatory toxicology services, while bioanalytical method development commands premium rates due to large-molecule expertise scarcity. CDSCO's streamlined IND review mechanisms are intensifying price competition among OECD-certified facilities as sponsors consolidate vendor rosters. Small biotechnology firms exhibit highest price sensitivity, whereas multinational pharmaceutical companies prioritize capacity allocation guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between India and Southeast Asian primate breeding networks dominates supply chain risk assessment for toxicology program execution. Live-animal sourcing draws from China, Vietnam, and Cambodia breeding facilities, with transcontinental logistics resting on IATA live-animal transport capacity. Beagle and non-human primate dependencies create single-source vulnerability during wildlife trade restriction enforcement. Distribution runs through Bangalore-Hyderabad corridor GLP-certified vivariums to North American and European pharmaceutical sponsors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India preclinical CRO market sits at an early-cycle expansion story justified by CDSCO's regulatory alignment with OECD standards accelerating sponsor placement of pivotal studies previously reserved for Western facilities.
For Market Incumbents: Pre-empt AI-augmented predictive toxicology displacement by investing in machine learning platforms trained on legacy study datasets. Consolidate chemistry-biology-DMPK handoff capabilities through LIMS harmonization to defend against emerging platform players compressing dose-range finding timelines. Expand GLP-certified vivarium capacity in Karnataka's Bangalore corridor to capture biologics pipeline expansion.
For New Entrants and Emerging Players: Build out gene therapy vector assessment capabilities as an underpenetrated service line where Indian CROs can leverage non-human primate access against Western capacity constraints. Target biotechnology firm segments with rapid study initiation protocols and flexible contracting structures. Pursue preferred-provider framework negotiations with venture-funded developers prioritizing speed over scale.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated campus operators with bundled accountability structures. Long-term viability hinges on regulatory data acceptance equivalence across US FDA and EMA jurisdictions. Acquisition target archetype: mid-scale specialists with GLP certification gaps and chemistry-biology platform depth. Monitor PLI scheme R&D spillover intensity as inflection indicator for captive preclinical demand generation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Predictive Toxicology Platform | Machine learning deployment compresses dose-range finding timelines for CDSCO IND submissions. |
| GLP Vivarium Capacity Expansion | OECD-certified infrastructure addition captures biologics sponsor pivot from Western CROs. |
| Gene Therapy Vector Assessment Capability | AAV biodistribution expertise addresses Western non-human primate access constraints. |
| Preferred-Provider Framework Negotiation | Master service agreements guarantee capacity allocation from consolidating pharmaceutical sponsors. |
| Organ-on-Chip Microphysiological System Integration | Hybrid cell culture platforms reduce animal use while accelerating mechanistic safety data generation. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, GLP study directors, and CRO procurement managers and refined through secondary validation. Primary fieldwork combined structured interviews with CDSCO officials and OECD-mutual recognition arrangement stakeholders with operational assessments of Bangalore-Hyderabad corridor facilities. Secondary sources encompassed CDSCO inspection reports, OECD GLP compliance databases, SEC filings from publicly listed CRO operators, and PLI scheme beneficiary disclosures. Bottom-up service line sizing and top-down pharmaceutical R&D outsourcing trend analysis were triangulated to establish market boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed service type, technology deployment, industry vertical, and sponsor organizational archetype. CAGRs were derived from sponsor outsourcing intensity projections and domestic R&D manufacturing capacity expansion under PLI incentives. Forecast inputs incorporated biologics pipeline composition shifts and CDSCO review timeline compression assumptions.
Stress conditions across primate import restriction severity, GLP facility capital cost inflation, and specialized talent compensation escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory data acceptance continuity and sponsor vendor consolidation trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Preclinical CRO Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
North America Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Synthetic Clinical Trial Data Market