
 Patient-Reported Outcome Data Monetization Market | 2026-2036
Patient-Reported Outcome Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Patient-Reported Outcome Data Monetization Market Insights
Cloud-native infrastructure is consolidating the economics of patient-reported outcome data platforms, replacing legacy on-premise systems that carried heavy maintenance overhead. IQVIA leverages its clinical data ecosystem to anchor real-world evidence services for pharmaceutical clients. Oracle sustains database dominance across healthcare verticals, competing directly with Microsoft on cloud analytics integration for PRO workflows.
Patient-reported outcome data monetization encompasses the systematic collection, aggregation, and commercialization of health status information directly from patients, typically captured through validated instruments such as the SF-36 or EQ-5D questionnaires delivered via digital platforms. The primary commercial purpose centers on supplying pharmaceutical manufacturers, payers, and regulators with evidence of treatment effectiveness beyond traditional clinical endpoints. Quality of Life data types command premium licensing terms due to their direct relevance in oncology and rare disease therapeutic areas, while Subscription monetization models are maturing fastest as enterprise clients seek predictable access to longitudinal patient cohorts. Real-World Evidence applications represent the fastest-expanding segment as sponsors supplement randomized trial data with observational PRO datasets for label expansion and health technology assessment submissions.
The FDA and EMA both enforce stringent validation requirements for PRO instruments used in regulatory submissions, with the FDA's Clinical Outcome Assessment Qualification Program shaping instrument development priorities and market access pathways for data vendors. HIPAA compliance obligations in the United States and GDPR provisions in Europe impose de-identification and consent management standards that directly influence platform architecture and data licensing terms. Stakeholders must monitor evolving regulatory guidance on synthetic data generation and cross-border health data transfers, as these frameworks will determine which monetization models remain commercially viable and which require structural adaptation.
Market Dynamics
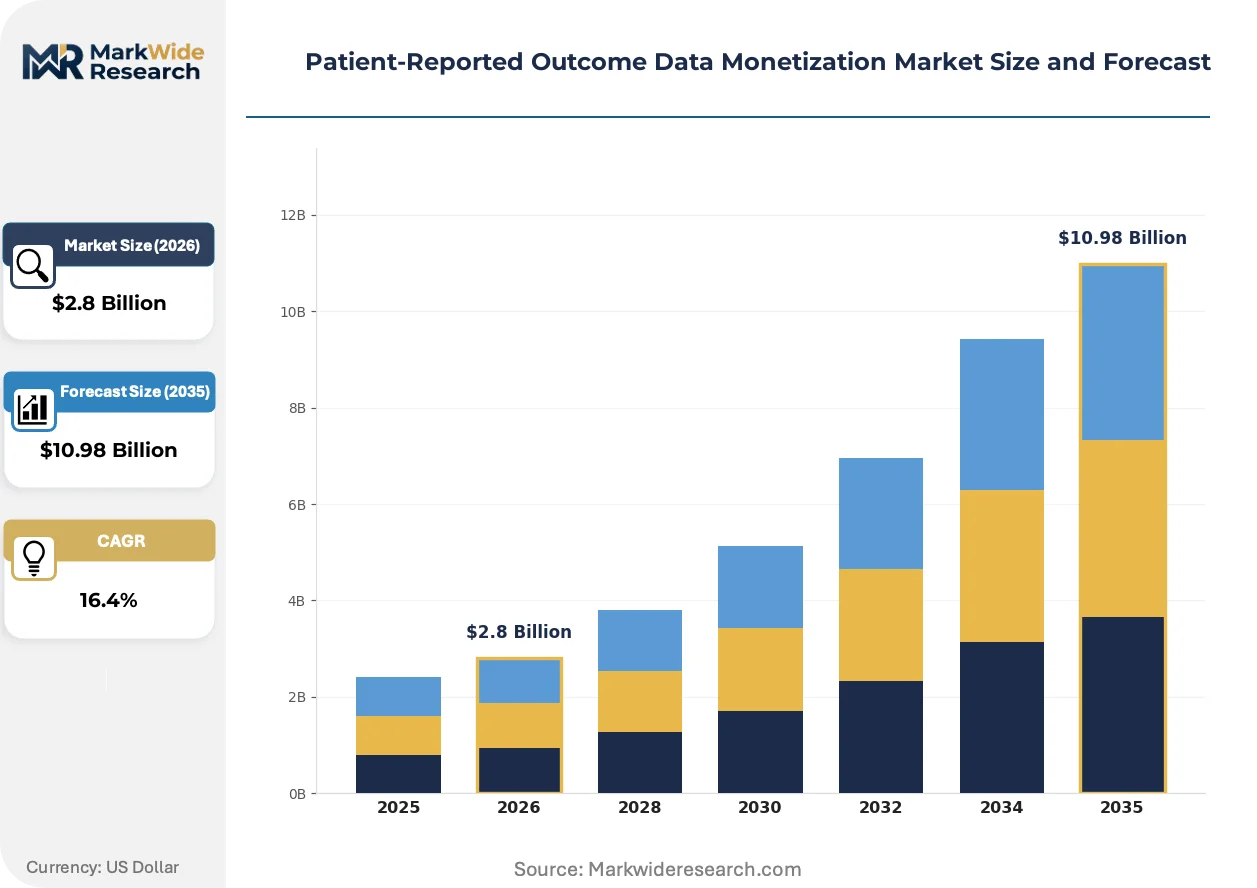
Cloud-native infrastructure consolidation is compressing platform economics while FDA's evolving digital health guidance forces vendors to re-architect validation workflows around real-world evidence standards.
Growth Catalysts
- FDA Clinical Outcome Assessment Qualification Program:The program accelerates instrument validation timelines for PRO platforms, reducing regulatory friction for sponsors submitting digital endpoints. Pharmaceutical manufacturers now prioritize qualified instruments in oncology and rare disease trials.
- Longitudinal patient cohorts:Enterprise clients demand multi-year data subscriptions to track treatment effectiveness across therapeutic areas. Subscription monetization models capture predictable revenue streams from payers and biotech firms.
- Synthetic data generation:Privacy-preserving techniques expand addressable datasets without HIPAA compliance burdens. Vendors license synthetic PRO profiles to AI developers training clinical prediction models.
Market Restraints
- GDPR cross-border transfer restrictions:European data localization mandates fragment global PRO repositories. Vendors must maintain separate infrastructure for EU patient data, duplicating fixed costs.
- De-identification technical limitations:Re-identification risks from genomic-linked PRO datasets constrain licensing terms. Legal teams impose narrower use restrictions, compressing per-record pricing.
- Legacy EHR integration costs:Health system IT departments resist API overhauls required for real-time PRO ingestion. Implementation timelines stretch 18-24 months, delaying platform deployments.
Strategic Opportunities
- Japan's PMDA digital health pathway:The regulator's 2024 guidance on patient-generated data creates first-mover advantages for validated Japanese-language PRO instruments. Local partnerships with academic medical centers anchor market entry.
- AI training data marketplaces:Convergence of federated learning architectures with differential privacy enables new licensing models. Pharmaceutical AI divisions purchase condition-specific PRO corpora for algorithm development.
- Direct-to-patient recruitment channels:Mobile health platforms bypass traditional site-based enrollment, capturing treatment-naive cohorts. Rare disease foundations partner with vendors to accelerate patient identification.
Industry Challenges
- Biostatistician talent scarcity:PRO instrument validation requires specialized psychometric expertise. Competition from pharmaceutical sponsors drives compensation inflation for qualified methodologists.
- Multi-jurisdiction consent management:Divergent HIPAA, GDPR, and emerging state privacy laws complicate unified platform architecture. Engineering teams maintain parallel consent workflows, increasing technical debt.
- Legacy SF-36 instrument licensing:Copyright holders of established questionnaires extract royalties that erode platform margins. Vendors face pressure to develop proprietary instruments or absorb pass-through costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient-Reported Outcome Data Monetization Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Quality of Life, Symptoms Tracking, Treatment Satisfaction, Medication Adherence, Functional Status Monetization Model: Subscription, Licensing, Pay-per-Use, Data Analytics Services, Market Research Reports End User: Pharmaceutical Companies, Medical Device Firms, Health Technology Vendors, Payers, Research Organizations Application: Clinical Trials, Real-World Evidence, Regulatory Submission, Patient Engagement, Health Outcomes Research |
| Companies Covered | IQVIA, Oracle, Microsoft, Salesforce, SAS Institute, SAP, Datavant, HealthVerity, Komodo Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient-Reported Outcome Data Monetization Market Trends and Innovations
Patient-reported outcome platforms are converging with ambient sensing technologies and decentralized trial infrastructure, creating continuous data streams that displace episodic questionnaire administration.
Federated learning architectures are integrating with edge-computing deployments to enable local model training on sensitive PRO datasets. Pharmaceutical sponsors adopt these frameworks to satisfy data residency requirements without sacrificing analytical depth. The technology is integrating privacy-preserving analytics directly into hospital IT environments, compressing the traditional extract-transform-load pipeline.
EMA's updated qualification opinion on digital health technologies is mandating prospective validation studies for PRO instruments used in regulatory submissions. Sponsors must now demonstrate measurement equivalence between electronic and paper administrations. Oncology trials in Europe face the steepest compliance burden, with sponsors extending study timelines to accommodate dual-mode validation.
Biopharma procurement teams are unbundling PRO data licensing from full-service clinical research contracts, creating standalone vendor relationships for real-world evidence. Contract research organizations lose exclusivity over patient data access as sponsors direct-negotiate with platform vendors. This disintermediation is most advanced in the United States, where health technology vendors have built direct sales teams targeting evidence-generation departments.
Patient-Reported Outcome Data Monetization Market Segmentation
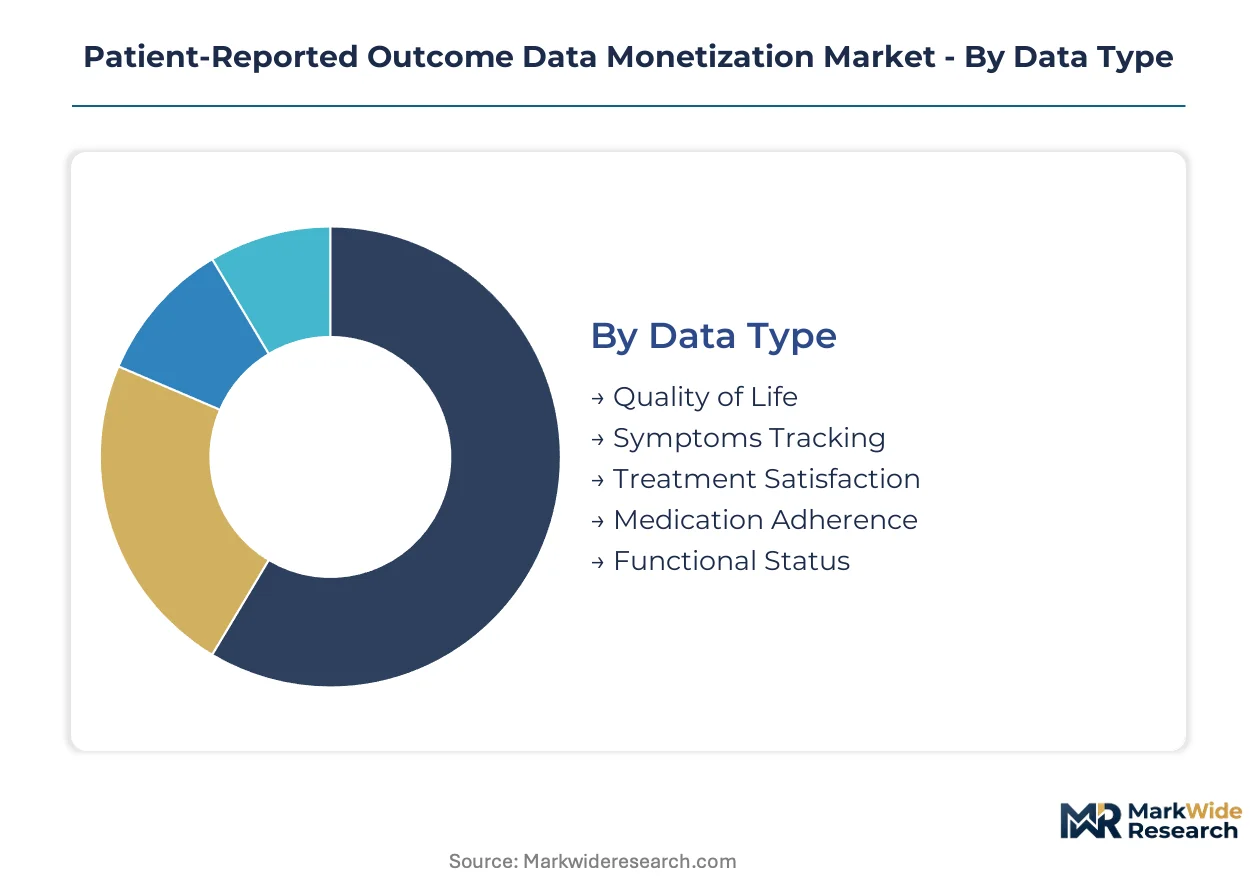
Segmentation in patient-reported outcome data monetization reveals how regulatory validation requirements and commercial use cases reshape platform economics. Pharmaceutical procurement teams unbundle data licensing from full-service contracts, creating distinct purchasing patterns across data types and monetization models.
Data Type:
FDA's Clinical Outcome Assessment Qualification Program imposes tiered validation burdens across data categories, with oncology-linked instruments facing the steepest psychometric requirements.
- Quality of Life:Captures physical, mental, and social functioning through validated instruments like SF-36 and EQ-5D. Oncology and rare disease sponsors in the United States pay premium licensing rates for longitudinal QoL datasets supporting health technology assessment submissions.
- Symptoms Tracking:Records patient-reported adverse events and disease-specific symptom severity via digital diaries. European EMA qualification opinions now mandate prospective validation for electronic symptom instruments used in regulatory submissions.
- Treatment Satisfaction:Measures patient-reported acceptability of therapeutic interventions.
- Medication Adherence:Tracks self-reported compliance with prescribed regimens.
- Functional Status:Assesses physical and cognitive performance capabilities.
Quality of Life sits at the top of the volume ranking, with Symptoms Tracking climbing the fastest.
Monetization Model:
Enterprise procurement patterns favor predictable spend commitments over transactional pricing, though AI training data marketplaces are disrupting traditional licensing structures.
- Subscription:Provides multi-year access to longitudinal patient cohorts with predictable renewal terms. Biotech firms in the United States favor annual subscriptions for real-world evidence pipelines, compressing vendor sales cycles.
- Licensing:Grants rights to specific PRO datasets for defined therapeutic areas or research purposes.
- Pay-per-Use:Charges per-record or per-query for episodic data access.
- Data Analytics Services:Bundles raw PRO data with biostatistical analysis and regulatory documentation.
- Market Research Reports:Delivers synthesized insights across therapeutic categories.
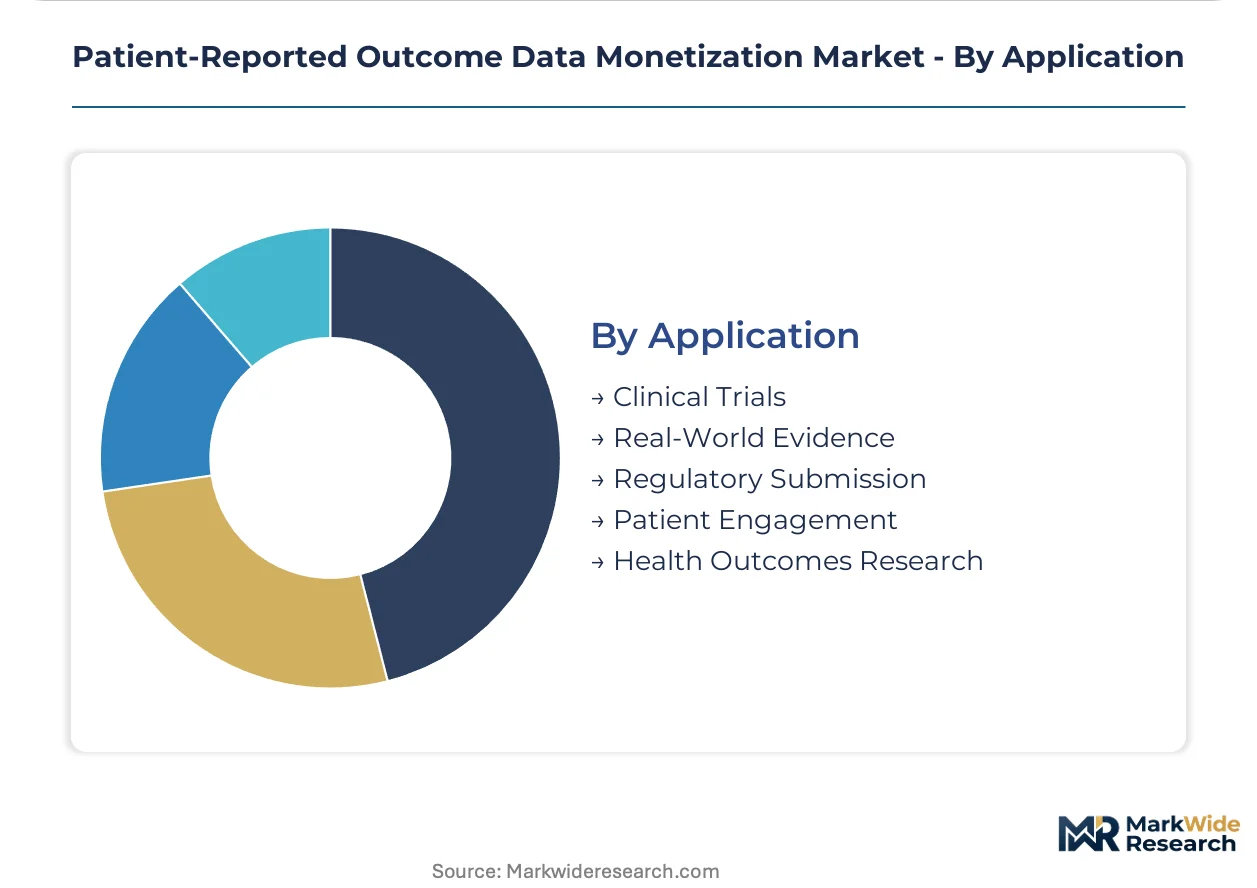
Subscription commands the largest revenue share, with Data Analytics Services expanding most quickly as sponsors seek bundled evidence packages.
End User:
Customer technical maturity determines platform deployment complexity, with health technology vendors requiring API-native architectures and research organizations demanding de-identification guarantees.
- Pharmaceutical Companies:Largest buyer segment, purchasing PRO data for clinical trial endpoints and label expansion. FDA's evolving digital health guidance forces these sponsors to prioritize qualified instruments in oncology programs.
- Medical Device Firms:Leverage patient-reported outcomes for premarket submission and post-market surveillance.
- Health Technology Vendors:Integrate PRO modules into broader digital health platforms.
- Payers:License treatment effectiveness data for formulary and coverage decisions.
- Research Organizations:Access PRO datasets for academic and government-funded studies.
Pharmaceutical Companies anchor demand volume, with Health Technology Vendors gaining share fastest through platform consolidation.
Application:
Use case technical requirements vary sharply, with regulatory submissions demanding instrument qualification and patient engagement programs prioritizing user experience.
- Clinical Trials:Primary revenue driver, requiring FDA-qualified PRO instruments as primary or secondary endpoints. Sponsors extend study timelines to accommodate EMA's dual-mode validation requirements for electronic versus paper administration.
- Real-World Evidence:Fastest-expanding application as sponsors supplement randomized trial data with observational PRO datasets.
- Regulatory Submission:Demands highest data quality standards and complete audit trails.
- Patient Engagement:Focuses on treatment adherence and care coordination.
- Health Outcomes Research:Supports comparative effectiveness and health technology assessment.
Clinical Trials dominate current deployment volume, with Real-World Evidence showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston life sciences corridor anchors PRO data platform development, with Massachusetts General Hospital and Brigham and Women's Hospital generating validated instrument datasets for pharmaceutical licensing.
United States
FDA's Clinical Outcome Assessment Qualification Program drives enterprise procurement of validated PRO instruments in oncology trials. HIPAA compliance mandates shape platform architecture for de-identification and consent management. The Research Triangle Park cluster in North Carolina hosts specialized analytics vendors serving contract research organizations.
Germany
EMA qualification opinions for electronic PRO instruments create validation service demand from sponsors running pan-European trials. GDPR data localization requirements fragment global repositories and duplicate infrastructure costs. The Munich biotech corridor concentrates health technology vendors building German-language instrument libraries.
United Kingdom
NHS digital transformation programs accelerate PRO integration into routine care pathways for real-world evidence generation. The UK Information Commissioner's Office enforces strict health data processing standards under UK GDPR. London's King's Health Partners academic medical center anchors public-private data sharing frameworks.
Japan
PMDA's 2024 guidance on patient-generated data creates first-mover opportunities for validated Japanese-language PRO instruments. METI funding supports digital health platform development for aging population monitoring. The Kanto region around Tokyo concentrates pharmaceutical headquarters seeking local PRO partnerships.
Switzerland
Swissmedic's alignment with EMA digital health standards attracts sponsors seeking streamlined European regulatory pathways. The country's data protection framework permits controlled cross-border health data transfers under adequacy decisions. Basel's pharmaceutical cluster drives demand for treatment-naive patient cohorts in rare disease trials.
Patient-Reported Outcome Data Monetization Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate federated learning architectures with hospital IT environments. The market structure concentrates around three tiers: diversified health technology conglomerates, specialized clinical data analytics firms, and emerging AI training data marketplaces. Two strategic archetypes define competitive positioning — ecosystem orchestrators leveraging existing clinical data infrastructure, and point-solution specialists building proprietary instrument libraries. Technology licensing agreements and M&A activity represent the dominant competitive moves as incumbents acquire differential privacy capabilities.
Among diversified technology providers, IQVIA and Oracle exemplify ecosystem orchestration through clinical data infrastructure dominance. IQVIA occupies a position representing real-world evidence service integration, while Oracle exemplifies database-centric platform architecture competing directly on cloud analytics workflows. Microsoft represents the cloud-native challenger archetype, leveraging Azure infrastructure to displace legacy on-premise PRO systems.
| Leading Market Players |
|---|
| IQVIA |
| Oracle |
| Microsoft |
| Salesforce |
| SAS Institute |
| SAP |
| Datavant |
| HealthVerity |
| Komodo Health |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical sponsors unbundling PRO data licensing from full-service CRO contracts force vendors to absorb copyright royalties for validated instruments like SF-36 and EQ-5D while competing on subscription pricing. This procurement shift compresses platform margins and accelerates cloud-native infrastructure investment to offset fixed-cost duplication across HIPAA and GDPR jurisdictions.
Pricing Analysis
Input-cost pass-through from legacy instrument copyright holders erodes margins for PRO platform vendors, who must either absorb royalty burdens or develop proprietary alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by instrument validation tier—FDA-qualified instruments command licensing premiums, while unvalidated digital diaries face price erosion. Cost compression in the standard tier intensifies because sponsor procurement teams demand predictable multi-year subscription terms. Biotech firms exhibit highest price sensitivity due to constrained evidence-generation budgets, while large pharmaceutical manufacturers prioritize validation pedigree over unit cost.
Supply Chain Analysis
Reverse-logistics flows for patient-reported outcome data center on de-identification and re-consent workflows, where data residency requirements force vendors to maintain parallel infrastructure for cross-border transfers. Supply concentrates in the United States, Germany, and Japan, with each jurisdiction anchoring distinct validation standards and language-specific instrument libraries. Raw material dependencies include psychometric validation expertise, cloud compute capacity, and synthetic data generation algorithms. Single-source vulnerability from biostatistician talent scarcity constrains platform scaling. Distribution runs through direct enterprise sales teams targeting pharmaceutical evidence-generation departments, bypassing traditional CRO intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sponsor procurement teams prioritize FDA-qualified instruments over unvalidated alternatives, elevating vendors with established regulatory track records.
For Market Incumbents: To counter disintermediation by health technology vendors building direct sales teams, IQVIA and Oracle should deepen proprietary instrument libraries through differential privacy acquisitions and anchor cloud-native validation workflows. Channel control over hospital IT integration represents the critical defensive lever. For New Entrants and Emerging Players: Launch via federated learning partnerships with academic medical centers to bypass legacy EHR integration costs. White-space targets include Japanese-language PRO instruments under PMDA's 2024 guidance and AI training data marketplaces for condition-specific corpora. Direct-to-patient mobile recruitment channels offer the most penetrable entry vector. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized clinical data analytics firms possessing qualified instrument portfolios and hospital IT integration capabilities. Long-term viability hinges on regulatory validation moats rather than raw data volume. The signal to watch is EMA dual-mode validation completion rates as an inflection indicator for European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables local model training on HIPAA-sensitive PRO datasets without cross-border transfer. |
| Proprietary Instrument Development | Reduces copyright royalty exposure from legacy SF-36 and EQ-5D licensing holders. |
| Direct-to-Patient Recruitment Channel | Bypasses 18-24 month site-based enrollment timelines for treatment-naive cohort capture. |
| Synthetic Data Generation Capability | Expands addressable datasets for AI developers while preserving patient privacy compliance. |
| Japanese-Language Validation Program | Secures first-mover positioning under PMDA's patient-generated data guidance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical evidence-generation directors, PRO platform product managers, biostatisticians, and health technology procurement officers with secondary validation against FDA qualification program records, EMA digital health guidance documents, ClinicalTrials.gov endpoint specifications, and hospital procurement database filings. Bottom-up patient cohort monetization models and top-down platform revenue estimates were triangulated for consistency.
Comparable-period anchoring used historical PRO data licensing transaction patterns to calibrate growth assumptions across the projection horizon. Segmentation dimensions modeled include data type, monetization model, end-user archetype, and application use case, with therapeutic area regulatory complexity as an industry-specific overlay. CAGRs were derived from sponsor spending trajectory analysis and platform vendor revenue recognition patterns, incorporating synthetic data licensing velocity and subscription renewal rate assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GDPR enforcement escalation or FDA qualification program scope expansion. Forecasts reflect documented assumptions regarding sponsor unbundling velocity and cloud infrastructure cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
India Preclinical CRO Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Atopic Dermatitis Clinical Trials Market