
 Saudi Arabia Neurology Devices Market | 2026-2036
Saudi Arabia Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Neurology Devices Market Outlook
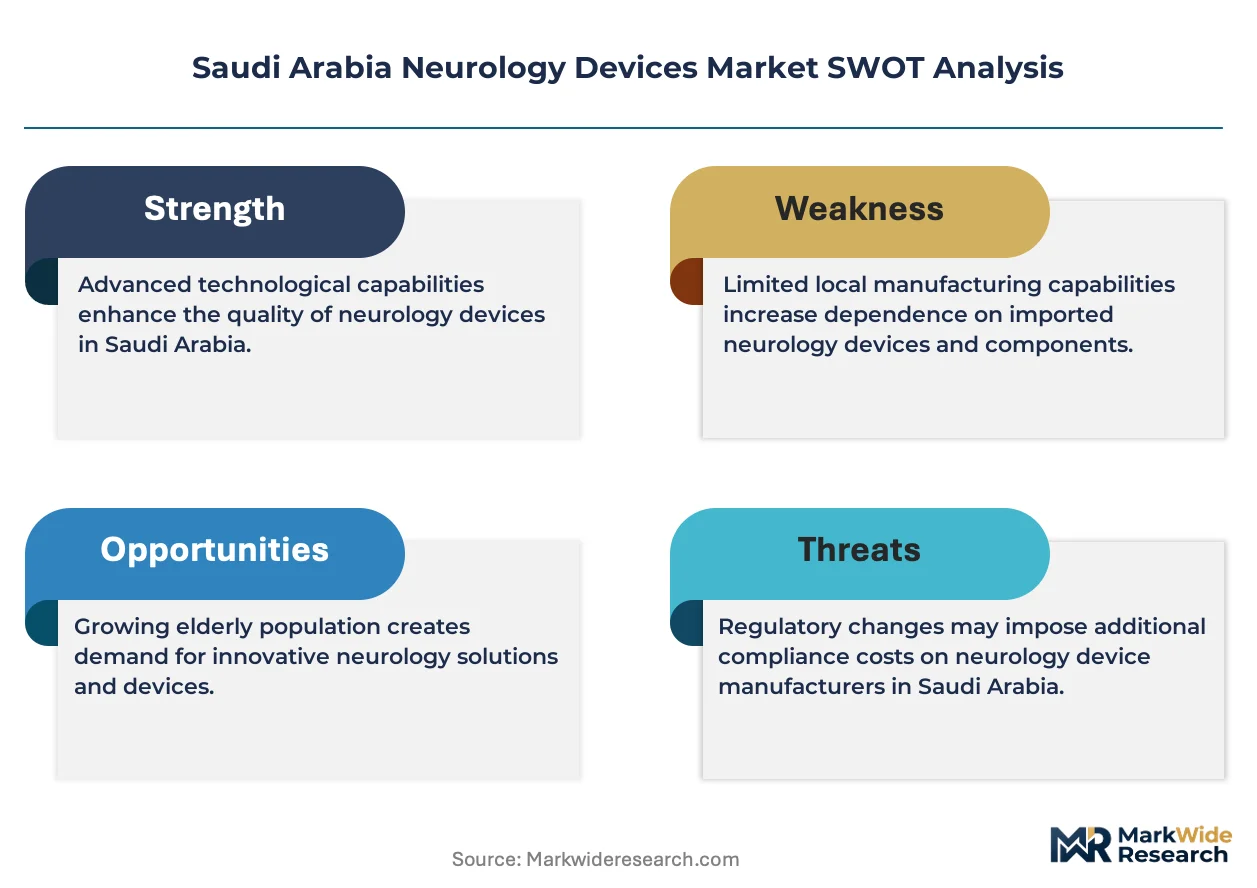
SFDA medical device registration requirements for Class III neurology implants is collapsing the vendor landscape to established multinationals. Medtronic PLC leverages its deep neurostimulation portfolio to sustain preference among Saudi neurosurgical departments. Stryker Corporation anchors the cranial and spinal access segment through integrated navigation platforms. Abbott Laboratories differentiates with proprietary directional lead technology for deep brain stimulation procedures.
Neurology devices encompass instrumented systems for diagnosing, monitoring, and treating disorders of the central and peripheral nervous systems, typically integrating biocompatible electrodes with signal amplification circuits operating at microvolt sensitivity thresholds and software algorithms for artifact rejection. Their primary commercial purpose is to restore neural function, manage refractory symptoms, or generate diagnostic images for surgical planning. Neurostimulation devices command the largest revenue share due to recurring battery replacement cycles and programming service contracts. Imaging technology, particularly 3T MRI with diffusion tensor imaging protocols, represents the fastest-growing capability area as Saudi hospitals build epilepsy surgery and functional neurosurgery programs. Wireless technology adoption lags in implantables but expands rapidly in ambulatory EEG and intraoperative monitoring settings.
SFDA implements risk-based classification aligned with EU MDR principles, requiring clinical evidence for novel neurology devices and mandating post-market surveillance for implantable systems. The country's national health insurance regulator, CCHI, shapes reimbursement access for high-cost neurostimulation therapies through indication-specific coverage policies. Stakeholders must monitor how Saudi Vision 2030 localization mandates for medical device manufacturing alter procurement preferences and partnership requirements for foreign suppliers.
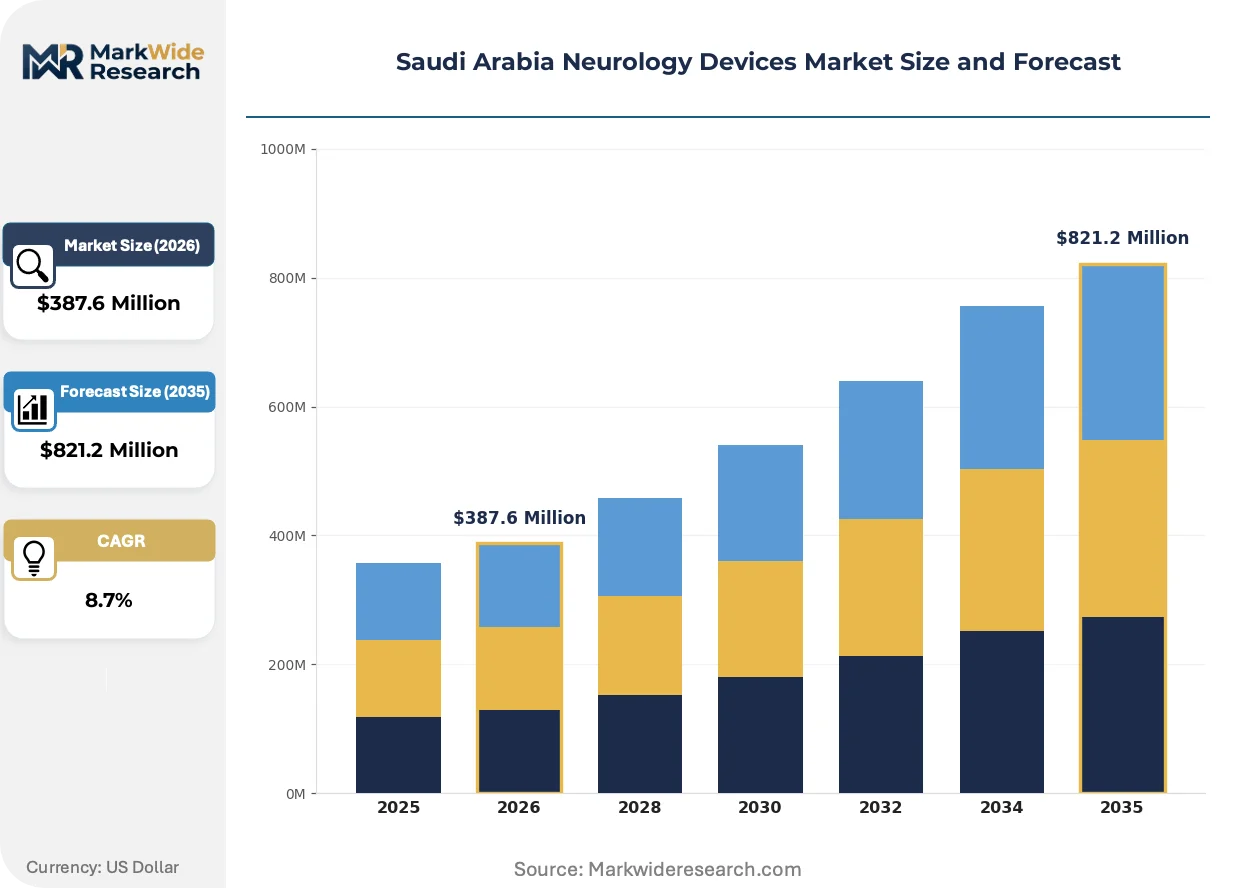
Market Dynamics
SFDA's risk-based classification alignment with EU MDR principles is compressing the vendor landscape for implantable neurostimulators, forcing tertiary hospitals to consolidate procurement around suppliers with established clinical evidence packages and post-market surveillance infrastructure.
Growth Catalysts
- Vision 2030 localization mandates:Domestic manufacturing requirements for medical devices are redirecting foreign supplier partnership strategies toward joint ventures and technology transfer agreements with Saudi entities.
- Deep brain stimulation expansion:King Faisal Specialist Hospital and affiliated neurology departments are building dedicated functional neurosurgery programs, generating demand for directional lead systems and intraoperative navigation platforms.
- CCHI indication-specific coverage:The national health insurance regulator's reimbursement policies for refractory epilepsy and movement disorders are expanding addressable patient populations for neurostimulation therapies.
Market Restraints
- Implantable battery supply concentration:Lithium-ion cell production for neurostimulators remains concentrated among a limited set of qualified suppliers, exposing replacement cycle revenue to input volatility.
- SFDA clinical evidence requirements:Novel neurology devices face extended pre-market approval timelines due to mandatory local clinical data generation, delaying commercialization for emerging technologies.
- Wireless telemetry limitations:Implantable wireless communication protocols face technical constraints around power consumption and signal integrity that restrict ambulatory monitoring capabilities.
Strategic Opportunities
- Jeddah private hospital corridor:Underpenetrated ambulatory EEG and intraoperative monitoring demand among private neurosurgical centers offers expansion potential for wireless diagnostic platforms.
- 3T MRI with diffusion tensor imaging:Convergence of high-field imaging with tractography software is enabling pre-surgical planning for epilepsy resections, creating demand for integrated navigation ecosystems.
- SFDA post-market surveillance infrastructure:Regulatory mandates for implantable device tracking are opening service contract opportunities for remote monitoring and predictive battery replacement scheduling.
Industry Challenges
- Functional neurosurgery talent scarcity:Deep brain stimulation programming and intraoperative neurophysiology monitoring require specialized training pipelines that Saudi academic medical centers are still developing.
- Legacy EEG system integration:Tertiary hospitals face technical friction when connecting new wireless ambulatory monitors to existing hospital information systems and archival databases.
- SFDA quality management system certification:Foreign manufacturers must establish local authorized representatives and maintain ISO 13485-compliant documentation, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Neurology Devices Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, EEG Devices, MRI Machines, CT Scanners Technology: Wireless Technology, Digital Signal Processing, Imaging Technology, Microelectromechanical Systems End User: Hospitals, Specialty Clinics, Research Institutions, Rehabilitation Centers Application: Chronic Pain Management, Neurological Disorders, Diagnostic Imaging, Surgical Procedures |
| Companies Covered | Stryker Corporation, Medtronic PLC, Abbott Laboratories, Siemens Healthineers, Nihon Kohden Corporation, Johnson & Johnson, Attieh Medico Ltd, Boston Scientific, Smith & Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Neurology Devices Market Strategic Shifts
Directional lead technology and closed-loop neurostimulation algorithms are redefining therapeutic precision in movement disorder management, while wireless telemetry expands from diagnostic into therapeutic monitoring applications.
Directional deep brain stimulation leads with independent current steering are supplanting traditional cylindrical electrodes in Saudi tertiary hospitals. King Faisal Specialist Hospital's functional neurosurgery unit has adopted these systems for Parkinson's disease and dystonia cases. The technology is compressing programming time and reducing stimulation-induced side effects that previously limited therapeutic windows.
SFDA's implementation of EU MDR-aligned post-market surveillance requirements is mandating systematic implantable device registries and adverse event reporting from all Saudi hospitals. Manufacturers must now maintain local quality management systems and authorized representatives. Implantable neurostimulator suppliers face the most significant compliance burden, with tertiary centers required to submit longitudinal outcome data.
Service unbundling is separating device sales from programming and battery replacement contracts in Saudi procurement. Tertiary hospitals increasingly negotiate standalone technical service agreements with neurostimulation specialists. This pattern concentrates in Riyadh's academic medical center cluster, where value-based purchasing frameworks are gaining traction among CCHI-contracted facilities.
Saudi Arabia Neurology Devices Market Segmentation
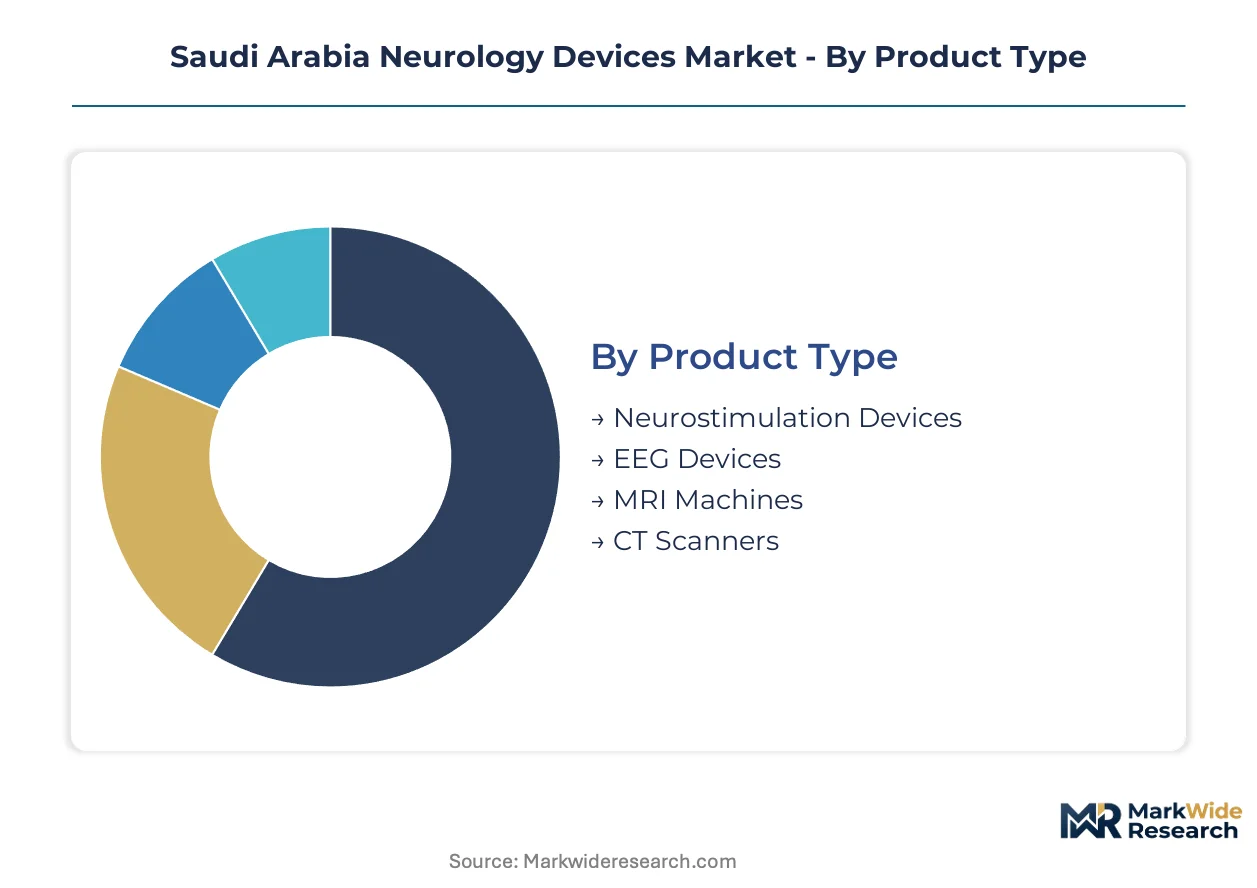
Segmentation in Saudi Arabia's neurology devices market reveals distinct margin architectures across product categories, with procurement decisions increasingly shaped by SFDA risk classification tiers and CCHI reimbursement pathways. Understanding where value concentrates helps suppliers prioritize regulatory investment and channel strategy.
Product Type:
Margin pools concentrate in implantable systems with recurring service revenue streams, while capital imaging equipment generates upfront sales with lower lifetime value capture.
- Neurostimulation Devices:Implantable pulse generators with biocompatible electrodes and programmable stimulation parameters command premium pricing through battery replacement cycles and programming service contracts. King Faisal Specialist Hospital's functional neurosurgery program anchors demand for deep brain stimulation systems, with CCHI's movement disorder coverage policies expanding addressable patient volumes.
- EEG Devices:Electroencephalography systems integrate signal amplification circuits operating at microvolt sensitivity with software algorithms for artifact rejection. Riyadh's tertiary hospital cluster drives procurement for high-density array systems, though legacy system integration creates technical friction during hospital information system upgrades.
- MRI Machines:High-field imaging platforms with neurology-optimized coil arrays.
- CT Scanners:Computed tomography systems for emergency neurology and stroke protocols.
Neurostimulation Devices hold installed capacity. EEG Devices is rotating up the share rankings.
Technology:
Technology selection in Saudi facilities tracks regulatory maturity and local technical support availability, with established digital platforms preferred over novel wireless protocols.
- Imaging Technology:3T MRI with diffusion tensor imaging protocols and tractography software enables pre-surgical planning for epilepsy resections. King Faisal Specialist Hospital and Jeddah's private hospital corridor are building integrated navigation ecosystems around these capabilities, with SFDA's emphasis on clinical evidence accelerating adoption of validated platforms.
- Digital Signal Processing:Real-time artifact rejection algorithms and cloud-based EEG analysis pipelines. Tertiary hospitals in Riyadh concentrate demand for diagnostic platforms with automated seizure detection, driven by neurologist workforce constraints and overnight monitoring requirements.
- Wireless Technology:Ambulatory EEG and intraoperative monitoring with telemetry capabilities.
- Microelectromechanical Systems:Miniaturized sensors for implantable neural interfaces.
Imaging Technology holds installed capacity. Wireless Technology is rotating up the share rankings.
End User:
Customer type determines procurement authority and contract structure, with centralized purchasing at academic medical centers contrasting with decentralized decision-making in private facilities.
- Hospitals:Tertiary academic centers with neurosurgery departments and comprehensive stroke centers. The King Faisal Specialist Hospital cluster in Riyadh and private hospital corridor in Jeddah concentrate high-value procurement, with SFDA Class III device registration requirements favoring suppliers with established local quality management systems.
- Specialty Clinics:Outpatient neurology practices with diagnostic and therapeutic capabilities. These facilities in Riyadh and Jeddah are expanding ambulatory EEG services, creating demand for wireless diagnostic platforms with simplified technical service requirements.
- Research Institutions:Academic medical centers with clinical trial infrastructure.
- Rehabilitation Centers:Post-acute facilities for neurostimulation programming and patient monitoring.
Hospitals hold installed capacity. Specialty Clinics is rotating up the share rankings.
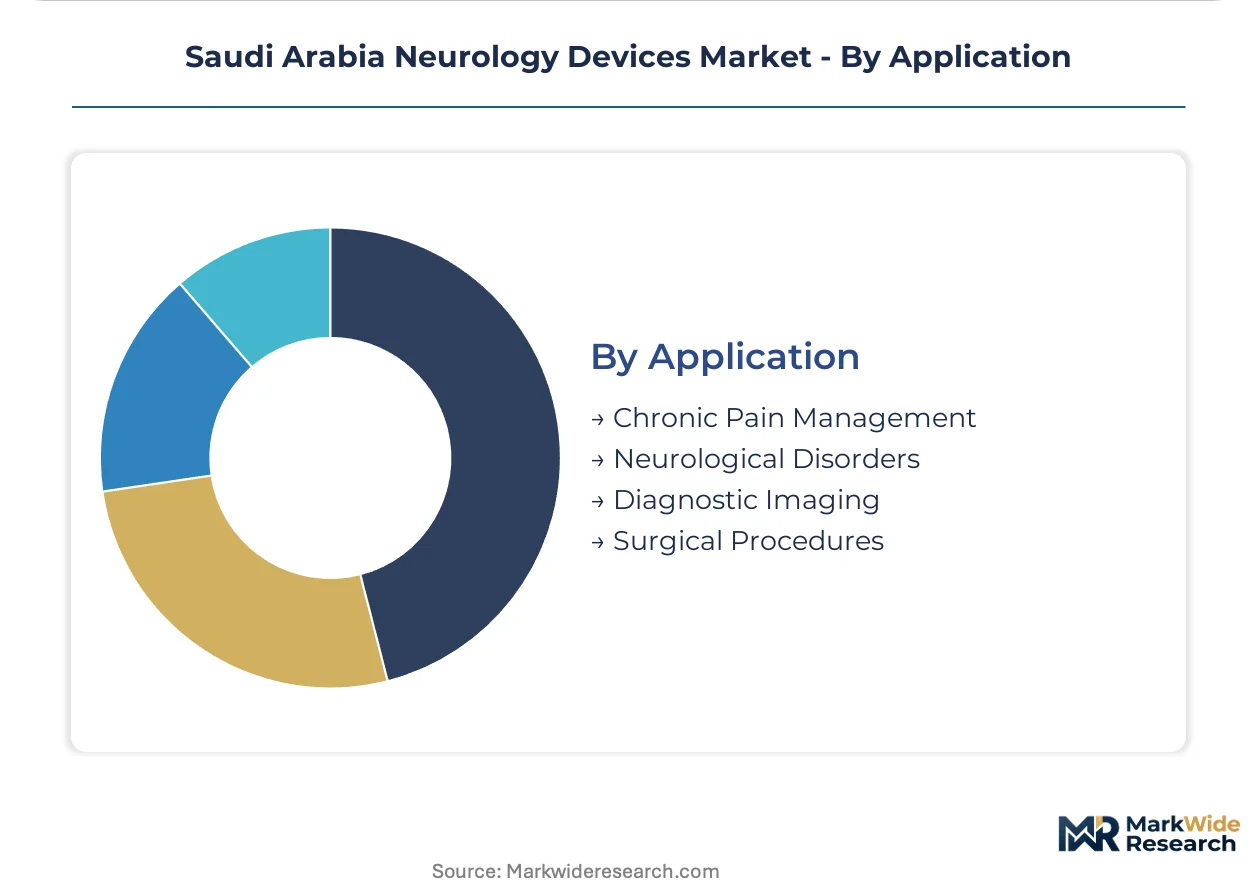
Application:
Application focus shapes product configuration and regulatory pathway, with therapeutic indications requiring more extensive clinical evidence packages than diagnostic workflows.
- Chronic Pain Management:Spinal cord stimulation and peripheral nerve stimulation systems with rechargeable or primary cell power sources. CCHI's indication-specific coverage policies for refractory pain conditions are expanding reimbursement access, though battery supply concentration among qualified lithium-ion cell suppliers creates input volatility.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease, dystonia, and emerging psychiatric indications. King Faisal Specialist Hospital's dedicated functional neurosurgery program anchors demand for directional lead systems, with service unbundling trends separating device sales from programming contracts.
- Diagnostic Imaging:Structural and functional neuroimaging for surgical planning.
- Surgical Procedures:Intraoperative monitoring and navigation platforms.
Chronic Pain Management holds installed capacity. Neurological Disorders is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration in Saudi Arabia's neurology devices market clusters around tertiary hospital neurology departments and specialized functional neurosurgery programs, with procurement authority residing in Riyadh's academic medical centers and Jeddah's private hospital corridor.
Riyadh
The King Faisal Specialist Hospital cluster anchors demand for deep brain stimulation systems and intraoperative navigation platforms. SFDA's Class III device registration requirements favor suppliers with established local quality management systems and post-market surveillance infrastructure. King Faisal Specialist Hospital's dedicated functional neurosurgery program generates concentrated procurement for directional lead technology and integrated imaging ecosystems.
Eastern Province
Aramco-affiliated healthcare facilities and Saudi Aramco Medical Services Organization drive demand for occupational neurology and neurorehabilitation devices. CCHI indication-specific coverage policies for refractory epilepsy expand addressable patient populations across the region's comprehensive stroke centers. Dammam's tertiary hospital cluster concentrates procurement for high-field MRI platforms with neurology-optimized coil arrays.
Western Region
Jeddah's private hospital corridor presents underpenetrated demand for ambulatory EEG and wireless diagnostic platforms among outpatient neurosurgical centers. The city's medical tourism infrastructure attracts patients from across Africa and South Asia, expanding the addressable market for neurostimulation therapies. Private facilities here negotiate standalone technical service agreements separate from device procurement.
NEOM Northwest
The giga-project's healthcare masterplan incorporates predictive neurology and AI-enabled diagnostic imaging as foundational capabilities. Vision 2030 localization mandates redirect foreign supplier partnership strategies toward joint ventures with Saudi entities for regional distribution and technical support. NEOM's planned medical city targets integration of closed-loop neurostimulation and remote monitoring infrastructure.
Saudi Arabia Neurology Devices Market Competitive Environment
Player mix skews toward multinational medical technology conglomerates with deep neurostimulation portfolios and established SFDA registration pathways. Market structure concentrates procurement decisions around suppliers possessing integrated navigation platforms, biocompatible electrode manufacturing capabilities, and local authorized representative infrastructure. Strategic archetypes include full-stack neurostimulation specialists, imaging-integrated navigation providers, and regional distribution partners with technical service capabilities. Dominant competitive moves encompass technology transfer agreements under Vision 2030 localization mandates and service unbundling that separates device sales from programming contracts.
Among US-based medical technology conglomerates, Medtronic PLC, Stryker Corporation, and Abbott Laboratories exemplify the archetype of full-stack neurostimulation specialists with directional lead capabilities and established clinical evidence packages. These entities occupy positions shaped by SFDA's EU MDR-aligned risk classification, which compresses the vendor landscape for implantable systems toward established multinationals with post-market surveillance infrastructure. Medtronic represents the archetype of deep neurostimulation portfolio breadth, Stryker anchors the cranial and spinal access segment through integrated platform positioning, and Abbott exemplifies differentiation through proprietary electrode technology.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic PLC |
| Abbott Laboratories |
| Siemens Healthineers |
| Nihon Kohden Corporation |
| Johnson & Johnson |
| Attieh Medico Ltd |
| Boston Scientific |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
Battery cell manufacturing scale economies in neurostimulator production concentrate procurement leverage among qualified lithium-ion suppliers, compressing margin capture for device manufacturers while elevating price floors for replacement cycle revenue streams across Saudi tertiary hospitals.
Pricing Analysis
Cost-plus contracts with lithium-ion cell indexation dominate neurostimulator procurement agreements between Saudi hospitals and multinational suppliers. Three-tier pricing structure across premium directional-lead systems, standard cylindrical electrodes, and economy-tier diagnostic platforms differentiates by CCHI reimbursement tier and SFDA certification level. Pricing pressure stems from Vision 2030 localization mandates requiring joint venture cost absorption. Private hospital corridor buyers in Jeddah exhibit highest price sensitivity, while King Faisal Specialist Hospital's academic procurement maintains lowest sensitivity due to bundled service contract structures.
Supply Chain Analysis
Inbound logistics costs through Jeddah Islamic Port congestion and Red Sea container availability constraints elevate landed costs for implantable neurostimulator components. Manufacturing concentration centers on Ireland, Switzerland, and Costa Rica for pulse generators, with Malaysia and Singapore anchoring electrode assembly. Raw material dependencies span medical-grade titanium, platinum-iridium alloys, and hermetic ceramic feedthroughs. Single-source vulnerability concentrates in qualified battery cell suppliers. Distribution runs through authorized representative networks with local quality management system certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in neurostimulator programming and predictive battery replacement scheduling are expanding faster than hardware sales, creating recurring-revenue layers that outpace capital equipment procurement cycles across Saudi tertiary centers.
For Market Incumbents: Shield market position by deepening backward integration into battery cell supply through captive sourcing agreements with qualified suppliers, and accelerate ISO 13485-certified local authorized representative infrastructure to preempt SFDA compliance barriers for emerging entrants. The threat of directional lead technology commoditization from second-tier suppliers demands certification investment as the priority defensive lever. For New Entrants and Emerging Players: Remote monitoring platform under-service among Jeddah private hospital corridor facilities creates white-space expansion potential for wireless diagnostic platforms with simplified technical service requirements. Target ambulatory EEG and intraoperative monitoring applications where legacy system integration friction delays incumbent refresh cycles. A software-first go-to-market angle with cloud-based seizure detection algorithms bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among neurostimulation specialists with established programming service contracts and battery replacement scheduling infrastructure. Long-term viability over a multi-year horizon favors acquisition targets with CCHI indication-specific coverage alignment and post-market surveillance registry participation. The signal to watch is SFDA joint venture approval velocity under Vision 2030 localization mandates as inflection indicator for partnership-driven market access.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Authorized Representative Establishment | Local quality management system certification accelerates Class III device registration timelines for implantable neurostimulators. |
| Directional Lead Technology Licensing | Proprietary electrode design access differentiates positioning in King Faisal Specialist Hospital functional neurosurgery procurement. |
| Remote Monitoring Platform Development | Cloud-based seizure detection addresses neurologist workforce constraints in Riyadh tertiary hospital overnight monitoring workflows. |
| CCHI Reimbursement Strategy Alignment | Indication-specific coverage expansion for refractory epilepsy and movement disorders widens addressable patient populations. |
| Vision 2030 Joint Venture Formation | Technology transfer agreements with Saudi entities satisfy localization mandates and secure preferential procurement positioning. |
Study Parameters
Initial hypotheses were tested against primary input from functional neurosurgeons, hospital biomedical engineers, SFDA regulatory affairs specialists, and GPO contracts managers, then refined through secondary validation against hospital procurement databases, SFDA medical device registration filings, CCHI coverage policy documents, and EU MDR implementation guidance. Bottom-up demand modeling from tertiary hospital installed base data triangulated with top-down market sizing from neurostimulator shipment records.
Variance decomposition across product type, technology platform, end-user facility tier, and therapeutic application segments structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves for neurostimulation adoption and replacement cycle velocity, with inputs from lithium-ion cell supply constraints and CCHI reimbursement expansion schedules.
Material uncertainties — SFDA regulatory pathway revisions, CCHI indication coverage delistings, and Red Sea logistics disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about Vision 2030 localization enforcement intensity and functional neurosurgery training pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Transcranial Doppler Market
Neurology
Tourette Syndrome Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
India Neurology Devices Market
Neurology
Status Epilepticus Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Neurological Biomarkers Market
Neurology
Cluster Headache Syndrome Market
Neurology
CNS Treatment and Therapy Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Neuroprotection Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Intracranial Aneurysm Market
Neurology
Narcolepsy Treatment Market
Neurology
China Neurology Devices Market
Neurology
Diabetic Neuropathy Market