
 2,4-Dichlorophenoxyacetic Market | 2026-2036
2,4-Dichlorophenoxyacetic Market Size, Share, and Industry Trends Forecast 2026-2036
2,4-Dichlorophenoxyacetic Market Analytics
China is fragmenting its 2,4-Dichlorophenoxyacetic acid manufacturing base across Jiangsu and Anhui provinces. Anhui Xinglong Chemical leverages captive chlorophenol feedstock to sustain cost leadership in technical-grade output. Nufarm anchors Australasian distribution through its established agrochemical channel infrastructure. Corteva Agriscience differentiates via proprietary ester formulations that navigate drift-mitigation standards in North American row-crop markets.
2,4-Dichlorophenoxyacetic acid is a synthetic auxin herbicide with the chemical formula C8H6Cl2O3, manufactured through chlorination of phenol followed by etherification with chloroacetic acid, and functions as a selective broadleaf weed control agent in monocot crops. Liquid formulations dominate volume consumption due to compatibility with aerial and ground-based spray equipment across large-scale farming operations. The agriculture application segment leads value generation, while forestry represents a concentrated margin pool tied to plantation management contracts. Granule formulations occupy a niche in precision horticulture where calibrated dosing limits off-target movement.
EPA registration requirements under FIFRA govern product composition and labeling in the United States, while REACH and EU Pesticides Regulation 1107/2009 restrict active substance approval timelines and co-formulant selection across Europe. China's MEE enforces emission caps on chlorophenol intermediate production that reshape manufacturing cost structures. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and secure multi-region market access.
Market Dynamics
Drift-mitigation mandates across North American row-crop jurisdictions are forcing formulation chemistry toward low-volatile ester variants, compressing legacy acid-based product viability and rewarding proprietary adjuvant investments.
Growth Catalysts
- Herbicide resistance management protocols:Integrated weed control programs in Brazilian soybean operations sustain 2,4-D rotation demand as glyphosate-tolerant weed populations expand.
- US EPA FIFRA registration pathways:Streamlined data requirements for low-volatile ester formulations accelerate product renewal timelines and reduce regulatory hold-up costs.
- Jiangsu-Anhui manufacturing corridor:Chlorophenol feedstock concentration in eastern China sustains technical-grade cost structures against European and North American import competition.
Market Restraints
- EU REACH authorization delays:Active substance renewal timelines under Regulation 1107/2009 extend commercial uncertainty for ester formulations in European cereal applications.
- Chlorophenol intermediate supply concentration:Three coastal Chinese provinces control over 80% of global feedstock output, exposing formulators to emission-cap volatility under MEE enforcement.
- Amino acid herbicide substitution:Glufosinate-ammonium and dicamba formulations capture share in broadleaf-resistant soybean systems, constraining 2,4-D volume expansion in premium crop protection budgets.
Strategic Opportunities
- Precision horticulture granule penetration:Calibrated dosing systems in California and Florida specialty crop operations open margin pools beyond commodity row-crop commoditization.
- EU F-Gas Regulation compliance services:Formulation advisory and drift-buffer modeling create service revenue attachments as co-formulant restrictions tighten under ECHA guidance.
- Drone-based aerial application convergence:Ultralow-volume spray systems paired with real-time wind monitoring reduce buffer zone requirements and unlock previously restricted acreage in Australian wheat belts.
Industry Challenges
- Formulation chemist scarcity:Expertise in ester stability and adjuvant compatibility concentrates among retiring technical staff at legacy agrochemical operations, constraining R&D pipeline velocity.
- Multi-jurisdiction label harmonization:Divergent drift-mitigation buffer requirements between EPA, PMRA, and APVMA registration systems force redundant field trial investments and delay coordinated product launches.
- Legacy equipment incompatibility:Existing ground sprayer fleets in Argentine Pampas operations lack precision nozzles required for new low-volatile formulations, creating adoption friction despite regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2,4-Dichlorophenoxyacetic Market |
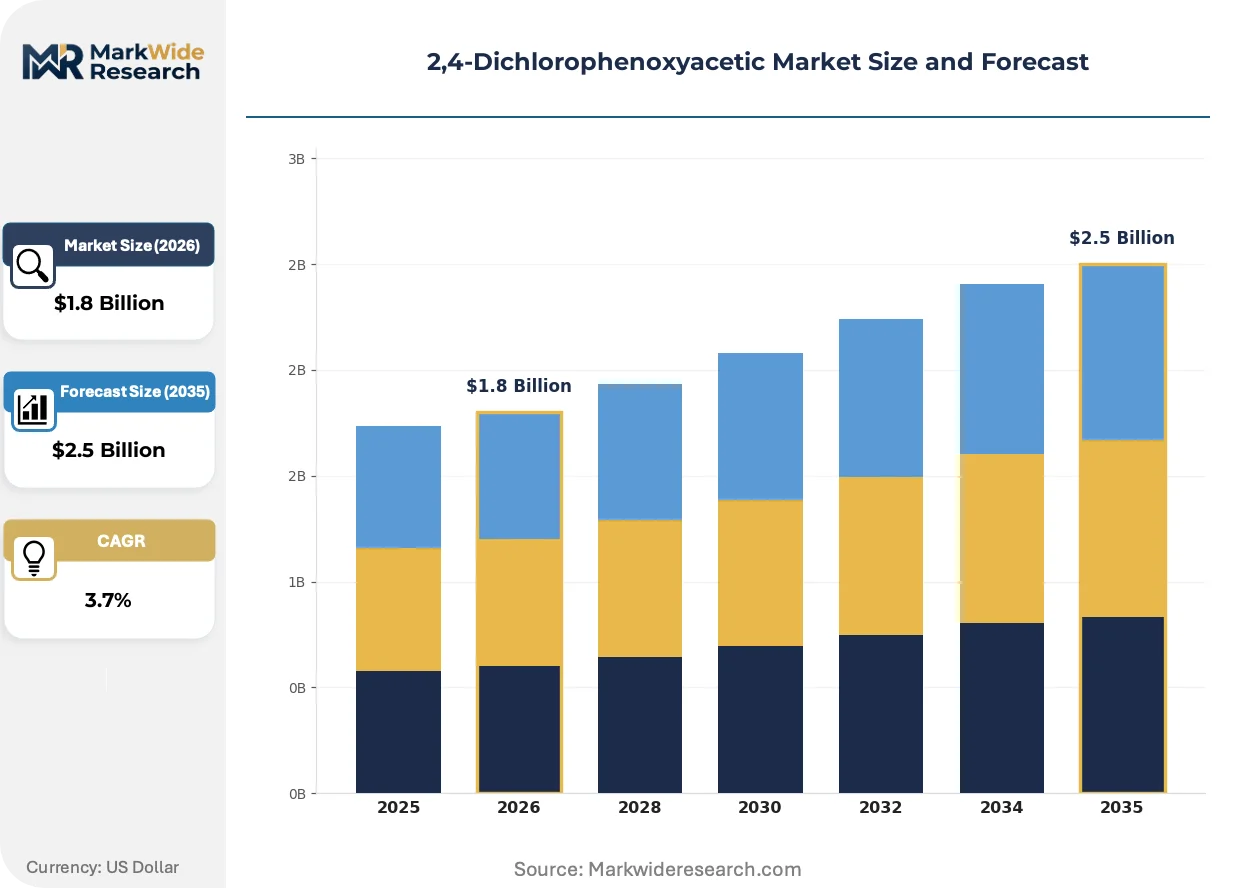
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides Application: Agriculture, Horticulture, Forestry, Landscaping Formulation: Granules, Liquids, Tablets, Powders Sales Channel: Direct Sales, Distributors, Online Retailers, Agricultural Stores |
| Companies Covered | Anhui Xinglong Chemical, Anhui Huaxing Chemical, Jiangsu Yongtaifeng Crop Science, Mesa Tech International, Jiangsu Changfeng Agrochemical, Nufarm, Corteva Agriscience, FMC Corporation, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2,4-Dichlorophenoxyacetic Market Evolving Landscape
Formulation chemistry is pivoting toward volatility reduction as the primary competitive axis, with adjuvant innovation and application technology converging to preserve market access under tightening environmental exposure limits.
Choline salt and 2,4-D ester formulations is hybridizing with proprietary drift-reduction adjuvants to meet EPA volatility criteria. Large-scale Midwest corn operations are adopting these variants at replacement-cycle pace as county-level restrictions on traditional amine salts proliferate. The technology is hybridizing product portfolios toward premium-positioned offerings that command formulation-service bundled pricing.
REACH candidate list expansion under ECHA guidance is reclassifying chlorophenol intermediates as substances of very high concern. This industrial consequence forces European formulators to audit supply chains and accelerate alternative feedstock qualification. Cereal herbicide portfolios in France and Germany face the most acute timeline pressure, with several manufacturers advancing bio-based precursor research to preempt authorization withdrawal.
After-sales service unbundling is separating application advisory from product supply in Brazilian distributor relationships. Large soybean cooperatives in Mato Grosso now contract independent agronomic consultancies for drift-buffer planning rather than relying on manufacturer field staff. This pattern is most visible in South American markets where buyer scale permits dedicated procurement functions and third-party certification of spray contractor compliance.
2,4-Dichlorophenoxyacetic Market Segmentation
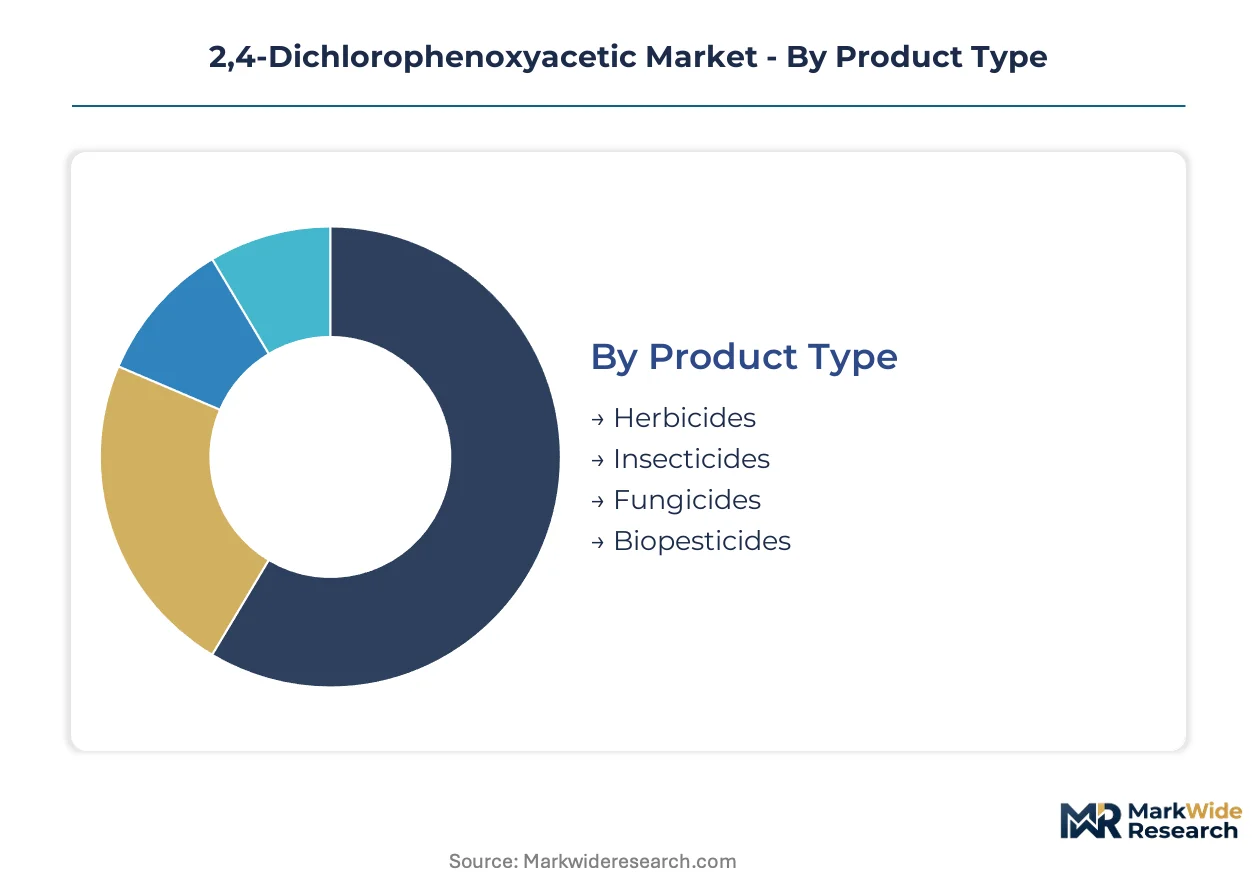
Segmentation in the 2,4-Dichlorophenoxyacetic market reveals divergent margin structures across formulation chemistry and application intensity. Product-type stratification separates commodity technical-grade supply from proprietary ester formulations with drift-mitigation premiums. Channel configuration determines whether manufacturers capture service revenue or surrender margin to distributor intermediaries.
Product Type:
Application intensity and regulatory tolerance separate commodity actives from specialty formulations with differentiated efficacy profiles.
- Herbicides:2,4-D acid and ester variants dominate volume consumption as selective broadleaf control agents in monocot cereal and corn systems. Brazilian soybean operations and US corn belt jurisdictions sustain rotation demand amid glyphosate resistance pressure.
- Insecticides:Pyrethroid and neonicotinoid combinations with 2,4-D co-formulations serve integrated pest management protocols in Australian wheat belts. Regulatory scrutiny on pollinator toxicity constrains label expansion in EU member states.
- Fungicides:Triazole-strobilurin blends occupy preventive spray schedules in humid North American growing regions. Resistance management protocols limit single-active dependency and sustain tank-mix compatibility requirements.
- Biopesticides:Microbial and biochemical alternatives capture organic-certified acreage in California specialty crop districts. Efficacy variability against established broadleaf populations restricts penetration in conventional row-crop systems.
Herbicides command the established base. The steepest expansion runs through biopesticides.
Application:
End-use concentration determines formulation specifications, with aerial spray compatibility and buffer zone requirements driving chemistry selection.
- Agriculture:Large-scale cereal and oilseed operations in Brazil, the United States, and Australia absorb liquid ester formulations at replacement-cycle pace. Drift-mitigation mandates in EPA-registered counties accelerate low-volatile product conversion.
- Horticulture:Precision granule applications in Florida citrus and California nut orchards limit off-target movement through calibrated dosing systems. Premium pricing reflects compliance documentation and contractor certification overhead.
- Forestry:Plantation management contracts in Chile and New Zealand sustain concentrated margin pools for aerial application services. Eucalyptus and radiata pine establishment programs generate recurring volume commitments.
- Landscaping:Municipal and golf course maintenance in US Sun Belt states consumes amine salt formulations for turfgrass broadleaf control. Seasonal demand concentration creates inventory management complexity for distributor networks.
Agriculture commands the established base. Forestry shows the steepest margin concentration per treated hectare.
Formulation:
Physical state dictates equipment compatibility, with spray system convergence favoring liquid chemistry over solid alternatives.
- Liquids:Emulsifiable concentrates and soluble liquids integrate with ground and aerial spray infrastructure across mechanized farming operations. Choline salt and low-volatile ester variants meet EPA volatility criteria in drift-sensitive counties.
- Granules:Calibrated-release formulations serve precision horticulture where root-zone placement limits environmental exposure. Equipment specialization in tree nut and vine crops sustains niche pricing.
- Tablets:Pre-measured dosing units simplify smallholder application in fragmented landholding structures. Dissolution rate variability constrains adoption in large-scale mechanized systems.
- Powders:Wettable powders persist in cost-sensitive markets with legacy mixing equipment. Inhalation exposure concerns and dust containment requirements limit expansion in regulated jurisdictions.
Liquids command the established base. Granules climb the fastest through precision horticulture penetration.
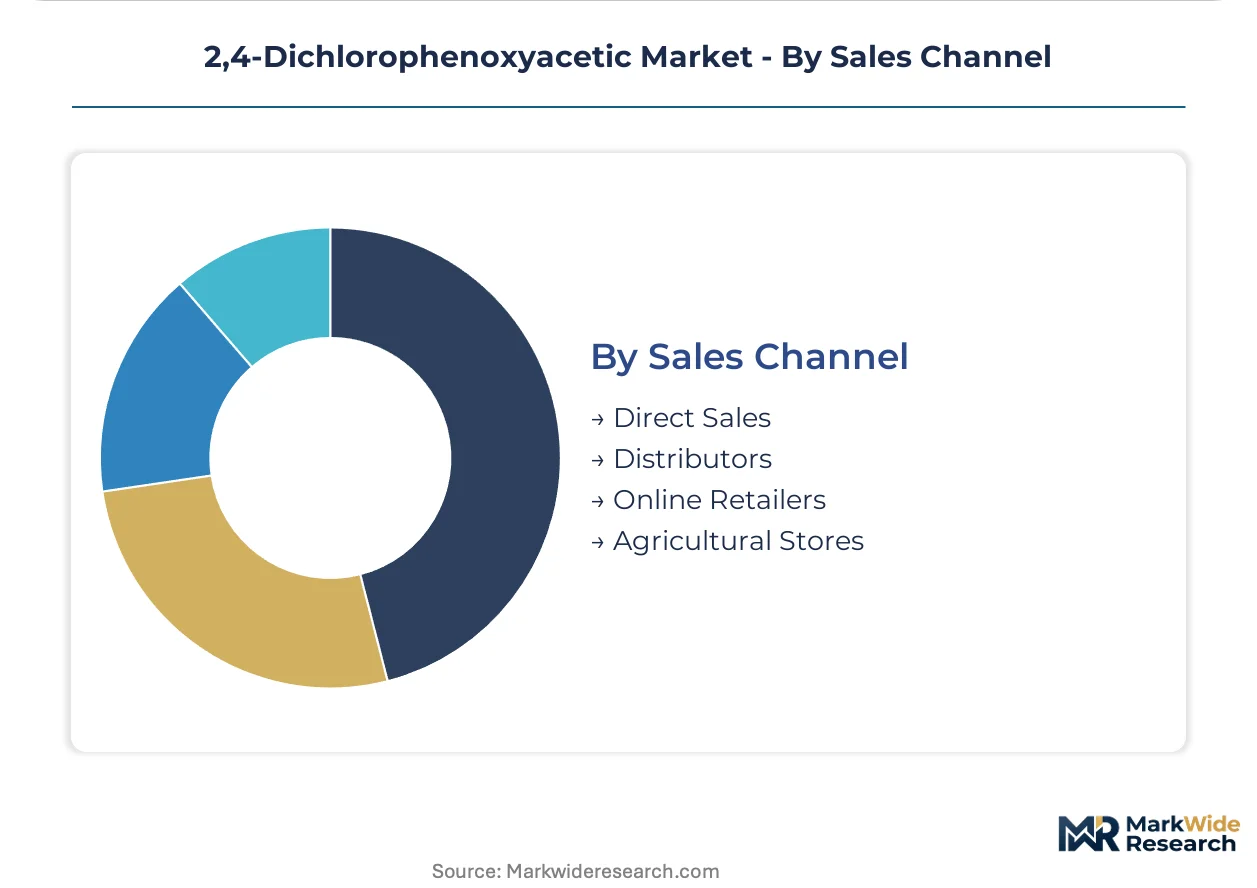
Sales Channel:
Channel structure determines manufacturer proximity to application decisions and capture of service revenue attachments.
- Distributors:Regional agrochemical wholesalers in Brazil's Mato Grosso and the US Midwest aggregate procurement for cooperative buying groups. Inventory financing and credit extension sustain intermediary relevance despite margin compression.
- Direct Sales:Large soybean cooperatives and integrated farming enterprises in Argentina's Pampas negotiate volume contracts bypassing distributor markups. Technical advisory services bundle with supply agreements to defend supplier relationships.
- Online Retailers:E-commerce platforms capture smallholder and hobby farmer demand in Australian and North American markets. Regulatory compliance documentation gaps constrain professional grower adoption.
- Agricultural Stores:Independent retail networks in India's Punjab and Haryana states serve tractor-owner cultivators with immediate availability requirements. Product authenticity verification challenges persist in fragmented procurement environments.
Distributors command the established base. Direct sales gain share fastest through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paraná-Paraguay waterway anchors South American agrochemical logistics, while Union Pacific and BNSF rail networks sustain bulk formulation movements across the US Midwest. These infrastructure assets determine regional supply velocity and inventory positioning.
United States
Corn belt operations in Iowa and Illinois absorb low-volatile ester formulations at replacement-cycle pace. EPA FIFRA registration pathways streamline product renewals for choline salt variants. The Mississippi River corridor concentrates bulk liquid terminal capacity near St. Louis and Memphis.
Brazil
Mato Grosso soybean cooperatives sustain rotation demand amid glyphosate-resistant weed pressure. ANVISA pesticide re-registration timelines extend commercial uncertainty for legacy acid formulations. The Santos port complex handles bulk technical-grade imports from Chinese manufacturing clusters.
China
Jiangsu and Anhui provinces fragment manufacturing capacity to manage MEE emission caps on chlorophenol intermediates. The Yangtze River Delta feedstock concentration sustains cost leadership against European import competition. Nantong chemical parks anchor technical-grade output expansion.
Australia
Wheat belt operations in New South Wales and Victoria adopt ultralow-volume aerial applications with real-time wind monitoring. APVMA registration systems enforce drift-mitigation buffer requirements distinct from EPA standards. The Port of Newcastle handles bulk formulation imports for eastern seaboard distribution.
Germany
REACH authorization delays under Regulation 1107/2009 constrain ester formulation availability for cereal applications. The Rhine corridor concentrates formulation blending capacity near Ludwigshafen. ECHA guidance on chlorophenol intermediate reclassification forces supply chain audits.
2,4-Dichlorophenoxyacetic Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between captive-feedstock manufacturers in eastern China and formulation innovators in North America and Europe. Three archetypes dominate: technical-grade producers with backward integration into chlorophenol intermediates, proprietary ester formulators with drift-mitigation portfolios, and regional distributors with established agrochemical channel infrastructure. Capacity expansion in Anhui and Jiangsu provinces runs parallel to adjuvant R&D investments by North American registrants.
Among Chinese technical-grade producers, Anhui Xinglong Chemical and Anhui Huaxing Chemical occupy positions anchored by eastern provincial feedstock access. Nufarm exemplifies the Australasian distribution archetype, while Corteva Agriscience represents proprietary formulation differentiation. These three entities illustrate the geographic and functional segmentation that defines competitive positioning across manufacturing, distribution, and product development vectors.
| Leading Market Players |
|---|
| Anhui Xinglong Chemical |
| Anhui Huaxing Chemical |
| Jiangsu Yongtaifeng Crop Science |
| Mesa Tech International |
| Jiangsu Changfeng Agrochemical |
| Nufarm |
| Corteva Agriscience |
| FMC Corporation |
| BASF |
| Others |
Value Network & Pricing Analysis
Overcapacity in Jiangsu province chlorophenol intermediate production is compressing technical-grade supplier margins while simultaneously granting Chinese manufacturers pricing leverage over European and North American import-dependent formulators. This utilization asymmetry feeds directly into a two-tier market where captive-feedstock producers sustain cost leadership and formulation innovators capture drift-mitigation premiums.
Pricing Analysis
EPA FIFRA volatility criteria dictate the pricing tier structure by bifurcating the market between legacy amine salt formulations and low-volatile ester variants with proprietary adjuvant bundles. Pricing stratifies across premium, standard, and economy tiers, with choline salt formulations commanding service-embedded premiums in Midwest corn operations while wettable powders erode in cost-sensitive markets with legacy mixing equipment. Cost compression in the technical-grade tier is intensifying because Jiangsu-Anhui manufacturing corridor expansion outpaces demand absorption. Smallholder cultivators in India's Punjab state exhibit the highest price sensitivity, whereas Brazilian soybean cooperatives prioritize efficacy guarantees and regulatory compliance documentation over unit cost.
Supply Chain Analysis
Chlorophenol feedstock concentration in Jiangsu, Anhui, and Shandong provinces anchors upstream supply, with etherification capacity clustering in the Yangtze River Delta chemical parks. Manufacturing draws from phenol derivatives, chlorine gas, and chloroacetic acid as primary inputs, with emission-cap enforcement under China's MEE introducing supply volatility through unplanned production halts. Single-source vulnerability concentrates in coastal Chinese intermediate supply, exposing formulators to abrupt feedstock disruption when provincial environmental inspections trigger temporary closures. Distribution runs through regional agrochemical wholesalers in Brazil's Mato Grosso and the US Midwest, with direct sales penetration accelerating among Argentine Pampas cooperatives seeking to bypass distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative consolidation in Brazilian soybean operations and direct procurement scaling among Midwest corn belt farming enterprises, fragmenting traditional distributor intermediaries and compressing manufacturer margin capture.
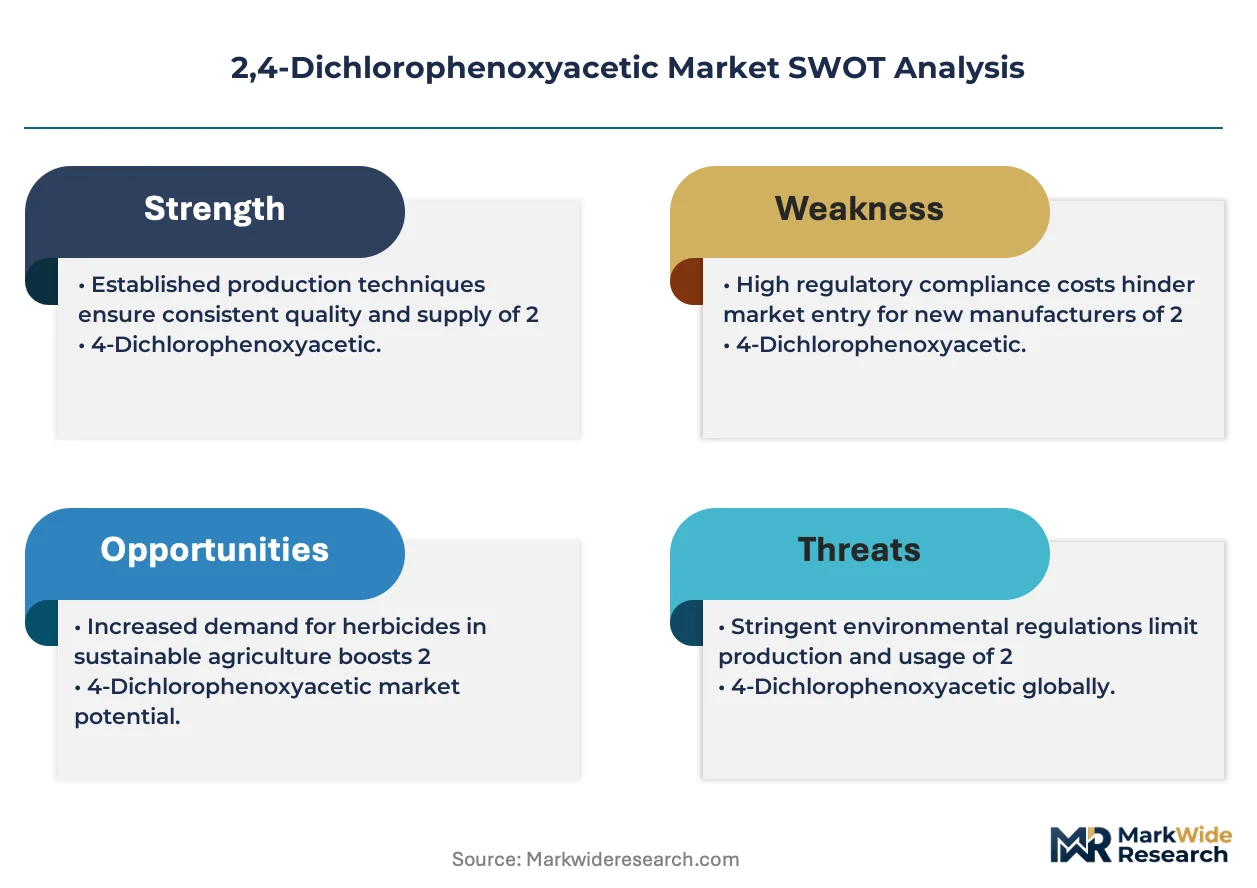
For Market Incumbents: Entrench proprietary ester formulation portfolios through accelerated adjuvant R&D investments that exceed EPA volatility criteria, while securing captive chlorophenol feedstock via backward integration into Anhui province manufacturing assets. The amino acid herbicide substitution threat from glufosinate-ammonium and dicamba formulations demands preemptive rotation protocol embedding with large soybean cooperatives. Channel control through technical advisory service bundling represents the critical lever for defending supplier relationships against distributor disintermediation. For New Entrants and Emerging Players: Precision horticulture granule applications in California nut orchards and Florida citrus operations represent the most penetrable entry point, given calibrated dosing equipment specialization that limits incumbent liquid-formulation dominance. Drone-based aerial application convergence in Australian wheat belts offers a second white-space target, with ultralow-volume spray system integration creating service revenue attachments beyond commodity product supply. A go-to-market angle anchored by independent agronomic consultancy partnerships bypasses entrenched distributor relationships in South American markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between EPA FIFRA streamlining and EU REACH authorization delays creates formulation portfolio valuation asymmetries. Acquisition targets should emphasize proprietary low-volatile ester registrants with established North American channel infrastructure and pending European active substance renewal timelines. The signal to watch is ECHA candidate list expansion pace for chlorophenol intermediate reclassification, which would trigger supply chain restructuring costs and reposition bio-based precursor innovators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorophenol Feedstock | Anhui province manufacturing assets secure cost leadership against European import competition under MEE emission caps. |
| Low-Volatile Ester Formulation Development | EPA FIFRA registration streamlining accelerates product renewal timelines for choline salt variants in drift-sensitive counties. |
| Drone-Based Aerial Application Partnership | APVMA-aligned ultralow-volume spray systems unlock restricted Australian wheat belt acreage through real-time wind monitoring. |
| EU F-Gas Regulation Compliance Service Launch | ECHA guidance on co-formulant restrictions creates advisory revenue attachments for drift-buffer modeling in French and German cereal markets. |
| Precision Horticulture Granule Capacity Expansion | California and Florida specialty crop operations sustain premium pricing through calibrated dosing system compatibility. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with agrochemical manufacturing executives, formulation R&D directors, Brazilian distributor procurement leads, and Australian aerial application contractors; and secondary validation through EPA FIFRA registration databases, ANVISA pesticide re-registration filings, ECHA authorization timelines, and Chinese MEE emission cap enforcement records. Bottom-up technical-grade production estimates from Jiangsu-Anhui manufacturing clusters were triangulated against top-down demand absorption metrics from Brazilian soybean cooperative purchasing data.
Forecast inputs incorporated formulation chemistry segmentation across acid, ester, and salt variants; application intensity differentials between commodity row-crop and precision horticulture systems; and regional regulatory cluster divergence between EPA-streamlined North American jurisdictions and REACH-constrained European markets. CAGRs were derived from replacement-cycle pacing in US corn belt operations and rotation protocol penetration in Brazilian glyphosate-resistant weed management programs, with chlorophenol intermediate supply elasticity under MEE enforcement serving as a key supply-side constraint variable.
Practitioners should monitor ECHA candidate list expansion, ANVISA re-registration timeline extensions, and Chinese provincial environmental inspection intensity for early signals of forecast revision. Cross-checking against ACC and Cefic agrochemical trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Adipic Acid Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
2-Ethyl Hexanol Market