
 Furfural Market | 2026-2036
Furfural Market Size, Share, and Industry Trends Forecast 2026-2036
Furfural Market Intelligence
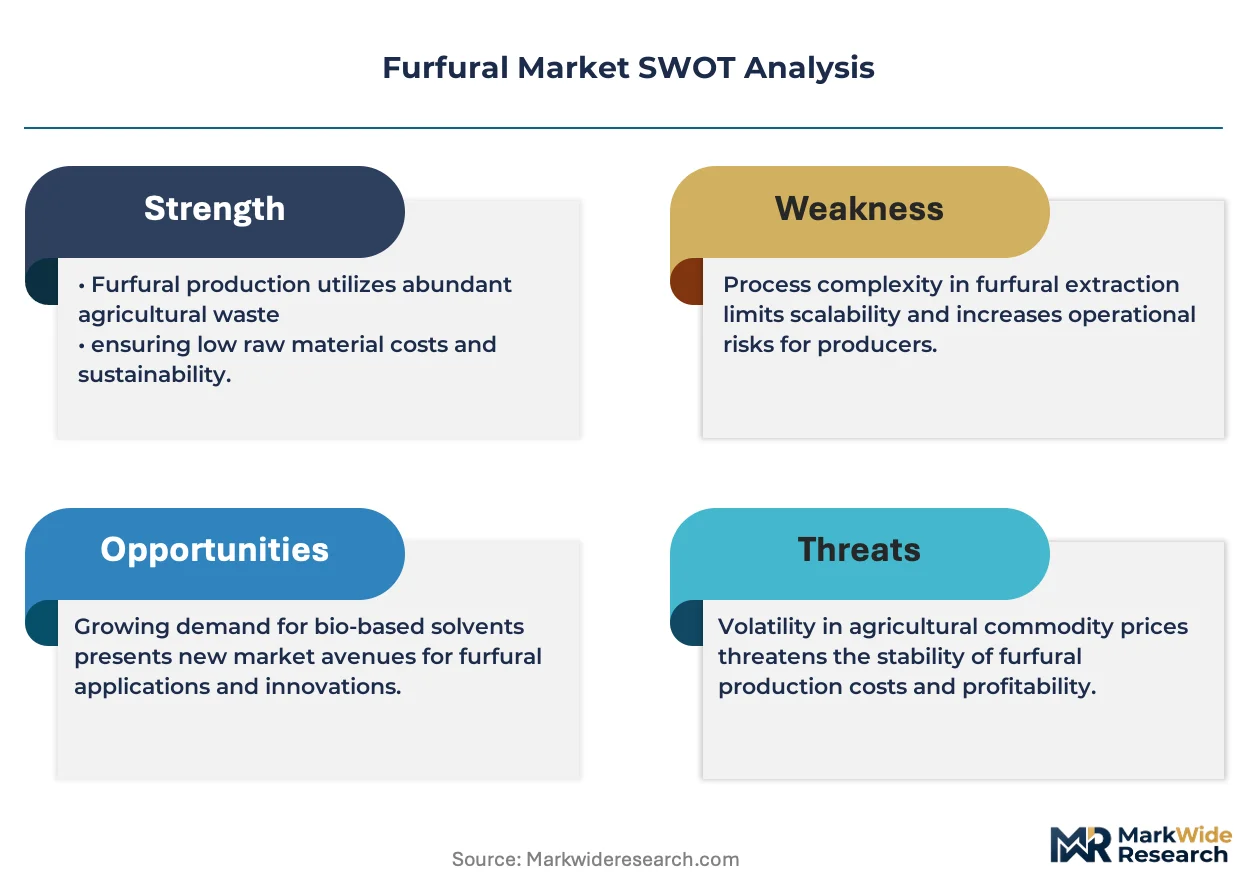
The capital-intensity gap between integrated agro-refiners and standalone furfural processors is bifurcating competitive returns across the value chain. Hongye Holding Group Corporation Ltd leverages captive agricultural residue supply to sustain cost leadership in conventional furfural output. TransFurans Chemicals bvba differentiates through specialized furan chemistry and downstream derivative control. Pennakem LLC anchors North American supply reliability with integrated solvent distribution infrastructure.
Furfural is a heterocyclic aldehyde derived from pentosan-rich biomass such as corn cobs, bagasse, and oat hulls via acid-catalyzed dehydration, typically yielding 90-95% purity grades for industrial solvent applications. The substance serves primarily as a selective extraction solvent for lubricating oil refining and as a chemical intermediate for furan resins and tetrahydrofuran precursors. Conventional furfural still occupies the dominant volume position due to mature supply chains and established pricing benchmarks, though bio-based furfural commands expanding interest from sustainability-driven chemical purchasers seeking Scope 3 emissions reductions. Furfural derivatives concentrate margin pools where pharmaceutical and agrochemical formulators require high-purity intermediates with documented chain-of-custody credentials.
EPA industrial chemical regulations govern furfural emissions thresholds and worker exposure limits in US manufacturing facilities, while REACH registration mandates in Europe impose comprehensive toxicological dossier requirements on importers and producers. China's MEE enforces wastewater discharge standards that directly affect acid-hydrolysis plant economics in Shanxi and Shandong provinces. Stakeholders must monitor evolving bio-based certification schemes and carbon border adjustment mechanisms that will reshape feedstock sourcing decisions and regional production competitiveness.
Market Dynamics
The furfural market is undergoing structural recalibration as agro-refinery integration reconfigures feedstock economics and captive supply chains displace merchant market dependency. Acid-catalyzed dehydration technology improvements are compressing unit costs for processors with direct agricultural residue access.
Growth Catalysts
- REACH purity mandates:European solvent-grade specifications are tightening material specifications, creating premium pricing tiers for high-purity furfural that certified producers can capture.
- Pharmaceutical synthesis demand:Tetrahydrofuran precursor requirements from generic drug manufacturers are expanding offtake volumes for refined furfural derivatives.
- Shanxi processing corridor concentration:China's corn cob supply density around Taiyuan enables acid-hydrolysis plants to achieve feedstock logistics cost advantages unavailable elsewhere.
Market Restraints
- Feedstock seasonality:Corn cob availability fluctuates with harvest cycles, forcing processors to absorb working capital costs for six-month inventory buffers.
- Sulfuric acid price volatility:Dehydration catalyst costs swing with sulfur energy market movements, eroding margin predictability for non-integrated operators.
- MEE wastewater discharge compliance:China's environmental enforcement tightens effluent standards for acid-hydrolysis facilities, requiring capital expenditure for treatment upgrades.
Strategic Opportunities
- Bio-based certification premiums:ISCC PLUS and similar chain-of-custody schemes enable pricing differentiation for Scope 3-conscious chemical purchasers in European markets.
- Furan resin specialty applications:High-performance composites for aerospace and electronics offer margin expansion beyond commodity solvent sales.
- Bagasse feedstock diversification:Brazilian and Indian sugarcane processing waste streams present underutilized pentosan sources for new production capacity.
Industry Challenges
- Skilled technician scarcity:Acid-hydrolysis process optimization requires experienced chemical engineers familiar with corrosive environment safety protocols.
- Legacy equipment retrofit complexity:Older batch reactors face pressure to convert to continuous processing for yield improvements, demanding substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furfural Market |
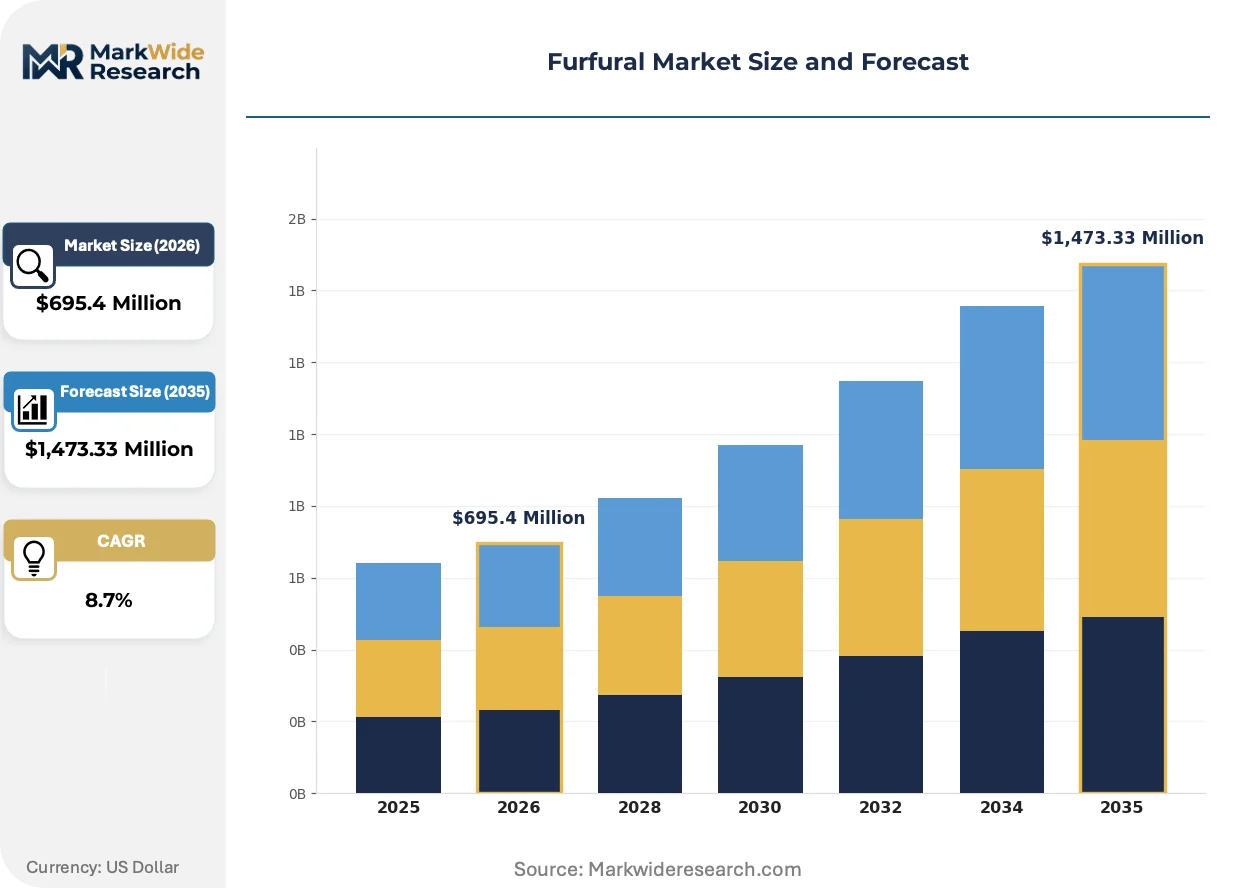
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $1,473.33 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Furfural, Bio-Based Furfural, Furfural Derivatives, Furan Application: Solvent, Intermediates, Resin, Agrochemicals End User: Chemicals, Pharmaceuticals, Food & Beverage, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Central Romana Corporation, Hongye Holding Group Corporation Ltd, Illovo Sugar Ltd, Pennakem LLC, Silvateam S.p.A., Tieling North Furfural (Group) Co. Ltd., Lenzing AG, KRBL Ltd, TransFurans Chemicals bvba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furfural Market Strategic Shifts & Innovations
Process intensification and sustainability verification protocols are actively restructuring competitive advantage in furfural manufacturing. Technology adoption patterns now favor operators who can demonstrate feedstock traceability alongside cost efficiency.
Continuous-flow reactor systems are supplanting traditional batch acid-hydrolysis configurations in new capacity installations. Specialty chemical producers with stringent purity requirements are adopting these systems fastest. The technology is supplanting conventional equipment in greenfield projects where capital availability permits integrated design.
REACH registration dossier requirements for furfural importers are expanding toxicological documentation obligations. European producers with existing compliance infrastructure gain relative advantage over new market entrants. Derivative manufacturers seeking pharmaceutical-grade certification are consolidating supplier relationships around REACH-registered sources.
Scope 3 emissions accounting is reshaping procurement specifications for multinational chemical purchasers. Lubricating oil refiners and resin formulators now require documented carbon intensity metrics alongside traditional purity certificates. This behavioral shift is most pronounced among European and North American buyers with net-zero commitments.
Furfural Market Segmentation
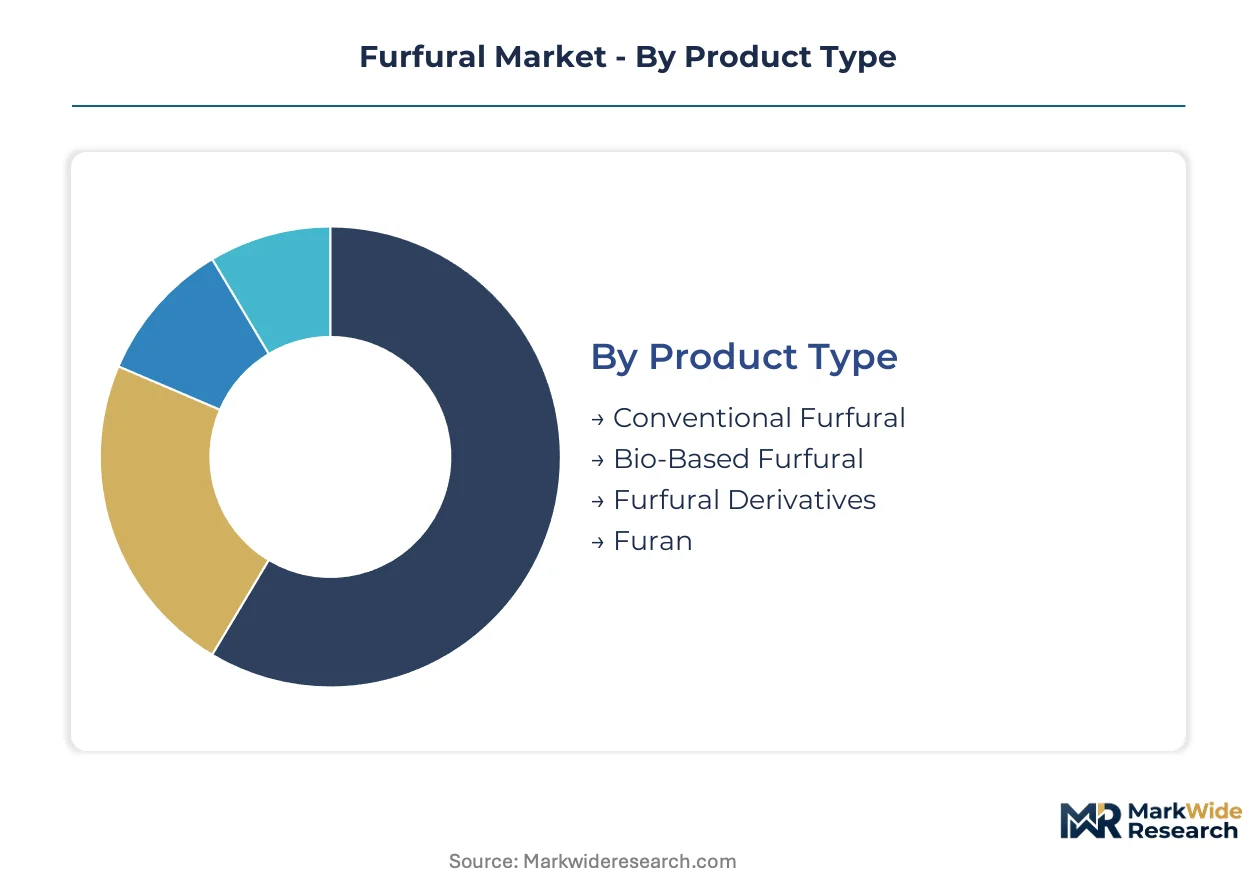
Furfural market segmentation reveals how feedstock sourcing, regulatory compliance burdens, and end-use purity requirements fragment commercial opportunities. Understanding these divisions helps processors align capital deployment with margin capture potential.
Product Type:
Domestic production concentrates on conventional and bio-based grades for regional solvent markets, while derivatives and furan specialty chemicals flow disproportionately into export channels serving pharmaceutical and aerospace formulators.
- Conventional Furfural:Acid-catalyzed dehydration of corn cobs and bagasse yields 90-95% purity material standardized for lubricating oil refining and commodity resin manufacture. Demand clusters in China's Shanxi province processing corridor where captive agricultural residue supply compresses unit costs below merchant market alternatives.
- Bio-Based Furfural:ISCC PLUS-certified production with documented chain-of-custody credentials commands premium positioning from European and North American purchasers tracking Scope 3 emissions. REACH-registered sources with comprehensive toxicological dossiers consolidate supplier relationships as pharmaceutical-grade certification requirements tighten.
- Furfural Derivatives:Tetrahydrofuran precursors and furan resin intermediates concentrate margin pools where high-purity specifications apply.
- Furan:Heterocyclic building block for specialty polymers and pharmaceutical synthesis with concentrated aerospace electronics demand.
Conventional furfural commands the established base. The steepest expansion runs through bio-based furfural.
Application:
Cost tier stratification separates commodity solvent sales from premium intermediate and resin applications where purity certification drives pricing power.
- Solvent:Selective extraction medium for lubricating oil refining represents the volume anchor for conventional furfural output, with offtake patterns tied to petroleum refining runs in the US Gulf Coast and Rotterdam-Antwerp corridor.
- Intermediates:Tetrahydrofuran precursors for generic drug manufacturing and agrochemical synthesis require documented impurity profiles that REACH-registered suppliers can substantiate, creating qualification barriers for unregistered sources.
- Resin:Furan-based binders for foundry molds and high-performance composites serve automotive and aerospace supply chains.
- Agrochemicals:Pesticide and herbicide formulation intermediates with seasonal demand patterns tied to Northern Hemisphere planting cycles.
Solvent applications anchor volume throughput. Intermediate sales are climbing the fastest as pharmaceutical synthesis requirements expand.
End User:
Customer type fragmentation splits procurement between multinational chemical purchasers with net-zero commitments and price-sensitive regional processors.
- Chemicals:Resin formulators and specialty polymer manufacturers constitute the core demand base, with procurement specifications increasingly incorporating carbon intensity metrics alongside traditional purity certificates.
- Pharmaceuticals:Generic drug manufacturers and active pharmaceutical ingredient producers drive the most stringent purity requirements, consolidating supplier relationships around REACH-registered sources with established toxicological documentation.
- Food & Beverage:Flavor and fragrance applications with limited volume contribution but premium pricing potential.
- Agriculture:Direct furfural use as a nematicide and soil fumigant with regulatory-dependent market access.
Chemical sector offtake maintains the volume foundation. Pharmaceutical demand is gaining share fastest as tetrahydrofuran precursor requirements multiply.
Distribution Channel:
Supply concentration patterns favor direct relationships for bulk solvent contracts while specialty derivatives move through distributor networks with technical service capabilities.
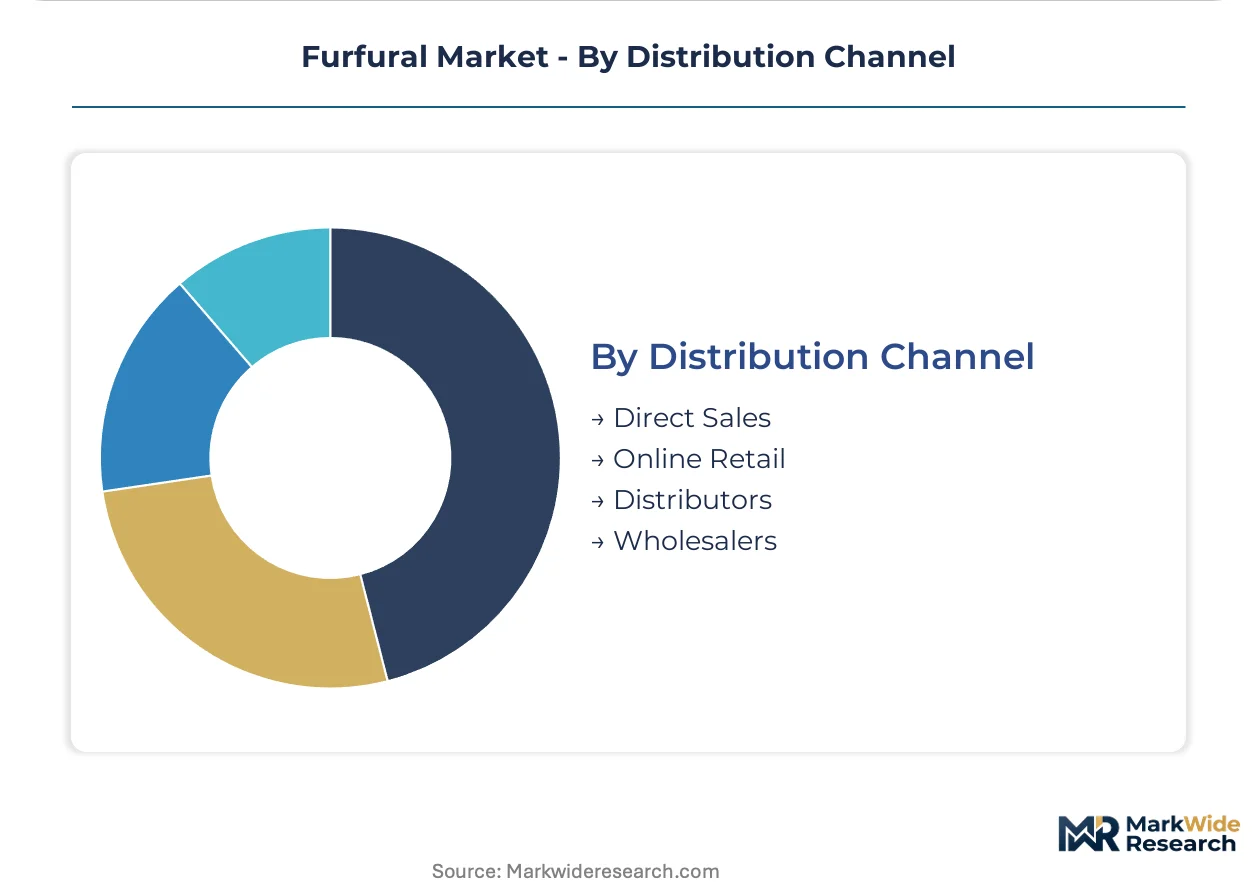
- Direct Sales:Integrated agro-refiners with captive agricultural residue supply leverage direct relationships with lubricating oil refiners and large resin formulators, bypassing merchant market price volatility.
- Distributors:Technical distributors with solvent blending and regulatory compliance support infrastructure capture value in fragmented specialty chemical segments.
- Online Retail:Limited to laboratory-scale quantities and research-grade material with minimal commercial relevance.
- Wholesalers:Regional inventory positioning for standard-grade solvent in markets lacking integrated supply.
Direct sales channels command the established base. Distributor-mediated specialty chemical sales are expanding most quickly as qualification complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese processors demonstrate the lowest price elasticity due to captive corn cob supply, while European purchasers show inelastic demand for REACH-registered material despite substantial premiums. This demand-curve divergence shapes regional investment allocation and capacity planning decisions.
China
Shanxi province's Taiyuan corridor processes over half of domestic corn cob feedstock into conventional furfural for lubricating oil extraction. MEE wastewater discharge standards tightened in 2023, forcing acid-hydrolysis facilities to install tertiary treatment systems. Shandong province's newer continuous-flow installations achieve higher yields with lower effluent loads than legacy batch operations in Shanxi.
United States
Gulf Coast lubricating oil refiners constitute the dominant solvent offtake base, with procurement specifications increasingly incorporating carbon intensity documentation. EPA industrial chemical regulations govern facility emissions thresholds and OSHA worker exposure limits at manufacturing sites. Pennakem LLC anchors regional supply reliability through integrated solvent distribution infrastructure serving Texas and Louisiana refining complexes.
Germany
REACH-registered furfural commands substantial premiums from pharmaceutical manufacturers requiring tetrahydrofuran precursor certification. ECHA toxicological dossier requirements impose comprehensive documentation burdens on importers that domestic producers with existing compliance infrastructure exploit. The Rhine-Ruhr industrial corridor hosts specialty chemical formulators consolidating supplier relationships around registered European sources.
Belgium
TransFurans Chemicals bvba exemplifies the specialized furan chemistry archetype, leveraging downstream derivative control to capture margin pools unavailable to commodity processors. REACH purity mandates for solvent-grade material tighten material specifications annually, rewarding producers with established certification infrastructure. The Port of Antwerp handles bulk furfural transshipment for European distribution networks.
Brazil
Sugarcane bagasse presents underutilized pentosan feedstock for new acid-hydrolysis capacity serving Latin American solvent markets. ANVISA pharmaceutical regulations create qualification barriers for unregistered furfural sources seeking intermediate supply contracts. São Paulo state's sugar-ethanol processing cluster offers proximity to bagasse generation points that could replicate China's corn cob logistics model.
Furfural Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with agro-refinery operators commanding feedstock cost advantages that standalone processors cannot replicate. The competitive terrain splits between scale-driven commodity producers and purity-focused derivative specialists. Three archetypes dominate: captive-feedstock agro-refiners, REACH-registered European specialists, and integrated North American solvent distributors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with technology licensing agreements enabling process intensification upgrades.
Within the agro-refiner tier, Hongye Holding Group Corporation Ltd and Tieling North Furfural (Group) Co. Ltd represent Chinese operators leveraging domestic corn cob density for cost leadership. TransFurans Chemicals bvba occupies the European specialist position, while Pennakem LLC anchors North American supply reliability. These three exemplify how geographic feedstock access and regulatory compliance infrastructure determine competitive positioning.
| Leading Market Players |
|---|
| Central Romana Corporation |
| Hongye Holding Group Corporation Ltd |
| Illovo Sugar Ltd |
| Pennakem LLC |
| Silvateam S.p.A. |
| Tieling North Furfural (Group) Co. Ltd. |
| Lenzing AG |
| KRBL Ltd |
| TransFurans Chemicals bvba |
| Others |
Cost & Logistics Intelligence
Shanxi province's corn cob processing density creates feedstock procurement advantages that compress unit production costs below merchant market alternatives. This scale concentration enables Chinese agro-refiners to sustain price floors that standalone processors in Europe and North America cannot match, bifurcating competitive returns across integrated and non-integrated supply chain archetypes.
Pricing Analysis
After-sales service bundling with technical support contracts drives lifetime value capture for specialty derivative suppliers serving pharmaceutical formulators. Contract-based long-term offtake agreements dominate conventional solvent sales to lubricating oil refiners, while bio-based certification premiums stratify pricing across ISCC PLUS-verified, REACH-registered, and unregistered supply tiers. Pricing pressure stems from sulfuric acid catalyst cost volatility eroding margin predictability for non-integrated operators. Regional processors in China's Shanxi corridor exhibit lowest price sensitivity due to captive feedstock supply, while European pharmaceutical purchasers show inelastic demand for documented chain-of-custody material despite substantial premiums.
Supply Chain Analysis
China, Belgium, and the United States anchor furfural manufacturing through distinct competitive archetypes: Shanxi's corn cob corridor, Antwerp's specialty chemical derivative hub, and Gulf Coast solvent distribution infrastructure. Pentosan-rich agricultural residues—corn cobs, bagasse, oat hulls—constitute primary feedstock inputs alongside sulfuric acid dehydration catalysts and wastewater treatment chemicals. Single-source vulnerability concentrates in China's Taiyuan processing cluster where over half of conventional furfural originates. Distribution runs through direct sales relationships for bulk solvent contracts and technical distributor networks for specialty derivative qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furfural market fragmentation creates multiple niche entry points as pharmaceutical synthesis requirements multiply and certification complexity rises. Scope 3 emissions accounting from multinational chemical purchasers splits procurement specifications between price-sensitive regional processors and premium-seeking sustainability-driven buyers.
For Market Incumbents: Secure backward integration into agricultural residue supply through offtake agreements with corn processing cooperatives in Shanxi and Shandong provinces. Deepen REACH registration dossier completeness to exploit toxicological documentation barriers against unregistered import competition. Capacity addition in continuous-flow reactor technology addresses yield advantages and MEE wastewater compliance simultaneously.
For New Entrants and Emerging Players: Anchor in Brazilian sugarcane bagasse processing corridors where ANVISA pharmaceutical regulations have not yet consolidated supplier relationships. Target tetrahydrofuran precursor supply to generic drug manufacturers seeking qualification alternatives to established REACH-registered sources. Pursue ISCC PLUS certification as primary go-to-market credential for European and North American Scope 3-conscious purchasers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agro-refinery operators with demonstrated continuous-flow reactor yields and established environmental compliance infrastructure. Long-term viability rests on feedstock procurement advantages that survive carbon border adjustment mechanism implementation. Acquisition target archetype: Shanxi-based processors with tertiary wastewater treatment upgrades and direct corn cob supply relationships. Watch for MEE enforcement intensity shifts as inflection indicator for Chinese production cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn cob offtake agreements in Shanxi province compress unit costs below merchant market alternatives. |
| Continuous-Flow Reactor Technology Licensing | Process intensification upgrades yield improvements and reduce MEE wastewater discharge compliance burdens. |
| ISCC PLUS Certification Program | Chain-of-custody credentials unlock premium positioning from European Scope 3-conscious chemical purchasers. |
| REACH Registration Dossier Investment | Comprehensive toxicological documentation consolidates supplier relationships with pharmaceutical-grade certification requirements. |
| Long-Term Supply Agreement with Lubricating Oil Refiners | Direct sales relationships with Gulf Coast and Rotterdam-Antwerp refining complexes bypass distributor price volatility. |
Research Approach
Desk research of customs and trade flow databases, chemical industry association reports, and environmental regulatory filings preceded structured interviews with acid-hydrolysis plant managers, pharmaceutical procurement leads, lubricating oil refinery technical directors, and specialty chemical distribution channel partners. Primary fieldwork with Shanxi province processors and Antwerp derivative manufacturers combined with secondary validation from EPA emissions disclosures, ECHA registration dossiers, and MEE wastewater discharge records. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation from end-use industry consumption patterns.
Variance decomposition across feedstock cost trajectories, regulatory compliance expenditure, and end-use demand elasticity shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, purity certification level, and regional production hub concentration. CAGRs derived from unit economics modeling of acid-catalyzed dehydration yields and derivative margin pool capture rates. Forecast inputs incorporated corn cob harvest cycle patterns and sulfuric acid price volatility indices.
Material uncertainties — MEE enforcement intensity revisions, REACH purity mandate expansions, and carbon border adjustment mechanism implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding continuous-flow reactor adoption rates and bio-based certification scheme recognition continuity. Recalibration cycles align with material shifts in environmental regulatory stringency and pharmaceutical synthesis demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Global Naphthalene Derivatives Market