
 Cobalt Acetate Crystals Market | 2026-2036
Cobalt Acetate Crystals Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Acetate Crystals Market Analysis
Aftermarket catalyst regeneration revenue is tilting toward specialized cobalt salt processors as original equipment makers seek to reduce virgin material costs. Umicore leverages its integrated refining network across Belgium and Finland to control feedstock quality for acetate production. Freeport Cobalt anchors North American supply through captive mine-to-salt processing in the Democratic Republic of Congo and Finland. Mechema Chemicals International specializes in custom crystal morphology for petrochemical catalyst clients requiring specific surface area profiles.
Cobalt acetate crystals consist of pink to red crystalline hydrated salts with the formula Co(C₂H₃O₂)₂·nH₂O, typically manufactured through the reaction of cobalt carbonate or cobalt hydroxide with acetic acid under controlled pH and temperature conditions. The compound serves primarily as a precursor for oxidation catalysts in terephthalic acid production and as a drying accelerator in polyester resin formulations. Technical grade material dominates volume shipments due to its widespread use in industrial catalyst formulations, while reagent grade commands premium positioning from laboratories and analytical chemistry end users in the chemical industry. Application demand clusters heavily in catalyst manufacturing, with pigment and nutrient applications trailing in absolute volume but offering higher margin potential for producers meeting food-grade and pharmaceutical-grade specifications.
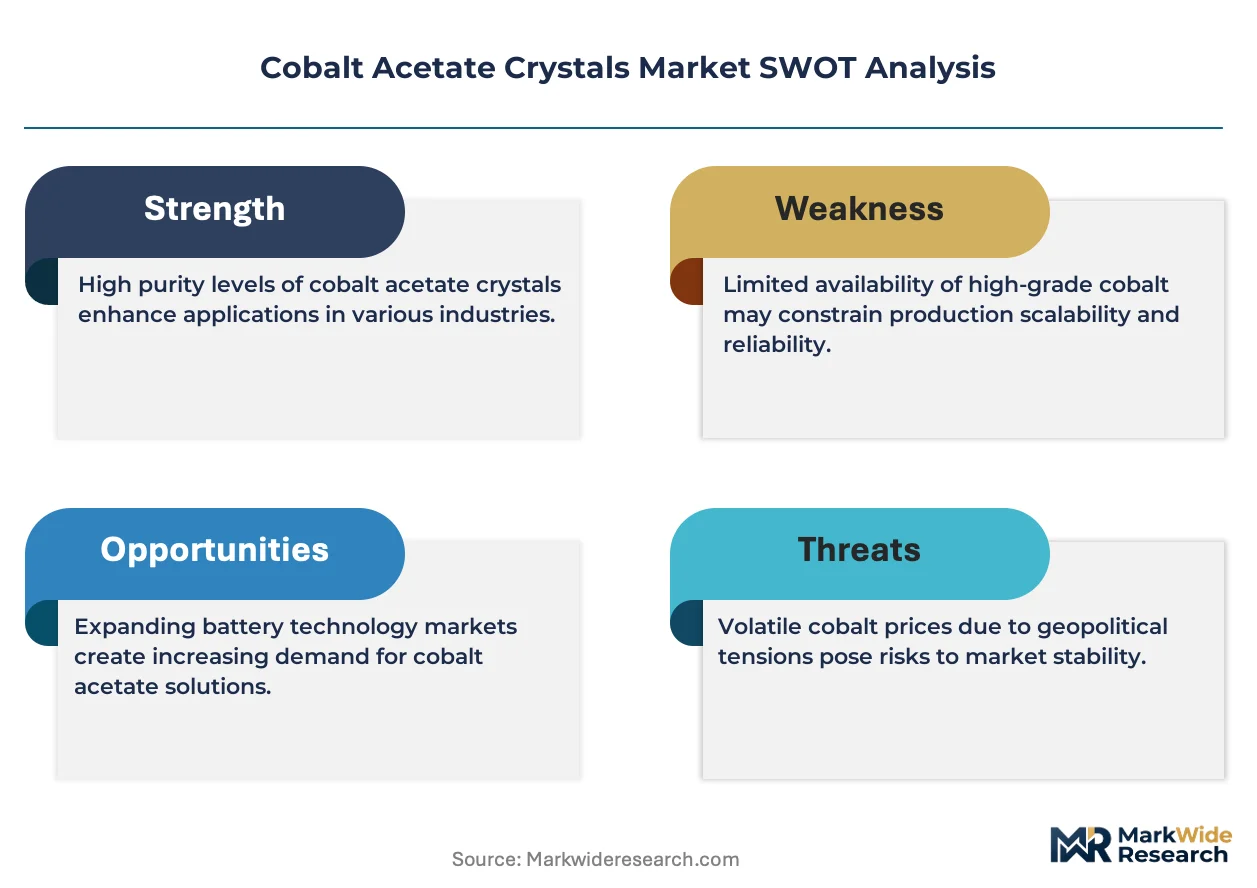
REACH registration requirements in Europe mandate full toxicological dossiers for cobalt acetate imports, while China's GB standards and SAMR oversight enforce purity thresholds for domestic distribution and export certification. The US EPA regulates cobalt compounds under TSCA Section 8(a) reporting rules, creating compliance cost differentials between jurisdictions. Stakeholders must monitor evolving battery-material competition for cobalt feedstock, as electric vehicle cell demand continues to pull available metal away from traditional acetate crystal production channels.
Market Dynamics
Catalyst manufacturers are consolidating procurement around long-term cobalt acetate supply contracts as battery cell producers divert feedstock toward cathode active materials, tightening merchant market availability for traditional chemical applications.
Growth Catalysts
- REACH and RoHS compliance tightening:European ECHA enforcement of full toxicological dossiers for cobalt salt imports is filtering out low-purity suppliers and concentrating demand among certified refiners.
- Polyester resin formulation expansion:Construction and automotive coating sectors in China are scaling cobalt acetate consumption as a drying accelerator for unsaturated polyester resins.
- Petrochemical catalyst regeneration:Aftermarket regeneration services are expanding cobalt acetate demand as refiners seek to extend catalyst lifecycles rather than purchase virgin material.
Market Restraints
- Cobalt feedstock competition from battery cathodes:Electric vehicle cell manufacturers are capturing an increasing share of mined cobalt, elevating raw material costs for acetate crystal producers.
- Supply concentration in Central Africa:Democratic Republic of Congo mine output dominates feedstock origination, exposing processors to geopolitical instability and artisanal mining scrutiny.
- Substitution by manganese and iron catalysts:Cost-conscious terephthalic acid producers are trialing non-cobalt oxidation catalysts in select reactor configurations.
Strategic Opportunities
- Food-grade and pharmaceutical-grade certification:Producers achieving USP and FCC compliance can access nutrient supplement applications commanding substantial price premiums over technical grade.
- India pigment manufacturing expansion:Domestic paint and ink producers are localizing cobalt salt procurement under Make in India incentives, creating import substitution demand.
- Closed-loop recycling integration:Spent catalyst recovery and cobalt reclamation from industrial waste streams is enabling circular supply models with reduced virgin metal dependency.
Industry Challenges
- Crystallization morphology control:Petrochemical clients require precise surface area specifications that demand sophisticated reactor engineering and quality systems.
- Multi-jurisdiction registration timelines:Simultaneous REACH, TSCA Section 8(a), and China GB standard compliance creates extended product launch cycles and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Acetate Crystals Market |
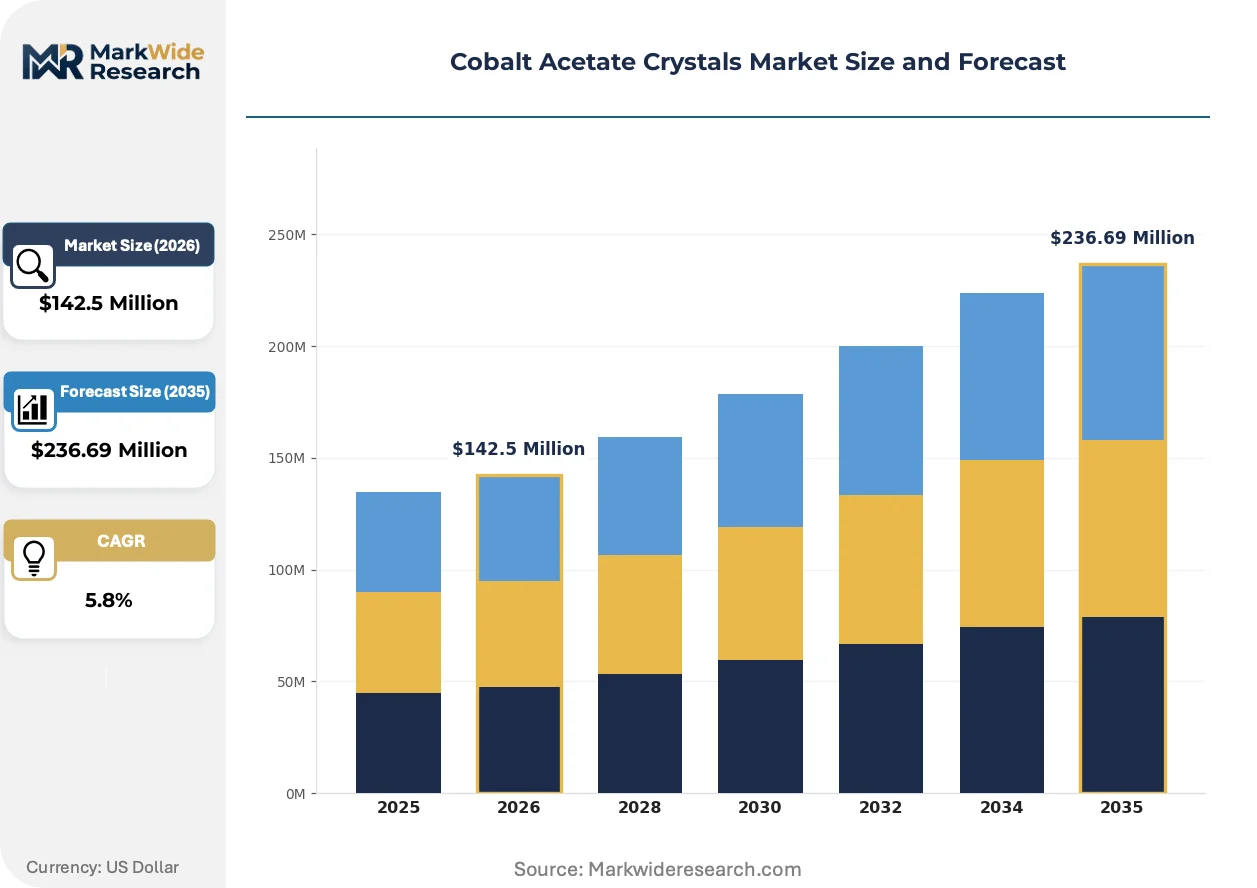
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Reagent Grade, Industrial Grade Application: Catalyst, Dye, Pigment, Nutrient End User: Chemical Industry, Plastic Manufacturing, Agriculture, Laboratories Packing Type: Bag, Drum, Bottle, Bulk |
| Companies Covered | Coremax Corporation, Umicore, Freeport Cobalt, Mechema Chemicals International, American Elements, Nanjing Chemical Reagent, Liaoyang Synthetic Catalyst, TIANFU CHEMICAL, Kansai Catalyst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Acetate Crystals Market Emerging Trajectories
Process control technologies and regulatory data systems are transforming how cobalt acetate producers manage purity certification and supply chain traceability across dispersed manufacturing networks.
Automated crystallization monitoring using inline particle size analyzers is digitizing quality assurance workflows. Catalyst manufacturers in Belgium and Finland are deploying these systems to eliminate batch-to-batch variation. The technology is digitizing documentation trails for REACH compliance, compressing audit preparation cycles from weeks to days.
ECHA's expanded Substance of Very High Concern candidate list for cobalt compounds is accelerating toxicological testing investments. European pigment and catalyst formulators are demanding certified conflict-free sourcing documentation. The regulation is reshaping supplier qualification protocols, with downstream buyers now requiring third-party verified chain-of-custody records.
Direct refiner-to-formulator contracting is displacing traditional distributor networks. Large catalyst houses in China are negotiating multi-year offtake agreements with domestic cobalt refiners, bypassing merchant traders. This concentration is most visible in Shandong and Jiangsu provinces, where integrated chemical parks enable just-in-time acetate crystal delivery to adjacent catalyst fabrication facilities.
Cobalt Acetate Crystals Market Segmentation
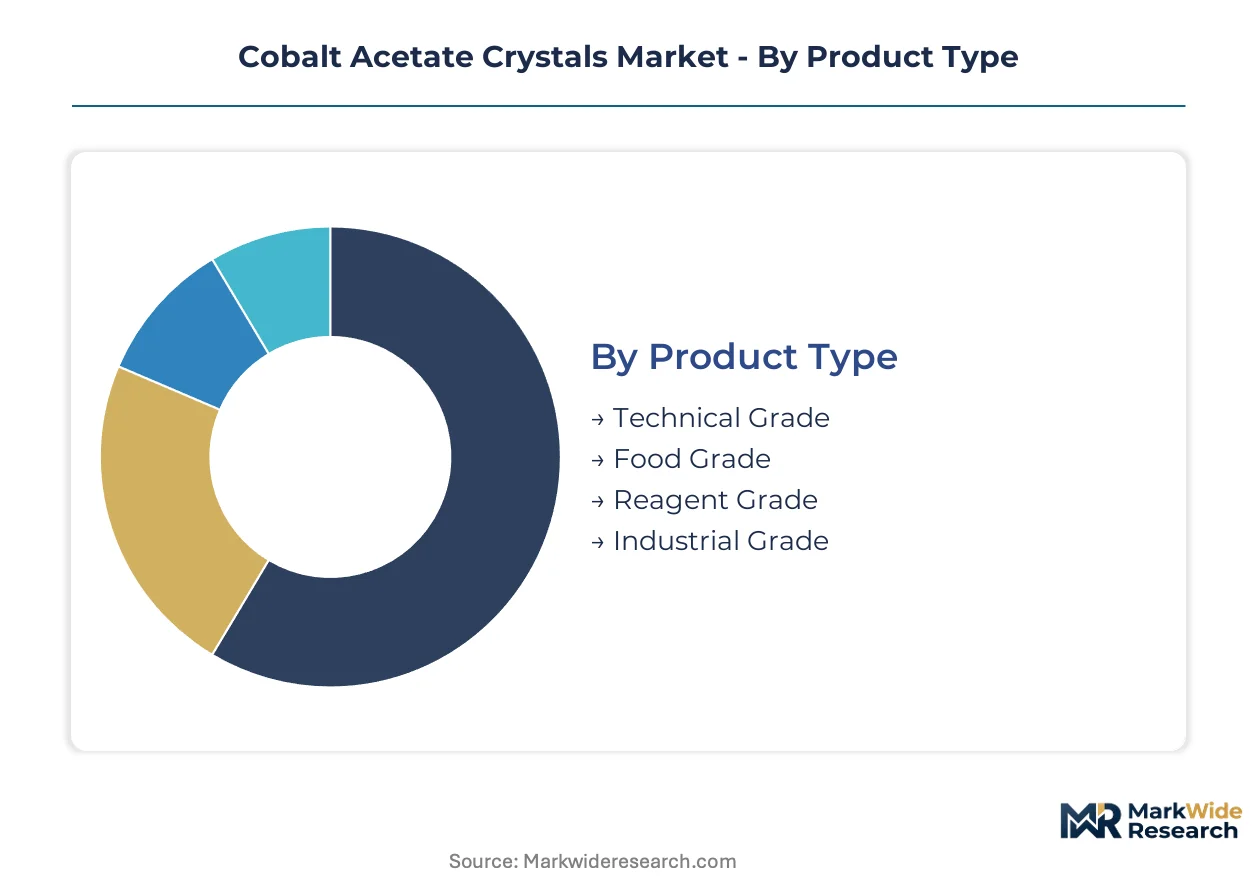
Segmentation in cobalt acetate crystals reveals how purity thresholds and packaging logistics create divergent service requirements across catalyst, pigment, and laboratory channels. Technical specifications vary sharply between industrial bulk shipments and reagent-grade laboratory bottles, demanding distinct supply chain configurations.
Product Type:
After-sales service intensity escalates with certification tier, as food-grade and reagent-grade segments require documentation support that technical-grade bulk shipments rarely demand.
- Technical Grade:Hydrated cobalt acetate crystals with standard purity levels serve oxidation catalyst manufacturing and polyester resin acceleration. Demand concentrates in Shandong province catalyst fabrication clusters, where integrated chemical parks enable just-in-time delivery adjacent to production lines.
- Food Grade:Refined to USP and FCC specifications for nutrient supplement applications, this segment commands substantial price premiums over technical material. European ECHA registration requirements and REACH toxicological dossier compliance filter supplier pools to certified refiners in Belgium and Finland.
- Reagent Grade:Analytical chemistry laboratories require ultra-high purity with batch-specific certification documentation.
- Industrial Grade:Basic specification material for non-critical drying accelerator applications in construction coatings.
Technical Grade holds the largest share; momentum sits with Food Grade as nutrient supplement applications expand.
Application:
Cost tier stratification separates commodity catalyst consumption from premium pigment and nutrient formulations.
- Catalyst:Primary consumption channel for terephthalic acid production oxidation catalysts. Petrochemical refiners in Jiangsu province are consolidating procurement around multi-year supply contracts as battery cathode manufacturers divert cobalt feedstock.
- Pigment:Ceramic and glass colorant applications require specific crystal morphology for uniform dispersion. Indian paint producers under Make in India incentives are localizing procurement, creating import substitution demand.
- Dye:Textile and ink formulations utilize cobalt acetate for specific color profiles.
- Nutrient:Animal feed and dietary supplement applications demand food-grade certification with full chain-of-custody documentation.
Catalyst dominates absolute volume; pigment climbs fastest as ceramic manufacturing expands in India.
End User:
Customer type determines order frequency and technical support depth, from laboratory single-bottle purchases to chemical industry bulk contracts.
- Chemical Industry:Catalyst manufacturers and specialty chemical formulators drive bulk consumption. REACH compliance tightening and RoHS enforcement in Europe are filtering supplier qualification to certified refiners with verified conflict-free sourcing.
- Plastic Manufacturing:Unsaturated polyester resin producers utilize cobalt acetate as polymerization accelerators for automotive and construction coatings.
- Agriculture:Nutrient supplement producers require food-grade material with full toxicological dossiers.
- Laboratories:Analytical chemistry and research institutions purchase reagent-grade material in small quantities with intensive documentation support.
Chemical Industry anchors demand volume; Plastic Manufacturing shows steepest expansion trajectory as construction coating sectors scale.
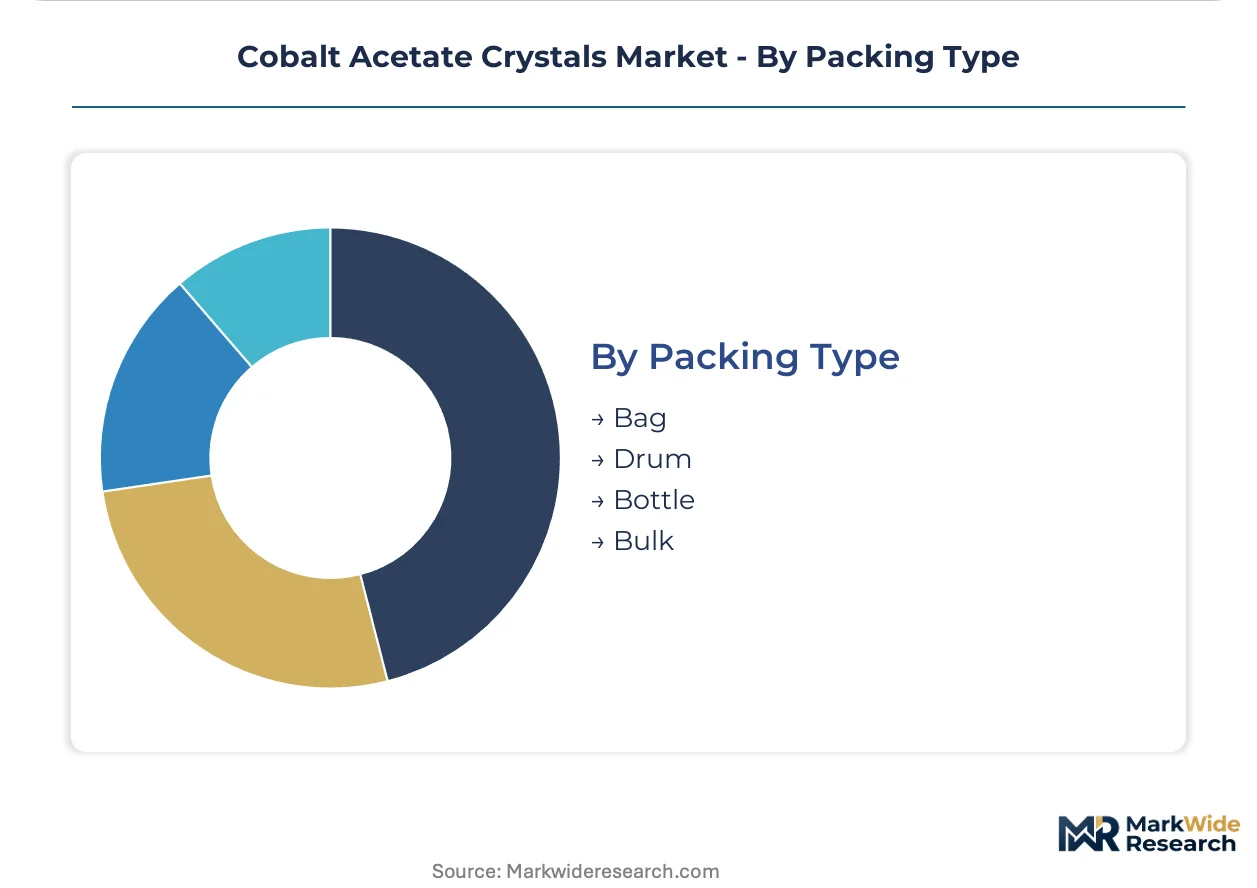
Packing Type:
Supply concentration in bulk shipments reflects catalyst and pigment manufacturing scale, while bottle and drum formats serve fragmented laboratory and agricultural channels.
- Bag:Standard flexible packaging for technical-grade material in catalyst manufacturing. Chinese integrated chemical parks favor bagged shipments for automated handling systems adjacent to production facilities.
- Drum:Steel and fiber drums protect material integrity for pigment and dye applications requiring controlled moisture exposure.
- Bottle:Laboratory-scale packaging for reagent-grade material with individual batch certification.
- Bulk:Tanker and silo delivery for large-volume catalyst producers with captive processing infrastructure.
Bulk captures the largest share; drum formats gain share fastest as pigment localization accelerates in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mine-to-salt processing infrastructure concentrates cobalt acetate supply chains in jurisdictions with integrated refining capabilities. Refiners in Belgium and Finland leverage captive feedstock networks to serve European catalyst manufacturers. Chinese chemical parks in Shandong and Jiangsu provinces dominate Asia-Pacific consumption through just-in-time delivery systems.
China
Domestic pigment and catalyst producers are securing multi-year offtake agreements with local refiners. SAMR oversight enforces GB standard purity thresholds for both domestic distribution and export certification. Integrated chemical parks in Shandong province enable adjacent catalyst fabrication facilities to receive just-in-time acetate crystal delivery.
Belgium
Umicore operates integrated refining infrastructure serving REACH-compliant catalyst formulators across Europe. ECHA enforcement of full toxicological dossiers filters supplier qualification to certified refiners with verified conflict-free sourcing. The Antwerp-Rotterdam chemical cluster anchors cobalt salt processing for terephthalic acid catalyst manufacturers.
Finland
Freeport Cobalt maintains captive mine-to-salt processing through Finnish refining assets serving North American and European markets. REACH registration requirements mandate comprehensive toxicological documentation for cobalt compound imports. Kokkola industrial zone hosts specialized cobalt salt crystallization capacity for petrochemical catalyst applications.
India
Domestic paint and ink producers are localizing cobalt salt procurement under Make in India incentives. BIS standards govern purity specifications for imported and domestically manufactured cobalt salts. Gujarat chemical manufacturing corridors are attracting catalyst producers seeking to reduce import dependency for oxidation reaction precursors.
United States
Specialty chemical formulators rely on imported refined cobalt salts due to limited domestic mine-to-salt infrastructure. EPA regulates cobalt compounds under TSCA Section 8(a) reporting rules, creating documentation requirements distinct from European REACH frameworks. Gulf Coast petrochemical complexes source acetate crystals for catalyst regeneration services extending refinery catalyst lifecycles.
Cobalt Acetate Crystals Market Vendor Landscape
Integrated refiners and specialized crystal processors split the market between captive supply security and custom morphology capabilities. Consolidation characterizes the upstream segment where mine-to-salt operators control feedstock origination. Three archetypes dominate: integrated mining-refining conglomerates, custom synthesis specialists, and regional merchant distributors. Capacity expansion in Chinese chemical parks and REACH-driven supplier qualification in Europe represent the primary competitive vectors reshaping market access.
Among integrated mining-refining conglomerates, Freeport Cobolt anchors North American supply security through captive African feedstock and Finnish processing assets. Umicore exemplifies the European REACH-compliant refiner archetype with Belgian and Finnish network control over quality certification. Mechema Chemicals International occupies the custom synthesis specialist position, serving petrochemical clients requiring precise surface area specifications. These three entities represent the strategic spectrum from raw material security to application-specific formulation expertise.
| Leading Market Players |
|---|
| Coremax Corporation |
| Umicore |
| Freeport Cobalt |
| Mechema Chemicals International |
| American Elements |
| Nanjing Chemical Reagent |
| Liaoyang Synthetic Catalyst |
| TIANFU CHEMICAL |
| Kansai Catalyst |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European REACH-compliant refining capacity is elevating pricing power for certified cobalt salt processors while forcing non-compliant suppliers toward distressed spot-market tiers. This utilization asymmetry rewards integrated refiners in Belgium and Finland with contract premium capture, while merchant traders absorb volatility from battery-sector feedstock diversion.
Pricing Analysis
REACH and RoHS compliance dictates the pricing tier structure across the cobalt acetate market. Three-tier pricing structure across food-grade, technical-grade, and industrial-grade levels separates certified nutrient supplement material commanding substantial premiums from basic drying accelerator specifications. Cost compression in technical-grade bulk shipments is intensifying because battery cathode manufacturers are capturing mined cobalt feedstock. Pigment formulators in India demonstrate highest price sensitivity due to Make in India localization incentives, while pharmaceutical-grade buyers exhibit lowest sensitivity given USP certification requirements.
Supply Chain Analysis
Tariff exposure between the Democratic Republic of Congo and European processing hubs dominates supply chain risk calculations for cobalt acetate producers. Mine-to-salt capacity concentrates in the DRC, Finland, and Belgium, with raw material flows drawing from artisanal mining clusters, cobalt hydroxide intermediates, and acetic acid reagents. Single-source vulnerability from Central African feedstock origination exposes processors to geopolitical disruption and ECHA conflict-mining scrutiny. Distribution runs through direct refiner-to-formulator contracting in Chinese chemical parks and specialized catalyst houses, displacing traditional merchant trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt acetate crystals function as a service-attach business where catalyst regeneration revenue and certification documentation support expand faster than virgin material sales. Aftermarket lifecycle extension services and toxicological dossier management represent recurring-revenue layers deepening customer retention beyond transactional crystal supply.
For Market Incumbents: Pre-empt manganese and iron catalyst substitution trials by locking petrochemical clients into multi-year regeneration service contracts with guaranteed purity specifications. Secure captive feedstock through backward integration into African mine assets or Finnish refining joint ventures before battery-sector demand further tightens merchant cobalt availability. Invest in automated crystallization monitoring systems to eliminate batch-to-batch variation that triggers REACH audit failures.
For New Entrants and Emerging Players: Build out food-grade certification capabilities targeting nutrient supplement applications where USP and FCC compliance filters competition to a handful of qualified refiners. Target Indian pigment manufacturing corridors under Make in India incentives, where domestic paint producers seek localized cobalt salt procurement to reduce import dependency. Establish toll-processing partnerships with existing REACH-registered refiners rather than building greenfield capacity.
For Investors and Strategic Acquirers: Capital is best deployed toward custom synthesis specialists with proprietary crystallization morphology control serving petrochemical catalyst clients requiring precise surface area profiles. Long-term viability hinges on circular supply models integrating spent catalyst recovery and cobalt reclamation from industrial waste streams. Watch for inflection when ECHA expands the Substance of Very High Concern candidate list to trigger accelerated toxicological testing investments and supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mine Assets | Captive DRC feedstock secures supply security against battery-sector diversion. |
| REACH Compliance Certification | ECHA toxicological dossier completion filters supplier pools to certified refiners. |
| Catalyst Regeneration Service Expansion | Aftermarket lifecycle extension deepens petrochemical client retention and recurring revenue. |
| Food-Grade USP/FCC Qualification | Nutrient supplement applications command substantial price premiums over technical material. |
| Closed-Loop Recycling Integration | Spent catalyst recovery enables circular supply models with reduced virgin metal dependency. |
Methodological Framework
Initial hypotheses were tested against primary input from catalyst manufacturing procurement directors, cobalt refinery plant managers, petrochemical R&D technical leads, and pigment formulator supply chain heads and refined through secondary validation against customs trade data, SEC 10-K filings from integrated mining conglomerates, ECHA registration databases, and China GB standard certification records. Bottom-up demand modeling across end-use segments was triangulated with top-down supply-side capacity assessments from mine-to-salt operators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included purity grade tier, application channel, packaging format, and regional production hub classification. CAGRs were derived from growth rate synthesis across segment-level volume trajectories. Forecast inputs incorporated battery-sector cobalt feedstock competition intensity and REACH enforcement escalation timelines.
Stress conditions across Central African supply disruption scenarios, manganese catalyst substitution penetration rates, and ECHA regulatory expansion pathways were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding feedstock availability and certification compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market