
 Global Cyclohexylbenzene Market | 2026-2036
Global Cyclohexylbenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyclohexylbenzene Market Foresight
High-purity benzene derivatives is hardening as the preferred feedstock pathway for electronic-grade cyclohexylbenzene, displacing legacy refining routes that struggle to meet semiconductor-battery dual specifications. BASF SE leverages its integrated aromatics complex in Ludwigshafen to sustain captive supply of precursor materials. Eastman Chemical Company anchors North American production through Kingsport, Tennessee operations that specialize in performance intermediates. LG Chem competes aggressively from its Korean petrochemical base, extending vertical reach into battery electrolyte formulations.
Cyclohexylbenzene is a bicyclic aromatic hydrocarbon with molecular formula C12H16, produced through catalytic hydrogenation of biphenyl or alkylation of benzene with cyclohexene, yielding a colorless liquid with boiling point near 240°C that serves primarily as a high-boiling solvent and chemical intermediate. Pure Cyclohexylbenzene dominates value capture for electronics applications where trace metal specifications below 10 ppb command substantial premiums. Intermediate Chemicals leads volume absorption across the application dimension, though Polymer Production represents the fastest-expanding demand pool as engineering resin formulations incorporate cyclohexylbenzene-derived stabilizers. The End Use Industry dimension shows Pharmaceuticals and Plastics Manufacturing as the twin pillars of structural demand, with margin pools concentrating in pharma-grade material where batch certification requirements create supply stickiness.
EPA oversight under TSCA governs manufacturing and import thresholds in the United States, while REACH registration mandates in Europe impose full substance dossier requirements that filter out non-compliant suppliers. China's MEE enforces dual carbon goals that tighten energy-intensity benchmarks for hydrogenation processes, reshaping cost structures for domestic producers. Buyers must monitor evolving battery-grade purity protocols and regulator alignment across these three jurisdictions to secure qualified supply.
Market Dynamics
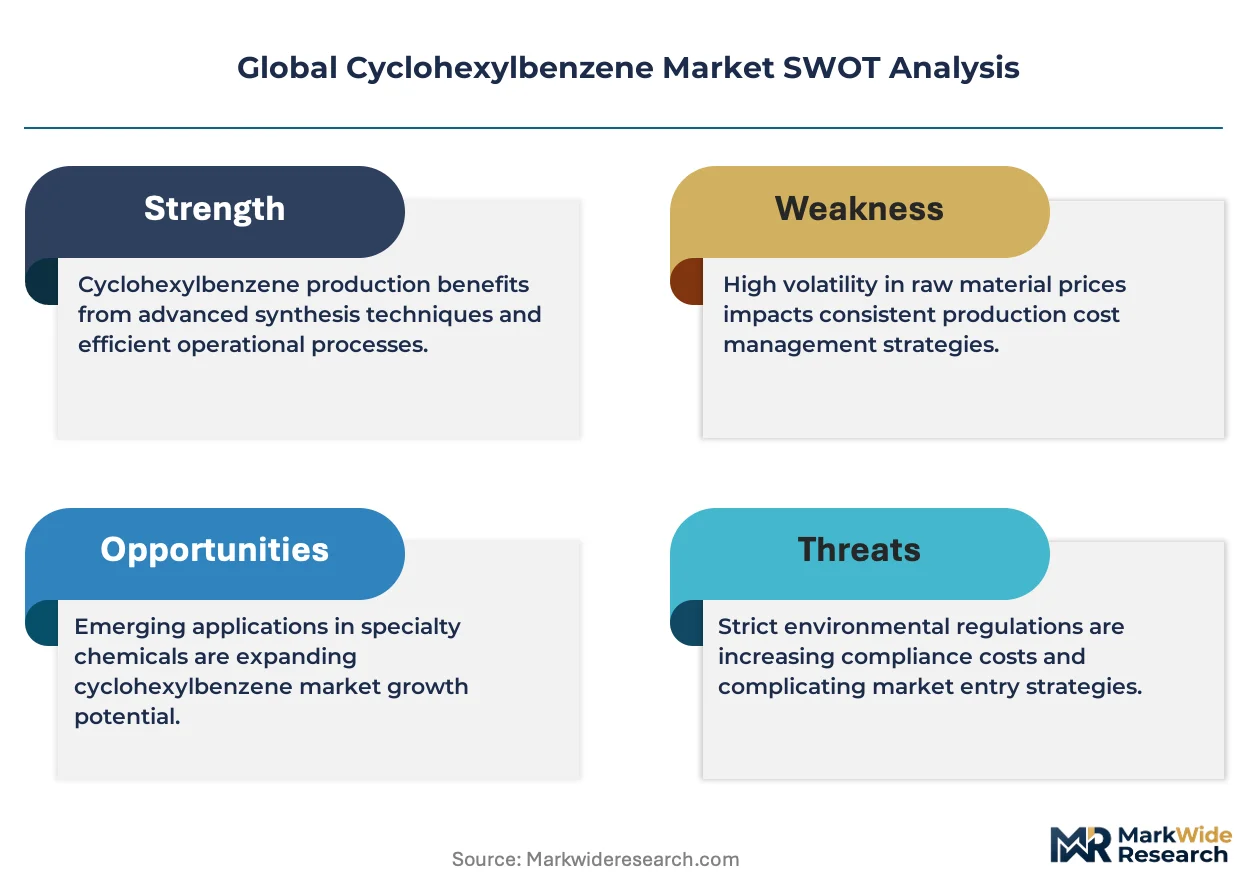
The lithium-ion battery electrolyte additive specification is hardening purity thresholds faster than legacy hydrogenation capacity can adapt, forcing producers to choose between semiconductor-grade retrofit investments and pharma-grade margin capture.
Growth Catalysts
- Battery electrolyte additive demand:Electric vehicle manufacturers specify cyclohexylbenzene-derived intermediates for thermal runaway suppression, pulling capacity toward electronic-grade certification.
- REACH registration dossier completion:Full substance data requirements under ECHA filter out marginal European suppliers, concentrating qualified supply among compliant producers.
- Dual carbon goals enforcement:China's MEE tightens energy-intensity benchmarks for catalytic hydrogenation, accelerating process efficiency investments at surviving facilities.
Market Restraints
- High-purity benzene feedstock volatility:Refinery aromatics output fluctuates with transportation fuel demand, squeezing margin predictability for derivative producers.
- East Asian supply concentration:Integrated chemical-electronics clusters in Japan and South Korea control qualified electronic-grade output, creating single-source vulnerability for Western buyers.
- Alkylation catalyst degradation:Cyclohexene-to-benzene ratio control limits batch-to-batch consistency below semiconductor thresholds without continuous reactor investment.
Strategic Opportunities
- Indian pharmaceutical formulation expansion:CDSCO batch certification requirements for active pharmaceutical ingredient solvents create sticky demand for import substitution.
- Solid-state battery electrolyte convergence:Polymer-ceramic hybrid formulations require novel high-boiling diluents, opening specification windows beyond liquid electrolyte legacy designs.
- EU Green Deal process incentives:Renewable hydrogen integration into hydrogenation loops qualifies for carbon border adjustment relief, reshaping cost structures for early adopters.
Industry Challenges
- Trace metal analysis capability scarcity:Sub-10 ppb detection requires inductively coupled plasma mass spectrometry investment that mid-scale producers defer.
- Multi-jurisdiction certification timeline compression:Simultaneous EPA TSCA notification, REACH dossier update, and China MEE environmental impact assessment strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyclohexylbenzene Market |
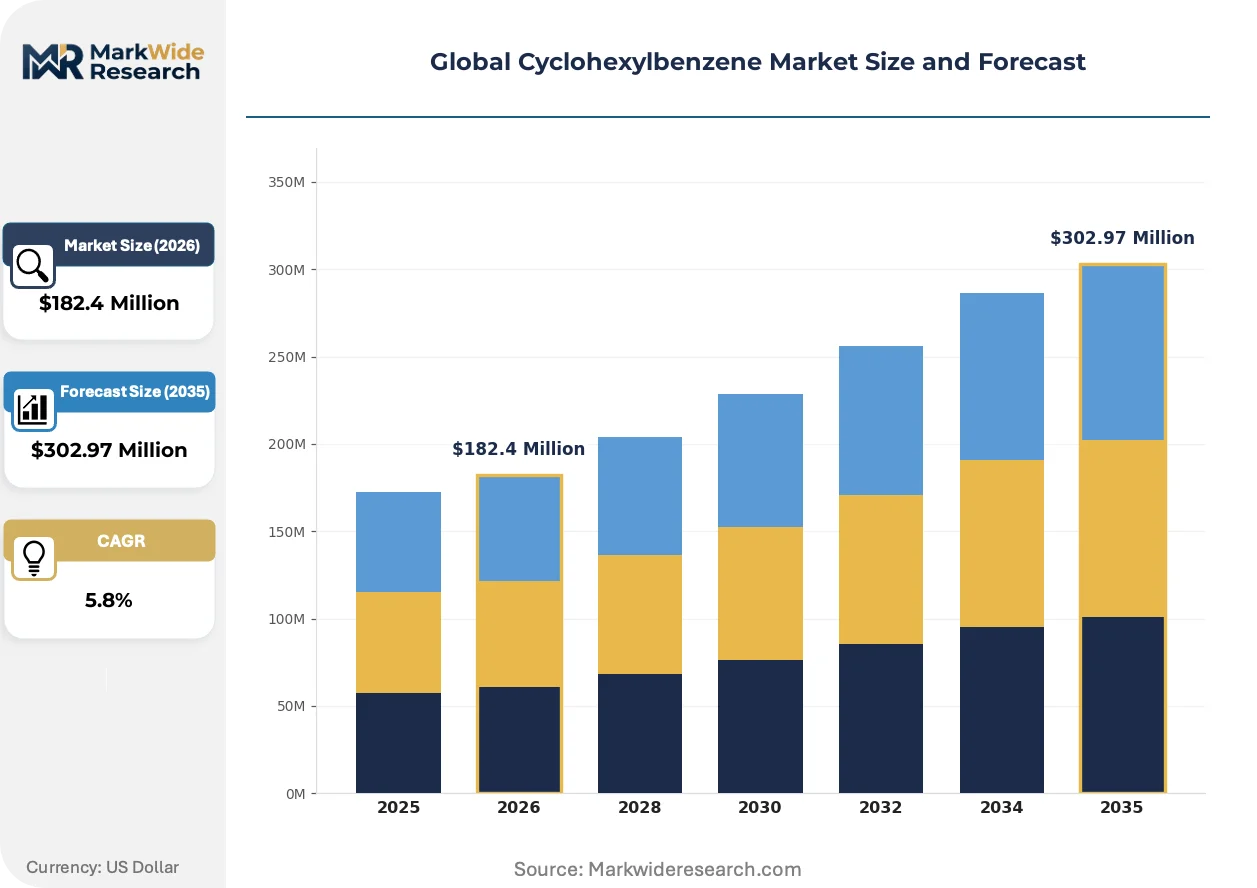
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $302.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Cyclohexylbenzene, Technical Grade, Industrial Grade, Laboratory Grade Application: Intermediate Chemicals, Solvent, Polymer Production, Rubber Additive, Surfactants End Use Industry: Pharmaceuticals, Agrochemicals, Plastics Manufacturing, Paints & Coatings, Detergent Production Packaging Type: Drums, Bulk Containers, Totes, Intermediate Bulk Containers, Composite Packaging |
| Companies Covered | Thermo Fisher Scientific, Sigma Aldrich, BASF SE, Eastman Chemical Company, Tokyo Chemical Industry, Schultz Canada Chemicals Ltd., Biosynth Carbosynth, Kishida Chemical, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyclohexylbenzene Market Shifts & Advancements
Process intensification and specification bifurcation are fragmenting the producer base into semiconductor-grade specialists and commodity-grade survivors, with little middle ground for undifferentiated capacity.
Continuous flow hydrogenation reactor design is modularizing production economics for electronic-grade cyclohexylbenzene. Battery electrolyte additive manufacturers in South Korea and Japan adopt skid-mounted units for 500-ton-per-year campaigns. This architecture compresses capital deployment timelines and enables distributed production closer to downstream formulation facilities.
ECHA's 2024 updated REACH guidance on substance identity for UVCB substances tightens analytical characterization requirements for hydrogenation-derived streams. Producers must now submit full component profiling rather than representative carbon number distributions. Electronic-grade suppliers with existing gas chromatography-mass spectrometry protocols absorb this friction more readily than commodity operators.
Long-term offtake contracting with electrolyte additive formulators is displacing spot market participation for qualified electronic-grade supply. Korean battery material producers lock eighteen-month supply commitments with purity guarantees and audit rights. This preference shift concentrates volume through direct producer-formulator relationships, bypassing traditional chemical distribution channels most visibly in the East Asian supply chain.
Global Cyclohexylbenzene Market Segmentation
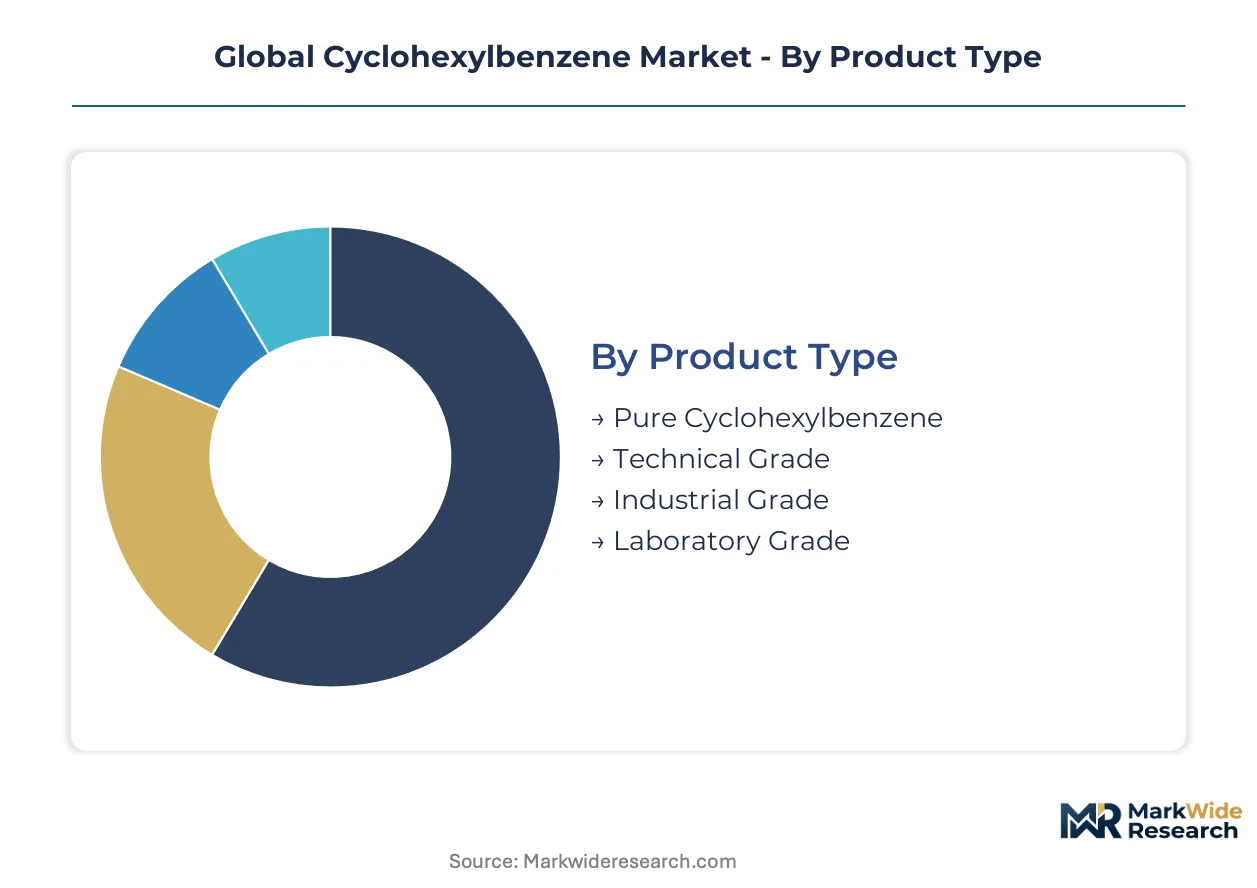
Segmentation in cyclohexylbenzene markets tracks purity thresholds that separate semiconductor-grade premiums from commodity solvent pricing. Investment requirements vary dramatically across grades, with electronic-grade purification demanding capital multiples above industrial specifications.
Product Type:
Capital intensity peaks in segments requiring sub-10 ppb metal content certification and continuous hydrogenation reactor systems.
- Pure Cyclohexylbenzene:Molecular formula C12H16 with boiling point near 240°C, produced through catalytic hydrogenation of biphenyl or alkylation of benzene with cyclohexene. South Korean battery material producers in Seoul and Suwon lock long-term offtake agreements with purity guarantees and audit rights for this grade. Trace metal specifications below 10 ppb command substantial premiums over technical alternatives.
- Technical Grade:Moderate purity suitable for chemical intermediate applications where semiconductor thresholds are unnecessary. Chinese producers in Jiangsu province dominate volume output for this segment, leveraging coal-based aromatics complexes that struggle to meet REACH electronic-grade dossier requirements.
- Industrial Grade:Standard purity for solvent and general chemical applications. BASF SE's Ludwigshafen complex and Eastman Chemical's Kingsport operations supply captive volumes into downstream formulation streams.
- Laboratory Grade:Small-batch certified material for analytical and research applications. Batch certification requirements create supply stickiness through qualified distributor networks in Germany, Japan, and the United States.
Pure Cyclohexylbenzene absorbs the bulk of installed capacity; Laboratory Grade is expanding most quickly.
Application:
Margin pools concentrate where end-users demand batch certification and regulatory dossier compliance across multiple jurisdictions.
- Intermediate Chemicals:Primary conversion pathway into downstream derivatives including phenol and cyclohexanone. Pharmaceutical manufacturers in India under CDSCO oversight drive specification hardening for import substitution campaigns.
- Solvent:High-boiling carrier for coatings and extraction processes. Paints and coatings formulators in Germany and Italy specify this grade under REACH SVHC screening protocols.
- Polymer Production:Stabilizer feedstock for engineering resin formulations. Japanese automotive suppliers in Nagoya and Toyota City specify cyclohexylbenzene-derived additives for thermal stability in under-hood applications.
- Rubber Additive:Processing aid and plasticizer component. Tire manufacturers in Thailand and Indonesia absorb regional supply from Singapore trading hubs.
- Surfactants:Hydrophobic building block for detergent formulations. Procter & Gamble and Unilever procurement teams in Cincinnati and Rotterdam specify this grade for household product lines.
Intermediate Chemicals absorbs the bulk of installed capacity; Polymer Production is climbing the fastest.
End Use Industry:
Customer procurement power varies sharply, with pharmaceutical buyers demanding audit rights and battery material producers locking eighteen-month supply commitments.
- Pharmaceuticals:Solvent for active pharmaceutical ingredient synthesis. FDA and EMA batch certification requirements create multi-year qualification timelines that filter out non-compliant suppliers. Indian CDSCO requirements for import substitution are accelerating domestic capacity announcements.
- Agrochemicals:Intermediate for pesticide and herbicide synthesis. Brazilian ANVISA and Australian APVMA registration timelines stretch 24-36 months for new supplier qualification.
- Plastics Manufacturing:Engineering resin stabilizers and processing aids. German automotive tier suppliers in Stuttgart and Wolfsburg specify this material under OEM chemical compliance protocols.
- Paints & Coatings:High-boiling solvent for industrial finishes. Italian decorative coatings producers in Milan specify low-VOC formulations under EU Green Deal decarbonization targets.
- Detergent Production:Surfactant intermediate for household and industrial cleaners. Procter & Gamble's Cincinnati technical center and Unilever's Rotterdam innovation hub co-develop specifications with qualified suppliers.
Plastics Manufacturing absorbs the bulk of installed capacity; Pharmaceuticals is gaining share fastest.
Packaging Type:
Logistics configuration tracks shipment scale and contamination risk, with electronic-grade material demanding dedicated handling protocols.
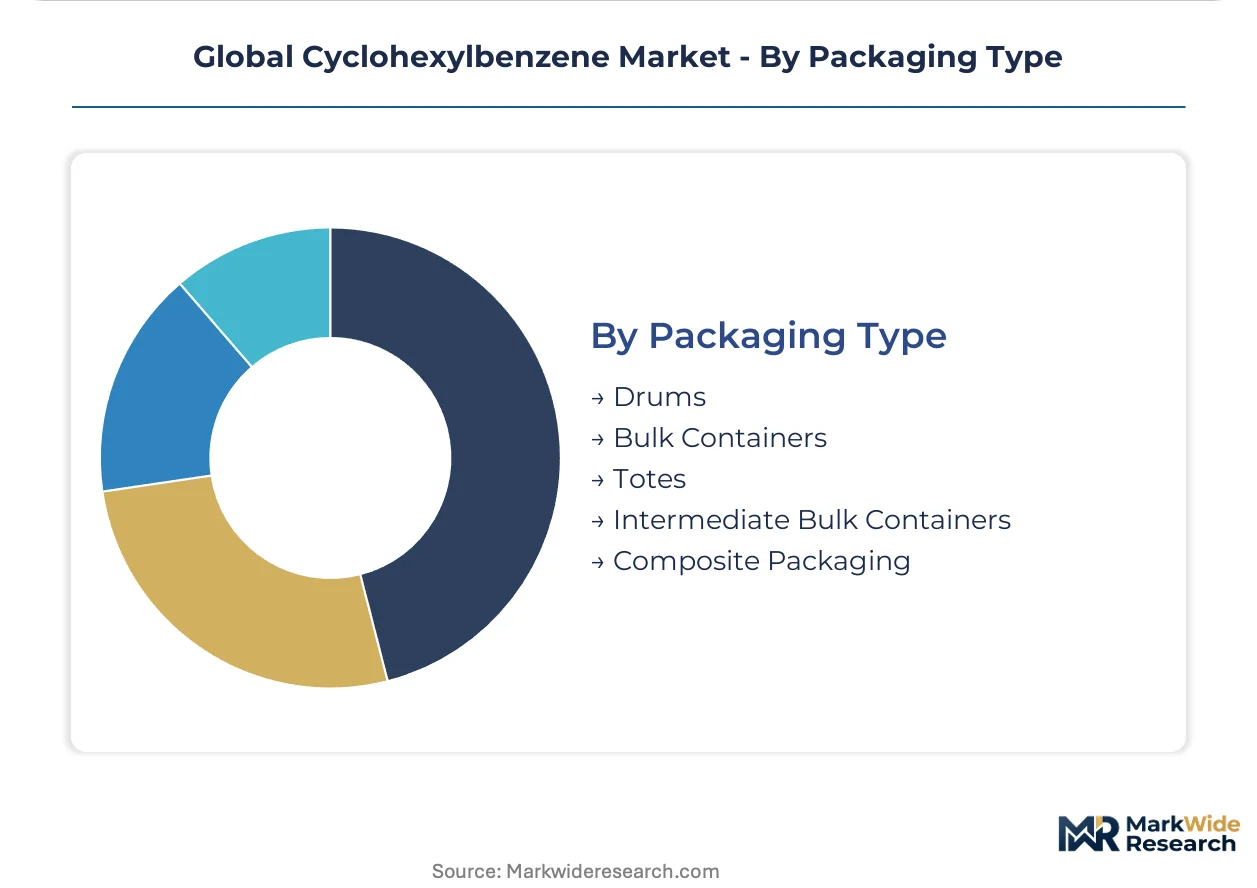
- Drums:Standard 200-liter steel containers for laboratory and small-batch industrial shipments. Pharmaceutical distributors in Switzerland and the Netherlands maintain qualified drum cleaning and certification facilities.
- Bulk Containers:Tank truck and railcar shipments for high-volume chemical intermediate customers. BASF's Ludwigshafen complex ships bulk volumes to downstream formulation sites across Germany and France.
- Totes:Intermediate bulk containers for mid-scale polymer and coatings producers. Japanese chemical distributors in Osaka and Yokohama specify tote fleets with dedicated cleaning validation.
- Intermediate Bulk Containers:Rigid composite containers for agrochemical and detergent compounders. Chinese producers in Shandong province export IBC shipments through Qingdao port to Southeast Asian formulators.
- Composite Packaging:Multi-layer barrier systems for ultra-high-purity electronic-grade material. South Korean battery material producers in Ulsan and Gumi require nitrogen-purged composite packaging with tamper-evident seals.
Bulk Containers absorbs the bulk of installed capacity; Composite Packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Japan, and South Korea concentrate cyclohexylbenzene demand through integrated chemical-electronics supply chains. Battery electrolyte additive specifications from Seoul and Tokyo producers pull global capacity toward electronic-grade certification. Regulatory divergence across EPA, REACH, and China's MEE creates compliance complexity for cross-border suppliers.
China
Jiangsu and Shandong provinces host coal-based aromatics complexes supplying technical-grade material for chemical intermediate applications. The Ministry of Ecology and Environment enforces dual carbon goals that tighten energy-intensity benchmarks for catalytic hydrogenation processes. Qingdao port serves as the primary export hub for IBC shipments to Southeast Asian detergent and agrochemical formulators.
United States
Tennessee's Kingsport operations anchor North American production of performance intermediates for polymer and pharmaceutical applications. EPA oversight under TSCA governs manufacturing and import thresholds with notification requirements for new supply sources. The Southeast chemical corridor connects to battery material formulators seeking qualified electronic-grade supply with trace metal specifications below 10 ppb.
Germany
Ludwigshafen's integrated aromatics complex sustains captive supply of precursor materials for downstream formulation streams. ECHA's REACH registration mandates impose full substance dossier requirements that filter out non-compliant suppliers from European markets. Stuttgart and Wolfsburg automotive tier suppliers specify cyclohexylbenzene-derived stabilizers under OEM chemical compliance protocols.
Japan
Nagoya and Toyota City engineering resin manufacturers incorporate cyclohexylbenzene-derived additives for thermal stability in under-hood automotive applications. METI industrial standards guide purity specifications for electronic-grade material serving semiconductor and battery supply chains. Osaka and Yokohama chemical distributors maintain qualified tote fleets with dedicated cleaning validation for mid-scale polymer producers.
South Korea
Ulsan and Gumi battery material producers lock eighteen-month supply commitments with purity guarantees and audit rights for electronic-grade supply. Seoul and Suwon electrolyte additive formulators adopt skid-mounted continuous flow hydrogenation units for distributed production. The national petrochemical base extends captive supply chains into battery electrolyte formulations through integrated aromatics derivatives.
Global Cyclohexylbenzene Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit hydrogenation assets for semiconductor-grade purity thresholds. The producer base fragments into electronic-grade specialists commanding substantial premiums and commodity-grade survivors competing on volume. Three archetypes define competitive positioning: integrated petrochemical majors with captive aromatics supply, mid-scale hydrogenation specialists serving pharma certification requirements, and regional distributors managing batch-certified laboratory material. Strategic moves concentrate on continuous reactor investment for electronic-grade consistency and long-term offtake contracting with battery electrolyte formulators.
Within the integrated petrochemical tier, BASF SE and LG Chem exemplify divergent geographic anchoring strategies for precursor supply security. Eastman Chemical Company occupies a position bridging performance intermediates and specialty solvent applications. Thermo Fisher Scientific and Sigma Aldrich sit within the analytical-grade distribution archetype, managing batch certification networks for research and quality control laboratories. These named entities represent structural positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sigma Aldrich |
| BASF SE |
| Eastman Chemical Company |
| Tokyo Chemical Industry |
| Schultz Canada Chemicals Ltd. |
| Biosynth Carbosynth |
| Kishida Chemical |
| LG Chem |
| Others |
Supply & Pricing Matrix
High-purity benzene feedstock costs cascade through three distinct pricing tiers as hydrogenation complexity escalates from industrial-grade solvent applications toward semiconductor-battery dual specifications. South Korean battery material producers in Ulsan and Gumi absorb substantial premiums for sub-10 ppb trace metal certification, while Chinese technical-grade output from Jiangsu coal-based aromatics complexes competes on volume at compressed margins.
Pricing Analysis
Volume absorption concentrates in technical-grade material where Chinese producers compete on scale, while margin capture concentrates in pure cyclohexylbenzene where electronic-grade certification commands substantial premiums. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by metal content specification and audit rights bundling. Pricing pressure stems from refinery aromatics output fluctuation with transportation fuel demand, squeezing derivative producer predictability. Pharmaceutical buyers under CDSCO oversight demonstrate lowest price sensitivity due to multi-year qualification timelines, while detergent compounders in Southeast Asia exhibit highest sensitivity to freight-adjusted delivered costs.
Supply Chain Analysis
Refurbishment flows for composite packaging and nitrogen-purged container systems create reverse logistics requirements unique to electronic-grade material handling. Supply concentrates in China, Japan, and South Korea through integrated chemical-electronics clusters that control qualified battery-grade output. Raw material dependencies rest on biphenyl hydrogenation feedstock, cyclohexene alkylation inputs, and catalytic reactor systems. Single-source vulnerability characterizes Western buyer exposure to East Asian electronic-grade capacity. Distribution runs through direct producer-formulator relationships with eighteen-month offtake commitments displacing traditional chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor-grade hydrogenation retrofit bottlenecks prop pricing power for qualified producers as legacy capacity struggles to meet hardening purity thresholds. The supply-constrained structure favors incumbents with existing certification infrastructure and continuous reactor investments.
For Market Incumbents: To counter alkylation catalyst degradation and batch-to-batch consistency failures below semiconductor thresholds, incumbents should prioritize continuous flow hydrogenation reactor deployment and deepen backward integration into captive high-purity benzene supply. BASF SE's Ludwigshafen aromatics complex exemplifies precursor security that buffers feedstock volatility. For New Entrants and Emerging Players: Battery electrolyte formulators in India represent the most penetrable white-space target as CDSCO import substitution campaigns accelerate domestic capacity need. New entrants should pursue laboratory-grade batch certification as a qualification pathway toward pharmaceutical and analytical markets, leveraging distributor networks in Germany and Japan for sticky customer access. For Investors and Strategic Acquirers: Eighteen-month supply commitment announcements from Seoul and Suwon producers are the leading indicator that electronic-grade capacity is tightening faster than retrofit timelines can accommodate. Long-term viability across the projection horizon rests on acquiring mid-scale hydrogenation specialists with existing REACH dossier infrastructure and gas chromatography-mass spectrometry protocols for UVCB substance characterization.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Hydrogenation Reactor Deployment | Modular skid-mounted units in South Korea compress capital timelines for electronic-grade campaigns. |
| Backward Integration into High-Purity Benzene | Captive aromatics supply at Ludwigshafen buffers BASF SE against refinery output volatility. |
| REACH Dossier Completion and Update | ECHA's tightened UVCB characterization requirements filter out non-compliant European competitors. |
| Long-Term Offtake Contracting with Battery Formulators | Korean producers lock eighteen-month commitments with purity guarantees and audit rights. |
| Renewable Hydrogen Integration | EU Green Deal carbon border adjustment relief reshapes cost structures for early hydrogenation adopters. |
Research Methodology
Independent corroboration across plant managers at hydrogenation facilities, procurement leads at downstream battery material producers, distribution channel partners in East Asian chemical trading hubs, and technical R&D directors at electrolyte additive formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed producers, and ECHA REACH registration databases. Bottom-up capacity assessments and top-down demand segmentation triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from value uplift as grade mix shifts toward electronic-grade certification. The analytical framework models segmentation across purity tier, end-use industry, packaging format, and regional production hub. CAGRs derive from installed capacity utilization rates, retrofit investment timelines, and demand pull from lithium-ion battery electrolyte additive specifications. Forecast inputs incorporate energy-intensity benchmark enforcement by China's MEE and evolving EPA TSCA notification requirements.
Several conditions sit outside the modeled scope, including breakthrough solid-state battery electrolyte formulations that eliminate liquid diluent requirements, and radical process innovations that bypass catalytic hydrogenation entirely. Forecasts reflect assumptions about regulatory alignment continuity and feedstock cost trajectories. Practitioners should monitor ECHA guidance updates on substance identity requirements, MEE dual carbon goal enforcement intensity, and Korean battery producer offtake commitment patterns for early signals of structural inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Lignin Waste Market