
 2,6-Dichlorobenzaldehyde Market | 2026-2036
2,6-Dichlorobenzaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
2,6-Dichlorobenzaldehyde Market Analytics
Buyer concentration among agrochemical formulators is hardening as crop-protection multinationals consolidate supplier lists and demand batch-traceable material. Henan Tianfu Chemical Company leverages its central China location to sustain cost-competitive bulk supply. LANXESS AG anchors European quality standards through controlled chlorination processes. Wuhan Dico Chemical Co. Ltd. specializes in custom synthesis for research-grade buyers.
2,6-Dichlorobenzaldehyde is an aromatic aldehyde bearing chlorine substituents at the 2- and 6-positions of the benzene ring, typically synthesized via Vilsmeier-Haack chlorination of salicylaldehyde or direct ring chlorination of benzaldehyde; it serves primarily as a building block for agrochemical active ingredients and pharmaceutical precursors. Industrial grade material dominates volume flows into herbicide intermediate chains, while pharmaceutical grade commands premium positioning due to stringent impurity profiles. The agrochemicals application segment leads absolute offtake, though research-grade supply to contract development organizations is expanding fastest.
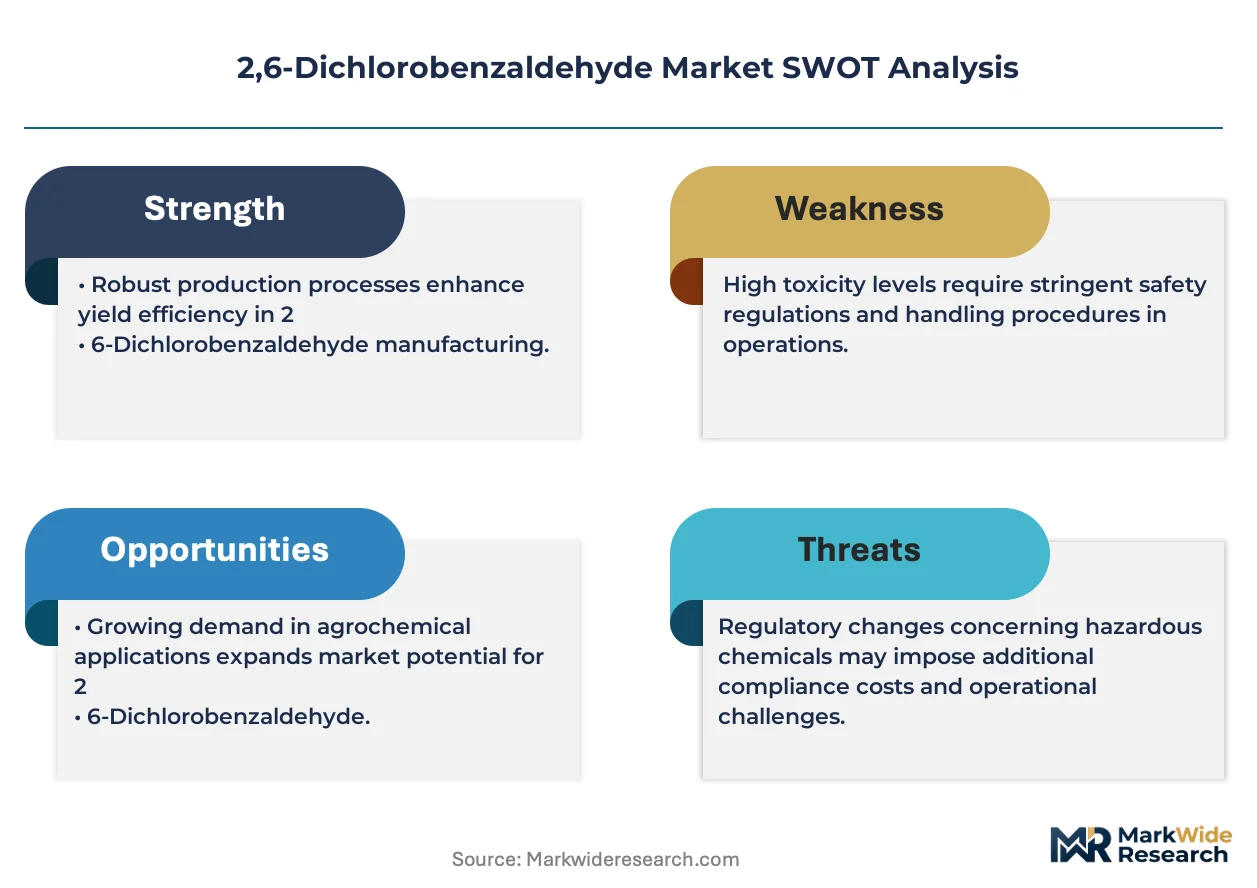
China's MEE enforces wastewater discharge limits on chlorinated aromatic production, raising compliance costs for Jiangsu and Zhejiang manufacturers. The EU REACH framework restricts persistent organic pollutant content in imported chemical intermediates, conditioning market access for Asian exporters. Stakeholders must monitor regulatory divergence between Chinese environmental permitting and European chemical safety authorization to align capacity investments with enforceable demand.
Market Dynamics
China's MEE wastewater discharge mandates are forcing chlorinated aromatic producers toward closed-loop solvent recovery systems, raising fixed cost structures while squeezing marginal Jiangsu and Zhejiang operators out of compliance.
Growth Catalysts
- Herbicide intermediate demand:Pyroxasulfone and other protoporphyrinogen oxidase inhibitors require 2,6-dichlorobenzaldehyde as a core scaffold. Agrochemical formulators in Brazil and India are expanding offtake for pre-emergent weed control.
- REACH authorization pathways:European chemical safety frameworks now permit streamlined intermediate registrations for agrochemical precursors. This regulatory clarity accelerates Asian exporter qualification timelines for EU-bound volumes.
- Yangtze River Delta clustering:Production gravity centers on Jiangsu province, where integrated chlor-alkali complexes provide captive chlorine and caustic soda. Co-location with benzaldehyde feedstock producers compresses logistics costs.
Market Restraints
- Chlorine feedstock volatility:Electrochemical cell maintenance cycles and energy pricing swings create input cost instability. Producers without backward integration into chlor-alkali operations face margin compression during chlorine supply tightness.
- Salicylaldehyde supply concentration:Three Chinese manufacturers control bulk salicylaldehyde output for Vilsmeier-Haack chlorination. This upstream bottleneck exposes 2,6-dichlorobenzaldehyde producers to allocation risk during phenol derivative demand spikes.
- Fluorinated herbicide substitution:Trifluralin and pendimethalin analogs displace chlorinated intermediates in certain crop-protection applications. Resistance management protocols in North American soybean cultivation favor these alternative chemistries.
Strategic Opportunities
- Pharmaceutical-grade custom synthesis:Contract development organizations seek GMP-compliant batches for kinase inhibitor programs. Research-grade pricing premiums exceed industrial material by substantial multiples.
- India agrochemical manufacturing:The PLI scheme subsidizes domestic active ingredient production. Indian formulators are qualifying new intermediate suppliers to reduce dependence on Chinese import streams.
- Continuous flow chlorination:Microreactor technology converges with inline quenching systems. This process intensification reduces solvent inventory and accelerates MEE compliance for wastewater generation.
Industry Challenges
- Halogenation process safety expertise:Exothermic Vilsmeier-Haack reactions require precise temperature control and emergency venting design. Qualified chemical engineers with chlorinated aromatic experience command scarcity premiums in labor markets.
- Batch-record traceability systems:Agrochemical multinationals now mandate electronic data integrity for supplier qualification. Legacy paper-based quality management systems require capital-intensive digitization to meet customer audit standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2,6-Dichlorobenzaldehyde Market |
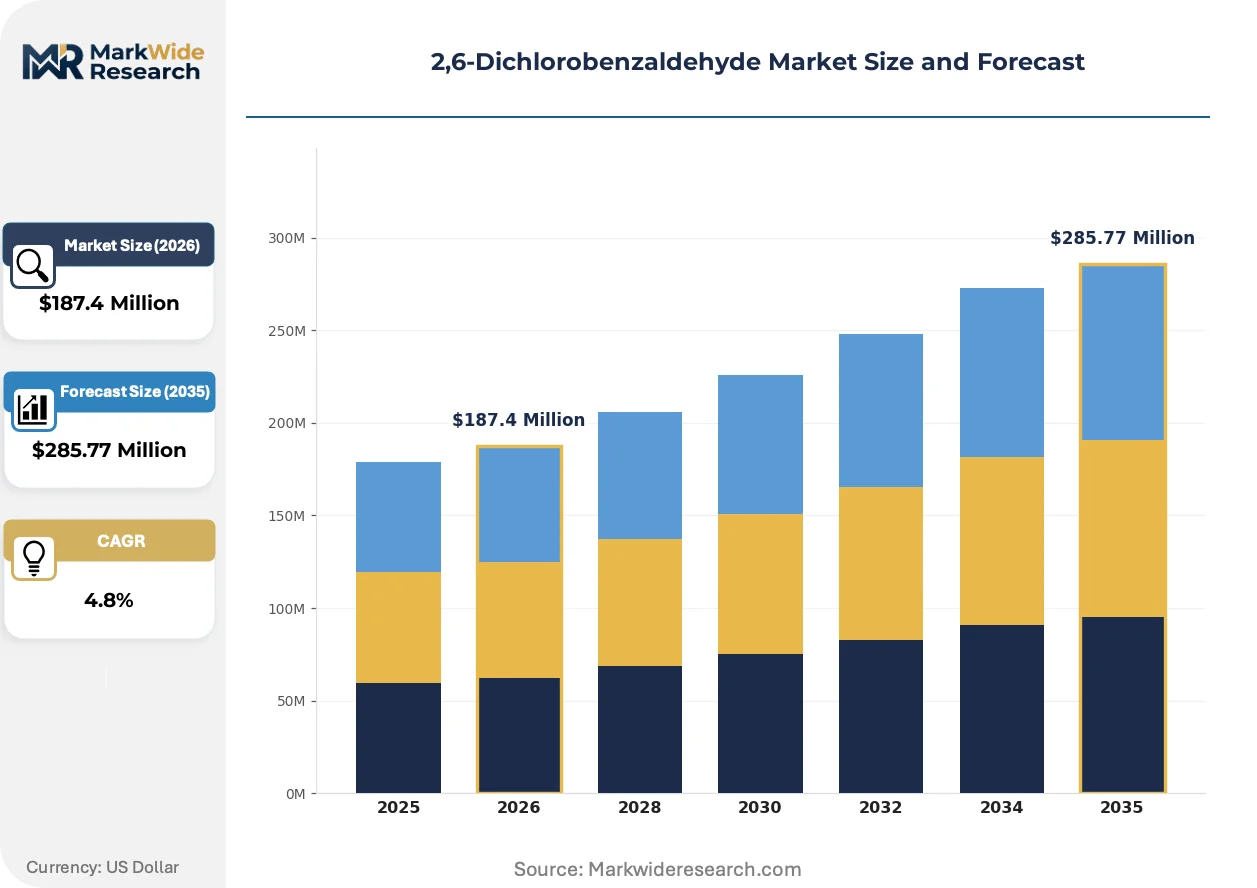
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Research Grade, Pharmaceutical Grade, Food Grade Application: Chemical Intermediates, Agrochemicals, Dyes, Pharmaceuticals End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, Agrochemical Firms Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Daken Chemical Co. Ltd., Dalian Richfortune Chemicals Co. Ltd., Henan Tianfu Chemical Company, ATK Chemical Co. Ltd., Hubei Kelin Bolun New Materials Co. Ltd., Wuhan Dico Chemical Co. Ltd., LANXESS AG, Valtris Specialty Chemicals, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2,6-Dichlorobenzaldehyde Market Evolving Landscape
Catalytic process intensification and regulatory data automation are compressing production economics while reshaping supplier qualification protocols across agrochemical value chains.
Continuous flow microreactor systems for aromatic chlorination are consolidating batch-wise Vilsmeier-Haack production into compact, thermally controlled units. European agrochemical intermediates suppliers adopt these systems to minimize solvent waste generation. The technology is consolidating competitive advantage around producers with capital access for reactor retrofitting.
REACH SCIP database requirements now mandate disclosure of substances of very high concern throughout intermediate supply chains. EU-based formulators demand granular composition data from Asian 2,6-dichlorobenzaldehyde exporters. Research-grade suppliers face the steepest compliance burden due to pharmaceutical customer audit intensity.
Agrochemical procurement teams now require supplier sustainability scorecards alongside technical specifications. Batch-traceable material with verified carbon intensity metrics commands preference in European and North American tender processes. This behavioral shift is most visible in Bayer CropScience and Syngenta supplier consolidation programs.
2,6-Dichlorobenzaldehyde Market Segmentation
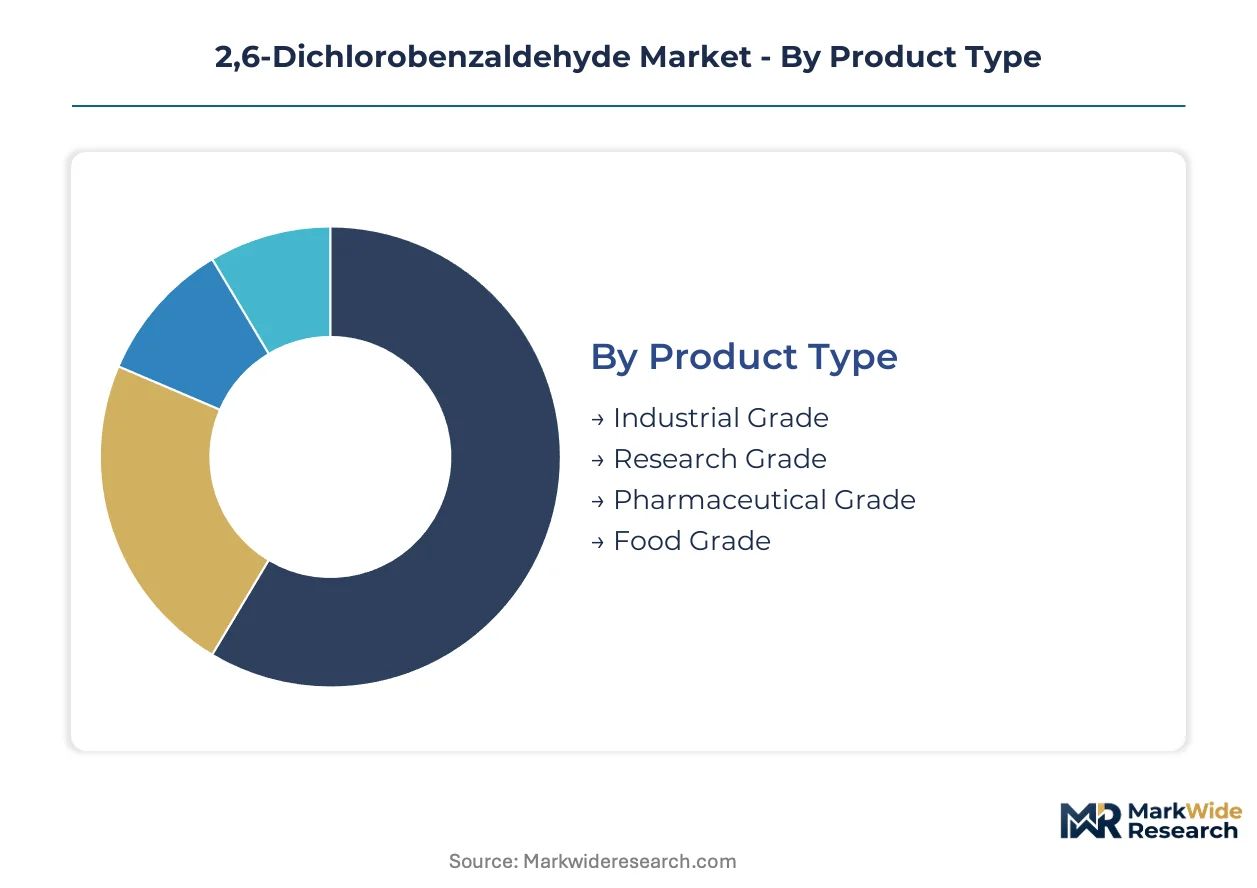
Segmentation in 2,6-dichlorobenzaldehyde markets separates bulk industrial flows from precision-grade supply chains. Each tier commands distinct qualification protocols, pricing architectures, and regulatory documentation burdens.
Product Type:
Standardization intensity varies sharply across this spectrum, with industrial material optimized for throughput and pharmaceutical grade engineered for impurity control.
- Industrial Grade:Material typically carries 98-99% purity with tolerance for minor chlorinated aromatic byproducts. Agrochemical formulators in Brazil and India absorb the largest volumes for herbicide intermediate synthesis, where cost efficiency outweighs trace impurity concerns.
- Pharmaceutical Grade:Specifications demand ≥99.5% purity with rigorous heavy metal and residual solvent limits. GMP-compliant batches serve kinase inhibitor programs at contract development organizations, where documentation packages accompany every lot.
- Research Grade:Small-batch production for academic and institutional laboratories. Wuhan Dico Chemical and specialized Chinese producers dominate this fragmented niche with flexible synthesis protocols.
- Food Grade:Stringent toxicity testing and migration studies apply. Limited current offtake reflects narrow approved applications in flavor and fragrance precursors.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Volume concentration versus value capture defines the strategic calculus across these use cases.
- Agrochemicals:Pyroxasulfone and related protoporphyrinogen oxidase inhibitors depend on this scaffold. Pre-emergent weed control demand in Brazilian soybean cultivation and Indian cotton farming anchors absolute consumption.
- Pharmaceuticals:Kinase inhibitor and antimicrobial precursor applications require custom synthesis capabilities. Research-grade pricing premiums reflect batch-traceable quality management systems.
- Chemical Intermediates:Downstream aromatic transformations for specialty chemical manufacturers. Henan Tianfu Chemical leverages central China logistics to serve this segment cost-competitively.
- Dyes:Pigment and colorant precursor applications in textile and printing industries. Environmental discharge regulations under China's MEE constrain expansion in this category.
Agrochemicals absorb the majority of industrial-grade volume. Pharmaceuticals are gaining share fastest.
End User:
Procurement sophistication and technical specification intensity diverge markedly across buyer categories.
- Agrochemical Firms:Bayer CropScience and Syngenta consolidate supplier lists and mandate sustainability scorecards. Batch-traceable material with verified carbon intensity metrics commands tender preference.
- Pharmaceutical Companies:Electronic data integrity requirements and audit-ready quality management systems define qualification. Legacy paper-based systems face capital-intensive digitization pressure.
- Chemical Manufacturers:Intermediate processors seeking feedstock for downstream chlorinated aromatic production. Price sensitivity dominates procurement criteria.
- Research Institutions:Small-volume, high-variability demand from universities and national laboratories. Custom synthesis flexibility outweighs unit cost considerations.
Most procurement volume routes through Agrochemical Firms. Research Institutions are expanding order frequency most rapidly.
Distribution Channel:
Channel selection reflects order scale, geographic reach, and technical service requirements.
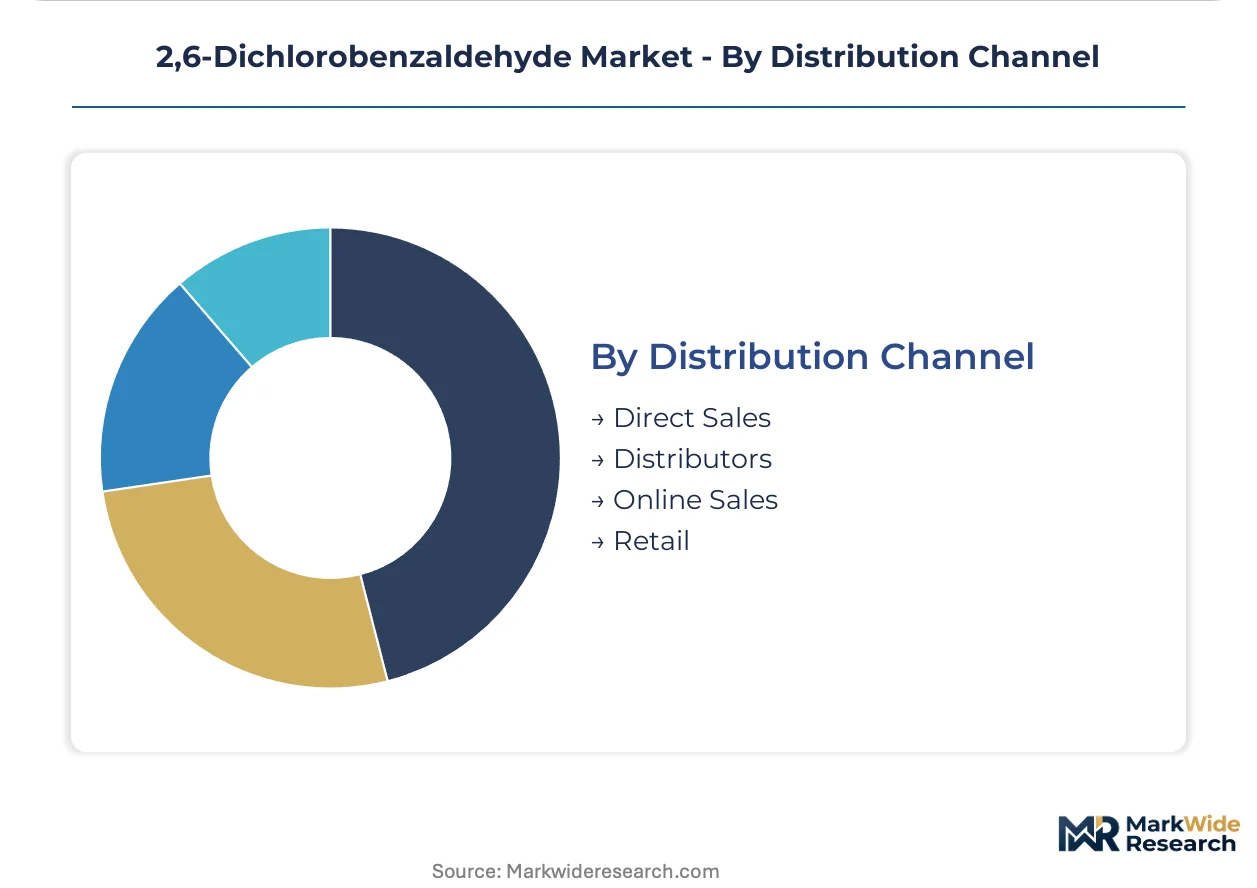
- Direct Sales:Bulk contracts between producers and agrochemical multinationals. LANXESS AG and major Chinese manufacturers maintain dedicated account teams for strategic relationships.
- Distributors:Regional chemical distributors aggregate demand from mid-size formulators and compounders. Inventory positioning in Rotterdam and Singapore hubs serves European and Asian markets.
- Online Sales:E-procurement platforms for research-grade and small-batch industrial orders. Alibaba and specialty chemical marketplaces facilitate spot transactions.
- Retail:Minimal relevance for this intermediate; limited to laboratory supply houses serving academic end users.
Direct Sales channels handle the largest tonnage. Online Sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the majority of 2,6-dichlorobenzaldehyde production capacity, while Germany anchors European quality certification for agrochemical intermediates. India is accelerating import substitution through domestic manufacturing incentives. Brazil's pre-emergent herbicide demand drives South American offtake. The United States maintains strict EPA registration requirements for chlorinated aromatic imports.
China
Agrochemical formulators in Jiangsu and Zhejiang provinces absorb the largest industrial-grade volumes for pyroxasulfone synthesis. MEE wastewater discharge mandates under the Yangtze River Economic Belt protection scheme are forcing chlor-alkali integrated producers toward closed-loop solvent recovery. The Nantong chemical cluster concentrates Vilsmeier-Haack chlorination capacity alongside captive benzaldehyde feedstock supply.
Germany
REACH authorization pathways for agrochemical precursors are streamlining intermediate registrations from Asian exporters. ECHA's SCIP database requirements now mandate granular substance disclosure throughout supply chains. The Leverkusen chemical corridor anchors European quality standards through controlled chlorination process expertise and batch-traceable documentation systems.
India
PLI scheme subsidies are accelerating domestic active ingredient production for crop protection formulators. CDSCO import regulations for pharmaceutical-grade intermediates require GMP compliance verification for custom synthesis batches. The Gujarat chemical belt around Vadodara and Ankleshwar is consolidating chlorinated aromatic manufacturing for export-oriented agrochemical supply.
Brazil
Pre-emergent weed control demand in Mato Grosso and Goiás soybean cultivation anchors pyroxasulfone intermediate consumption. ANVISA residue monitoring protocols for chlorinated aromatics in food crops condition import specifications. The São Paulo state chemical processing hub serves as the distribution nexus for South American agrochemical formulation networks.
United States
EPA registration requirements under FIFRA govern chlorinated aromatic intermediate imports for domestic herbicide synthesis. OSHA process safety management standards enforce rigorous documentation for Vilsmeier-Haack reaction handling. The Texas Gulf Coast petrochemical corridor provides captive chlorine feedstock for specialty chemical manufacturers serving North American agrochemical markets.
2,6-Dichlorobenzaldehyde Market Competitive Landscape
Chinese producers anchor the industrial-grade volume tier; European specialists hold premium certification positions for pharmaceutical and research-grade supply. Market structure tilts toward geographic concentration with three to five major chlor-alkali integrated operators commanding bulk flows. Strategic archetypes separate into backward-integrated commodity suppliers, GMP-certified custom synthesis houses, and research-grade boutique operators. Competitive moves center on capacity rationalization for MEE compliance and REACH registration investments for EU market access.
Among Chinese chemical manufacturers, Henan Tianfu Chemical Company and Wuhan Dico Chemical Co. Ltd. occupy distinct positioning archetypes within the supplier base. LANXESS AG represents the European quality-tier anchor with controlled process expertise. These three entities exemplify the geographic and grade-based stratification that defines procurement decisions for agrochemical multinationals.
| Leading Market Players |
|---|
| Daken Chemical Co. Ltd. |
| Dalian Richfortune Chemicals Co. Ltd. |
| Henan Tianfu Chemical Company |
| ATK Chemical Co. Ltd. |
| Hubei Kelin Bolun New Materials Co. Ltd. |
| Wuhan Dico Chemical Co. Ltd. |
| LANXESS AG |
| Valtris Specialty Chemicals |
| Sigma-Aldrich |
| Others |
Value Network & Pricing Analysis
China's MEE wastewater discharge mandates under the Yangtze River Economic Belt protection scheme gate both qualified supply and premium-tier pricing access, forcing chlorinated aromatic producers toward closed-loop solvent recovery systems that bifurcate the market into compliance-capable premium suppliers and squeezed marginal operators.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for industrial-grade material as chlor-alkali integrated producers exploit captive benzaldehyde feedstock supply. Three-tier pricing structure across pharmaceutical, industrial, and research grades reflects purity certification and documentation intensity. Cost compression in standard industrial tiers is intensifying because MEE compliance investments raise fixed cost structures for non-integrated Jiangsu and Zhejiang manufacturers. Agrochemical formulators in Brazil and India show highest price sensitivity, while contract development organizations for kinase inhibitor programs absorb substantial premiums for GMP-compliant batches.
Supply Chain Analysis
Salicylaldehyde supply rests on three Chinese manufacturers controlling bulk output for Vilsmeier-Haack chlorination, creating upstream bottleneck exposure for 2,6-dichlorobenzaldehyde producers. Production concentrates in China, Germany, and India, with European REACH-registered material commanding qualification premiums. Chlorine feedstock, benzaldehyde derivatives, and specialized chlorination catalysts constitute critical input dependencies. Single-source vulnerability in salicylaldehyde allocation during phenol derivative demand spikes poses structural risk. Distribution runs through direct bulk contracts for agrochemical multinationals, regional chemical distributors in Rotterdam and Singapore hubs, and e-procurement platforms for research-grade spot orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2,6-Dichlorobenzaldehyde Market functions as a stable compounder anchored by enduring herbicide intermediate demand for protoporphyrinogen oxidase inhibitors in Brazilian soybean and Indian cotton cultivation.
For Market Incumbents: Lock in backward integration into chlor-alkali operations to neutralize chlorine feedstock volatility and MEE compliance cost pressures. Consolidate supplier qualification relationships with Bayer CropScience and Syngenta by deploying batch-traceable electronic data integrity systems that satisfy tightening sustainability scorecard requirements. Capacity rationalization for environmental permitting, not expansion, secures positioning against fluorinated herbicide substitution threats in North American markets. For New Entrants and Emerging Players: India's PLI scheme subsidies for domestic active ingredient production open a window for qualifying new intermediate suppliers to reduce Indian formulator dependence on Chinese import streams. Target pharmaceutical-grade custom synthesis for contract development organizations, where GMP compliance barriers deter commodity competition and pricing premiums exceed industrial material by multiples. Establish flexible microreactor-based production to accelerate MEE wastewater compliance without legacy fixed asset burdens. For Investors and Strategic Acquirers: Roll-up economics work for GMP-certified custom synthesis houses because pharmaceutical customer audit intensity and documentation requirements create sticky, long-term relationships with high switching costs. Focus acquisition screening on Jiangsu and Zhejiang operators with existing MEE permits and chlor-alkali integration potential. Watch for salicylaldehyde supply allocation disruptions as inflection indicators that would compress margins for non-integrated producers and accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine supply neutralizes feedstock volatility and MEE compliance cost pressures. |
| GMP Certification Investment | Pharmaceutical-grade qualification unlocks kinase inhibitor program pricing premiums at contract development organizations. |
| Continuous Flow Microreactor Adoption | Process intensification reduces solvent inventory and accelerates Yangtze River Economic Belt wastewater compliance. |
| REACH Registration Completion | ECHA authorization streamlines EU market access for Asian exporter qualification timelines. |
| Electronic Data Integrity Deployment | Batch-traceable quality management satisfies Bayer CropScience and Syngenta supplier audit requirements. |
Research Methodology
Multiple input streams — primary interviews with chlorinated aromatic plant managers, agrochemical procurement leads, and contract development organization technical directors, alongside secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings from disclosed chemical manufacturers — were reconciled through bottom-up and top-down triangulation to construct segment-level volume and value estimates.
Historical production and trade flow patterns were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points. Chlor-alkali capacity utilization rates and herbicide active ingredient registration timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement intensity variations and salicylaldehyde supply allocation disruptions. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and agrochemical formulator consolidation behavior. A small set of named triggers — fluorinated herbicide substitution acceleration, REACH authorization pathway modifications, and Indian PLI scheme subsidy revisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Sorbic Acid Market