
 Phosphorus and Derivatives Market | 2026-2036
Phosphorus and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorus and Derivatives Market Intelligence
The replacement of halogenated flame retardants with organophosphorus compounds is shifting product economics in the electronics and textile industries. ICL Group leverages its specialized portfolio in this transition, focusing on high-margin applications. Hubei Xingfa Chemicals Group competes on manufacturing scale and cost leadership in elemental phosphorus production. These dynamics create distinct competitive positioning for integrated producers versus specialists.
Phosphorus is a highly reactive nonmetal element, existing in several allotropic forms, primarily white and red phosphorus. Its derivatives, such as phosphoric acid and various phosphates, are produced mainly through the wet process or thermal process from phosphate rock. The fertilizers application continues to dominate volume, though with mature growth characteristics. In contrast, organophosphorus compounds used as flame retardants and food additives represent higher-margin, specialized product categories.
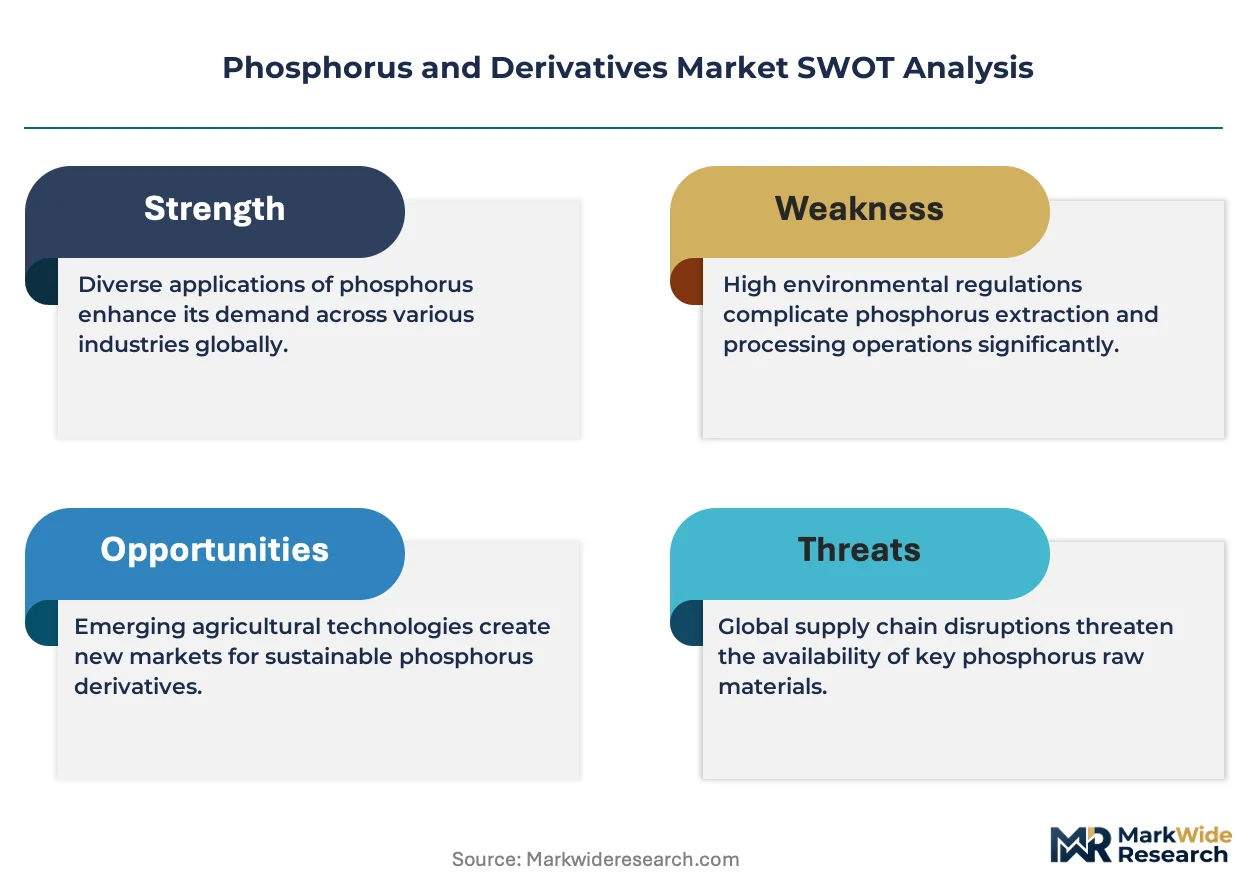
Environmental regulations, including the US EPA's nutrient criteria and the EU's REACH framework managed by ECHA, govern the use of phosphates in detergents and agriculture. China's Ministry of Ecology and Environment (MEE) imposes strict standards on phosphorus discharge from industrial facilities. Navigating geopolitical concentration of phosphate rock reserves and evolving circular economy mandates will be critical for long-term supply chain strategy.
Market Dynamics
The central dynamic is a divergence between high-volume, low-margin fertilizer applications and high-value, technology-driven specialty segments. Environmental regulations on nutrient discharge and circular economy principles are simultaneously constraining traditional production while creating new phosphorus recovery value chains, fundamentally altering supply-side economics.
Growth Catalysts
- Circular Economy Mandates:European Union policies promoting resource recovery are spurring investment in technologies to reclaim phosphorus from municipal wastewater and agricultural runoff, creating localized, secondary supply sources for industrial and fertilizer use.
- Electronics Sector Demand:The transition to non-halogenated flame retardants in consumer electronics and data center hardware drives consumption of high-purity organophosphorus compounds, which offer superior thermal stability and performance.
- Chinese Manufacturing Scale:The concentration of chemical production in industrial clusters within China provides significant economies of scale for elemental phosphorus and its primary derivatives, lowering baseline costs for global supply chains.
Market Restraints
- Phosphate Rock Volatility:Price fluctuations and logistical challenges for phosphate rock, the primary raw material, create significant input cost uncertainty for producers of phosphoric acid and downstream derivatives.
- Geopolitical Supply Risk:The high concentration of global phosphate rock reserves in a limited number of countries, particularly Morocco and Western Sahara, exposes the supply chain to geopolitical instability and trade policy shifts.
- Regulatory Compliance Burden:The European Union's REACH framework imposes extensive testing and registration requirements on phosphorus compounds, increasing development costs and potentially restricting market access for certain chemicals.
Strategic Opportunities
- Battery Materials Application:The expanding electric vehicle market creates a significant opportunity for high-purity phosphoric acid as a key precursor for lithium iron phosphate (LFP) cathode materials, a fast-growing battery chemistry.
- Phosphorus Recovery Technology:Developing and licensing advanced struvite precipitation or ion exchange systems for phosphorus recovery from waste streams offers a new revenue model for technology providers and water treatment operators.
- Semiconductor Grade Purity:Meeting the stringent purity requirements for phosphoric acid used in semiconductor fabrication as an etchant represents a high-margin niche for suppliers with advanced purification and quality control capabilities.
Industry Challenges
- Capital-Intensive Infrastructure:The construction or retrofitting of wet process or thermal process phosphoric acid plants to meet modern environmental standards requires substantial capital investment and long project timelines.
- Navigating Divergent Regulations:Producers face operational complexity in complying with varying phosphorus discharge limits and product safety standards set by different authorities like the US EPA and China's MEE.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorus and Derivatives Market |
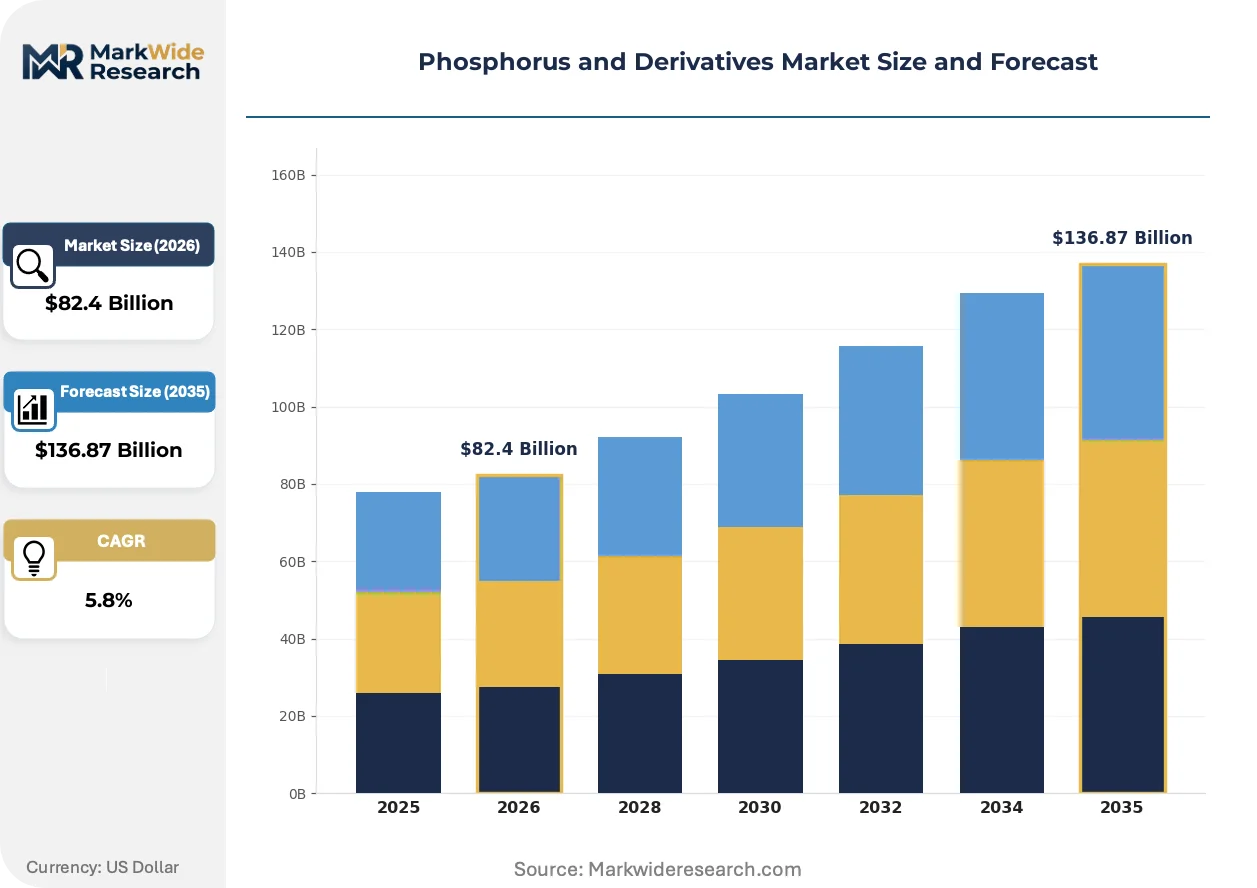
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $136.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elemental Phosphorus, Phosphoric Acid, Phosphates, Organophosphorus Compounds, Inorganic Phosphorus Derivatives Application: Fertilizers, Flame Retardants, Water Treatment, Metal Treatment, Food Additives, Pesticides End User Industry: Agribusiness, Chemical Manufacturing, Textile Processing, Electronics Fabrication, Pharmaceuticals Form: Liquid, Solid, Powder, Granules, Crystals |
| Companies Covered | OCP S.A., The Mosaic Company, Hubei Xingfa Chemicals Group, EuroChem Group AG, Yara International ASA, Sichuan Chuantou Chemical Industry Group, Nutrien Ltd., ICL Group, Jiangsu Chengxing Phosph-Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorus and Derivatives Market Strategic Shifts & Innovations
Material science advancements are bifurcating the market, creating a distinct separation between commodity phosphates and high-performance organophosphorus specialties. This evolution is driven by sustainability pressures and the technical demands of advanced industries, forcing a re-evaluation of production processes and supply chain traceability.
Advanced process control software provides real-time monitoring and adjustment for phosphoric acid production. Chemical manufacturers are adopting these systems to improve reaction efficiency, control purity levels, and reduce energy consumption. The implementation of digital twins for production lines is automating the optimization of temperature, pressure, and reagent flows, minimizing waste and manual oversight.
The EU Green Deal and its associated policies, such as the Circular Economy Action Plan, are directly impacting phosphorus sourcing and usage. These regulations incentivize the use of recycled phosphorus from sources like sewage sludge ash and manure, creating a new class of "green" phosphate products. The fertilizer and detergent sectors are most affected, now competing for certified recycled content to meet sustainability targets.
A shift toward supply chain transparency is altering buying behavior for food-grade phosphates and specialty additives. End-users in the food and beverage industry are demanding verifiable proof of origin and adherence to ethical sourcing standards for raw phosphate rock. This disrupts traditional commodity purchasing models and benefits suppliers who can provide detailed lifecycle and traceability data, a trend most visible in North America and Europe.
Phosphorus and Derivatives Market Segmentation
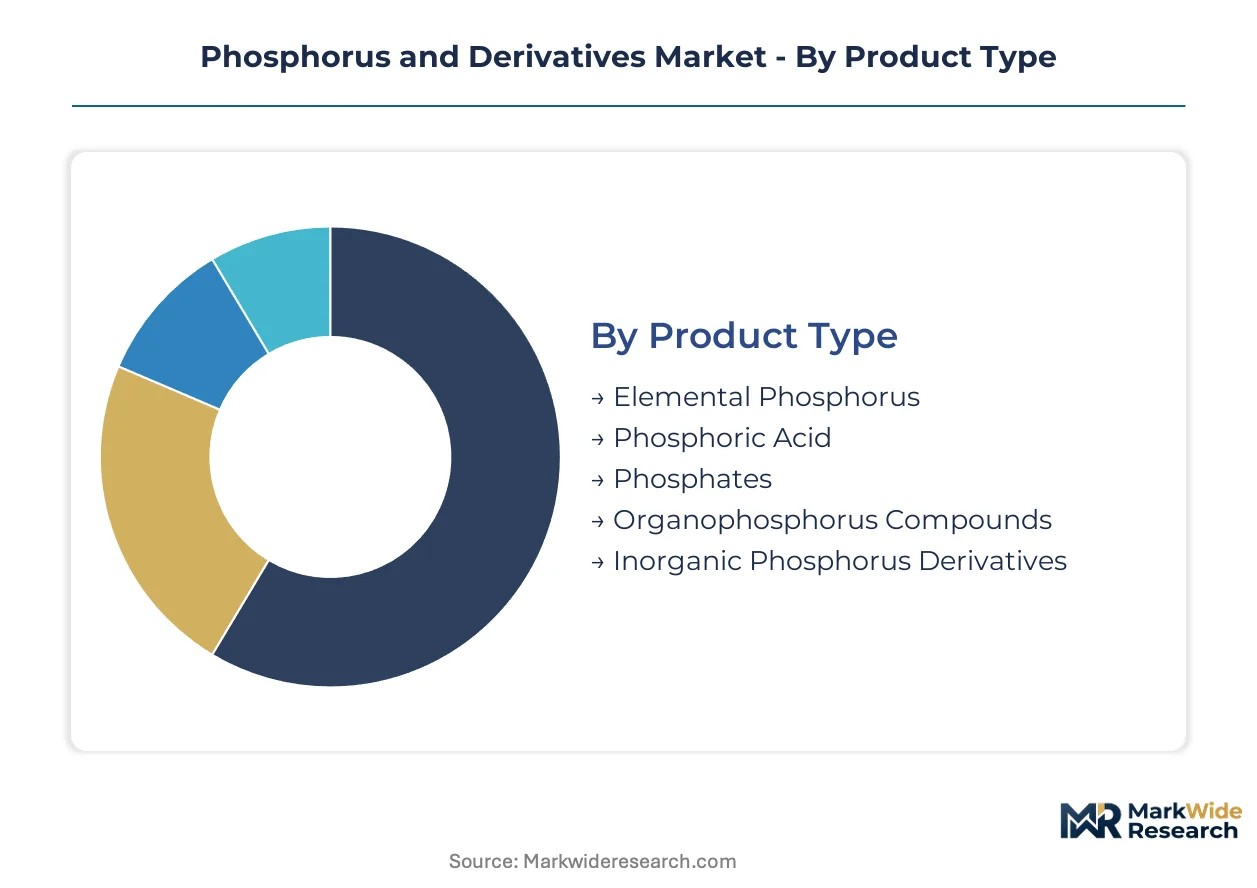
The segmentation analysis for the phosphorus and derivatives market highlights distinct product categories, diverse applications, and varied end-user industries. Understanding these segments is critical for producers to tailor product offerings, optimize supply chains, and identify high-growth niches. Form factors also influence handling, storage, and final product integration.
Product Type:
The product type segmentation distinguishes between standalone phosphorus compounds and those primarily integrated into complex chemical systems.
- Phosphoric Acid:This inorganic acid, typically produced via the wet process, serves as a fundamental precursor for fertilizers and industrial phosphates. Demand for high-purity grades is concentrating in Asia for lithium iron phosphate battery cathode production.
- Organophosphorus Compounds:These carbon-containing phosphorus derivatives offer tailored properties for specialized applications like flame retardants and pesticides. The electronics fabrication sector, particularly in China and Southeast Asia, drives consumption for non-halogenated flame retardant solutions.
- Elemental Phosphorus:A highly reactive nonmetal, primarily white or red phosphorus, used as a chemical intermediate.
- Phosphates:These salts of phosphoric acid include various forms like monocalcium phosphate and sodium tripolyphosphate, essential for detergents and food additives.
- Inorganic Phosphorus Derivatives:This category encompasses various non-carbon-containing compounds beyond phosphoric acid and phosphates, often used in water treatment.
Phosphoric Acid leads volumes today; Organophosphorus Compounds are gaining share fastest.
Application:
The application landscape reveals a broad spectrum of uses, ranging from high-volume commodity sectors to specialized, performance-driven niches.
- Fertilizers:Phosphorus-based fertilizers, such as diammonium phosphate (DAP) and monoammonium phosphate (MAP), are crucial for global agricultural productivity. Demand remains robust across major agricultural regions, including Brazil and India, to support crop yields.
- Flame Retardants:These phosphorus derivatives, particularly organophosphorus compounds, are incorporated into plastics, textiles, and electronics to inhibit combustion. European regulations, like REACH, accelerate the shift towards non-halogenated options.
- Water Treatment:Phosphates are utilized in municipal and industrial water treatment to sequester metal ions and inhibit corrosion.
- Metal Treatment:Phosphorus compounds serve as surface treatment agents, providing corrosion resistance and adhesion promotion for metals.
- Food Additives:Phosphates act as leavening agents, emulsifiers, and pH regulators in various food and beverage products, ensuring texture and preservation.
- Pesticides:Organophosphorus compounds are widely used as insecticides and herbicides in agriculture, protecting crops from pests.
Demand for Fertilizers remains foundational, while Flame Retardants exhibit robust expansion.
End User Industry:
End-user industries vary significantly in their maturity and growth profiles, influencing demand stability and innovation requirements for phosphorus derivatives.
- Agribusiness:This sector represents the largest consumer of phosphorus, primarily for crop nutrition and soil amendment. Large-scale farming operations in North America and South America drive consistent demand for phosphate fertilizers.
- Electronics Fabrication:The electronics industry uses high-purity phosphoric acid for etching and organophosphorus compounds as flame retardants in devices. Asian electronics manufacturing hubs, particularly in South Korea and Taiwan, require stringent material specifications.
- Chemical Manufacturing:This industry utilizes phosphorus derivatives as intermediates for synthesizing a wide array of specialized chemicals.
- Textile Processing:Phosphorus compounds are employed in textile finishing for flame retardancy and other functional properties.
- Pharmaceuticals:Phosphorus derivatives find applications in drug synthesis, excipients, and nutritional supplements within the pharmaceutical sector.
The Agribusiness sector represents a stable base, with the Electronics Fabrication sector demonstrating dynamic growth.
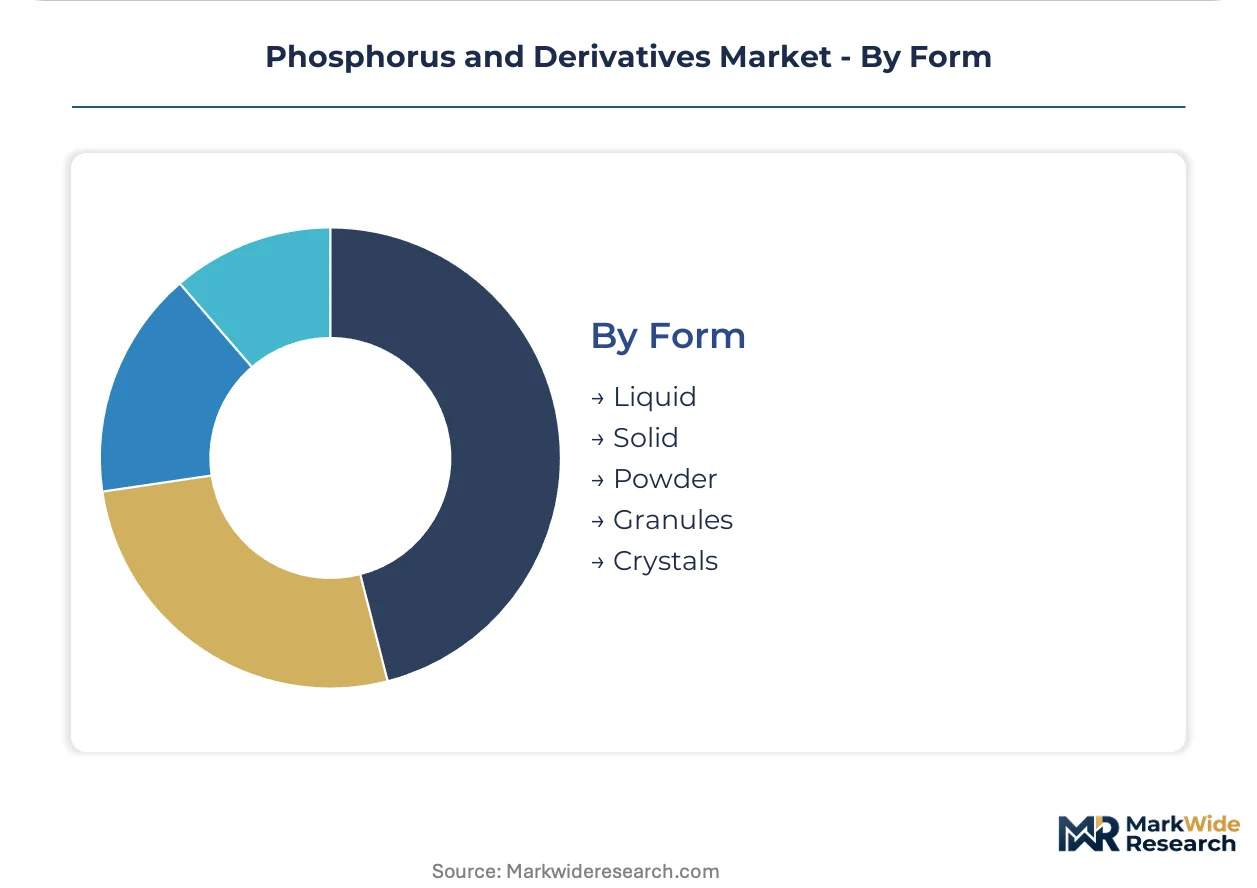
Form:
The physical form of phosphorus and its derivatives dictates handling, transportation logistics, and suitability for specific manufacturing processes.
- Liquid:Liquid forms, predominantly phosphoric acid solutions, offer ease of pumping, mixing, and precise dosing in industrial processes. Large-scale chemical production facilities in China rely heavily on liquid bulk deliveries.
- Solid:Solid forms encompass a wide range of products, including phosphate rock, granular fertilizers, and powdered specialty chemicals. Their stability and ease of storage make them suitable for diverse applications.
- Powder:Powdered phosphorus compounds are used where high surface area or rapid dissolution is required, such as in food additives or certain chemical reactions.
- Granules:Granular forms, particularly for fertilizers, offer controlled release characteristics and improved handling for agricultural spreading.
- Crystals:Crystalline phosphorus derivatives are often high-purity specialty chemicals used in sensitive applications like pharmaceuticals or electronics.
Bulk transport relies on Liquid forms, while Granules cater to specific agricultural spreading processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical manufacturing clusters drive global phosphorus and derivatives production, influencing supply chain dynamics and cost structures worldwide. This market exhibits diverse regional demand patterns, driven by agricultural needs, electronics manufacturing, and stringent environmental regulations. Specific countries demonstrate unique growth trajectories and regulatory landscapes for phosphorus compounds.
China
Demand for elemental phosphorus and organophosphorus compounds for electronics fabrication remains strong in China. The Ministry of Ecology and Environment (MEE) imposes strict standards on phosphorus discharge from industrial facilities. Chemical manufacturing clusters in regions like the Yangtze River Delta continue to provide significant economies of scale for global supply chains.
United States
Agricultural productivity and water treatment applications drive significant demand for phosphorus derivatives in the United States. The US EPA's nutrient criteria influence the use of phosphates in various industrial and municipal processes. Chemical complexes along the Gulf Coast concentrate phosphoric acid production for domestic and international markets.
Germany
Specialty chemical applications and advanced materials propel the market for high-purity organophosphorus compounds in Germany. The EU REACH framework and Green Deal policies incentivize the use of recycled phosphorus content. Chemical parks in the Rhine-Ruhr region focus on producing high-value derivatives for European industries.
Brazil
Agricultural demand for phosphate fertilizers, including DAP and MAP, anchors phosphorus consumption in Brazil. National agricultural policies support crop yields and ensure consistent demand from large-scale farming operations. The São Paulo and Mato Grosso regions are central to fertilizer distribution and application across agricultural lands.
South Korea
Electronics fabrication, particularly for high-purity phosphoric acid and non-halogenated flame retardants, fuels growth in South Korea. The country's national environmental standards guide industrial discharge limits for phosphorus compounds. Gyeonggi Province electronics manufacturing hubs require stringent material specifications for semiconductor production.
Phosphorus and Derivatives Market Key Industry Players
Global majors compete with regional champions across product portfolios and geographic reach within the phosphorus and derivatives market. The industry structure reflects a tiered landscape, encompassing large-scale integrated producers and specialized manufacturers. Strategic archetypes include high-volume commodity suppliers, niche organophosphorus specialists, and technology providers for phosphorus recovery. Companies pursue competitive moves such as capacity expansion in key production regions and portfolio diversification into higher-margin applications.
At the scale-driven end, Hubei Xingfa Chemicals Group, a Chinese entity, exemplifies cost leadership in elemental phosphorus production. ICL Group represents specialized organophosphorus manufacturers, leveraging its portfolio for high-margin applications like non-halogenated flame retardants. The Mosaic Company, a global agricultural player, anchors the fertilizer segment with its extensive production capacity for phosphate-based nutrients.
| Leading Market Players |
|---|
| OCP S.A. |
| The Mosaic Company |
| Hubei Xingfa Chemicals Group |
| EuroChem Group AG |
| Yara International ASA |
| Sichuan Chuantou Chemical Industry Group |
| Nutrien Ltd. |
| ICL Group |
| Jiangsu Chengxing Phosph-Chemicals |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, with its circular economy mandates, gates qualified phosphorus supply and access to premium-tier pricing for certified recycled content. This dynamic fundamentally shifts economic incentives across the value chain, favoring sustainable sourcing. Supply chain configurations directly influence pricing power for both commodity and specialty phosphorus products.
Pricing Analysis
Input cost pass-through from volatile phosphate rock prices influences phosphoric acid and derivative pricing. The dominant pricing model for commodity phosphates features contract-based long-term offtake agreements. Price differentiation stems from purity grade requirements for electronics fabrication versus fertilizer applications, and certification levels such as REACH compliance. Pricing pressure stems from raw material volatility and environmental compliance costs, particularly for wet process producers. Agribusiness buyers demonstrate the most price sensitivity, while the electronics sector exhibits lower sensitivity for high-purity materials.
Supply Chain Analysis
Certification and qualification gating for high-purity organophosphorus compounds and food-grade phosphates shape supply chain access. Geographic supply concentrates in Morocco for phosphate rock, China for elemental phosphorus and derivatives, and the United States for phosphoric acid production. Raw material dependencies center on phosphate rock and sulfuric acid, critical for wet process production. Geopolitical instability in phosphate rock-rich regions represents a significant supply chain risk. Distribution runs through direct sales channels for large industrial consumers and specialized distributors for niche, high-value applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Phosphorus and Derivatives market functions as a regulatory compounder, with the EU REACH framework specifically driving demand for non-halogenated flame retardants.
For Market Incumbents: Lock in long-term supply agreements for phosphate rock to mitigate raw material volatility. Invest in advanced phosphorus recovery technologies to diversify raw material sourcing and reduce reliance on geopolitical supply. Expand high-purity organophosphorus compound capacity in Asia to meet the growing electronics sector demand, defending against competitive threats from alternative flame retardants. Focus on optimizing existing production assets for energy efficiency and reduced emissions.
For New Entrants and Emerging Players: Digital platforms for traceable, certified recycled phosphorus products offer a market entry point. Target the European fertilizer and detergent sectors seeking "green" phosphate products to meet sustainability targets. Focus on developing and licensing advanced struvite precipitation systems for municipal wastewater treatment, representing a penetrable segment for technology providers. This approach capitalizes on circular economy mandates and creates new revenue streams.
For Investors and Strategic Acquirers: Roll-up economics work for specialized organophosphorus compound manufacturers because the market demands niche capabilities and high-purity production. Acquire firms with proprietary phosphorus recovery technologies to capitalize on circular economy mandates over the next decade. A signal to watch is the increasing adoption rate of lithium iron phosphate (LFP) batteries, indicating sustained demand for high-purity phosphoric acid.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet growing demand for high-purity organophosphorus compounds in electronics fabrication. |
| Backward Integration | Secure stable access to phosphate rock, mitigating raw material supply volatility. |
| Green Manufacturing Transition | Align production processes with EU Green Deal and circular economy principles. |
| Long-term Supply Agreement | Ensure consistent supply of critical raw materials like phosphate rock for producers. |
| Joint Venture | Develop advanced phosphorus recovery technologies with water treatment specialists. |
Research Approach
Bottom-up electronics fabrication modeling reconciled against top-down phosphate rock production tracking forms the analytical core. Primary interviews with plant managers, procurement leads at downstream OEMs, R&D directors, and environmental compliance officers informed the analysis. Secondary data from customs reports, China's MEE environmental disclosures, and chemical industry association publications validated primary insights.
Historical trendline analysis of phosphorus and derivatives consumption established baseline growth rates across the analysis window. Segmentation dimensions modeled include product type, application, end-user industry, and regional production hubs. Compound annual growth rates derived from a weighted average of historical performance and projected demand drivers. Key inputs included global agricultural output forecasts and electronics manufacturing expansion plans over the projection horizon.
Geopolitical shifts, raw material price volatility, and evolving environmental regulations are the dominant revision risks. Forecasts reflect assumptions documented at the time of publication. A model refresh is warranted upon material change in global trade policies or key technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Aluminum Sulfide Market