
 Global Molten Sulfur Market | 2026-2036
Global Molten Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molten Sulfur Market Foresight
Tanker freight contracting between Gulf Coast refineries and Gulf of Mexico port terminals is reconfiguring molten sulfur logistics economics. Marathon Petroleum Corp. leverages its integrated refinery network to control captive sulfur volumes across Texas and Louisiana processing sites. Chevron Corp. anchors West Coast supply through its California refining complex, while Kuwait National Petroleum Co. competes on long-haul bulk shipments into Asian fertilizer corridors.
Molten sulfur is liquid elemental sulfur maintained at temperatures between 115°C and 155°C to preserve fluidity for pumping, storage, and transport; it derives primarily from Claus process recovery at petroleum refineries and natural gas processing plants where hydrogen sulfide is converted to saleable sulfur. Industrial grade product dominates volume flows into sulfuric acid manufacturing for phosphate fertilizer production, while agricultural grade commands tighter impurity specifications for direct soil amendment applications. Chemical Manufacturing as an application segment sustains premium pricing through electronics-grade sulfur requirements, whereas Petroleum Refining as a source segment occupies the largest share of upstream supply origination.
EPA sulfur recovery standards under the Clean Air Act mandate maximum achievable control technology at US refineries, directly shaping molten sulfur output volumes and quality benchmarks. REACH registration requirements in Europe govern sulfur classification and safe handling protocols for cross-border bulk shipments. China's MEE enforces dual carbon goals that tighten refinery emissions limits and expand sulfur recovery unit installation mandates. Stakeholders must monitor evolving refinery run rates and sulfuric acid plant commissioning schedules to anticipate regional supply-demand imbalances.
Market Dynamics
Refinery sulfur recovery unit economics now pivot on hydrogen sulfide feedstock availability from sour crude processing, with US Gulf Coast operators adjusting run rates to balance sulfuric acid offtake against stockpile limits.
Growth Catalysts
- Phosphate fertilizer corridor expansion:Brazilian and Southeast Asian producers are commissioning new sulfuric acid plants to process domestic phosphate rock reserves, pulling molten sulfur volumes into Atlantic and Pacific shipping lanes.
- China's GB standards tightening:Revised industrial sulfur purity specifications under MEE oversight are filtering substandard product from export supply chains, consolidating volume around certified Gulf Coast and Middle Eastern suppliers.
- Claus process optimization:Advanced tail gas treatment technologies at natural gas processing facilities are boosting sulfur recovery rates above 99.8%, expanding merchant sulfur availability without incremental refinery capacity.
Market Restraints
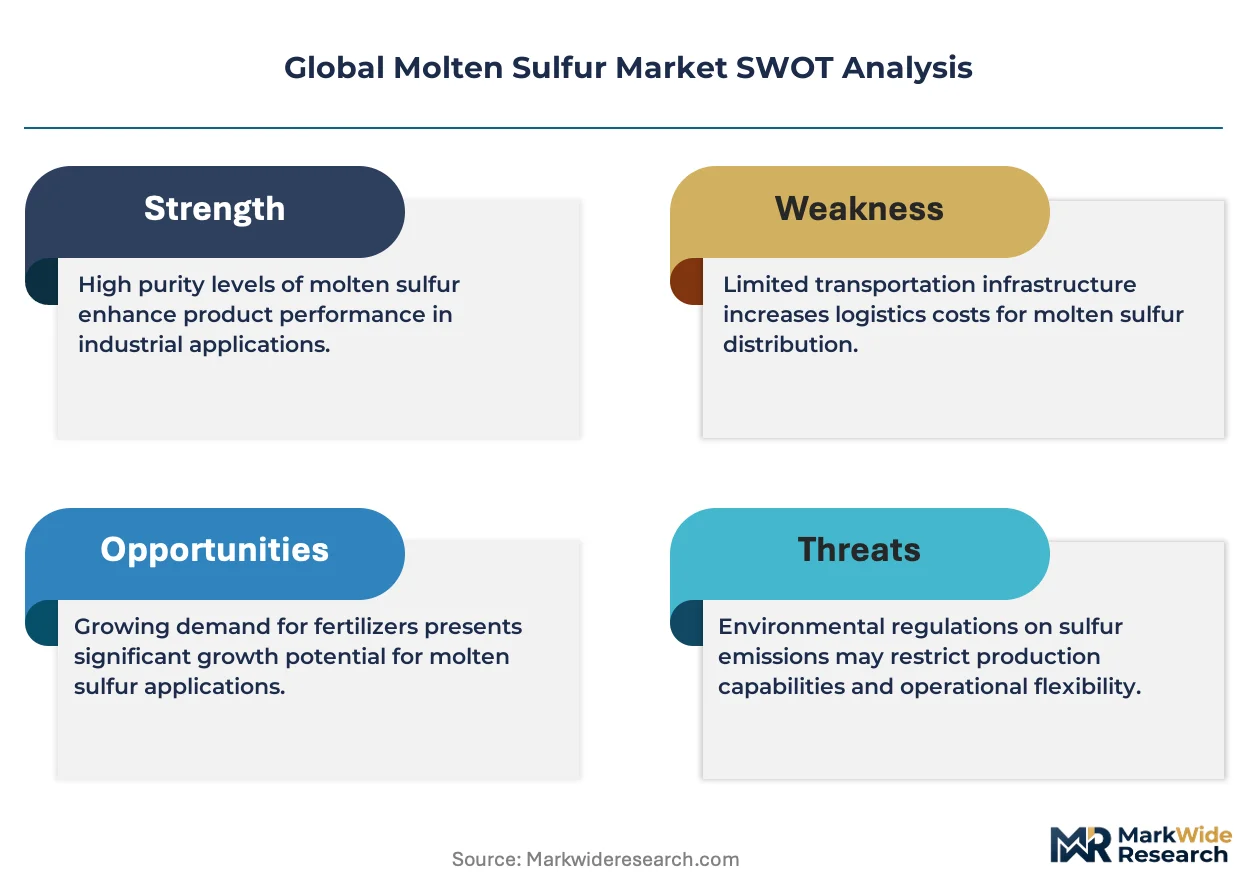
- Sour crude price volatility:Input cost swings for hydrogen sulfide-rich feedstocks compress refinery sulfur recovery margins and destabilize molten sulfur contract pricing.
- Gulf Coast supply concentration:Over 60% of US merchant sulfur originates from Texas and Louisiana refining clusters, creating single-point vulnerability to hurricane disruptions and pipeline outages.
- Solid sulfur substitution:Prilled and granulated sulfur forms are capturing direct-application agricultural demand, bypassing liquid handling infrastructure entirely.
Strategic Opportunities
- India's fertilizer subsidy restructuring:Revised nutrient-based support schemes favor domestic sulfuric acid production, opening import demand for Middle Eastern molten sulfur via Hazira and Paradip port terminals.
- Electronics-grade sulfur purification:Semiconductor chemical manufacturers require ultra-low arsenic and selenium content, commanding 3-4x industrial grade premiums.
- Carbon capture integration:Amine-based CO2 scrubbing at refineries generates incremental hydrogen sulfide streams, enabling sulfur recovery unit feedstock diversification without crude throughput expansion.
Industry Challenges
- Specialized tanker fleet scarcity:Insulated stainless steel vessels with heating coils command day rates 40% above standard chemical tankers, constraining spot market liquidity.
- Cross-border REACH documentation:ECHA registration requirements for sulfur classification create 6-12 month approval delays for new European import channels.
- Legacy storage tank retrofitting:Existing carbon steel tanks require internal coating upgrades to handle tightened GB standard purity specifications, demanding capital deployment without revenue uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molten Sulfur Market |
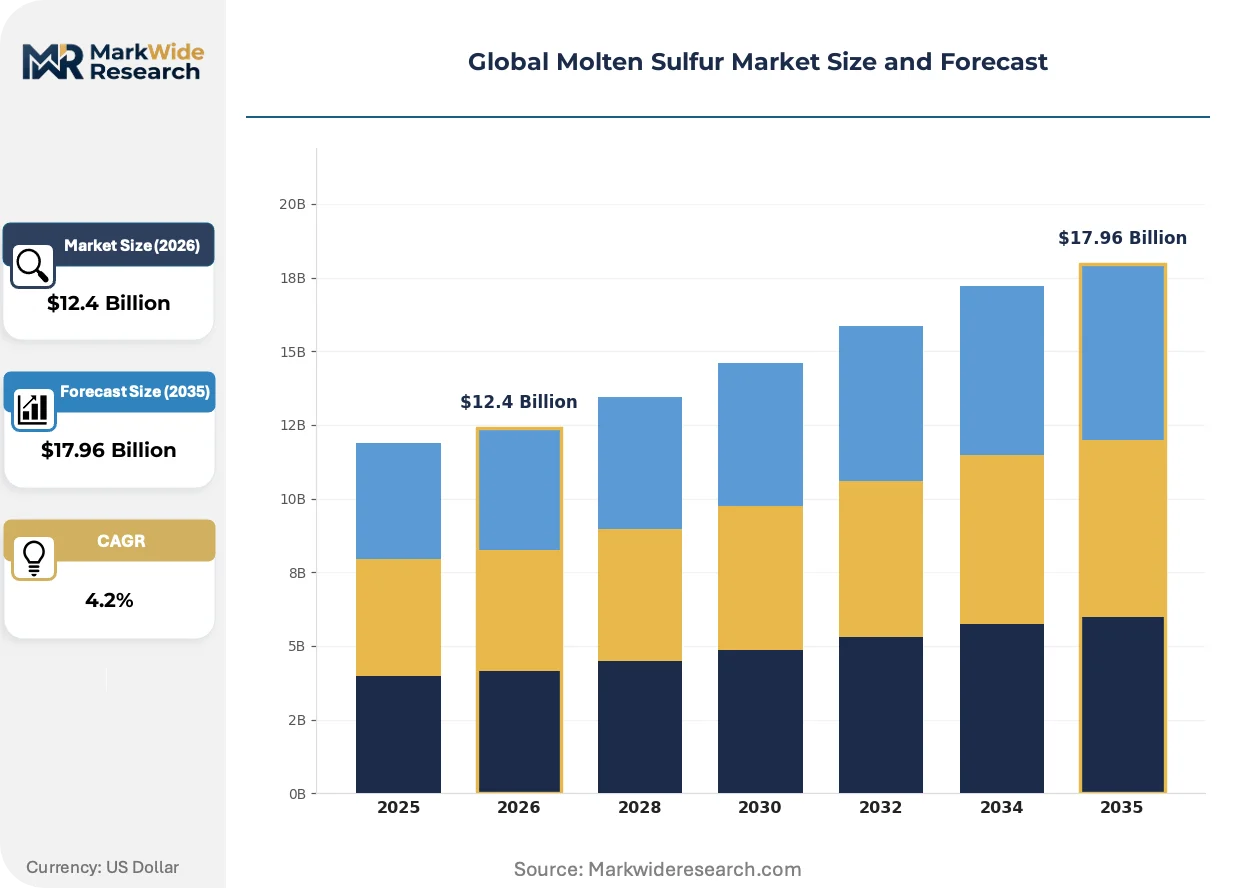
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.96 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Agricultural Grade, Pharmaceutical Grade, Electronic Grade Application: Fertilizers, Chemical Manufacturing, Petroleum Refining, Pesticides End User Industry: Chemical Plants, Mining Operations, Energy Production, Specialty Manufacturing Packaging Type: Bulk Tankers, Drums, Containers, Road Tankers, ISO Tanks |
| Companies Covered | Suncor Energy Inc., Kuwait National Petroleum Co., Chemtrade Logistics Income Fund, Montana Sulphur and Chemical Co, Marathon Petroleum Corp., Akzo Nobel NV, Sasol Ltd., H.J. Baker and Bro. LLC, Chevron Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molten Sulfur Market Shifts & Advancements
Thermal management and emissions compliance are converging to reshape how sulfur moves from refinery fence lines to acid plant intake points, with digital tracking and modular processing gaining operational footholds.
Membrane-based sulfur recovery systems are replacing conventional Claus catalytic stages in select natural gas processing trains. Operators at Wyoming and Alberta sour gas facilities are piloting these units for 15-20% energy reduction. The technology is rendering obsolete multi-reactor thermal oxidation configurations that dominated sulfur recovery architecture for four decades.
REACH registration requirements under ECHA oversight now mandate updated safety data sheets and exposure scenario documentation for bulk sulfur shipments into Rotterdam and Antwerp terminals. Chemical manufacturers must demonstrate downstream use compliance across fertilizer, rubber, and chemical synthesis applications. European sulfuric acid producers are consolidating supplier lists to reduce documentation burden, favoring integrated refinery suppliers with established registration portfolios.
Fertilizer cooperatives in Brazil's Center-West region are contracting directly with Gulf Coast refineries, bypassing traditional trading house intermediaries. These offtake agreements specify sulfuric acid plant commissioning milestones with volume flex provisions tied to phosphate rock processing schedules. The pattern is most pronounced in Mato Grosso and Goias states, where new mine developments require acid plant construction synchronization.
Global Molten Sulfur Market Segmentation
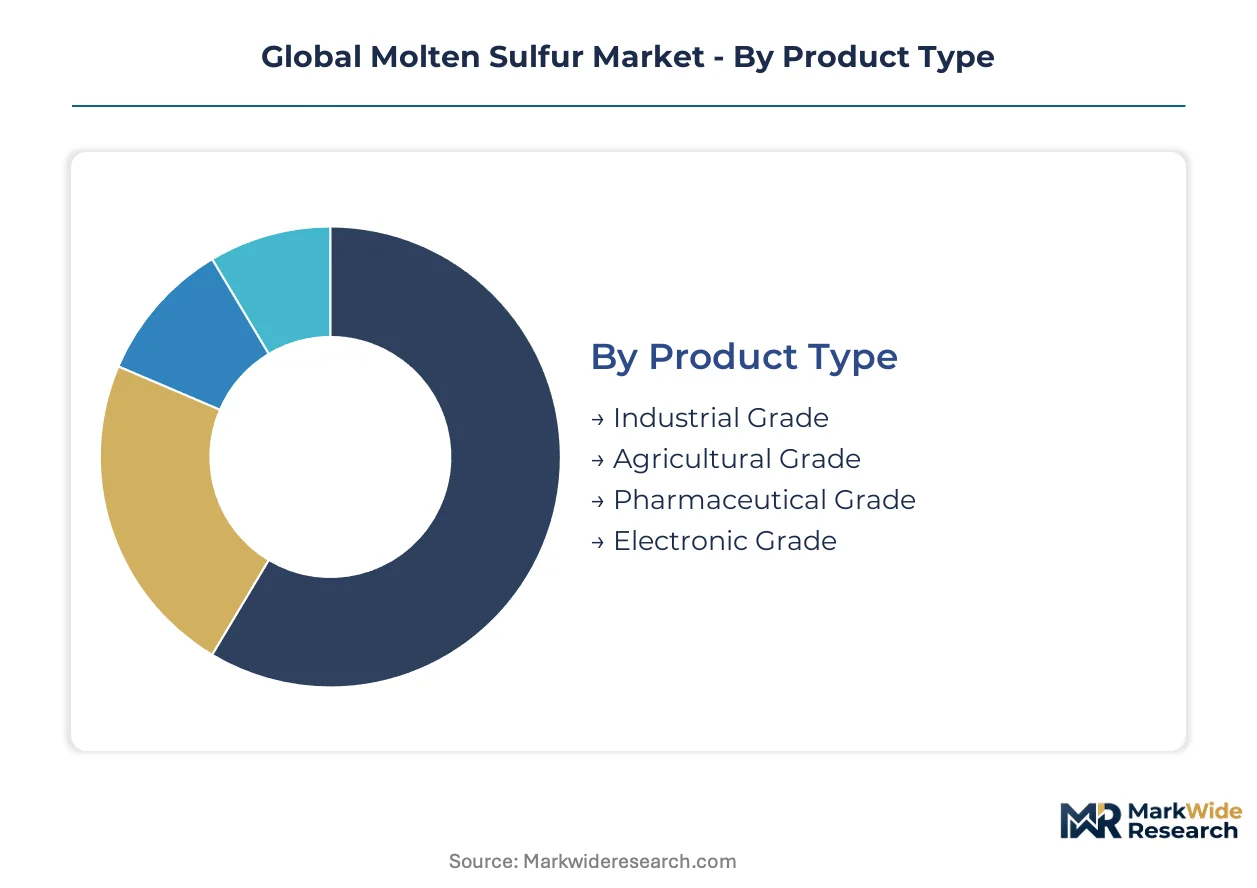
Molten sulfur segmentation reveals how purity specifications and thermal handling requirements fragment supply chains across industrial corridors. Distinct grade tiers command separate logistics infrastructure and pricing benchmarks.
Product Type:
Cycle times vary dramatically across purity grades, with industrial grade turning over weekly at Gulf Coast terminals while electronic grade moves through semiconductor chemical channels on quarterly schedules.
- Industrial Grade:Maintains 99.5% minimum purity with controlled moisture content below 0.5% for sulfuric acid feedstock. Demand concentrates in US Gulf Coast petrochemical complexes where Marathon Petroleum and Chevron supply integrated acid plants. China's GB standards tightening is filtering substandard product from export channels.
- Agricultural Grade:Carries tighter arsenic and heavy metal specifications for direct soil amendment compatibility. Brazilian fertilizer cooperatives in Mato Grosso and Goias states are contracting directly with Gulf Coast refineries, bypassing traditional trading intermediaries. Prilled sulfur substitution is eroding liquid market share in this segment.
- Pharmaceutical Grade:Meets USP monograph requirements for excipient and API manufacturing with comprehensive heavy metal testing protocols.
- Electronic Grade:Requires ultra-low arsenic and selenium content below 1 ppm for semiconductor chemical synthesis, commanding substantial premiums over industrial specifications.
Industrial grade dominates installed base. Electronic grade is where expansion concentrates.
Application:
Cost tier differentiation separates commodity acid manufacturing from specialized chemical synthesis, with fertilizer applications absorbing volume at thin margins while electronics chemicals sustain pricing power.
- Fertilizers:Phosphate fertilizer producers in Brazil and Southeast Asia commission sulfuric acid plants to process domestic phosphate rock reserves. Indian nutrient-based subsidy restructuring favors domestic acid production, opening import demand via Hazira and Paradip terminals.
- Chemical Manufacturing:Electronics-grade sulfur requirements sustain premium positioning through ultra-purification capabilities. Semiconductor chemical manufacturers in Taiwan and South Korea specify sub-ppm impurity thresholds.
- Petroleum Refining:Captive sulfur recovery from Claus process units feeds integrated downstream processing with minimal merchant market exposure.
- Pesticides:Intermediate synthesis for organophosphate and sulfonylurea herbicide manufacturing requires consistent feedstock quality.
Fertilizer applications anchor volume throughput. Chemical Manufacturing is climbing the fastest.
End User Industry:
Customer type fragmentation separates integrated refinery operators from merchant market buyers, with captive supply relationships dominating North American Gulf Coast corridors.
- Chemical Plants:Sulfuric acid manufacturers in the US Gulf Coast corridor source directly from adjacent refinery sulfur recovery units, minimizing transport costs through pipeline connections.
- Mining Operations:Copper and nickel heap leaching operations in Chile and Australia consume sulfuric acid at mine-site generation facilities, pulling molten sulfur into remote logistics networks.
- Energy Production:Power sector flue gas desulfurization and battery manufacturing create emerging demand channels outside traditional fertilizer chemistry.
- Specialty Manufacturing:Carbon disulfide and rubber chemical synthesis requires consistent sulfur quality for process stability.
Chemical Plants dominate installed base. Mining Operations is where expansion concentrates.
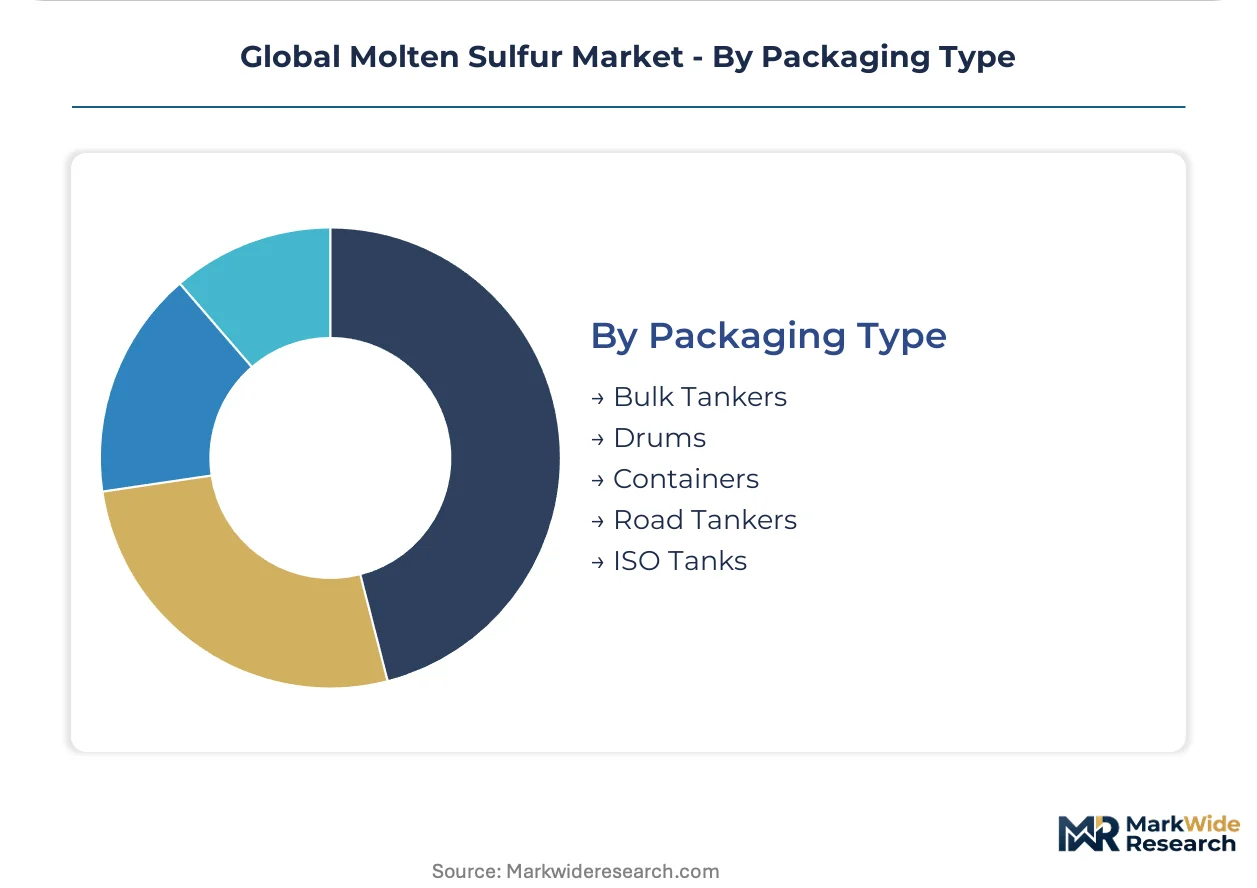
Packaging Type:
Supply concentration in insulated stainless steel infrastructure creates equipment scarcity premiums, with specialized heating systems commanding day rates substantially above standard chemical tankers.
- Bulk Tankers:Insulated vessels with steam heating coils maintain 115-155°C fluidity for transoceanic shipments from Gulf Coast to Asian fertilizer corridors.
- Drums:Solidified sulfur in steel drums serves small-batch chemical synthesis and laboratory applications with minimal thermal management requirements.
- Containers:Flexitank and ISO tank configurations enable multimodal transfer between rail, truck, and short-sea shipping networks.
- Road Tankers:Dedicated fleets serve regional acid plant supply with rapid turnaround at refinery loading facilities.
- ISO Tanks:Standardized intermodal equipment reduces handling costs for international chemical trade lanes.
Bulk Tankers dominate installed base. ISO Tanks is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA sulfur recovery standards under the Clean Air Act mandate maximum achievable control technology at US refineries, directly shaping molten sulfur output volumes across the dominant geography. Regional supply-demand imbalances hinge on refinery run rates and sulfuric acid plant commissioning schedules in fertilizer corridors.
United States
Marathon Petroleum Corp. leverages its integrated refinery network to control captive sulfur volumes across Texas and Louisiana processing sites. EPA regulations mandate maximum achievable control technology at sulfur recovery units, tightening quality benchmarks for merchant market supply. The US Gulf Coast petrochemical corridor concentrates over 60% of domestic merchant sulfur output, with pipeline connections minimizing transport costs to adjacent acid plants.
China
GB standards for industrial sulfur purity are tightening product specifications across export supply chains, filtering substandard product from international channels. MEE oversight enforces dual carbon goals that expand sulfur recovery unit installation mandates at domestic refineries. Yangtze River Delta chemical complexes source certified product from consolidated Gulf Coast and Middle Eastern suppliers meeting revised impurity thresholds.
Brazil
Fertilizer producers in the Center-West region commission new sulfuric acid plants to process domestic phosphate rock reserves, pulling molten sulfur volumes into Atlantic shipping lanes. ANVISA and environmental regulators oversee chemical handling protocols at port terminals receiving bulk shipments. Mato Grosso and Goias states host direct refinery offtake agreements that bypass traditional trading house intermediaries.
India
Nutrient-based subsidy restructuring favors domestic sulfuric acid production, opening import demand for Middle Eastern molten sulfur via Hazira and Paradip port terminals. BIS standards govern industrial chemical purity specifications for fertilizer manufacturing feedstock. Western and eastern coastal corridors concentrate acid plant construction synchronized with phosphate fertilizer capacity expansion.
Kuwait
Kuwait National Petroleum Co. competes on long-haul bulk shipments into Asian fertilizer corridors, leveraging integrated refinery-sulfur recovery infrastructure. National petroleum regulations align sulfur output quality with international fertilizer industry specifications. Port terminal infrastructure at Mina Al-Ahmadi supports heated tanker loading for transoceanic supply to Indian and Southeast Asian markets.
Global Molten Sulfur Market Competitive Landscape
Integrated refinery operators and merchant sulfur specialists split the market along captive supply versus third-party distribution lines. Concentration is pronounced in the US Gulf Coast corridor, where refinery fence-line proximity to acid plants minimizes logistics costs and locks in supply relationships. Three archetypes dominate: vertically integrated petroleum majors with dedicated sulfur recovery units, independent trading houses managing spot and contract volumes, and regional distributors serving fragmented agricultural demand. Competitive moves center on pipeline infrastructure control and long-term offtake contracting with fertilizer producers.
Within the integrated petroleum tier, Marathon Petroleum Corp. and Chevron Corp. occupy positions anchored by refinery network scale, while Kuwait National Petroleum Co. represents Middle Eastern supply origination for long-haul Asian corridors. These entities exemplify archetypes rather than discrete strategic postures, with geographic placement and infrastructure ownership determining competitive positioning more than product differentiation.
| Leading Market Players |
|---|
| Suncor Energy Inc. |
| Kuwait National Petroleum Co. |
| Chemtrade Logistics Income Fund |
| Montana Sulphur and Chemical Co |
| Marathon Petroleum Corp. |
| Akzo Nobel NV |
| Sasol Ltd. |
| H.J. Baker and Bro. LLC |
| Chevron Corp. |
| Others |
Supply & Pricing Matrix
Refinery sulfur recovery unit undercapacity across the US Gulf Coast during peak turnaround seasons drives spot price volatility and forces buyers into longer contract tenors. This utilization squeeze concentrates pricing power with integrated operators while compressing margins for merchant market participants dependent on spot cargoes.
Pricing Analysis
Atlantic-Pacific freight differentials between Gulf Coast load ports and Asian fertilizer terminals sustain persistent price spreads. Contract-based long-term offtake dominates, with electronic grade commanding substantial premiums over industrial specifications due to ultra-low arsenic requirements. Pricing pressure stems from sour crude input cost swings compressing refinery sulfur recovery economics. Fertilizer cooperatives exhibit highest price sensitivity, while semiconductor chemical manufacturers absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Hurricane exposure across Texas and Louisiana refining clusters dominates supply chain risk assessment for Atlantic basin buyers. Merchant sulfur originates primarily from the United States, Kuwait, and Canada, with Claus process hydrogen sulfide feedstock drawing from sour crude processing and natural gas sweetening operations. Single-point vulnerability concentrates in Gulf Coast pipeline corridors connecting refinery fence lines to marine terminals. Distribution runs through heated bulk tanker fleets with specialized stainless steel construction and steam coil infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molten sulfur market rewards operators commanding scarce logistics assets—insulated tanker capacity and heated terminal infrastructure—while penalizing pure traders without physical supply chain control. Electronics-grade purification capabilities represent the critical capability gap separating commodity players from premium capture.
For Market Incumbents: Pre-empt solid sulfur substitution in agricultural applications by securing direct offtake agreements with Brazilian fertilizer cooperatives in Mato Grosso and Goias states. Backward integration into sulfuric acid plant construction or pipeline infrastructure locks in volume commitment. Counter prilled sulfur erosion through long-term contracting with phosphate rock miners synchronizing acid plant commissioning schedules. For New Entrants and Emerging Players: Build out electronics-grade purification capabilities targeting semiconductor chemical manufacturers in Taiwan and South Korea demanding sub-ppm arsenic specifications. India's Hazira and Paradip port terminals offer penetrable entry points under nutrient-based subsidy restructuring favoring domestic acid production. Lead with ISO tank multimodal logistics to bypass scarce bulk tanker fleet constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic grade purification infrastructure due to ultra-low contamination requirements and extended qualification timelines. Long-term viability favors integrated refinery operators with captive hydrogen sulfide feedstock over pure merchant traders exposed to sour crude volatility. Target acquisition archetypes combine Gulf Coast terminal assets with established REACH registration portfolios. The signal to watch is semiconductor capital expenditure announcements indicating electronics-grade sulfur demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Brazilian fertilizer cooperatives bypass trading intermediaries through direct refinery contracting with volume flex provisions. |
| Capacity Expansion | Gulf Coast sulfur recovery unit additions at natural gas processing facilities expand merchant sulfur availability without crude throughput growth. |
| Backward Integration | Refinery operators acquiring sulfuric acid plant equity lock in downstream offtake and capture margin stack compression. |
| Green Manufacturing Transition | Membrane-based sulfur recovery systems at Wyoming sour gas facilities reduce energy intensity versus conventional Claus configurations. |
| Joint Venture | Middle Eastern suppliers partnering with Indian port terminal operators secure Hazira and Paradip access under subsidy restructuring. |
Research Methodology
Operator-level perspectives from refinery sulfur recovery unit managers, sulfuric acid plant procurement leads, heated tanker fleet operators, and fertilizer cooperative supply chain directors anchored the qualitative base. Secondary validation drew from EPA Clean Air Act enforcement records, ECHA REACH registration databases, China MEE dual carbon policy filings, and customs trade flow data. Bottom-up volume estimates triangulated against top-down refinery run rate and sulfuric acid capacity expansion projections.
Scenario-bracketing framed demand trajectories across phosphate fertilizer corridor expansion, electronics-grade purity requirement tightening, and solid sulfur substitution penetration. Segmentation modeling spanned grade tier, end-use application, packaging format, and regional production hub concentration. CAGRs derived from operating rate assumptions, acid plant commissioning schedules, and purity standard evolution across the projection horizon. Claus process optimization rates and membrane technology adoption curves informed supply-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Middle Eastern national oil companies or rapid membrane technology deployment would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Global Acrylate Monomers Market