
 US Dental Clearing Houses Market | 2026-2036
US Dental Clearing Houses Market Size, Share, and Industry Trends Forecast 2026-2036
US Dental Clearing Houses Market Insights
Multi-source vendor strategies is shifting how dental service organizations procure clearing house capabilities. Vyne Dental leverages cloud-native architecture to sustain competitive positioning among distributed practice networks. Change Healthcare anchors enterprise-scale eligibility verification through its payer connectivity density. DentalXChange specializes in real-time claim status tracking that differentiates its offering for mid-market dental groups.
Dental clearing houses function as electronic intermediaries that translate, validate, and route dental claims between providers and payers using ANSI X12 837D transaction standards, with core platforms processing eligibility inquiries, claim submissions, remittance advice, and electronic funds transfer. Cloud-based deployment leads service delivery, though hybrid solutions capture margin pools from security-conscious regional health networks. Claims management remains the largest service category by transaction volume, while payment processing represents the fastest-expanding segment as real-time adjudication gains traction among dental practices seeking reduced accounts-receivable cycles.
FDA oversight of software-as-medical-device classifications, HIPAA Security Rule requirements enforced by the Office for Civil Rights, and CMS electronic data interchange mandates collectively elevate compliance costs for market entrants. State dental boards in California, New York, and Texas impose supplementary credentialing verification protocols that fragment operational standardization. Stakeholders must monitor evolving state-level surprise billing regulations and CMS interoperability rulemaking to anticipate platform investment requirements.
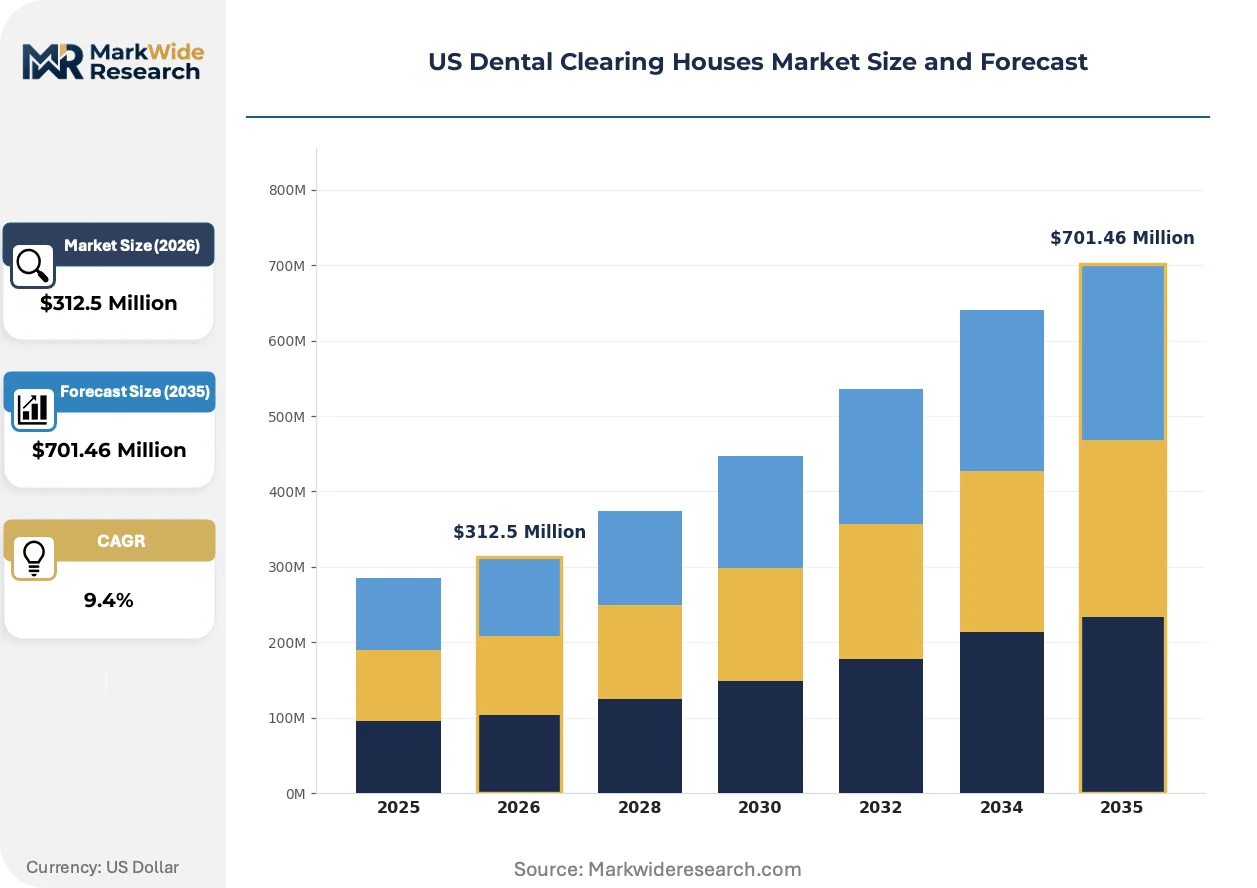
Market Dynamics
Dental service organizations across Texas, Florida, and Ohio are consolidating clearing house procurement under single-vendor contracts to streamline HIPAA compliance audits and reduce administrative overhead across distributed practice networks.
Growth Catalysts
- No Surprises Act:Federal surprise billing regulations mandate enhanced price transparency and patient notification protocols, compelling dental practices to upgrade clearing house capabilities for automated eligibility verification and cost estimation workflows.
- Cloud-native architecture:Multi-location dental groups are migrating from on-premise claim management systems to API-first platforms that enable real-time claim tracking and centralized revenue cycle management across state boundaries.
- Midwest and Southeast concentration:Regional dental practice consolidation in Ohio, Georgia, and North Carolina is creating demand for clearing houses with localized payer connectivity and state-specific Medicaid integration expertise.
Market Restraints
- HIPAA Security Rule enforcement:Office for Civil Rights audit protocols impose substantial compliance infrastructure costs on clearing house operators, elevating barriers for new entrants and compressing margins for mid-tier vendors.
- Payer connectivity concentration:Dominant national payers control EDI gateway access terms, creating dependency risk for clearing houses lacking direct contractual relationships with Delta Dental, UnitedHealthcare, and Aetna dental divisions.
- ANSI X12 837D version fragmentation:Payer-specific implementation guides and version compatibility requirements force clearing houses to maintain multiple translation engines, increasing technical debt and operational complexity.
Strategic Opportunities
- Real-time adjudication expansion:Payment processing capabilities that enable instant claim settlement are capturing share from traditional batch-processing clearing houses as dental practices prioritize cash flow velocity.
- State dental board credentialing automation:California, New York, and Texas supplementary verification protocols create white space for platforms integrating automated provider credentialing with core claims management workflows.
- Hybrid deployment models:Security-conscious regional health networks in the Mountain West and Pacific Northwest are seeking on-premise data retention with cloud-based analytics, opening margin pools beyond pure SaaS offerings.
Industry Challenges
- Interoperability rulemaking uncertainty:CMS electronic data interchange mandate evolution creates platform investment risk as clearing houses must anticipate forthcoming API standards and patient access requirements without definitive timelines.
- Legacy practice management system integration:Dental practices running outdated Dentrix, Eaglesoft, or Open Dental deployments require costly custom middleware development, extending implementation cycles and eroding project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dental Clearing Houses Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Management, Patient Billing, Eligibility Verification, Payment Processing Technology: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Platforms End User: Dental Practices, Insurance Companies, Third-Party Administrators, Healthcare Networks Integration Level: Full Integration, Partial Integration, Standalone Systems, Custom Solutions |
| Companies Covered | Vyne Dental, Office Ally, DentalXChange, Dental Cashflow Solutions, Smart Data Solutions, Dentrix, Electronic Dental Services, Napa EA MEDX LLC, Change Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dental Clearing Houses Market Trends and Innovations
Electronic claims processing infrastructure is undergoing architectural transformation as real-time data exchange replaces batch-oriented workflows, with vendor differentiation increasingly tied to analytics depth and payer network density rather than transaction volume alone.
Application programming interfaces for eligibility verification and claim status inquiry are modularizing clearing house service delivery, enabling dental groups to embed revenue cycle functions directly into practice management dashboards. Mid-market dental organizations in Florida and Texas are adopting these modular components fastest, compressing the traditional clearing house value chain by disintermediating standalone portal access.
CMS interoperability rulemaking and HIPAA information blocking provisions are mandating standardized patient data exchange formats, forcing clearing houses to reengineer proprietary data architectures toward FHIR-compliant interfaces. Dental service organizations with multi-state footprints face the steepest adaptation burden as state-level Medicaid programs implement staggered compliance timelines, with Ohio and California programs advancing fastest toward mandatory API adoption.
Subscription-based pricing for clearing house services is displacing per-transaction models as buyer preference shifts toward predictable cost structures aligned with practice revenue cycle staffing. Dental groups with ten-plus locations are negotiating enterprise licenses that bundle eligibility, claim submission, and payment processing, with this procurement pattern most visible among Texas-based dental service organizations seeking to consolidate vendor relationships under single-contract governance.
US Dental Clearing Houses Market Segmentation
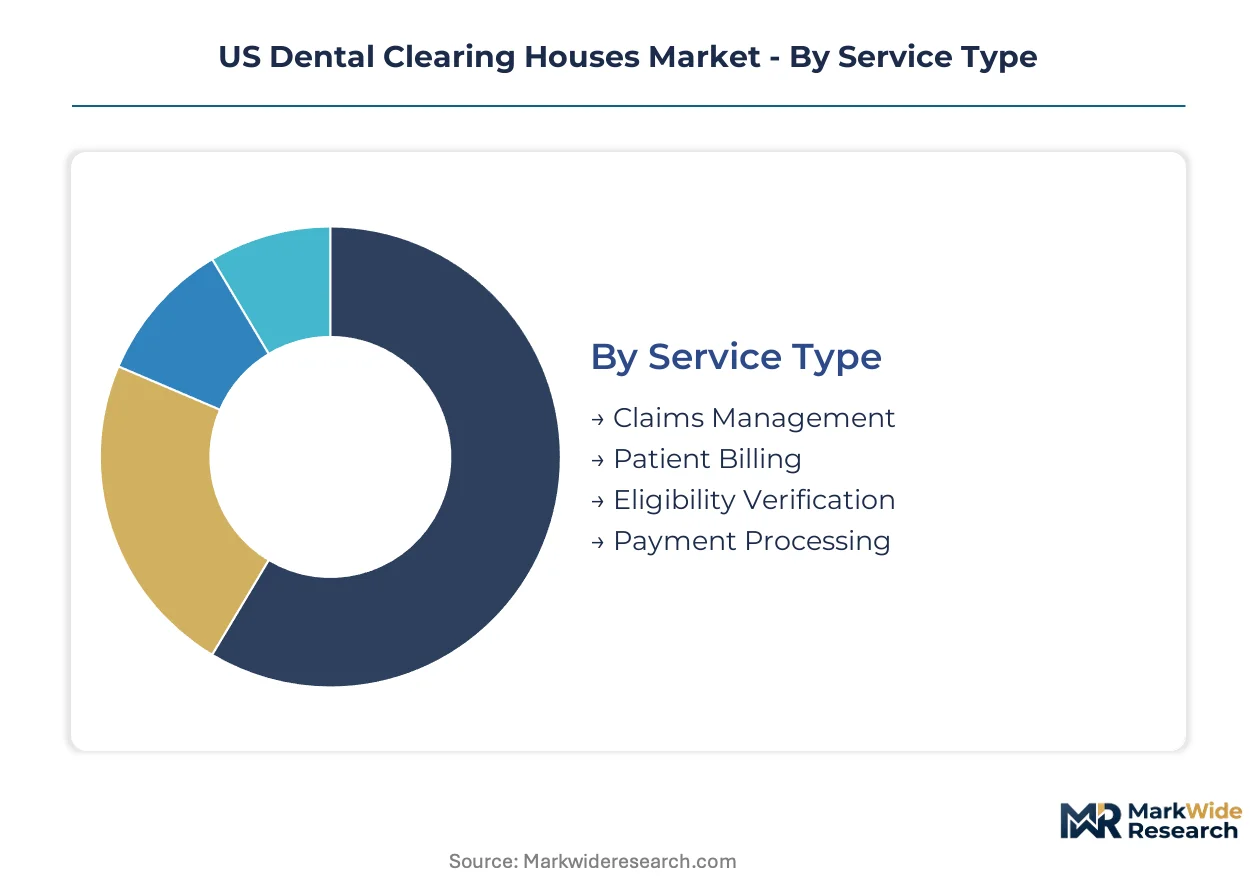
Dental clearing houses segment across service delivery models, technology architectures, and customer integration requirements. Each dimension carries distinct margin profiles and compliance obligations that reshape vendor competitive positioning.
Service Type:
Standardized transaction processing competes with configurable workflow automation across the service spectrum.
- Claims Management:Core platform function encompassing claim scrubbing, ANSI X12 837D translation, and payer routing. Multi-location dental groups in Texas and Florida consolidate procurement here to streamline HIPAA audit trails across distributed networks.
- Payment Processing:Electronic funds transfer and remittance advice management with accelerating real-time adjudication capabilities. Dental service organizations prioritize this segment to compress accounts-receivable cycles and improve cash flow velocity.
- Eligibility Verification:Automated payer connectivity for real-time benefit inquiry and patient cost estimation.
- Patient Billing:Statement generation, payment plan administration, and collections workflow support.
Leading the category by volume: Claims Management. Growing fastest: Payment Processing.
Technology:
Deployment architecture determines security posture, scalability limits, and total cost of ownership for dental practice networks.
- Cloud-Based:API-first platforms enabling centralized revenue cycle management across state boundaries. Vyne Dental leverages this architecture to serve distributed practice networks with real-time claim tracking and minimal on-site infrastructure.
- Hybrid Solutions:On-premise data retention paired with cloud analytics for security-conscious regional health networks. Mountain West and Pacific Northwest providers favor this model for HIPAA Security Rule compliance with localized control.
- On-Premise:Legacy server-based installations requiring dedicated IT maintenance and upgrade cycles.
- Mobile Platforms:Smartphone-accessible claim status inquiry and eligibility verification for field-based dental practitioners.
Cloud-Based deployments dominate new procurement. Hybrid Solutions capture the steepest expansion trajectory among security-sensitive buyers.
End User:
Customer type dictates platform complexity requirements and contractual negotiation patterns.
- Dental Practices:Solo practitioners through multi-location dental service organizations requiring scalable claim volume processing. Ohio, Georgia, and North Carolina consolidation drives demand for platforms with localized payer connectivity and state Medicaid integration.
- Healthcare Networks:Regional health systems with dental divisions seeking unified revenue cycle management across medical and dental service lines. These buyers command enterprise pricing leverage and custom integration requirements.
- Insurance Companies:Payer-side EDI gateway management and provider network administration tools.
- Third-Party Administrators:Benefits management intermediaries requiring multi-payer claim consolidation capabilities.
Dental Practices generate the highest transaction volume. Healthcare Networks are expanding most quickly as vertical integration accelerates.
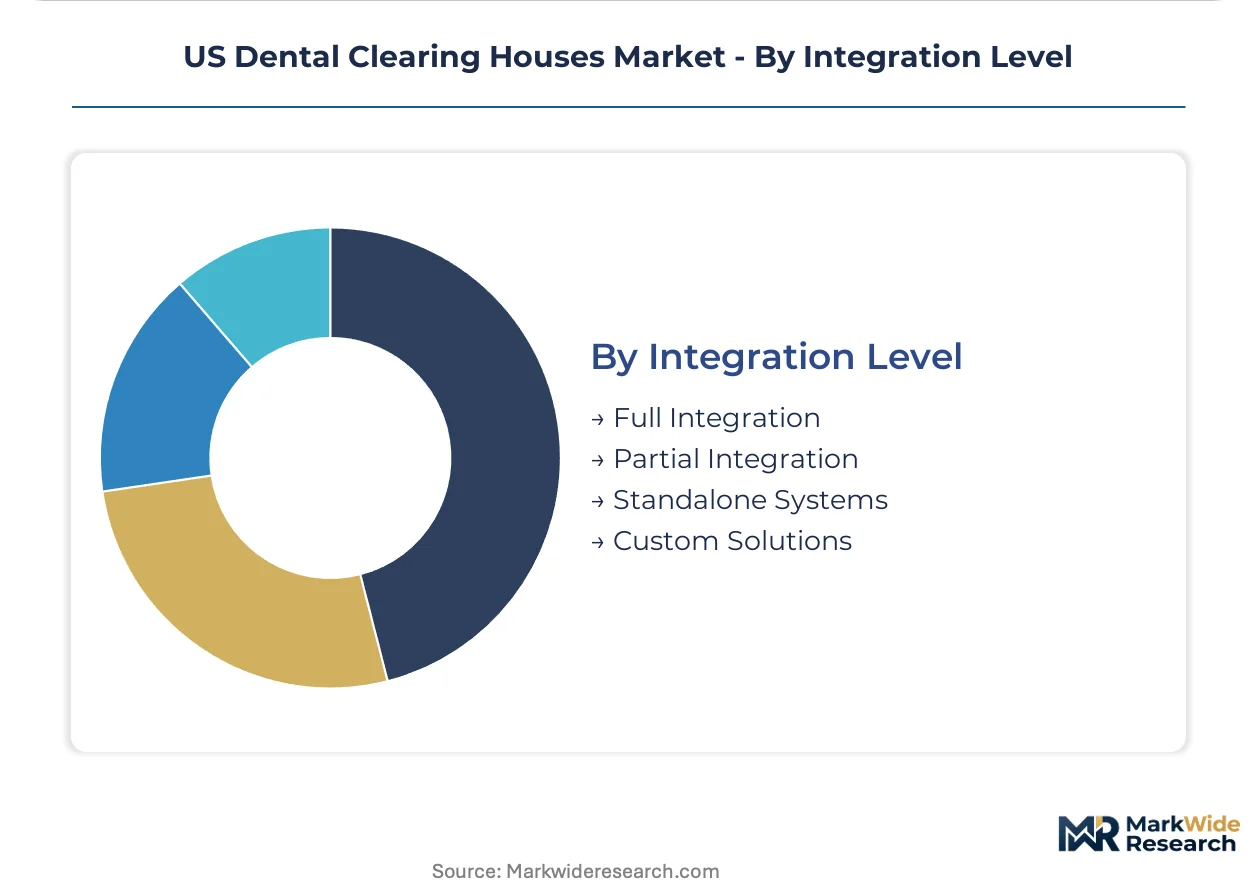
Integration Level:
Technical embedding depth determines implementation complexity and long-term vendor switching costs.
- Full Integration:Native connectivity with Dentrix, Eaglesoft, Open Dental, and other practice management systems enabling seamless workflow embedding. Custom middleware development for legacy deployments extends implementation cycles and elevates project economics.
- Custom Solutions:Bespoke API development and workflow configuration for dental service organizations with multi-state footprints. California, New York, and Texas dental boards impose supplementary credentialing protocols that fragment standardization and elevate customization demand.
- Partial Integration:Selective data exchange with core practice management functions remaining siloed.
- Standalone Systems:Portal-based access requiring manual data entry and duplicate workflow steps.
Full Integration commands the largest existing installed base. Custom Solutions are gaining share fastest as multi-state compliance complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-location dental service organizations concentrate procurement activity across Texas, Florida, and Ohio, with state-level Medicaid integration requirements and HIPAA enforcement intensity shaping vendor selection patterns.
Texas
Enterprise license consolidation dominates procurement among Dallas-Fort Worth and Houston dental service organizations seeking single-contract governance across ten-plus locations. HIPAA Security Rule enforcement by the Office for Civil Rights elevates compliance infrastructure as a selection criterion. Austin and San Antonio practice networks drive demand for real-time adjudication capabilities that compress accounts-receivable cycles.
Florida
Mid-market dental groups in Miami-Dade and Broward counties adopt API-first eligibility verification modules fastest, embedding revenue cycle functions directly into practice management dashboards. State dental board credentialing protocols fragment standardization requirements. Tampa and Orlando consolidation activity creates demand for platforms with localized payer connectivity to Delta Dental of Florida and UnitedHealthcare networks.
Ohio
Regional practice consolidation in Cleveland-Akron and Columbus metro areas accelerates outsourced claims management adoption. State Medicaid program API adoption timelines advance faster than national averages, forcing clearing house reengineering toward FHIR-compliant interfaces. Cincinnati dental service organizations prioritize hybrid deployment models that retain on-premise data control.
California
Supplementary credentialing verification protocols imposed by the state dental board elevate customization demand for multi-state dental service organizations with California footprints. Los Angeles and San Francisco Bay Area practices command enterprise pricing leverage through unified revenue cycle management across medical and dental service lines. Sacramento Medicaid integration complexity fragments platform standardization.
Georgia
Atlanta metropolitan dental group consolidation creates demand for clearing houses with Southeast regional payer connectivity expertise. State-level surprise billing regulation evolution mirrors federal No Surprises Act compliance timelines. Savannah and Augusta practice networks seek cloud-native architecture that enables centralized revenue cycle management across state boundaries.
US Dental Clearing Houses Market Competitive Landscape
Consolidation of procurement under single-vendor contracts dominates the current landscape, with dental service organizations streamlining HIPAA compliance audits and reducing administrative overhead across distributed networks. The vendor base organizes into three tiers: enterprise-scale platforms with dense payer connectivity, cloud-native specialists serving distributed practice networks, and regional operators with state-specific Medicaid integration expertise. Two strategic archetypes anchor competitive positioning: API-first platforms enabling modular service embedding, and hybrid-deployment providers capturing security-conscious regional health networks. M&A activity and strategic partnerships represent the dominant competitive moves as vendors seek geographic expansion and technology licensing opportunities.
Among cloud-native specialists, Vyne Dental and DentalXChange exemplify the API-first archetype serving distributed practice networks with real-time claim tracking capabilities. Change Healthcare anchors the enterprise-scale tier with payer connectivity density that supports consolidated procurement patterns among multi-location dental groups. These three companies occupy positions that reflect the market's bifurcation between modular, embedded service delivery and unified enterprise platform consolidation.
| Leading Market Players |
|---|
| Vyne Dental |
| Office Ally |
| DentalXChange |
| Dental Cashflow Solutions |
| Smart Data Solutions |
| Dentrix |
| Electronic Dental Services |
| Napa EA MEDX LLC |
| Change Healthcare |
| Others |
Pricing and Supply Chain Analysis
API-first platform migration simultaneously compresses implementation costs and concentrates procurement leverage among multi-location dental service organizations. Cloud-native architecture shifts vendor economics from per-transaction margins toward enterprise subscription retention, reshaping how clearing houses structure service bundling and compliance infrastructure investments.
Pricing Analysis
Service bundling separates compliance-heavy enterprise tiers from unbundled mid-market offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers incorporating automated credentialing verification and real-time adjudication. Price differentiation rests on HIPAA audit support depth and payer connectivity density. Pricing pressure stems from subscription model displacement of per-transaction revenue as dental groups consolidate vendor relationships. Solo practitioners exhibit highest price sensitivity; multi-state dental service organizations prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Regional data center distribution anchors clearing house service delivery, with hub-and-spoke patterns radiating from Dallas-Fort Worth, Phoenix, and Northern Virginia cloud infrastructure clusters. Software development concentrates in the United States, with specialized engineering talent pools in Austin, Seattle, and Boston. Raw material dependencies include cloud compute capacity from AWS, Azure, and Google Cloud; cybersecurity infrastructure from Palo Alto Networks and CrowdStrike; and EDI gateway licenses from dominant national payers. Supply chain risk centers on single-source payer connectivity agreements with Delta Dental, UnitedHealthcare, and Aetna dental divisions. Distribution runs through direct enterprise sales teams and dental practice management system integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as HIPAA Security Rule enforcement costs force marginal operators toward acquisition or exit. Dental service organization procurement centralization creates winner-take-most dynamics among clearing houses with dense payer connectivity and multi-state compliance automation.
For Market Incumbents: Anticipate margin compression from API modularization by deepening vertical integration into state Medicaid program direct connections. Acquire regional operators with California, New York, and Texas dental board credentialing expertise to defend against cloud-native entrants. Priority lever: hybrid deployment capability for security-conscious regional health networks in the Mountain West and Pacific Northwest. For New Entrants and Emerging Players: The mid-market price-point gap between Change Healthcare enterprise contracts and standalone portal offerings creates white-space opportunity. Target Ohio and Georgia dental groups undergoing consolidation with real-time claim status tracking as differentiated entry wedge. Go-to-market angle: API-first eligibility verification modules that embed directly into Open Dental and Dentrix dashboards without middleware development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by healthcare IT platforms seeking dental vertical penetration. Long-term viability favors clearing houses with direct payer gateway contracts rather than intermediary-dependent routing. Acquisition target archetype: cloud-native specialists with FHIR-compliant architecture and multi-state Medicaid integration. Signal to watch: CMS interoperability rulemaking finalization triggering platform reengineering investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Payer Gateway Direct Contracting | Eliminates intermediary routing fees and locks in revenue visibility through exclusive EDI access terms with Delta Dental networks. |
| FHIR-Compliant Architecture Migration | Positions platforms for CMS interoperability mandate compliance while opening patient data exchange revenue streams. |
| State Medicaid API Integration | Captures procurement preference among dental service organizations with Ohio and California footprints where program timelines advance fastest. |
| Hybrid Deployment Capability Buildout | Addresses security-conscious regional health networks in Pacific Northwest markets seeking localized data retention with cloud analytics. |
| Real-Time Adjudication Infrastructure | Enables instant claim settlement that compresses accounts-receivable cycles for dental practices prioritizing cash flow velocity. |
Research Methodology
Multi-period observation of clearing house transaction volumes, payer connectivity expansions, and dental service organization procurement patterns anchored the trend analysis, supplemented by interviews with revenue cycle management directors at multi-location dental groups, HIPAA compliance officers, dental practice management system integration specialists, and state Medicaid program EDI coordinators. Secondary validation drew from CMS Medicare data releases, Office for Civil Rights enforcement action records, state dental board regulatory filings, and dental industry trade association surveys. Bottom-up practice-level adoption modeling and top-down market sizing triangulation produced convergent estimates.
Segment-weighting across service type, technology deployment architecture, end-user category, and integration level informed the analytical framework. CAGRs were derived from slope analysis of historical transaction growth rates projected across the modeling period, adjusted for HIPAA interoperability mandate implementation timelines and No Surprises Act compliance phase-in effects. Industry-specific forecast inputs included payer EDI gateway capacity expansion announcements and dental practice consolidation velocity indices.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time adjudication adoption rates and proprietary payer contract terms introduce uncertainty bands around payment processing segment projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Healthcare IT Outsourcing Market