
 China Artificial Organs and Bionic Implants Market | 2026-2036
China Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
China Artificial Organs and Bionic Implants Market Outlook
The price-performance gap between premium imported implants and domestically manufactured alternatives is hardening across China's hospital procurement channels. Medtronic anchors its position through captive supply of high-margin cardiac rhythm devices to top-tier medical centers. Regenovo Biotechnology leverages bioprinting research partnerships to differentiate in tissue-engineered grafts. Zimmer Biomet sustains orthopedic market presence via manufacturing scale in joint reconstruction systems.
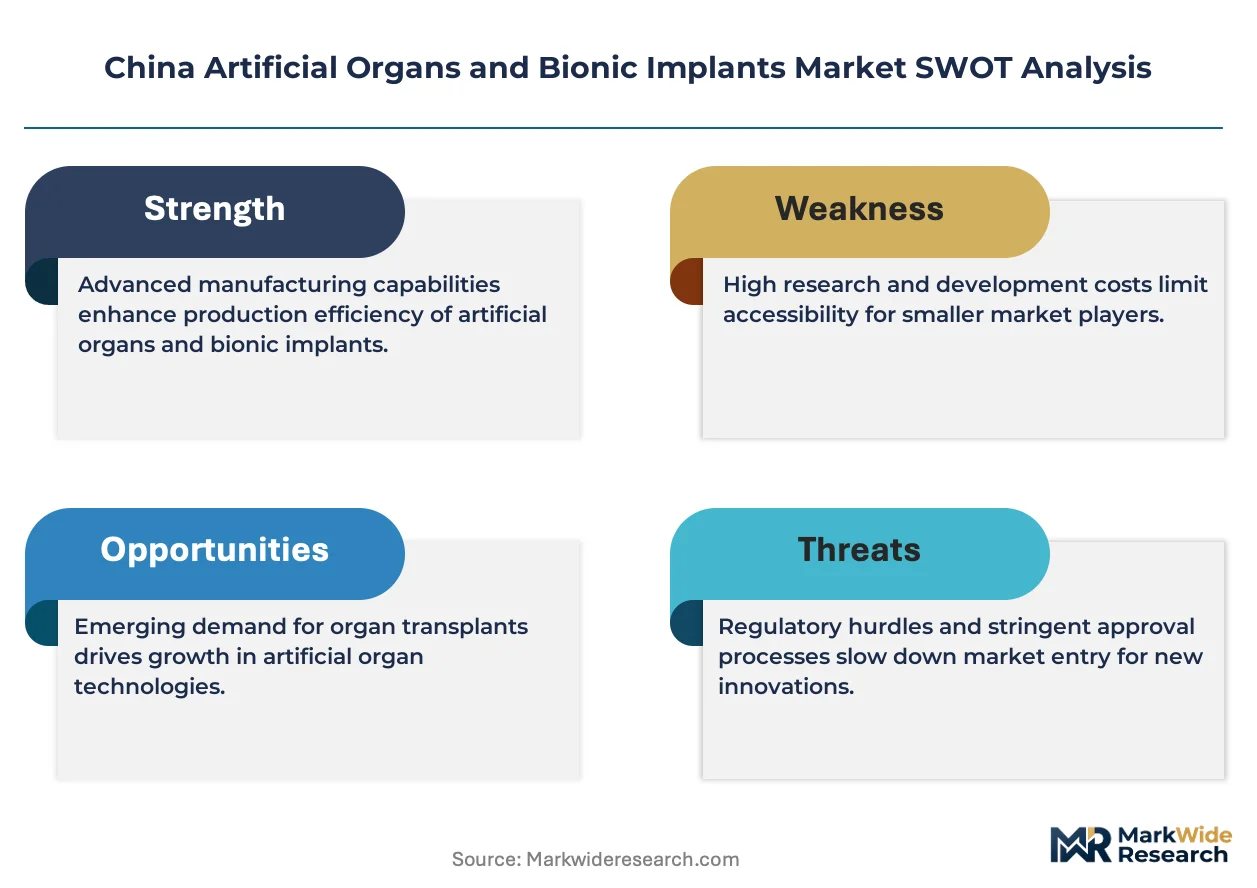
Artificial organs and bionic implants encompass electromechanical and biological substitutes engineered to replicate native physiological functions, typically incorporating titanium alloys, cobalt-chrome substrates, or biocompatible polymers with porosity specifications matched to bone ingrowth requirements. Their primary purpose spans restoration of motor, sensory, or organ function in patients with congenital defects, traumatic injury, or degenerative disease. Orthopedic implants occupy the largest revenue pool among product types due to aging demographics and trauma incidence, while 3D bioprinting represents the fastest-expanding technology segment as domestic equipment makers reduce per-unit fabrication costs. Cardiac implants command premium pricing tiers tied to NMPA Class III certification requirements and extended clinical trial obligations.
NMPA, GB standards, and the dual carbon goals framework collectively shape product registration timelines, materials sourcing compliance, and energy-intensive manufacturing constraints across the sector. GB standards mandate biocompatibility testing protocols that extend development cycles but elevate barrier-to-entry protection for certified domestic producers. Stakeholders must monitor evolving provincial centralized procurement rules that increasingly weight total cost-of-ownership metrics against upfront device pricing in hospital tender evaluations.
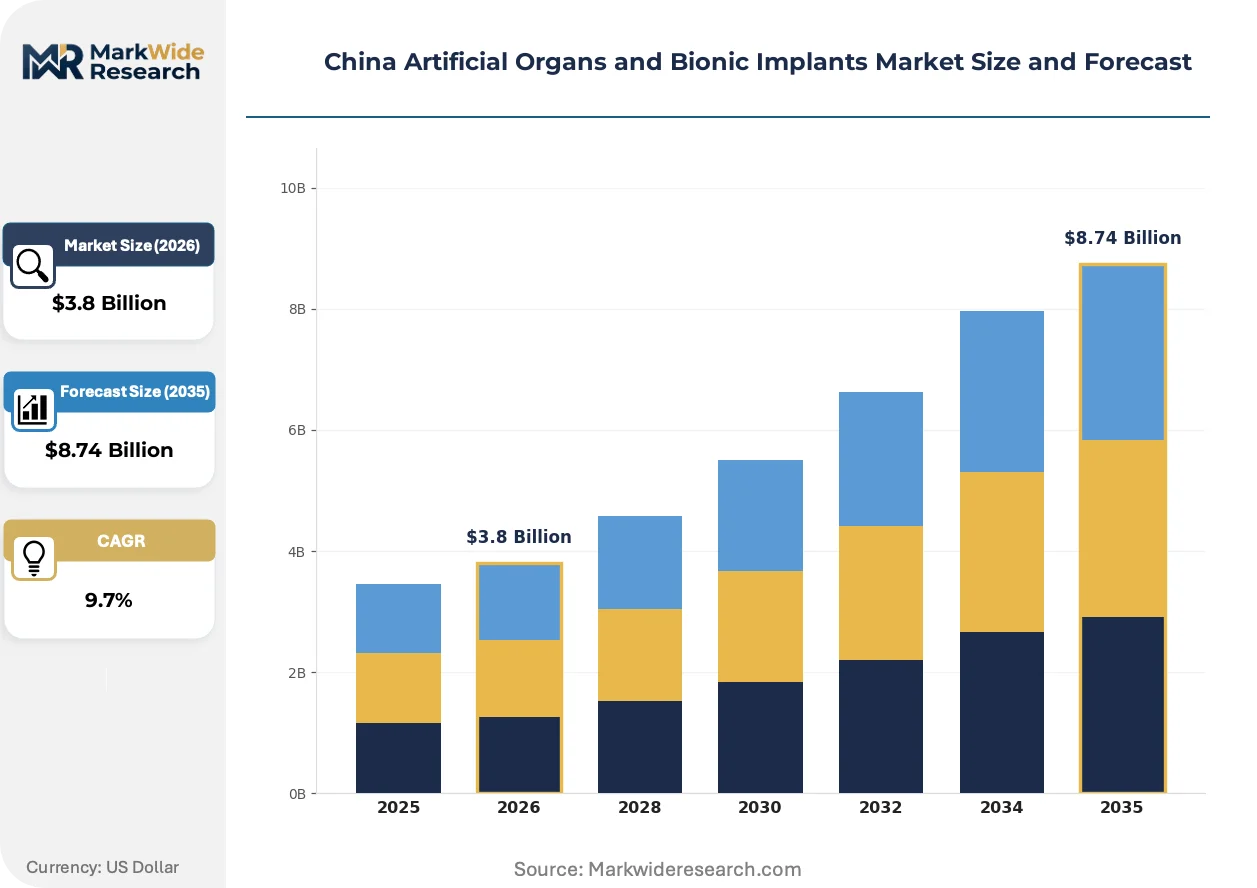
Market Dynamics
Centralized provincial procurement is compressing margins for artificial organ and bionic implant suppliers while simultaneously accelerating domestic substitution of imported cardiac and orthopedic devices in tier-one Chinese hospitals.
Growth Catalysts
- Dual carbon goals framework:Energy efficiency mandates are redirecting capital toward low-carbon bioprinting facilities, reducing per-unit fabrication costs for tissue-engineered grafts.
- Shanghai and Beijing hospital clusters:Concentrated surgical capability in these municipalities is generating procedure volume that amortizes high fixed costs of advanced implant systems.
- GB standards biocompatibility protocols:Harmonized testing requirements are streamlining cross-provincial product registration, accelerating time-to-market for certified domestic producers.
Market Restraints
- Titanium alloy import dependency:Aerospace-grade substrate supply concentrates in a limited supplier base, exposing fabricators to input cost volatility and geopolitical sourcing friction.
- NMPA Class III certification timelines:Extended clinical trial obligations for cardiac rhythm devices extend development cycles and elevate capital lockup periods.
- Biologic graft shelf-life limitations:Tissue-engineered products face degradation constraints that compress distribution radii and elevate cold-chain logistics costs.
Strategic Opportunities
- Central and western province hospital networks:Tier-two and tier-three facilities in Sichuan, Hubei, and Shaanxi remain underpenetrated for advanced orthopedic reconstruction systems.
- 3D bioprinting and AI-driven topology optimization convergence:Integrated design-to-fabrication workflows are enabling patient-specific implant geometries that command premium positioning.
- Provincial centralized procurement rule evolution:Emerging total cost-of-ownership weighting in tender evaluations favors suppliers with integrated after-sales service capabilities.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-functional expertise spanning materials science, regulatory affairs, and surgical workflow design remains concentrated in coastal metropolitan clusters.
- Cleanroom manufacturing capex intensity:ISO 14644-compliant production facilities for Class III devices require substantial upfront investment with extended depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Artificial Organs and Bionic Implants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Cochlear Implants, Orthopedic Implants, Artificial Organs Technology: Biocompatible Materials, 3D Bioprinting, AI-Assisted Devices, Neuroprosthetics End User: Healthcare Facilities, Research Institutions, Rehabilitation Centers, Patients Application: Restorative Surgery, Neurology, Trauma care, Cardiovascular treatments |
| Companies Covered | Medtronic, Abiomed, Ossur, Regenovo Biotechnology, Chengdu Baishixing Science & Technology Industry Co Ltd, Boston Scientific Corporation, Zimmer Biomet, Terumo Corporation, Otto Bock Holding GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Artificial Organs and Bionic Implants Market Strategic Shifts
Electromechanical neural interfaces and regenerative bioprinting platforms are converging to redefine functional restoration paradigms, while regulatory acceleration mechanisms and procurement rationalization are reshaping competitive access to Chinese hospital channels.
3D bioprinting is overtaking conventional subtractive manufacturing for patient-specific orthopedic implants. Shanghai-based surgical centers are adopting extrusion-based and laser-assisted fabrication systems for complex cranio-maxillofacial reconstructions. This shift is compressing lead times from weeks to days while enabling porosity gradients that match native bone ingrowth kinetics.
NMPA breakthrough device designation pathways are shortening review timelines for innovative cardiac and neurological implants. Domestic manufacturers leveraging these accelerated tracks are securing market access months ahead of conventional registration routes. Cardiac rhythm management devices and deep-brain stimulation systems are experiencing the most pronounced regulatory velocity gains.
Hospital procurement committees are consolidating vendor relationships around integrated service contracts that bundle device supply with surgical training and long-term maintenance. This bundling is displacing transactional spot purchasing in Beijing and Guangdong province health systems. Orthopedic implant suppliers with captive technical education infrastructure are capturing disproportionate share in these consolidated tenders.
China Artificial Organs and Bionic Implants Market Segmentation
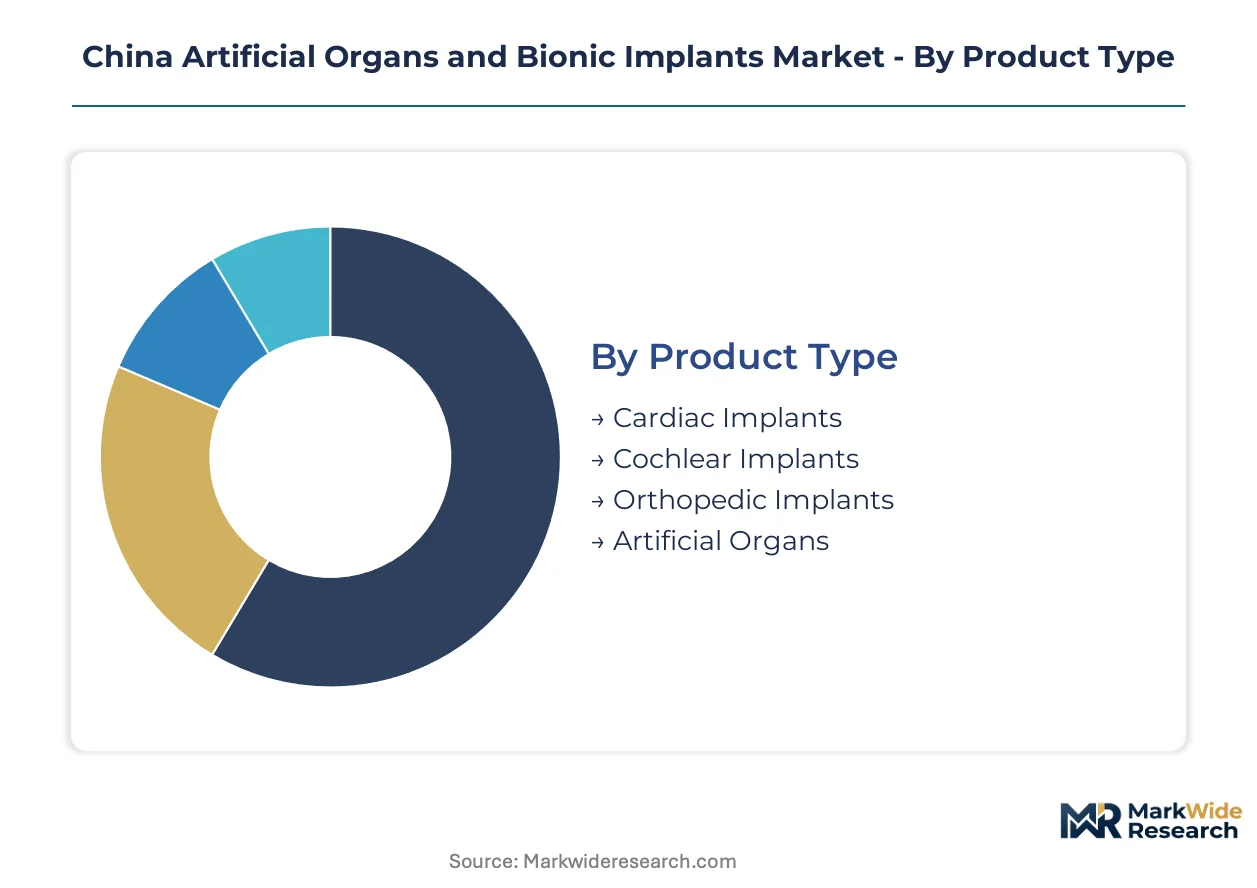
Segmentation in China's artificial organs and bionic implants market reveals divergent capital requirements, regulatory pathways, and procurement dynamics. Product type and technology categories demand the heaviest upfront investment, while end-user and application dimensions shape distribution economics and reimbursement structures.
Product Type:
Orthopedic and cardiac implant systems require the most substantial manufacturing infrastructure, with ISO 14644 cleanroom facilities and NMPA Class III certification timelines driving fixed cost structures.
- Cardiac Implants:Pacemakers, ICDs, and valve systems incorporate lithium-iodine batteries and titanium housings with hermetic sealing specifications. Shanghai and Beijing cardiac centers concentrate demand as NMPA breakthrough device pathways compress review timelines for domestic rhythm management manufacturers.
- Orthopedic Implants:Joint reconstruction systems utilize cobalt-chrome substrates and ultra-high molecular weight polyethylene bearing surfaces. Tier-one hospitals in Guangdong and Jiangsu provinces drive volume as centralized procurement rules increasingly weight total cost-of-ownership metrics.
- Cochlear Implants:Multi-channel electrode arrays and speech processor units.
- Artificial Organs:Ventricular assist devices and artificial kidneys with biocompatible membrane technologies.
Orthopedic implants absorb the bulk of installed capacity; 3D bioprinted patient-specific geometries are expanding most quickly in cranio-maxillofacial applications.
Technology:
3D bioprinting platforms and neuroprosthetic systems command premium R&D intensity, while biocompatible materials represent the most mature, margin-compressed layer of the technology stack.
- 3D Bioprinting:Extrusion-based and laser-assisted fabrication systems enable porosity gradients matched to native bone ingrowth kinetics. Shanghai surgical centers are compressing lead times from weeks to days for complex reconstructions as domestic equipment makers reduce per-unit fabrication costs.
- AI-Assisted Devices:Machine learning algorithms optimize implant sizing and surgical placement trajectories. Beijing hospital clusters are piloting topology optimization workflows that command premium positioning in bundled service contracts.
- Biocompatible Materials:Titanium alloys, cobalt-chrome substrates, and bioresorbable polymers with standardized porosity specifications.
- Neuroprosthetics:Deep-brain stimulation systems and electromechanical neural interfaces with NMPA accelerated review pathways.
Biocompatible materials anchor volume throughput; neuroprosthetics are climbing the fastest as regulatory velocity gains concentrate in neurological applications.
End User:
Procurement concentration varies sharply by facility tier, with tier-one hospitals capturing advanced cardiac and orthopedic systems while rehabilitation centers specialize in post-surgical device management.
- Healthcare Facilities:Tier-one hospitals in coastal provinces with advanced surgical capabilities and NMPA Class III device handling credentials. Centralized provincial procurement is consolidating vendor relationships around integrated service contracts in Beijing and Guangdong health systems.
- Research Institutions:Bioprinting research partnerships and preclinical testing infrastructure. Regenovo Biotechnology leverages academic collaborations to differentiate in tissue-engineered graft development.
- Rehabilitation Centers:Post-implant patient monitoring and device programming services.
- Patients:Direct-to-consumer channels for hearing aid and select orthopedic accessories.
Healthcare facilities absorb the bulk of high-value device shipments; research institutions are expanding most quickly as bioprinting partnerships proliferate.
Application:
Procedure reimbursement rates and clinical outcome data requirements create divergent market access conditions across surgical specialties.
- Restorative Surgery:Cranio-maxillofacial and dental reconstructions utilizing patient-specific 3D-printed implants. Shanghai surgical centers are adopting extrusion-based fabrication systems that enable porosity gradients matching native bone ingrowth kinetics.
- Cardiovascular Treatments:Rhythm management and structural heart interventions with extended NMPA clinical trial obligations. Medtronic anchors position through captive supply of high-margin devices to top-tier medical centers.
- Neurology:Deep-brain stimulation and neural interface applications.
- Trauma Care:Emergency orthopedic stabilization and fracture fixation systems.
Cardiovascular treatments absorb the bulk of premium pricing tiers; restorative surgery is gaining share fastest as 3D bioprinting compresses patient-specific fabrication economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's surgical corridor anchors China's artificial organs and bionic implants demand, with Ruijin Hospital and Zhongshan Hospital performing thousands of complex implant procedures annually. Beijing and Guangzhou follow as secondary concentration nodes.
Shanghai
Cardiac rhythm management and orthopedic reconstruction procedures concentrate in Shanghai's tier-one hospital cluster. NMPA breakthrough device pathways compress review timelines for domestic manufacturers headquartered in the municipality. Zhangjiang Hi-Tech Park houses bioprinting research facilities that partner with surgical centers on patient-specific cranio-maxillofacial implants.
Beijing
Structural heart interventions and neurological implant demand concentrates in Beijing's military and civilian hospital network. GB standards biocompatibility testing protocols streamline cross-provincial registration for certified producers operating in the capital. Zhongguancun Science Park anchors AI-assisted surgical planning development that integrates with implant placement workflows.
Guangdong
Pearl River Delta manufacturing clusters supply titanium alloy substrates and biocompatible polymers to domestic fabricators. Provincial centralized procurement rules in Guangdong weight total cost-of-ownership metrics against upfront device pricing in hospital tenders. Shenzhen's medical device industrial zone hosts contract manufacturers serving both domestic and export markets.
Sichuan
Tier-two hospital networks in Chengdu and surrounding municipalities remain underpenetrated for advanced orthopedic reconstruction systems. Western China development programs channel infrastructure investment toward surgical capability expansion in the province. Tianfu New Area is emerging as a distribution hub for cold-chain logistics serving biologic graft shipments.
Jiangsu
Joint reconstruction system demand concentrates in Nanjing and Suzhou hospital clusters serving aging coastal populations. Dual carbon goals framework mandates redirect capital toward energy-efficient bioprinting facilities in the province. Suzhou Industrial Park hosts foreign-invested manufacturing operations that supply orthopedic implants to East China markets.
China Artificial Organs and Bionic Implants Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and service integration dimensions. Market structure fragments across multinational device manufacturers, domestic bioprinting specialists, and state-affiliated procurement distributors. Three archetypes dominate: captive supply operators with hospital integration, research-partnership bioprinting ventures, and scale-driven orthopedic fabricators. Consolidation through strategic partnerships and backward integration into substrate sourcing represent the dominant competitive vectors.
Among multinational operators, Medtronic and Boston Scientific Corporation exemplify the premium-tier archetype through captive supply relationships with top-tier cardiac centers. Zimmer Biomet occupies a position within the scale-driven orthopedic segment, leveraging manufacturing infrastructure for joint reconstruction systems. Regenovo Biotechnology represents the research-partnership model, anchoring its market presence through academic collaborations in tissue-engineered graft development.
| Leading Market Players |
|---|
| Medtronic |
| Abiomed |
| Ossur |
| Regenovo Biotechnology |
| Chengdu Baishixing Science & Technology Industry Co Ltd |
| Boston Scientific Corporation |
| Zimmer Biomet |
| Terumo Corporation |
| Otto Bock Holding GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Titanium alloy substrate costs cascade through China's artificial organ and bionic implant tiers, with aerospace-grade material premiums concentrating pricing power among NMPA Class III certified fabricators serving Beijing and Shanghai cardiac centers while compressing margins for orthopedic producers exposed to provincial centralized procurement.
Pricing Analysis
Value-based pricing anchors on clinical outcome guarantees bundled with surgical training and long-term device maintenance. Three-tier pricing structure across premium, standard, and economy levels separates NMPA breakthrough-designated cardiac rhythm devices from conventional orthopedic implants and unbranded trauma fixation systems. Price differentiation hinges on certification tier and after-sales service integration. Cost compression in standard-tier joint reconstruction is intensifying because Guangdong and Jiangsu provincial procurement committees weight total cost-of-ownership metrics. Tier-two hospital networks in Sichuan and Shaanxi exhibit highest price sensitivity; tier-one cardiac centers in Shanghai demonstrate lowest sensitivity due to outcome-linked reimbursement protocols.
Supply Chain Analysis
Regional distribution centers in Shanghai Zhangjiang Hi-Tech Park and Suzhou Industrial Park anchor hub-and-spoke cold-chain logistics for biologic grafts and Class III device shipments. Upstream supply draws from Japan and Germany for precision extrusion equipment, while titanium alloy substrates concentrate in domestic smelters and Russian aerospace-grade suppliers. Raw material dependencies include cobalt-chrome bearing surfaces, lithium-iodine battery cells, and bioresorbable polymer feedstocks. Single-source vulnerability in aerospace-grade titanium exposes fabricators to geopolitical sourcing friction and input cost volatility. Distribution runs through state-affiliated procurement platforms and GPO contracts to tier-one hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over bioprinting research infrastructure and titanium alloy substrate sourcing determines margin sustainability across NMPA certification tiers.
For Market Incumbents: Acquire bioprinting research partnerships and academic tissue-engineering collaborations to defend against domestic substitution acceleration. Secure long-term offtake agreements with aerospace-grade titanium suppliers to mitigate input cost volatility. Build captive technical education infrastructure to capture consolidated tender awards as Beijing and Guangdong procurement shifts toward bundled service contracts. For New Entrants and Emerging Players: Begin with tier-two orthopedic reconstruction systems in Sichuan, Hubei, and Shaanxi hospital networks where advanced implant penetration remains limited. Target cranio-maxillofacial applications where 3D bioprinting lead times compress competitive differentiation. Establish go-to-market positioning through AI-assisted surgical planning integration with provincial distribution partners. For Investors and Strategic Acquirers: Distressed-cycle entries favor research-partnership bioprinting ventures in Shanghai and Beijing with NMPA breakthrough device pipeline visibility. Long-term viability hinges on regulatory velocity advantages and substrate sourcing control across the projection horizon. Monitor NMPA Class III certification timeline compression as the primary inflection signal for domestic manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Breakthrough Device Pathway | Accelerated review timelines compress domestic manufacturer time-to-market against multinational incumbents. |
| Bioprinting Research Partnership | Academic collaborations in Zhangjiang Hi-Tech Park differentiate tissue-engineered graft development capabilities. |
| Provincial GPO Contract Consolidation | Integrated service bundling displaces spot purchasing in Beijing and Guangdong health system tenders. |
| Titanium Substrate Backward Integration | Captive supply of aerospace-grade alloys insulates against geopolitical sourcing friction and cost volatility. |
| AI-Assisted Surgical Planning Integration | Topology optimization workflows command premium positioning in bundled orthopedic implant contracts. |
Study Parameters
Document review covered NMPA device registration databases, GB standards biocompatibility protocols, and provincial centralized procurement tender disclosures, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from SAMR policy circulars, dual carbon goals framework implementation reports, and hospital procurement expenditure records. Bottom-up procedure volume modeling and top-down market sizing triangulated across manufacturer shipment data and import-export customs records.
Historical implant shipment trajectories cross-referenced against expert panel inputs on NMPA review timeline evolution and procurement rule changes. Segmentation modeling spanned product type, technology platform, end-user facility tier, and application specialty across the analysis window. CAGRs derived from procedure volume elasticity to aging demographics, trauma incidence, and surgical capability expansion in coastal versus interior provinces. Forecast inputs incorporated bioprinting cost curve trajectories and breakthrough device designation velocity assumptions.
Underlying measurement precision varies by segment; NMPA Class III cardiac implants carry tighter precision than emerging bioprinting applications where clinical adoption remains formative. Forecasts reflect documented assumptions regarding regulatory acceleration, procurement centralization pace, and substrate supply stability. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that geopolitical sourcing disruptions or abrupt NMPA policy shifts could materially revise trajectory projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Stool Management Systems Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market