
 Europe Bioresorbable Vascular Scaffold Market | 2026-2036
Europe Bioresorbable Vascular Scaffold Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bioresorbable Vascular Scaffold Market Intelligence
Modular scaffold configurations paired with delivery system bundles is expanding choice for European cath labs seeking procedure-specific solutions. BIOTRONIK SE & Co. KG leverages its German manufacturing base to sustain proximity to major implanting centers. Abbott Laboratories anchors its position through specialized R&D programs focused on next-generation polymer degradation profiles. Boston Scientific Corporation competes by extending its interventional cardiology portfolio across Western European hospital networks.
Europe bioresorbable vascular scaffolds are implantable coronary devices fabricated from biodegradable polymers such as poly-L-lactic acid (PLLA) or magnesium alloys, designed to provide transient radial support during arterial healing before complete resorption within 24-36 months. Their primary purpose is restoring vessel patency while eliminating permanent metallic foreign bodies that trigger late adverse events. The material dimension shows PLLA-based platforms dominating current clinical utilization due to established degradation kinetics, while magnesium alloy variants represent the fastest-growing category as manufacturers resolve early corrosion control challenges. Coronary artery disease applications occupy the largest share of procedure volume, though peripheral artery disease indications are gaining traction as vascular surgeons seek alternatives to permanent metal stents in below-the-knee interventions.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies demanding extended clinical follow-up data that extends development timelines and raises compliance costs for scaffold manufacturers. EMA guidelines on absorbable implantables further shape trial design requirements, particularly around endpoints measuring vessel restoration rather than mere patency. Germany's Federal Institute for Drugs and Medical Devices (BfArM) maintains stringent evaluation protocols that influence adoption patterns across neighboring EU markets. Stakeholders must monitor how evolving MDR implementation timelines and national reimbursement decisions interact to determine viable commercialization pathways for novel scaffold platforms.
Market Dynamics
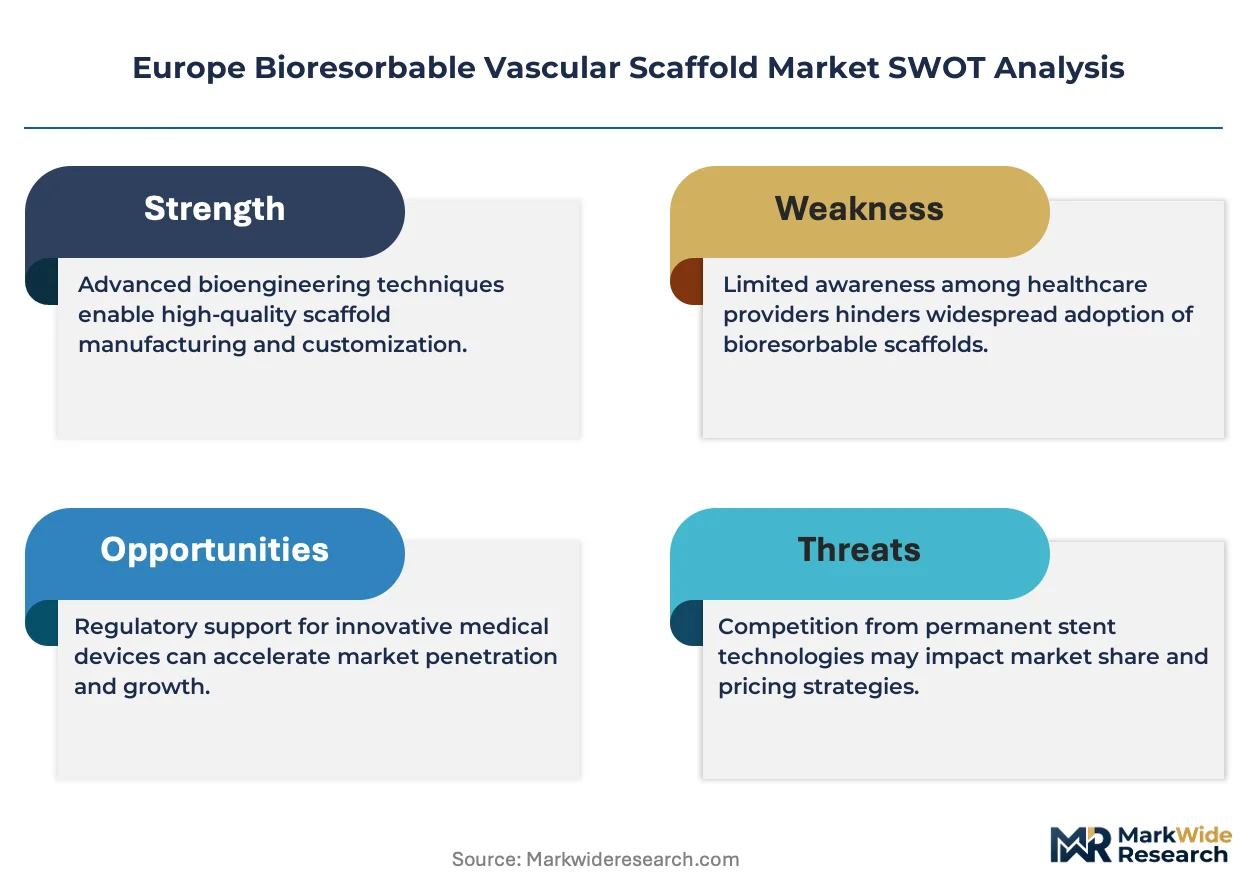
The EU Medical Device Regulation is compressing development timelines while forcing scaffold manufacturers to front-load clinical evidence generation, creating a structural squeeze between compliance costs and reimbursement certainty.
Growth Catalysts
- Biodegradable polymer advancement:Poly-L-lactic acid platforms now demonstrate predictable 24-month resorption profiles that satisfy BfArM durability requirements. German interventional cardiology centers are standardizing these configurations for left anterior descending artery procedures.
- CE marking pathway refinement:Notified bodies in the Netherlands and Germany have streamlined technical documentation review for magnesium alloy variants. This regulatory momentum accelerates market entry for corrosion-controlled scaffold platforms.
- France:The country's national health technology assessment body has issued favorable reimbursement opinions for bioresorbable scaffolds in complex coronary lesions. Parisian university hospitals are expanding catheterization lab capacity accordingly.
Market Restraints
- Extended clinical follow-up mandates:The EU MDR requires 5-year patient tracking for absorbable implantables. This structural barrier extends development cycles and ties up capital in longitudinal trial infrastructure.
- Polymer precursor concentration:High-purity PLLA resin supply concentrates among three European chemical processors. Input cost volatility for medical-grade polymers directly compresses scaffold gross margins.
- Metallic stent substitution threat:Drug-eluting stents with biodegradable polymers represent a mature, lower-cost alternative. Italian regional purchasing consortia actively benchmark bioresorbable pricing against these established platforms.
Strategic Opportunities
- Peripheral artery disease expansion:Below-the-knee interventions in diabetic patients remain underpenetrated. Vascular surgery units in Spain and Portugal are piloting magnesium scaffolds for tibial artery revascularization.
- EMA adaptive pathway designations:The agency's accelerated assessment framework for breakthrough devices creates regulatory tailwinds. Manufacturers can leverage conditional approval mechanisms based on intermediate vessel restoration endpoints.
- Direct-to-hospital distribution:Bypassing traditional device distributors reduces markup layers. Specialist scaffold producers are building captive sales forces to serve high-volume German cardiac centers directly.
Industry Challenges
- Interventional cardiologist training gaps:Scaffold deployment requires distinct technique refinement compared to metallic stent placement. European catheterization labs face bottlenecks in proctored case volume for credentialing.
- MDR notified body capacity constraints:Certification backlog at designated conformity assessment bodies delays CE marking timelines. Manufacturers queue for technical file review amid limited auditor availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bioresorbable Vascular Scaffold Market |
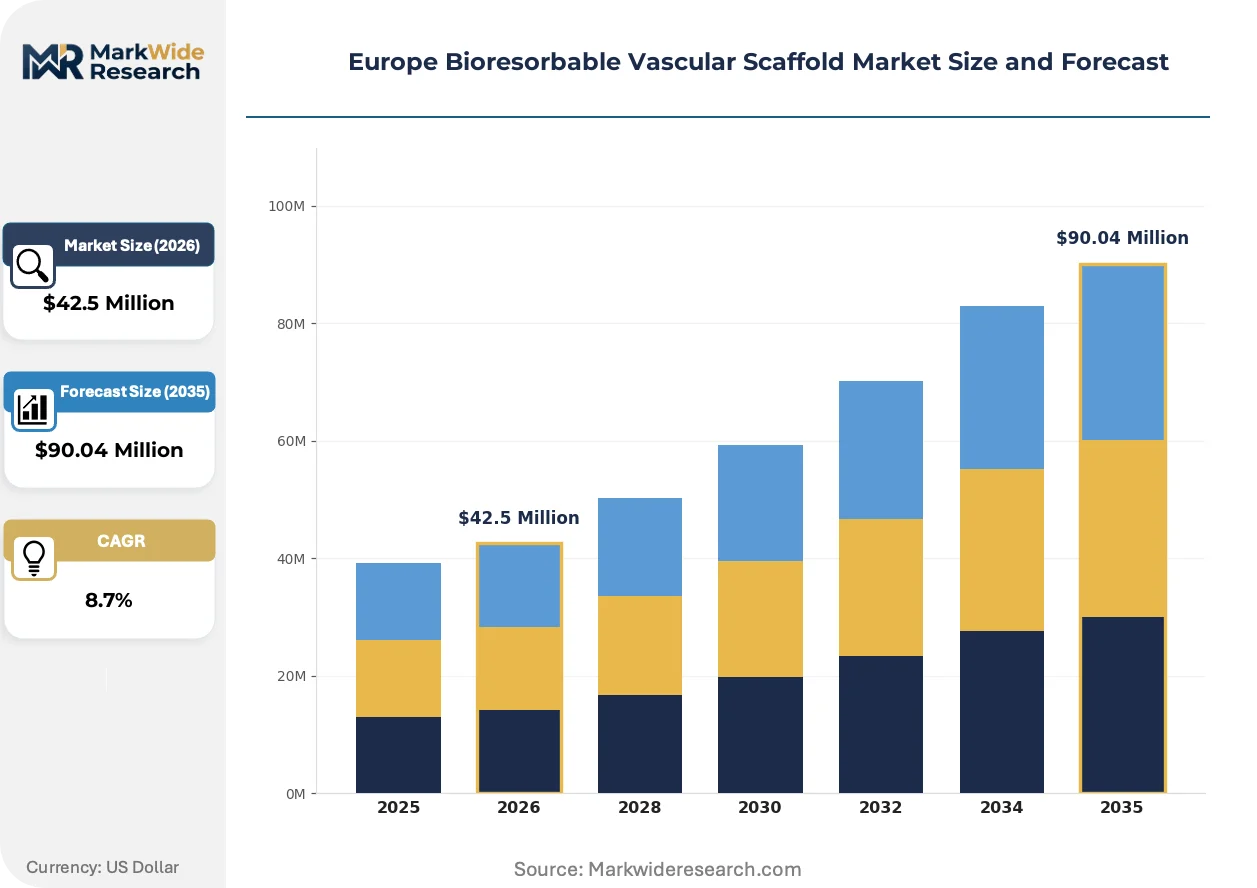
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $90.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DES, BVS, Biodegradable Stent, Coated Stent End User: Hospitals, Cardiology Clinics, Research Laboratories, Academic Institutions Material: PLA, PGA, PLLA, Magnesium Alloy Application: Coronary Artery Disease, Peripheral Artery Disease, Angioplasty, Vascular Surgery |
| Companies Covered | BIOTRONIK SE & Co. KG, Arterial Remodeling Technologies SA, Abbott Laboratories, Medtronic, Boston Scientific Corporation, REVA Medical, Elixir Medical Corp., Maquet Holding B.V. & Co. KG, B. Braun Melsungen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bioresorbable Vascular Scaffold Market Strategic Shifts & Innovations
Material science convergence with digital imaging analytics is redefining how scaffold performance gets measured and reimbursed across European cath labs.
Magnesium alloy scaffold technology is expanding into coronary applications as manufacturers resolve early corrosion control challenges through proprietary coating chemistries. French and Italian interventional cardiology departments are adopting these platforms for bifurcation lesions where rapid endothelialization matters. The technology is expanding into procedure categories previously reserved for polymer-based alternatives, compressing the historical material-segmentation of the market.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to integrate real-world evidence capture into commercial infrastructure. Scaffold producers must now fund patient registries and adverse event reporting systems that operate across multiple member states. High-volume implanting centers in Germany and the Netherlands are negotiating data-sharing agreements that offset registry participation costs against device pricing.
Hospital procurement committees are consolidating vendor relationships around full interventional cardiology portfolios rather than standalone scaffold purchases. Cardiac centers in Belgium and Austria now bundle scaffold procurement with catheter, guidewire, and imaging system contracts. This concentration of purchasing authority favors manufacturers with broad coronary intervention portfolios over scaffold-specialist suppliers.
Europe Bioresorbable Vascular Scaffold Market Segmentation
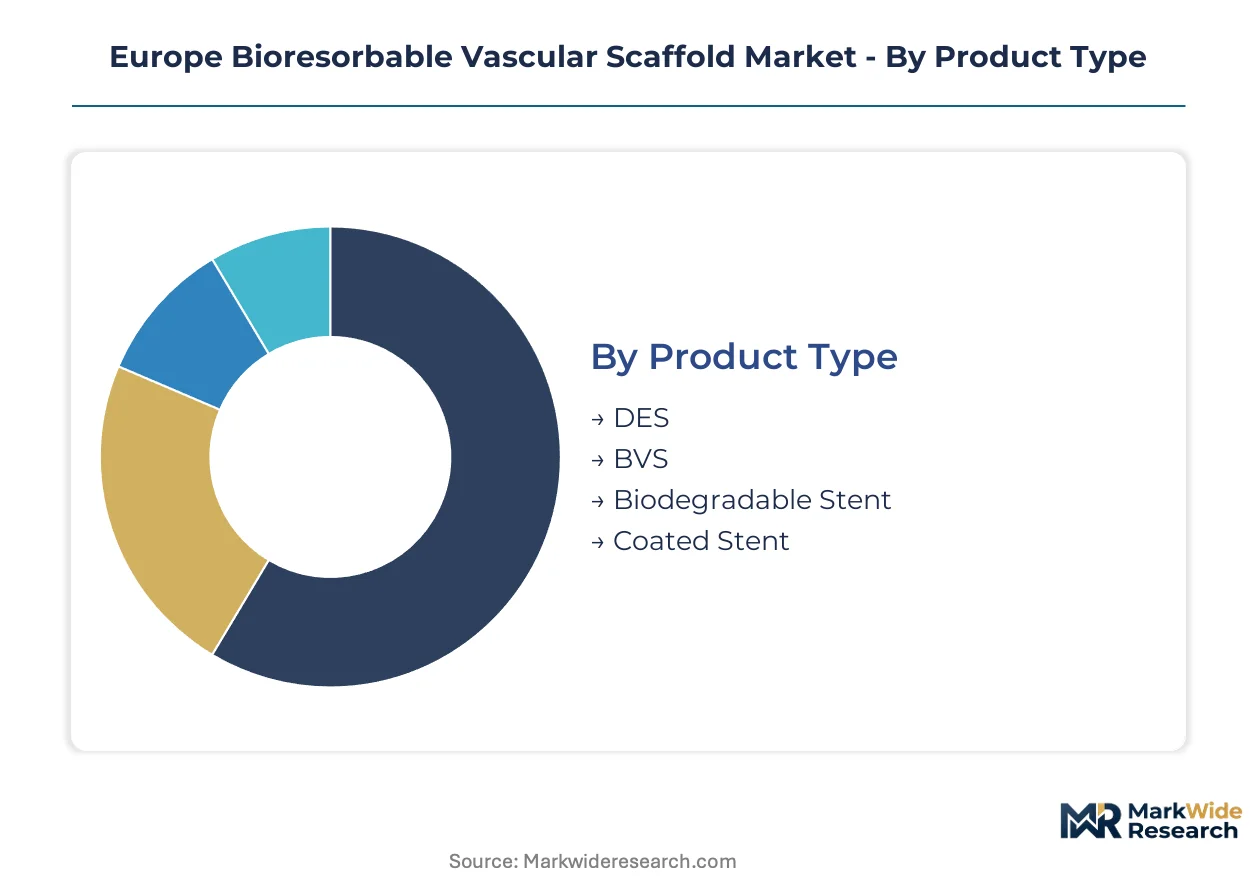
Segmentation in the Europe bioresorbable vascular scaffold market reveals how capital allocation, regulatory pathways, and clinical adoption intersect across distinct technology and customer categories. Understanding these divisions helps manufacturers prioritize R&D spending and distribution investments.
Product Type:
Capital requirements vary sharply across scaffold architectures, with polymer-based platforms demanding extended biodegradation testing infrastructure while metallic alternatives require corrosion-control manufacturing investments.
- DES:Drug-eluting scaffolds integrate antiproliferative agents with biodegradable polymer matrices. German university hospitals concentrate demand for these configurations in complex lesion cases where restenosis prevention outweighs resorption timeline concerns.
- BVS:Bioresorbable vascular scaffolds represent the core technology category, fabricated from PLLA or magnesium alloys to provide transient radial support. French interventional cardiology centers in Paris and Lyon are standardizing BVS deployment for left anterior descending artery procedures as reimbursement pathways stabilize.
- Biodegradable Stent:Simpler architectures without drug coatings serve cost-sensitive procurement environments.
- Coated Stent:Surface-modified metallic platforms with biodegradable polymer layers occupy a transitional market position.
BVS absorbs the bulk of installed capacity; biodegradable stent configurations are expanding most quickly as regional purchasing consortia seek intermediate price points.
End User:
Customer concentration patterns show high-volume cardiac centers driving procurement scale while research institutions shape early technology validation.
- Hospitals:Tertiary cardiac centers with catheterization labs generate the dominant procedure volume. German hospital networks including Charité Berlin and Heidelberg University Hospital maintain dedicated BVS implantation programs with proctored credentialing pathways.
- Cardiology Clinics:Specialized interventional cardiology facilities concentrate expertise and drive adoption velocity. Italian private clinic chains in Lombardy and Emilia-Romagna are expanding BVS capacity following favorable regional reimbursement decisions.
- Research Laboratories:Academic medical centers and contract research organizations conduct preclinical and clinical validation studies.
- Academic Institutions:Medical schools and teaching hospitals train the next generation of interventional cardiologists on scaffold deployment techniques.
Hospitals command the largest procurement budgets; cardiology clinics are climbing the fastest as outpatient intervention volumes rise.
Material:
Raw material sourcing and processing sophistication create tiered manufacturing economics across polymer and metallic feedstocks.
- PLA:Polylactic acid offers established biodegradation kinetics and broad chemical processing infrastructure. Netherlands-based polymer suppliers serve scaffold manufacturers with medical-grade resin meeting CE marking biocompatibility requirements.
- PGA:Polyglycolic acid provides faster resorption profiles suited to specific vascular healing timelines.
- PLLA:Poly-L-lactic acid dominates current clinical utilization with predictable 24-month degradation profiles. German BfArM evaluation protocols have validated PLLA durability for coronary applications, anchoring adoption across neighboring EU markets.
- Magnesium Alloy:Corrosion-controlled metallic platforms represent the steepest expansion trajectory as coating technologies resolve early endothelialization challenges. Spanish and Portuguese vascular surgery units are piloting magnesium scaffolds for below-the-knee interventions in diabetic patients.
PLLA holds the largest installed manufacturing base; magnesium alloy platforms are gaining share fastest as corrosion engineering matures.
Application:
Procedure category penetration reflects both clinical evidence accumulation and specialty-specific reimbursement dynamics.
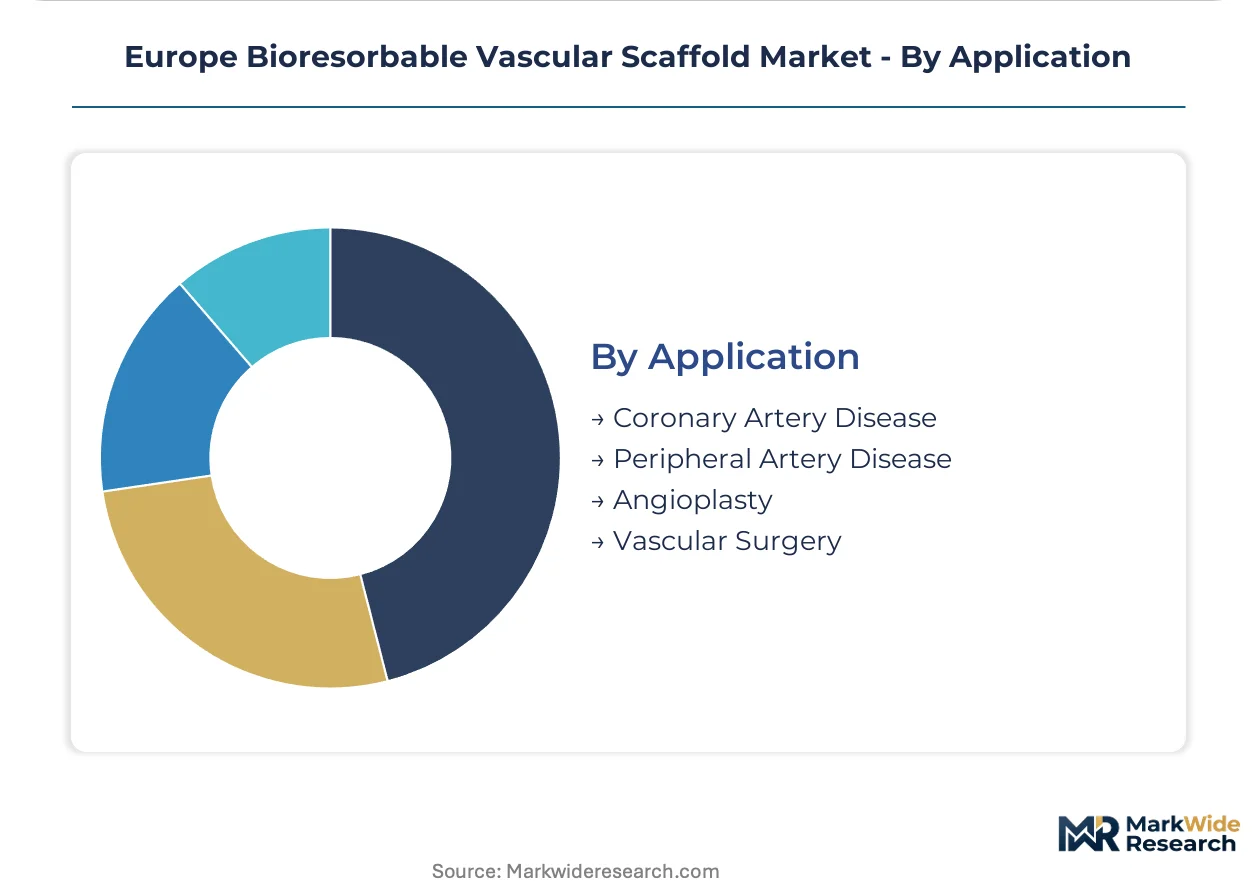
- Coronary Artery Disease:Transient scaffold support during arterial healing delivers maximum value in coronary interventions where late stent thrombosis risks dominate long-term outcomes. Belgian cardiac centers bundle BVS procurement with diagnostic catheter contracts for comprehensive coronary care programs.
- Peripheral Artery Disease:Below-the-knee revascularization in diabetic patients remains underpenetrated. Austrian vascular surgery departments are expanding magnesium scaffold evaluation for tibial artery procedures where permanent metal stents historically failed.
- Angioplasty:Scaffold-assisted balloon angioplasty procedures combine mechanical dilation with temporary structural support.
- Vascular Surgery:Open and endovascular surgical applications extend scaffold utility beyond percutaneous catheter-based interventions.
Coronary artery disease commands the dominant procedure volume; peripheral artery disease is expanding most quickly as vascular surgeons seek alternatives to permanent implants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scaffold production concentrates in Germany and the Netherlands, while consumption spreads across Western European cardiac centers. German manufacturers supply PLLA-based platforms to French and Italian implanting hospitals. Regional demand patterns diverge as reimbursement frameworks mature at uneven speeds.
Germany
Charité Berlin and Heidelberg University Hospital drive procedure volume for complex coronary interventions. The Federal Institute for Drugs and Medical Devices maintains stringent evaluation protocols that shape adoption across neighboring EU markets. Bavarian manufacturing clusters around Munich and Erlangen produce medical-grade PLLA resin for scaffold fabrication.
France
Parisian university hospitals expand catheterization lab capacity following favorable reimbursement opinions from the national health technology assessment body. ANSM oversees post-market surveillance for absorbable implantables under EU MDR implementation. The Lyon cardiac cluster pilots magnesium alloy scaffolds for bifurcation lesions.
Italy
Lombardy and Emilia-Romagna private clinic chains scale BVS capacity after regional reimbursement decisions stabilized. Italian regional purchasing consortia benchmark bioresorbable pricing against drug-eluting stents with biodegradable polymers. Milan-based interventional cardiology centers train specialists on scaffold deployment techniques.
Spain
Vascular surgery units in Madrid and Barcelona pilot magnesium scaffolds for below-the-knee interventions in diabetic patients. Spanish notified bodies participate in CE marking technical documentation review for corrosion-controlled platforms. Catalan cardiac centers negotiate data-sharing agreements for EU MDR-mandated patient registries.
Netherlands
Eindhoven-region polymer suppliers serve scaffold manufacturers with medical-grade resin meeting CE marking biocompatibility requirements. Dutch notified bodies streamlined technical documentation review for magnesium alloy variants. Amsterdam cardiac centers bundle scaffold procurement with diagnostic imaging system contracts.
Europe Bioresorbable Vascular Scaffold Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across scaffold material categories and application segments. The vendor base clusters around three tiers: German and Swiss manufacturers with integrated polymer supply chains, US-based multinationals with broad interventional cardiology portfolios, and emerging specialists in magnesium alloy corrosion engineering. Strategic moves center on M&A to secure polymer precursor supply and direct-to-hospital distribution buildouts that bypass traditional device distributors.
Among diversified medical technology conglomerates, Abbott Laboratories and Boston Scientific Corporation occupy positions defined by interventional cardiology portfolio breadth. BIOTRONIK SE & Co. KG anchors the European manufacturer tier with proximity to German implanting centers. REVA Medical exemplifies the specialist archetype focused on scaffold-specific degradation profile engineering.
| Leading Market Players |
|---|
| BIOTRONIK SE & Co. KG |
| Arterial Remodeling Technologies SA |
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| REVA Medical |
| Elixir Medical Corp. |
| Maquet Holding B.V. & Co. KG |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
EU MDR sustainability mandates for biodegradable implantables gate qualified supply access and premium-tier pricing power, as manufacturers must fund multi-year patient registries and adverse event reporting systems that compliant German and Dutch producers amortize through elevated contract pricing.
Pricing Analysis
Margin tightening in standard-tier scaffolds reflects Italian regional purchasing consortia benchmarking bioresorbable platforms against drug-eluting stents with biodegradable polymers. Three-tier pricing structure across premium, standard, and economy levels differentiates by CE marking tier and procedural complexity bundle. Cost-down pressure accelerates as hospital procurement committees consolidate vendor relationships around full interventional cardiology portfolios. Cardiology clinics demonstrate highest price sensitivity; German university hospitals with dedicated BVS programs exhibit lowest.
Supply Chain Analysis
Direct-to-hospital distribution channels handle high-volume German cardiac center demand, bypassing traditional device distributors. Medical-grade PLLA resin concentrates in Netherlands and German Bavarian chemical processing clusters. Magnesium alloy feedstock draws from specialized European metallurgical suppliers. Single-source vulnerability in high-purity polymer precursor supply creates structural exposure. Distribution runs through captive sales forces and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer precursor supply and patient registry infrastructure constitutes the critical vertical-integration race, as EU MDR compliance costs and reimbursement certainty gaps determine sustainable competitive position.
For Market Incumbents: Acquire PLLA resin processing capacity in Bavaria or Netherlands to secure input cost stability against volatile medical-grade polymer pricing. Build proprietary patient registry infrastructure spanning German, French, and Spanish implanting centers to deflect MDR compliance cost pressure from distributor-dependent rivals. Drug-eluting stents with biodegradable polymers represent the substitution threat requiring portfolio breadth defense. For New Entrants and Emerging Players: Begin with magnesium alloy corrosion engineering for below-the-knee peripheral interventions in Spain and Portugal, where vascular surgeons seek alternatives to permanent metal stents and reimbursement pathways remain unsettled. Target direct-to-hospital distribution in Austrian and Belgian cardiac centers bundling scaffold procurement with diagnostic imaging systems. For Investors and Strategic Acquirers: EMA adaptive pathway designations for breakthrough devices are the leading indicator that corrosion-controlled magnesium platforms will achieve accelerated market access. Five-to-ten year viability favors specialists with integrated coating chemistry and biodegradable polymer degradation profile expertise. Monitor BfArM durability validation decisions as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined technical documentation review at Dutch and German notified bodies accelerates magnesium alloy platform market entry. |
| Hospital System Partnership | Data-sharing agreements with Charité Berlin and Heidelberg University Hospital offset EU MDR-mandated registry participation costs. |
| Backward Integration | Captive PLLA resin processing in Bavarian manufacturing clusters reduces input cost volatility and margin compression. |
| Reimbursement Strategy | Favorable opinions from France's national health technology assessment body stabilize procurement pathways for complex coronary lesions. |
| Software Companion Development | Digital imaging analytics integration redefines scaffold performance measurement and reimbursement justification across European cath labs. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, biomedical engineering consultations, and GPO contracts manager discussions underwrites the qualitative findings. Primary fieldwork engaged interventional cardiologists, vascular surgeons, regulatory affairs specialists at notified bodies, and polymer supply chain managers. Secondary validation drew from EMA guideline documents, BfArM evaluation protocols, CE marking technical file databases, and hospital procurement records. Bottom-up procedure volume modeling and top-down market sizing triangulate value estimates.
Comparable-period anchoring to historical implantation volumes and reimbursement decision timelines structured the projection horizon. Segmentation dimensions modeled include product architecture, material chemistry, application category, and end-user facility type. CAGRs derive from procedure volume trajectories, pricing elasticity assumptions, and regulatory pathway probability weightings. Magnesium alloy corrosion control maturation and MDR implementation timeline uncertainty constitute industry-specific forecast inputs.
Underlying measurement precision varies by segment; coronary artery disease applications carry tighter precision than peripheral artery disease pilots given reimbursement pathway maturity. Forecasts reflect assumptions around EU MDR notified body capacity expansion and national health technology assessment body decision timelines. Periodic stress-testing of base assumptions against BfArM protocol updates and EMA adaptive pathway designation frequency is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Bionic Eye Market