
 Artificial Organ Bank Market | 2026-2036
Artificial Organ Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Organ Bank Market Outlook
Aftermarket bioreactor maintenance and organ conditioning services is rewriting margin capture across the value chain. Medtronic Inc. anchors its position through captive perfusion device networks that extend service contracts beyond initial hardware sales. Boston Scientific Corporation competes via specialized catheter-based delivery systems for implantable artificial tissues. Edwards Lifesciences Corporation dominates structural heart replacement platforms, leveraging decades of hemodynamic engineering to occupy premium positions in cardiac organ banking.
An artificial organ bank comprises cryopreserved, bioreactor-maintained, or on-demand manufactured biological and synthetic constructs designed for therapeutic implantation, drug testing, or disease modeling, typically stored under controlled temperatures between minus 150 degrees Celsius and 4 degrees Celsius with perfusion protocols that preserve cellular viability. These facilities serve healthcare providers, pharmaceutical developers, and research institutions requiring immediate access to immunocompatible tissues without cadaveric donor dependency. Bioengineered organs command the dominant value share given their functional equivalence to native tissues and extended preservation windows, while organ-on-a-chip platforms represent the fastest-expanding category as pharmaceutical companies seek predictive toxicology models that reduce animal testing burdens. Synthetic tissues maintain stable demand in dermal and orthopedic applications where off-the-shelf availability outweighs biological complexity requirements.
The FDA enforces current good tissue practice regulations and regenerative medicine advanced therapy pathways that dictate manufacturing standards and clinical evidence thresholds for banked artificial organs seeking commercial approval. The European Medicines Agency applies the advanced therapy medicinal products framework and medical device regulation requirements that create dual compliance obligations for cross-border tissue banking operations. The International Organization for Standardization publishes ISO 14155 and ISO 21973 guidelines governing clinical investigation and characterization of bioengineered tissues, establishing baseline quality benchmarks that national regulators reference. Stakeholders must monitor evolving reimbursement coding decisions by Medicare and major European statutory health insurers, as payment policy lags behind regulatory clearance and determines whether artificial organ banks achieve sustainable utilization rates.
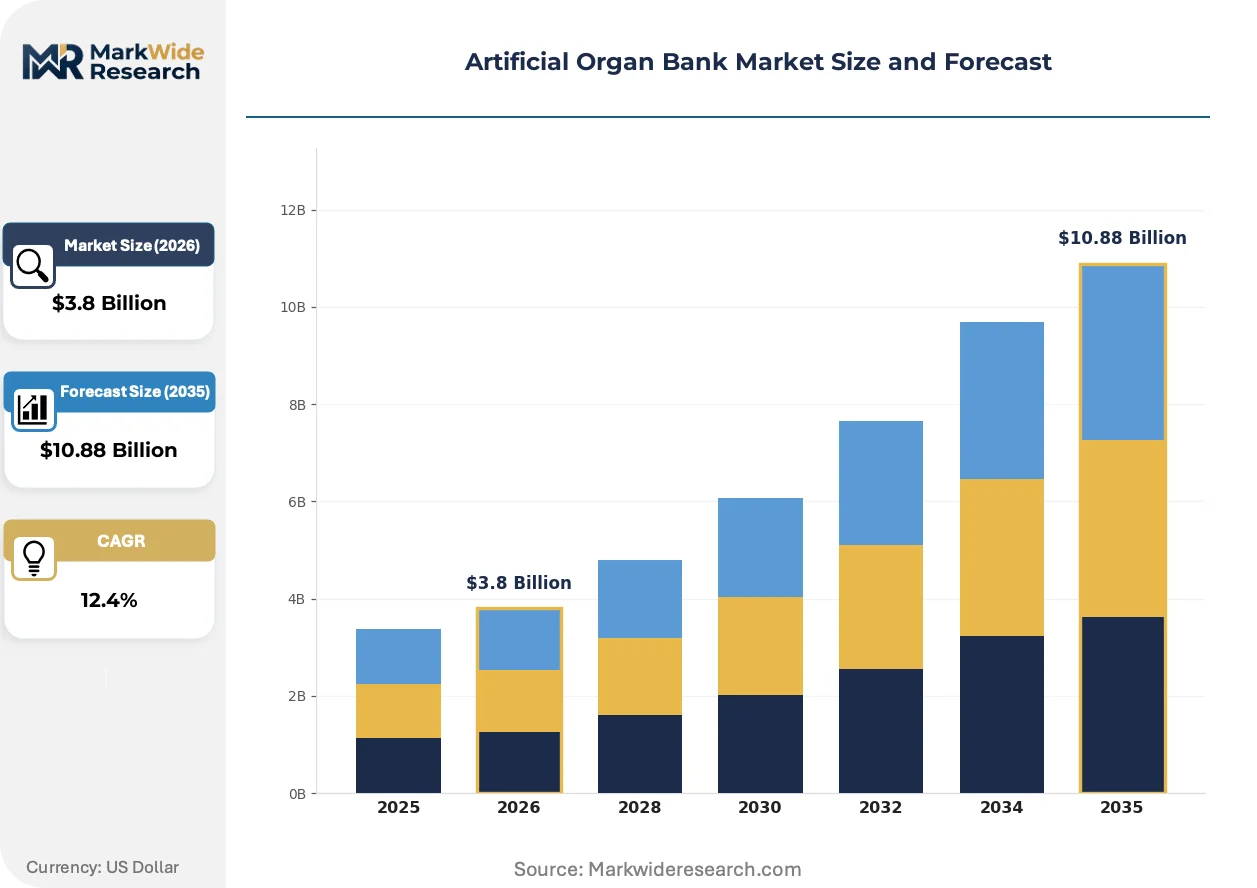
Market Dynamics
Bioreactor-perfusion infrastructure is consolidating procurement decisions around facilities capable of maintaining cellular viability across extended preservation windows, concentrating demand among integrated health systems with captive organ conditioning capabilities.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy Designation:Accelerated clinical trial pathways compress development timelines for bioengineered heart and kidney constructs, reducing regulatory friction for transplantation centers scaling procurement.
- Waitlist Volume Pressure:Cadaveric supply chain strain in the United States and Germany is forcing healthcare providers toward manufactured alternatives with predictable availability and immunocompatible matching.
- Organ-on-a-Chip Toxicology:Pharmaceutical developers are adopting microfluidic tissue platforms to replace animal testing, creating parallel demand streams beyond therapeutic implantation.
Market Restraints
- Cryopreservation Input Costs:Liquid nitrogen supply volatility and specialized perfusate chemistry expenses constrain margin expansion for regional banking facilities without captive bioreactor networks.
- Dual Compliance Burden:Cross-border tissue banking between the United States and European Union faces overlapping FDA current good tissue practice and EMA advanced therapy medicinal products obligations.
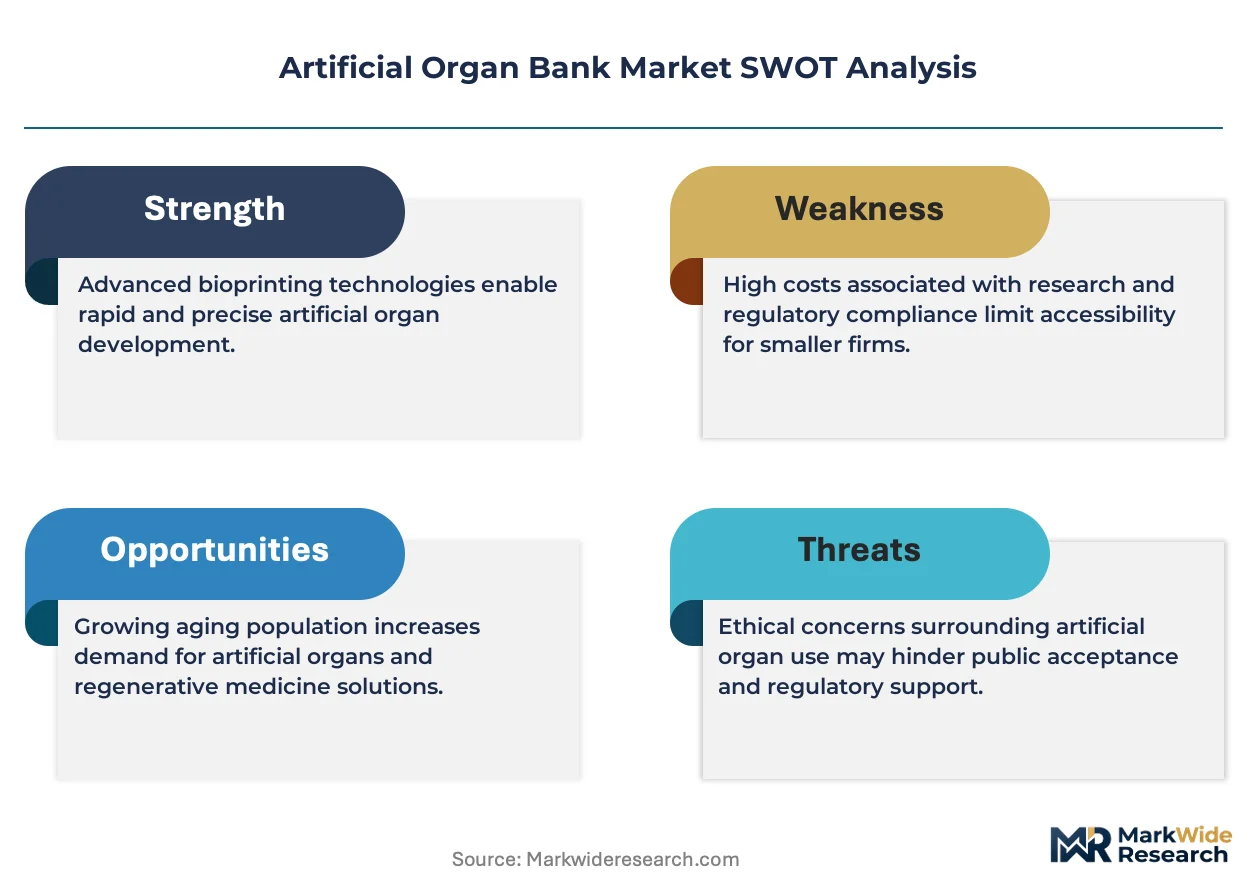
- Biological Complexity Ceiling:Vascularized organ manufacturing remains technically constrained by endothelialization protocols, limiting functional equivalence for liver and lung constructs relative to cardiac applications.
Strategic Opportunities
- Japan Reimbursement Maturation:PMDA pathway alignment with statutory health insurance coding creates first-mover advantage for artificial heart valve banking operations targeting Asia-Pacific transplantation networks.
- Decentralized Manufacturing:Point-of-care bioreactor installations at major academic medical centers enable on-demand organ production, bypassing centralized cold chain logistics.
- ISO 21973 Harmonization:Standardized characterization protocols for bioengineered tissues reduce regulatory duplication costs, accelerating multi-jurisdictional market entry for compliant manufacturers.
Industry Challenges
- Bioengineering Talent Scarcity:Cross-disciplinary expertise combining tissue engineering, perfusion physiology, and regulatory science remains concentrated at fewer than two dozen academic programs globally.
- Capex-Intensive Facility Buildout:Cleanroom infrastructure, captive liquid nitrogen generation, and redundant power systems require eight-figure investments before revenue-generating tissue banking operations commence.
- Reimbursement Lag:Medicare coding decisions for artificial organ interventions trail FDA clearance by multiple years, creating utilization rate uncertainty for early commercial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Organ Bank Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioengineered Organs, Synthetic Tissues, Organ-on-a-Chip, 3D Printed Organs End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Academic Institutions Application: Transplantation, Drug Testing, Disease Modeling, Regenerative Medicine Technology: Tissue Engineering, Biomaterials, Genetic Engineering, Microfabrication |
| Companies Covered | Medtronic Inc., Boston Scientific Corporation, Edwards Lifesciences Corporation, Berlin Heart GmbH, Jarvik Heart Inc., Second Sight Medical Products Inc., Abiomed Inc., Ekso Bionics, Lifenet Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Organ Bank Market Strategic Shifts
Preservation technology convergence with real-time metabolic monitoring is redefining quality assurance protocols, shifting competitive advantage toward facilities with integrated viability analytics rather than passive cold storage capabilities.
Hypothermic machine perfusion systems is migrating from experimental preservation adjunct to standard-of-care infrastructure for cardiac and renal constructs. Major transplantation centers in the United States and Germany are adopting these platforms at accelerating pace. This technology is compressing geographic constraints on organ matching by extending viable transport windows from hours to days, enabling interstate and international banking networks.
EMA advanced therapy medicinal products framework revisions are tightening manufacturing site inspection frequency for cross-border tissue shipments. Industrial consequence includes mandatory quality management system upgrades at third-party bioreactor facilities. Cardiac construct manufacturers with European distribution ambitions are responding by establishing captive production within EU member states rather than relying on United States-based supply.
Service unbundling is separating organ conditioning from implantation procedures, creating standalone revenue streams for specialized perfusion teams. Transplantation centers are disaggregating traditional bundled payments, contracting separately with artificial organ banks for viability maintenance. This pattern is most visible in the United States, where Medicare's transplant diagnosis-related group structures are adapting to accommodate discrete banking fees.
Artificial Organ Bank Market Segmentation
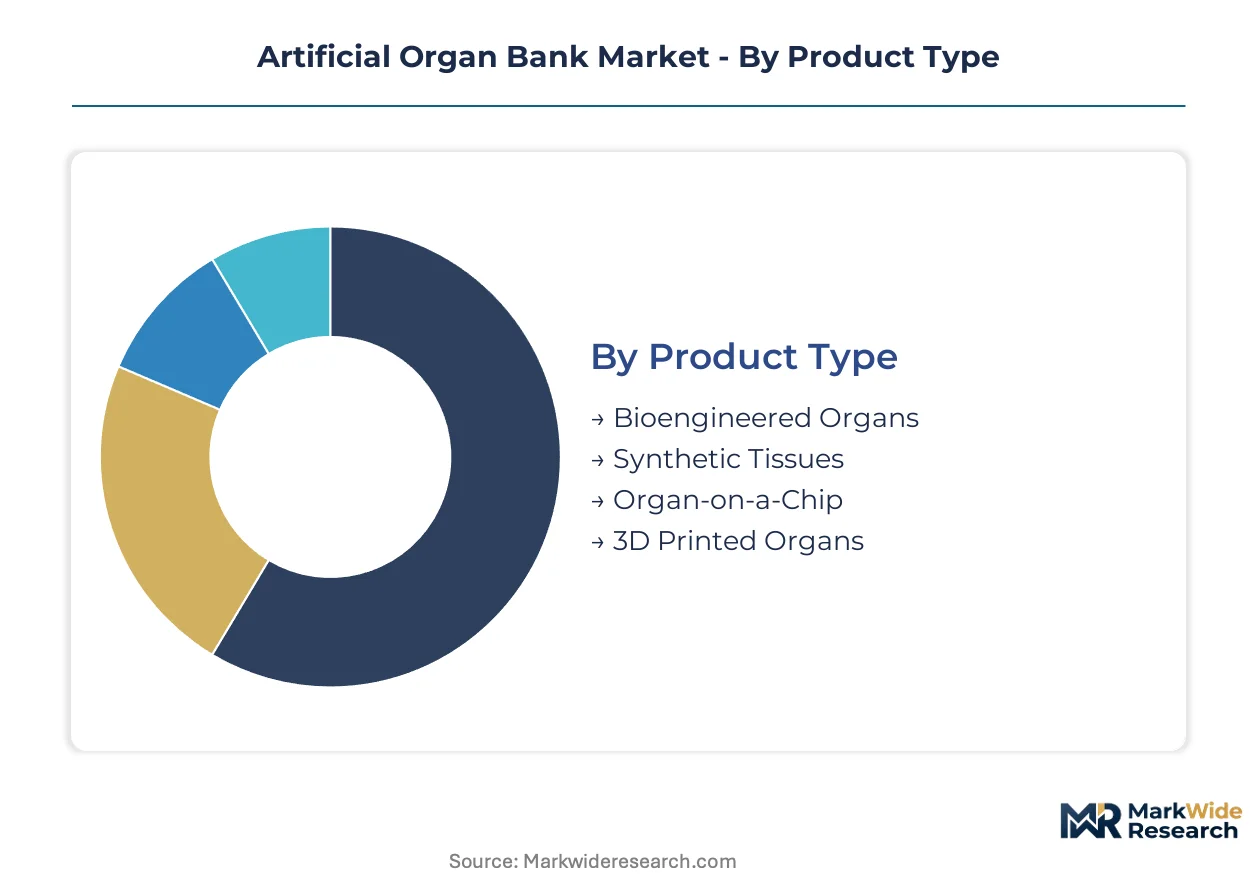
Segmentation in artificial organ banking reveals divergent value capture models across therapeutic versus research applications. Product type determines infrastructure requirements, while end-user concentration shapes pricing power and contract structures.
Product Type:
The use-case spectrum spans implantable therapeutics demanding immunocompatibility to disposable research platforms prioritizing throughput over longevity.
- Bioengineered Organs:Living cellular constructs derived from patient-specific or allogeneic stem cells, maintained in bioreactor-perfusion systems until implantation. Transplantation centers in the United States and Germany are scaling procurement as cadaveric waitlists strain, though endothelialization complexity limits liver and lung applications relative to cardiac constructs.
- Organ-on-a-Chip:Microfluidic tissue platforms integrating multiple cell types on engineered substrates to replicate organ-level physiology. Pharmaceutical companies in the United States and Japan are displacing animal toxicology studies with these predictive models, compressing preclinical timelines and reducing regulatory submission risks.
- Synthetic Tissues:Acellular scaffolds or polymer-based substitutes for dermal and orthopedic applications where off-the-shelf availability outweighs biological functional requirements.
- 3D Printed Organs:Additively manufactured constructs using bioinks combining cells, growth factors, and hydrogel matrices, currently constrained by vascular network resolution limits.
The dominant share belongs to Bioengineered Organs, while Organ-on-a-Chip is closing the gap fastest.
End User:
Customer concentration varies by procurement sophistication, with integrated health systems commanding volume discounts unavailable to fragmented research buyers.
- Healthcare Providers:Transplantation centers and academic medical hospitals requiring immediate access to immunocompatible tissues with guaranteed viability windows. Procurement decisions in the United States increasingly favor facilities with captive bioreactor networks over third-party banks.
- Pharmaceutical Companies:Developers seeking predictive toxicology platforms and disease models for lead optimization. Contract structures emphasize throughput guarantees and regulatory documentation packages for FDA submission support.
- Research Institutions:Independent laboratories with intermittent demand patterns and limited cold chain infrastructure, typically purchasing smaller lots at premium per-unit pricing.
- Academic Institutions:University-based programs combining educational procurement with exploratory bioengineering research, often qualifying for discounted pricing through consortium arrangements.
Healthcare Providers capture the largest revenue concentration, though Pharmaceutical Companies are expanding procurement fastest as toxicology outsourcing accelerates.
Application:
Application maturity correlates with regulatory pathway clarity, with transplantation facing the steepest evidence thresholds.
- Transplantation:Therapeutic implantation of manufactured organs as alternatives to cadaveric donation. Reimbursement lag in the United States and Germany creates utilization uncertainty despite FDA and EMA regulatory clearances for select cardiac constructs.
- Drug Testing:Preclinical safety and efficacy screening using human-relevant tissue models. Adoption concentrates among mid-cap pharmaceutical developers seeking to de-risk IND submissions before expensive animal studies.
- Disease Modeling:Patient-specific tissue constructs replicating pathophysiology for mechanistic research and personalized therapeutic development.
- Regenerative Medicine:Cell-based therapies and tissue repair applications outside full organ replacement, including wound healing and orthopedic reconstruction.
Transplantation generates the highest per-unit revenue, while Drug Testing is scaling volume fastest.
Technology:
Technology differentiation determines barrier height, with genetic engineering requiring capital intensity that excludes regional competitors.
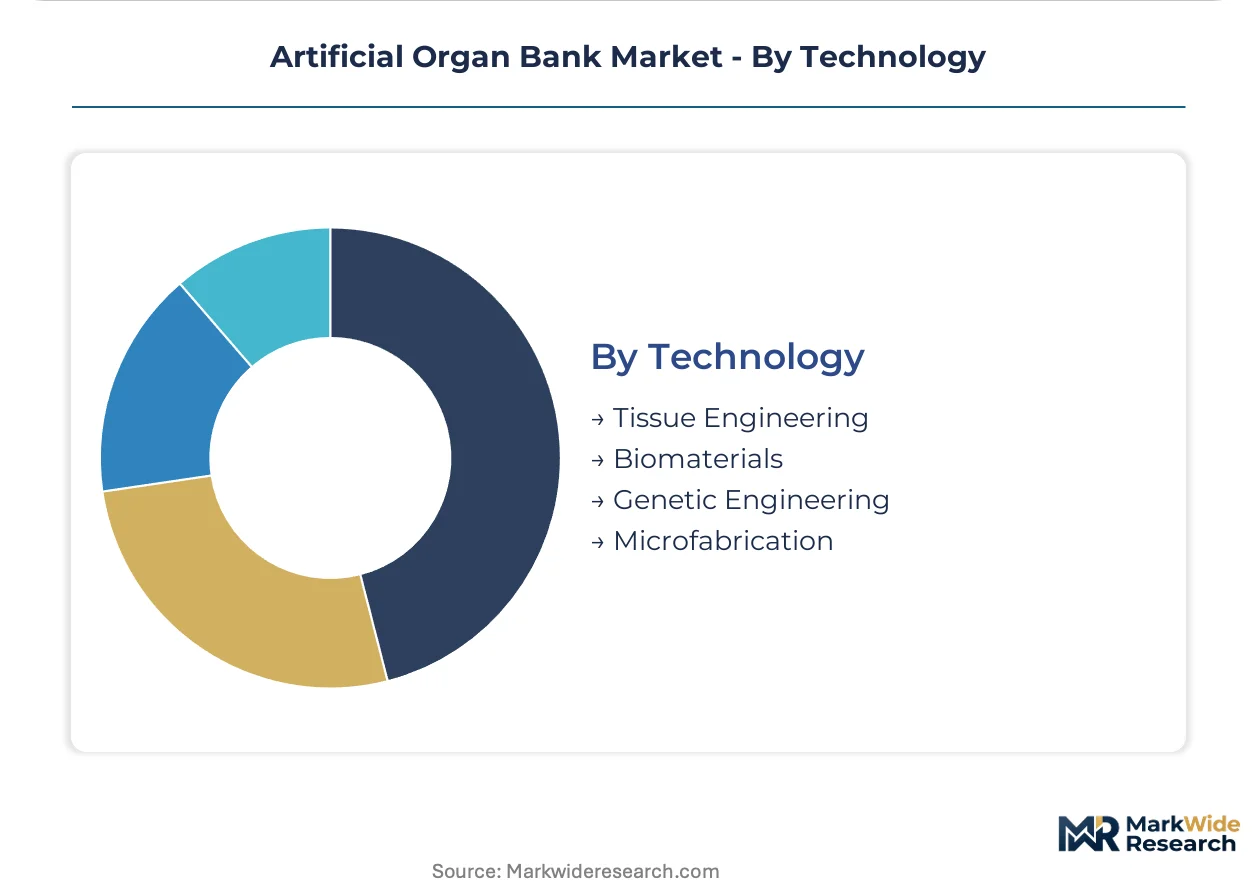
- Tissue Engineering:Scaffold-based cellular cultivation combining biomaterials with bioreactor perfusion protocols. Maturity is highest in cardiac applications where hemodynamic conditioning protocols are standardized.
- Genetic Engineering:CRISPR-based immunomodulation and knock-out strategies to reduce rejection risk and enable xenotransplantation pathways. Concentration remains among fewer than two dozen academic programs with combined gene editing and perfusion expertise.
- Biomaterials:Hydrogel, decellularized matrix, and synthetic polymer development for scaffold and bioink applications.
- Microfabrication:Precision engineering of microfluidic channels and electrode arrays for organ-on-a-chip and neural interface platforms.
Tissue Engineering commands established revenue share, though Genetic Engineering is climbing fastest as xenotransplantation trials advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in Germany demonstrate lowest price elasticity as statutory reimbursement frameworks mature, while research institutions in India exhibit highest sensitivity to per-unit tissue costs. Transplantation centers in the United States occupy a middle position where bundled payment structures partially offset premium pricing for bioengineered constructs.
United States
FDA regenerative medicine advanced therapy designation accelerates clinical trial enrollment for cardiac constructs at Cleveland Clinic and Mayo Clinic transplantation networks. Medicare reimbursement coding for artificial heart valves creates predictable payment pathways that de-risk procurement decisions. Boston Scientific Corporation and Edwards Lifesciences Corporation anchor manufacturing capacity in California and Minnesota, extending service contracts beyond hardware sales into perfusion maintenance.
Germany
Statutory health insurance frameworks for engineered tissues mature fastest in Europe, enabling transplantation centers in Berlin and Munich to scale bioengineered kidney procurement. EMA advanced therapy medicinal products framework mandates dual compliance with medical device regulation for cross-border tissue shipments. Berlin Heart GmbH maintains captive production within EU member states to bypass United States-based supply dependencies.
Japan
PMDA pathway alignment with statutory health insurance coding creates first-mover positioning for artificial heart valve banking operations targeting Asia-Pacific networks. METI funding for regenerative medicine infrastructure concentrates bioreactor installations at University of Tokyo and Osaka University medical centers. Domestic pharmaceutical developers displace animal toxicology studies with organ-on-a-chip platforms manufactured in Kansai industrial corridors.
India
CDSCO regulatory harmonization with ISO 21973 standards reduces multi-jurisdictional market entry costs for compliant tissue manufacturers. Price-sensitive research institutions in Maharashtra and Karnataka drive demand for synthetic tissue alternatives where biological complexity requirements remain modest. Bioreactor-perfusion infrastructure concentrates at All India Institute of Medical Sciences and Christian Medical College Vellore.
United Kingdom
NHS England specialized commissioning frameworks for engineered tissues create procurement concentration among integrated academic medical centers in London and Manchester. MHRA post-Brexit regulatory autonomy enables divergence from EMA inspection frequencies for third-party bioreactor facilities. Oxford and Cambridge university spinouts dominate organ-on-a-chip development for pharmaceutical toxicology outsourcing.
Artificial Organ Bank Market Competitive Environment
Integrated device-perfusion networks and specialized catheter platforms split the market between full-stack service providers and component specialists. The vendor base concentrates among fewer than ten entities with captive bioreactor capabilities, though regional tissue banks fragment the long tail. Cardiac construct manufacturers and organ-on-a-chip developers represent distinct strategic archetypes with divergent capital intensity requirements. Competitive moves center on backward integration into liquid nitrogen generation and strategic partnerships with academic medical centers for clinical trial site designation.
Among United States-based medical technology conglomerates, Medtronic Inc. and Boston Scientific Corporation exemplify the integrated device-perfusion archetype, while Edwards Lifesciences Corporation occupies premium positioning in structural heart replacement platforms. These three entities anchor the competitive landscape through decades of hemodynamic engineering accumulation and captive service network extension.
| Leading Market Players |
|---|
| Medtronic Inc. |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Berlin Heart GmbH |
| Jarvik Heart Inc. |
| Second Sight Medical Products Inc. |
| Abiomed Inc. |
| Ekso Bionics |
| Lifenet Health |
| Others |
Value Chain & Pricing Dynamics
Minneapolis-St. Paul anchors North American bioreactor manufacturing capacity, where captive liquid nitrogen generation and redundant cleanroom infrastructure concentrate pricing power among integrated device-perfusion networks serving transplantation centers.
Pricing Analysis
Aftermarket service contracts and extended perfusion maintenance agreements drive lifetime value capture beyond initial hardware sales. Three-tier pricing structure across premium bioreactor-perfusion bundles, standard cryopreservation services, and economy synthetic tissue alternatives stratifies the market. Cost compression in mid-tier organ conditioning services is intensifying because regional banking facilities without captive networks face input volatility. Research institutions exhibit highest price sensitivity, while integrated health systems in Germany demonstrate lowest elasticity due to mature statutory reimbursement frameworks.
Supply Chain Analysis
Export-control restrictions on CRISPR-based gene editing tools and advanced bioreactor control systems limit technology flows between United States and Chinese research institutions. Manufacturing capacity concentrates in the United States, Germany, and Japan, with specialized perfusate chemistry and decellularized matrix scaffolds drawing from captive supplier networks. Single-source vulnerability in liquid nitrogen regional distribution creates supply risk for facilities without on-site generation. Distribution runs through transplantation center GPO contracts and pharmaceutical developer direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial organ banking fragments across therapeutic implantation and research platform demand, with organ-on-a-chip toxicology outsourcing creating distinct niches beyond traditional transplantation procurement.
For Market Incumbents: Insulate core perfusion service revenue by backward integration into liquid nitrogen generation and captive bioreactor manufacturing capacity. Lock in long-term GPO contracts with major academic medical centers before Medicare reimbursement coding decisions mature. Defensive certification investment in ISO 21973 harmonization reduces regulatory duplication costs against emerging regional competitors.
For New Entrants and Emerging Players: India exhibits lowest penetration of hypothermic machine perfusion infrastructure among major research economies, creating white-space opportunity for synthetic tissue banking at price points accessible to CDSCO-compliant manufacturers. Target pharmaceutical toxicology outsourcing in Kansai industrial corridors through organ-on-a-chip platform partnerships. Go-to-market leverage rests on throughput guarantees with regulatory documentation packages for FDA submission support.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because bioreactor-perfusion networks exhibit natural monopoly characteristics once installed base reaches critical mass. Acquisition focus: mid-cap specialists with combined tissue engineering and genetic engineering capabilities spanning fewer than two dozen academic programs globally. Watch PMDA reimbursement pathway alignment with statutory health insurance coding as Asia-Pacific inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor-Perfusion Network Expansion | Captive infrastructure at Cleveland Clinic and Mayo Clinic transplantation networks locks in GPO contract renewals. |
| ISO 21973 Harmonization Compliance | Standardized characterization protocols reduce EMA and FDA dual compliance burdens for cross-border manufacturers. |
| Organ-on-a-Chip Platform Launch | Microfluidic tissue platforms manufactured in Kansai corridors displace animal toxicology studies for Japanese pharmaceutical developers. |
| Point-of-Care Bioreactor Installation | Decentralized manufacturing at University of Tokyo and Osaka University medical centers bypasses centralized cold chain logistics. |
| Reimbursement Strategy Development | Medicare coding alignment for artificial heart valves creates predictable payment pathways in United States transplantation networks. |
Study Parameters
Initial hypotheses were tested against primary input from transplantation center procurement directors, biomedical engineers, regulatory affairs specialists at EMA and FDA, and GPO contracts managers, then refined through secondary validation against CMS Medicare reimbursement databases, ClinicalTrials.gov regenerative medicine entries, hospital procurement records, and ISO standard development documentation. Bottom-up demand modeling from end-user procurement patterns combined with top-down supply capacity assessments across bioreactor manufacturing facilities.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, end user concentration, application maturity, and technology differentiation dimensions. CAGRs were derived from installed base expansion rates and pricing trajectory assumptions, with specific inputs including waitlist volume pressure in United States transplantation networks and pharmaceutical toxicology outsourcing adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by mid-cap regional banking facilities or breakthrough endothelialization protocols for liver and lung constructs would shift outcomes. Material shifts in FDA regenerative medicine advanced therapy designation criteria or EMA advanced therapy medicinal products framework revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Bioprosthetics Market