
 Mutation Generation Systems Market | 2026-2036
Mutation Generation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mutation Generation Systems Market Foresight
ISO 13485 certification for in vitro diagnostic device quality management is reorganizing vendor eligibility across the mutation generation systems landscape. Thermo Fisher Scientific leverages its captive reagent supply chain to dominate sequencing instrument deployments. Bio-Rad Laboratories anchors its position through specialized PCR thermal cyclers for high-throughput mutation screening. Lonza differentiates via contract development capabilities that extend into custom cell-line engineering for pharmaceutical clients.
Mutation generation systems comprise integrated hardware and reagent platforms designed to introduce, detect, and characterize targeted genetic alterations at single-nucleotide resolution, operating through thermal cycling, enzymatic modification, or direct nucleic acid cleavage with typical throughput rates exceeding 10,000 variants per run. These systems serve pharmaceutical discovery pipelines by enabling rapid validation of genotype-phenotype relationships and therapeutic target identification. Editing Tools command premium pricing due to CRISPR guide RNA synthesis complexity and intellectual property licensing overhead. Agricultural Biotechnology represents the fastest-expanding application segment as seed developers adopt targeted mutagenesis for trait stacking and regulatory-compliant gene editing.
FDA oversight of gene-editing therapeutic products and EPA coordination on plant-incorporated protectants create dual compliance thresholds for system vendors entering clinical and ag-bio end markets. EMA's Advanced Therapy Medicinal Products framework and China's NMPA gene-therapy technical guidelines further fragment market access requirements across jurisdictions. Stakeholders must monitor evolving germline editing moratoria and national biosecurity export controls that could restrict CRISPR component shipments to designated research institutions.
Market Dynamics
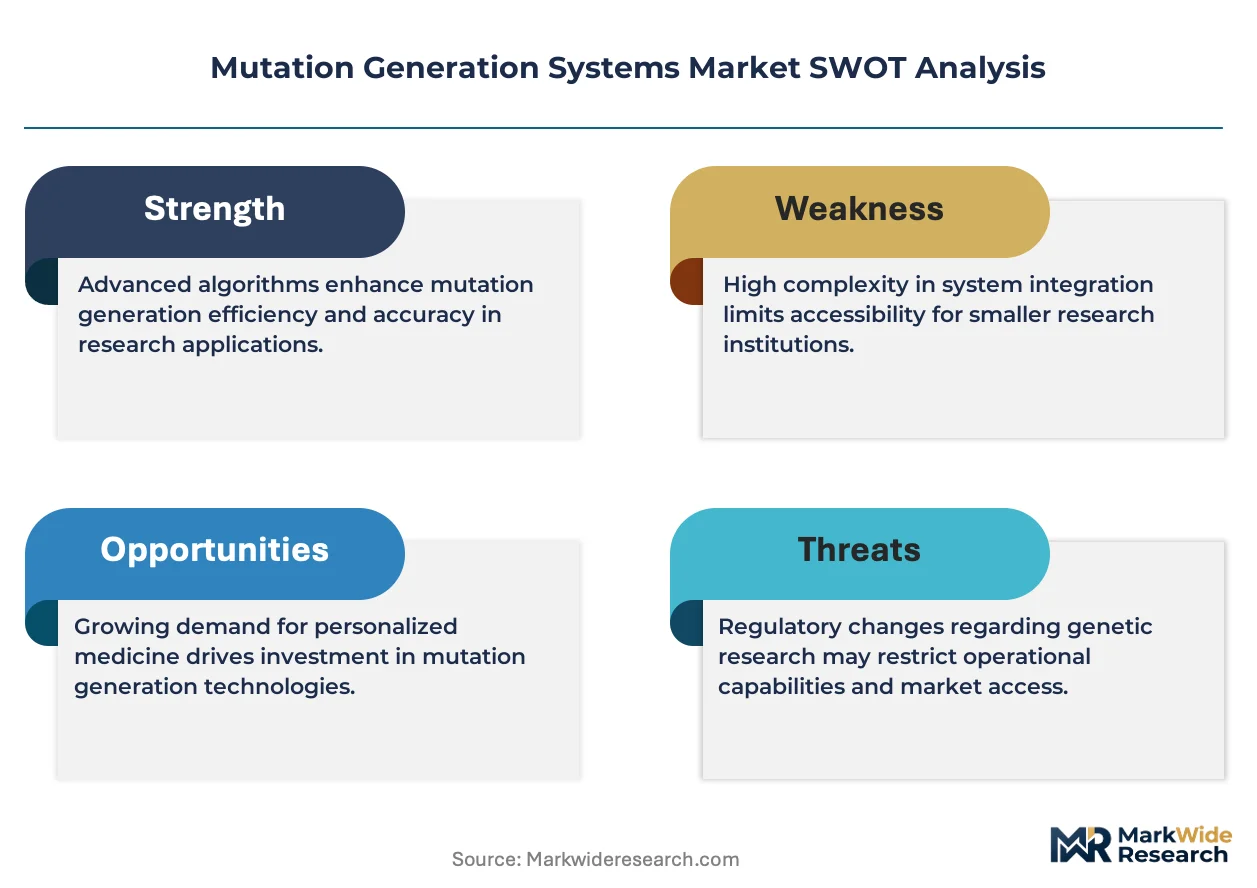
CRISPR platform maturation is compressing R&D timelines across pharmaceutical and agricultural pipelines, forcing vendors to upgrade hardware-software integration while navigating fragmented multi-jurisdictional approval frameworks for gene-edited outputs.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Accelerated clinical trial pathways for gene therapies in the European Union drive sequencing infrastructure investment by contract research organizations.
- Seed developer trait-stacking demand:Agricultural biotechnology firms deploy targeted mutagenesis systems to stack multiple traits while maintaining regulatory-compliant non-transgenic status under EPA plant-incorporated protectant guidelines.
- Enzymatic modification throughput gains:Thermal cycling platforms achieving single-nucleotide resolution at 10,000-plus variants per run compress validation cycles for genotype-phenotype mapping.
Market Restraints
- Guide RNA synthesis cost volatility:Intellectual property licensing overhead and complex chemical synthesis requirements inflate reagent pricing for CRISPR editing tools.
- Reagent supply concentration:Captive supply chains controlled by dominant sequencing instrument vendors create procurement bottlenecks for mid-tier research institutions.
- Germline editing moratoria:National biosecurity export controls restrict CRISPR component shipments to designated research institutions in multiple jurisdictions.
Strategic Opportunities
- China NMPA gene-therapy technical guidelines:Evolving regulatory clarity creates market access pathways for foreign system vendors targeting biotech clusters in Shanghai and Shenzhen.
- Base editing convergence with next-generation sequencing:Integration of cytosine and adenine base editors with real-time readout platforms opens precision medicine applications beyond knockouts.
- ISO 13485 certification gap:In vitro diagnostic device quality management certification remains sparse among specialized PCR thermal cycler manufacturers, creating first-mover advantage for compliant entrants.
Industry Challenges
- Bioinformatics integration complexity:Legacy laboratory information management systems require costly middleware development to interface with cloud-based variant analysis pipelines.
- Dual-use research of concern protocols:Institutional biosafety committees impose extended review timelines for experiments involving pathogenic organism genetic modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mutation Generation Systems Market |
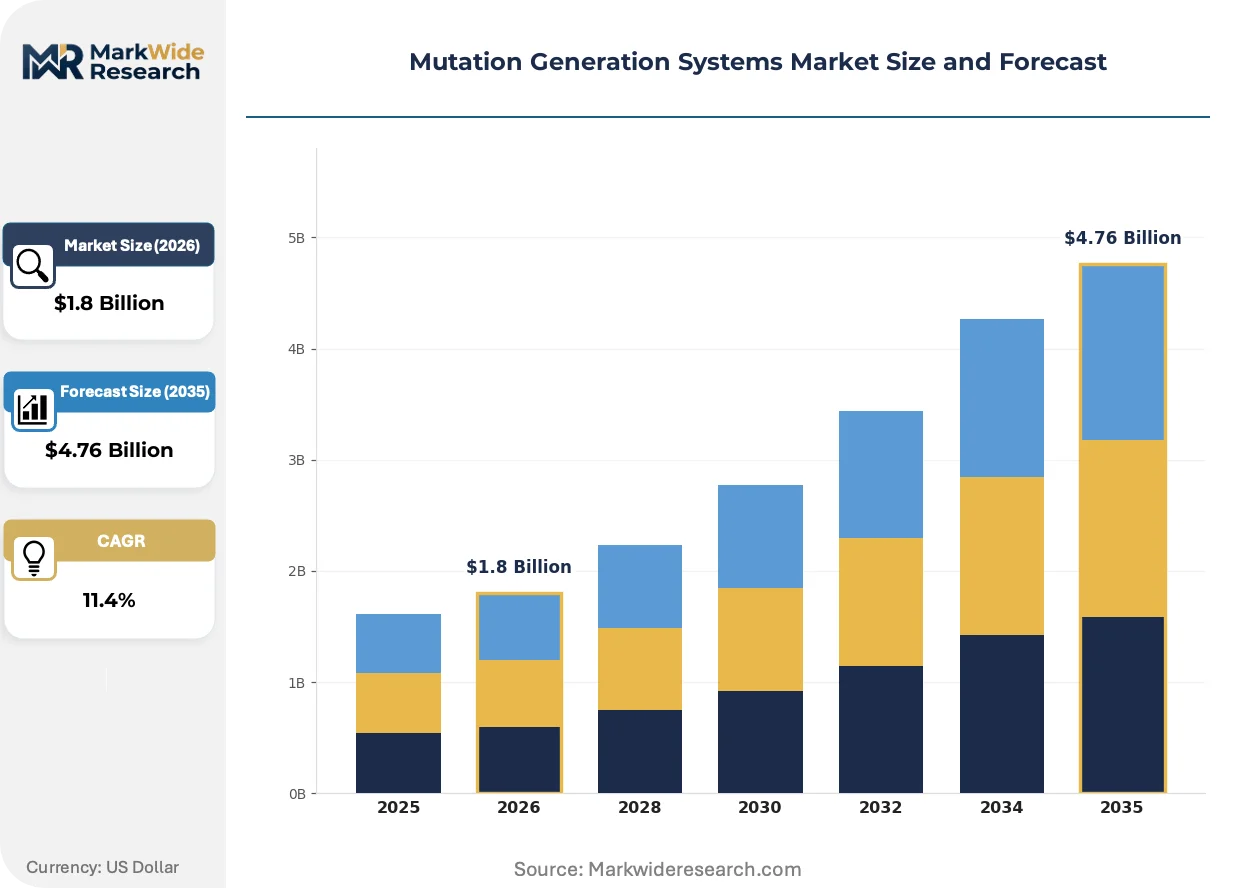
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Instruments, PCR Systems, Editing Tools, Analyzers Application: Genetic Research, Drug Development, Disease Treatment, Agricultural Biotechnology End User: Academic Institutions, Pharmaceutical Companies, Research Laboratories, Biotech Firms Technology: CRISPR, Synthetic Biology, NGS, Genome Editing |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Lonza, Merck KGaA, Agilent Technologies, Illumina, New England Biolabs, Takara Bio, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mutation Generation Systems Market Shifts & Advancements
Platform architectures are splitting between high-throughput production systems and flexible benchtop units, with software-defined workflow automation becoming the primary differentiation axis.
Prime editing technology is bifurcating the precision editing landscape. The system enables all 12 types of point mutations plus small insertions and deletions without double-strand breaks. Agricultural biotechnology firms in the United States and seed developers in Germany are adopting prime editing at twice the pace of clinical research organizations. This capability is compressing the addressable market for traditional homology-directed repair platforms while expanding total accessible edit types.
EPA coordination with USDA on plant-incorporated protectant exemptions is reshaping regulatory burden distribution. Gene-edited crops lacking foreign DNA now face streamlined oversight relative to transgenic alternatives. Agricultural biotechnology application segments in the United States are responding by redirecting R&D expenditure from transgenic trait development toward targeted mutagenesis infrastructure.
Service unbundling is fragmenting traditional system vendor business models. Pharmaceutical discovery pipelines now procure editing reagents, hardware, and bioinformatics analysis from separate specialized suppliers rather than integrated platforms. This pattern is most visible in United States biotech clusters where contract development organizations negotiate à la carte component sourcing to optimize cost per validated target.
Mutation Generation Systems Market Segmentation
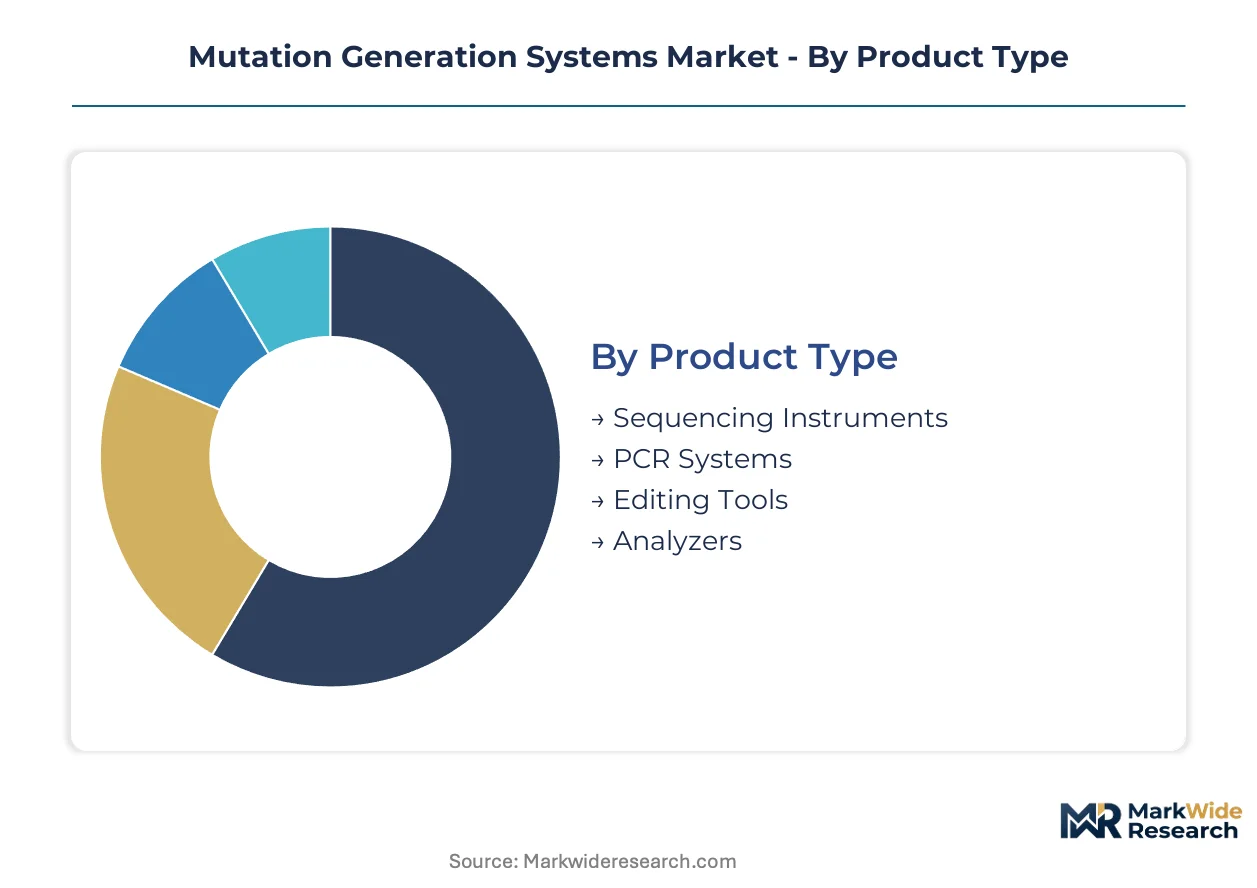
Mutation generation systems fragment across hardware, reagent, and software layers that command distinct margin profiles. Technology type and application end-use create the sharpest purchasing behavior divides among research and commercial buyers.
Product Type:
Margin pools concentrate in consumable reagents and precision editing components rather than capital equipment. Hardware platforms face pricing pressure from sequencing commoditization while specialized enzymatic tools retain premium positioning.
- Sequencing Instruments:High-throughput platforms achieving single-nucleotide resolution integrate thermal cycling with real-time detection optics. Pharmaceutical companies in the United States drive replacement cycles as CRISPR validation pipelines demand higher variant-per-run throughput.
- PCR Systems:Specialized thermal cyclers for mutation screening operate at 10,000-plus variants per run with software-defined workflow automation. Research laboratories in Germany prioritize ISO 13485-certified units for regulatory-compliant diagnostic development.
- Editing Tools:Guide RNA synthesis platforms with intellectual property licensing overhead.
- Analyzers:Integrated detection systems for genotype-phenotype mapping.
The dominant share belongs to Sequencing Instruments, while Editing Tools is closing the gap fastest.
Application:
End-use demand concentrates where regulatory pathways for gene-edited outputs have clarified. Agricultural biotechnology commands accelerating capital deployment as seed developers redirect R&D from transgenic to targeted mutagenesis approaches.
- Agricultural Biotechnology:Targeted mutagenesis systems enable trait stacking while maintaining non-transgenic status under EPA plant-incorporated protectant guidelines. Seed developers in the United States deploy prime editing at twice the pace of clinical research organizations, compressing validation timelines for drought resistance and yield optimization.
- Drug Development:Precision drug target validation pipelines require rapid genotype-phenotype relationship mapping. Pharmaceutical companies leverage CRISPR platform maturation to compress preclinical timelines, with contract research organizations in China expanding sequencing infrastructure to capture outsourced validation work.
- Genetic Research:Academic discovery programs with constrained capital budgets.
- Disease Treatment:Gene therapy development under FDA and EMA advanced therapy frameworks.
Agricultural Biotechnology claims the steepest expansion trajectory, though Drug Development retains the largest revenue footprint.
End User:
Procurement authority shifts with funding source and regulatory exposure. Pharmaceutical companies negotiate à la carte component sourcing while academic institutions remain tethered to integrated platform vendors with captive reagent supply.
- Pharmaceutical Companies:Discovery pipelines unbundle editing reagents, hardware, and bioinformatics from separate specialized suppliers. United States biotech clusters optimize cost per validated target through contract development organization negotiations, fragmenting traditional system vendor business models.
- Biotech Firms:Venture-backed developers prioritize flexible benchtop units with cloud-based variant analysis integration. Shanghai and Shenzhen clusters respond to evolving NMPA gene-therapy technical guidelines by scaling sequencing infrastructure for regulatory-compliant target validation.
- Academic Institutions:Budget-constrained procurement concentrated in multi-user core facilities.
- Research Laboratories:Government and privately funded discovery programs with middleware integration challenges.
Pharmaceutical Companies control the largest procurement volume, while Biotech Firms is gaining share fastest.
Technology:
Platform architectures split between established enzymatic systems and emerging precision modalities. Prime editing capability is bifurcating competitive positioning by enabling all 12 point mutation types without double-strand breaks.
- CRISPR:Guide RNA-programmable nucleases with mature IP licensing frameworks and established supplier ecosystems. Platform maturation compresses R&D timelines across pharmaceutical and agricultural pipelines, forcing hardware-software integration upgrades.
- Genome Editing:Encompasses base editors, prime editors, and homology-directed repair platforms with expanding edit type accessibility. Agricultural biotechnology firms in Germany adopt cytosine and adenine base editor integration with real-time readout for precision trait development.
- NGS:Next-generation sequencing readout platforms for variant characterization.
- Synthetic Biology:Cell-free and chassis organism engineering approaches for metabolic pathway optimization.
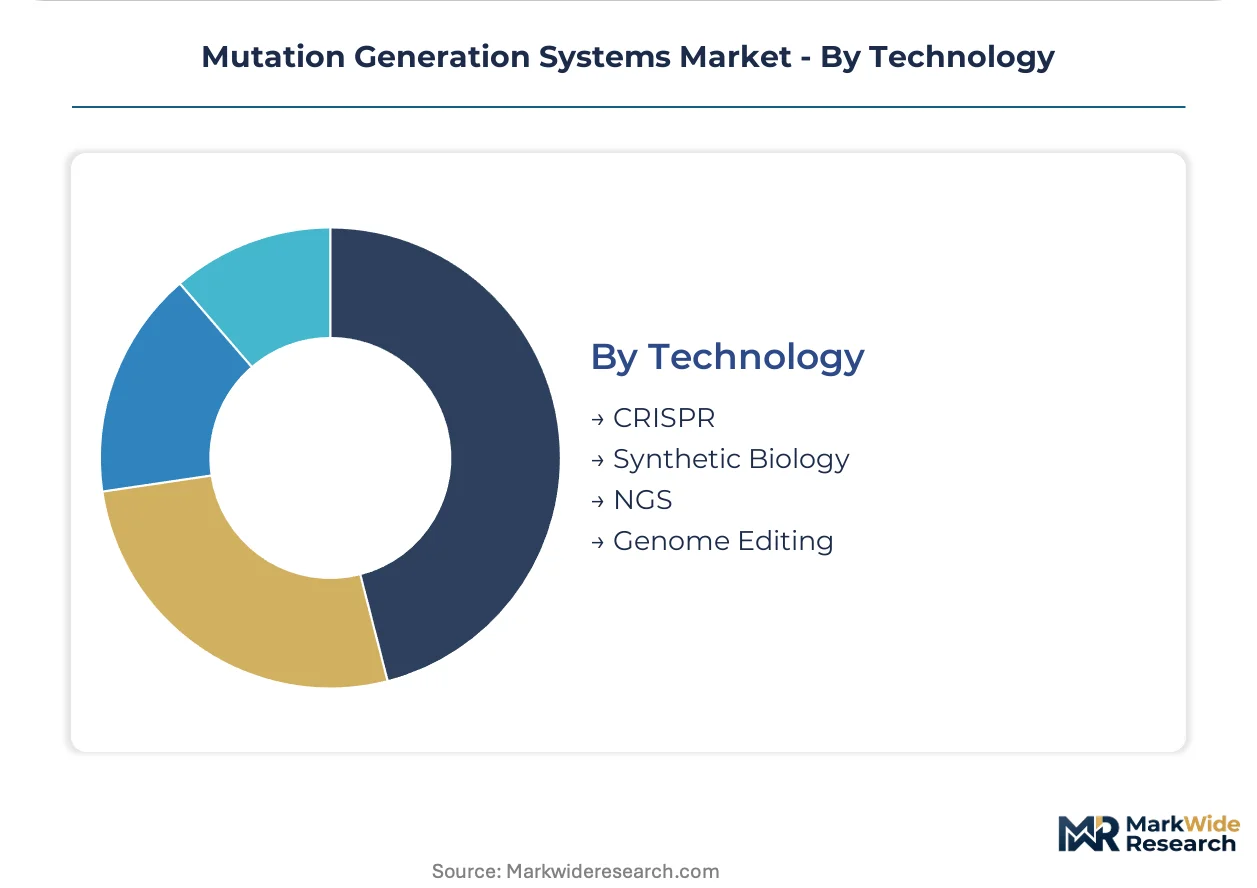
CRISPR maintains installed base dominance, though Genome Editing is climbing the fastest as base and prime editing platforms commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gene-editing therapeutic oversight and EMA Advanced Therapy Medicinal Products frameworks are accelerating sequencing infrastructure deployment across pharmaceutical clusters. Government-backed biotechnology initiatives in China and Germany are redirecting public research funding toward precision editing platforms. Patent licensing regimes and biosecurity export controls are fragmenting vendor access across jurisdictions.
United States
Pharmaceutical companies in Greater Boston and San Francisco Bay Area drive CRISPR validation pipeline expansion. EPA coordination with USDA on plant-incorporated protectant exemptions streamlines oversight for gene-edited crops lacking foreign DNA. Seed developers in the Midwest are redirecting R&D expenditure from transgenic trait development toward targeted mutagenesis infrastructure.
Germany
Agricultural biotechnology firms in Bavaria adopt cytosine and adenine base editors for precision trait development. EMA's Advanced Therapy Medicinal Products framework accelerates clinical trial pathways for gene therapies. Research laboratories in Baden-Württemberg prioritize ISO 13485-certified PCR thermal cyclers for regulatory-compliant diagnostic development.
China
Biotech clusters in Shanghai and Shenzhen scale sequencing infrastructure to capture outsourced pharmaceutical validation work. NMPA gene-therapy technical guidelines are evolving to create market access pathways for foreign system vendors. Contract research organizations in the Yangtze River Delta expand CRISPR platform deployments under state-backed precision medicine initiatives.
United Kingdom
Academic discovery programs in the Cambridge-London corridor concentrate multi-user core facility procurement around integrated platform vendors. The Medicines and Healthcare products Regulatory Agency aligns gene therapy oversight with EMA frameworks post-Brexit. Research laboratories in Oxford and Edinburgh face middleware integration challenges interfacing legacy systems with cloud-based variant analysis.
Japan
PMDA guidelines for regenerative medicine and gene therapy products are clarifying approval pathways for clinical editing applications. METI-funded biotechnology initiatives support prime editing adoption by agricultural research institutes in Tsukuba. Pharmaceutical firms in the Kanto region unbundle editing reagents and bioinformatics from separate specialized suppliers.
Mutation Generation Systems Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with captive reagent supply chains and specialized enzymatic tool developers. Market structure concentrates around three to five integrated platform vendors controlling sequencing instrument deployments, while mid-tier PCR thermal cycler manufacturers compete on certification compliance. Strategic archetypes include full-stack instrumentation providers, precision editing reagent specialists, and contract development organizations extending into custom cell-line engineering. Dominant competitive moves encompass ISO 13485 certification acquisition for diagnostic market eligibility and hardware-software integration upgrades to compress customer R&D timelines.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Illumina anchor positions through sequencing platform installed bases and captive consumable ecosystems. Bio-Rad Laboratories exemplifies the specialized thermal cycler archetype, occupying a position among ISO 13485-certified vendors targeting regulatory-compliant mutation screening workflows. Lonza represents the contract development extension model, sitting within service-oriented competitive positioning that reaches into custom cell-line engineering for pharmaceutical clients. Merck KGaA and Agilent Technologies occupy intermediate positions spanning reagent supply and analytical instrumentation. New England Biolabs, Takara Bio, and Promega Corporation cluster within the enzymatic reagent specialist tier.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Lonza |
| Merck KGaA |
| Agilent Technologies |
| Illumina |
| New England Biolabs |
| Takara Bio |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for CRISPR guide RNA synthesis lock in supply access and price visibility for pharmaceutical discovery pipelines, insulating United States biotech clusters from reagent cost volatility while exposing mid-tier research institutions to spot-market premiums.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-compliant PCR thermal cyclers and uncertified benchtop units. Three-tier pricing structure across premium, standard, and economy levels reflects intellectual property licensing overhead for CRISPR editing tools versus commoditized sequencing consumables. Cost compression in standard-tier hardware is intensifying because sequencing platform commoditization erodes capital equipment margins. Academic institutions exhibit highest price sensitivity due to constrained capital budgets, while pharmaceutical companies prioritize throughput per run over unit economics.
Supply Chain Analysis
Strategic stockpiling of guide RNA synthesis reagents dominates procurement behavior among contract research organizations facing biosecurity export control restrictions. Manufacturing concentration in the United States, Germany, and China anchors global supply for precision editing platforms. The chain draws from specialized enzymatic modification chemistries, synthetic oligonucleotide precursors, and optical detection components. Single-source vulnerability around captive reagent ecosystems controlled by dominant sequencing instrument vendors threatens mid-tier buyer access. Distribution runs through direct vendor relationships for pharmaceutical clients and academic core facility aggregators for research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in mutation generation systems reflects prime editing adoption doubling validation throughput for agricultural biotechnology firms, creating penetration headroom before platform maturation compresses hardware replacement cycles.
For Market Incumbents: Secure ISO 13485 certification pathways for diagnostic market eligibility while capturing prime editing integration contracts from seed developers redirecting R&D from transgenic approaches. Threat of service unbundling fragments traditional integrated platform revenues; backward integration into guide RNA synthesis capacity insulates margin pools from reagent supply concentration. For New Entrants and Emerging Players: Lead with cloud-based variant analysis middleware targeting United Kingdom and Japan research laboratories facing legacy system integration challenges. White-space concentrates in ISO 13485-certified PCR thermal cyclers for regulatory-compliant diagnostic development and base editing convergence platforms for precision medicine beyond knockouts. Go-to-market through contract development organization procurement channels bypasses incumbent captive reagent lock-in. For Investors and Strategic Acquirers: Specialized enzymatic reagent developers with prime editing IP portfolios represent priority acquisition targets given agricultural biotechnology adoption velocity. Long-term viability hinges on regulatory pathway clarity for gene-edited therapeutic outputs across FDA, EMA, and NMPA jurisdictions. Signal to watch: EPA plant-incorporated protectant exemption expansion accelerating seed developer capital deployment into targeted mutagenesis infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Unlocks diagnostic device market eligibility for PCR thermal cycler manufacturers competing against sequencing instrument incumbents. |
| Prime Editing Platform Integration | Enables all 12 point mutation types for agricultural biotechnology firms compressing homology-directed repair addressable markets. |
| Cloud-Based Variant Analysis Development | Resolves middleware integration challenges facing United Kingdom and Japan research laboratories with legacy LIM systems. |
| Guide RNA Synthesis Capacity Expansion | Reduces procurement bottlenecks from captive reagent supply chains controlled by dominant sequencing platform vendors. |
| Contract Development Organization Partnership | Captures pharmaceutical discovery pipeline unbundling trend through à la carte component sourcing negotiations in United States biotech clusters. |
Research Methodology
Desk research of FDA gene-editing therapeutic filings, EMA Advanced Therapy Medicinal Products submissions, and NMPA technical guideline precedents preceded structured interviews with pharmaceutical discovery executives, agricultural biotechnology R&D directors, contract research organization procurement leads, and ISO certification auditors. Secondary validation drew from patent landscaping databases, CRISPR intellectual property licensing records, and sequencing instrument deployment disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across technology and application segments.
Variance decomposition across the projection horizon isolates pricing, volume, and mix effects within hardware, reagent, and software layers. Segmentation dimensions encompass product type, application end-use, end user procurement authority, and technology platform maturity. CAGRs derive from fitted growth curves calibrated to CRISPR platform upgrade cycles and regulatory pathway clarity timelines. Forecast inputs include prime editing adoption velocity among seed developers and biosecurity export control stringency indices.
The analysis sits within stated boundaries; outcomes outside sustained EMA and FDA regulatory framework stability or germline editing moratoria relaxation would require recalibration. Forecasts reflect assumptions regarding CRISPR intellectual property licensing overhead persistence and sequencing commoditization trajectories. Revision becomes warranted when EPA plant-incorporated protectant exemption scope or NMPA gene-therapy guideline evolution crosses thresholds altering agricultural biotechnology capital deployment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Difficult-To-Express Proteins Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
DNA Synthesizer Market