
 Global Photobiostimulation Devices Market | 2026-2036
Global Photobiostimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photobiostimulation Devices Market Foresight
Clinical-grade specification tiers is bifurcating the competitive landscape between professional rehabilitation settings and at-home wellness segments. THOR Photomedicine Ltd sustains its position through intensive R&D investment in superpulsed laser architectures. Erchonia Corporation differentiates via specialized FDA-cleared applications in pain management and nerve regeneration. BIOFLEX occupies a distinct niche with flexible light delivery systems designed for physiotherapy clinic workflows.
Photobiostimulation devices employ monochromatic or narrow-band light energy, typically in the red to near-infrared spectrum, to trigger photochemical reactions in cellular mitochondria without thermal tissue damage. These systems operate at wavelengths between 600 nm and 1000 nm with power densities below 100 mW/cm², serving primarily to accelerate tissue repair, reduce inflammation, and modulate cellular metabolism across medical and aesthetic applications. LED phototherapy devices command expanding share in dermatology treatment due to lower capital requirements and reduced operator training burdens compared with laser-based alternatives. Pulsed wave technology leads musculoskeletal therapy applications where temporal modulation of light delivery enhances penetration depth in dense tissue structures. Combination devices integrating multiple wavelengths represent the fastest-growing configuration as clinicians seek versatile platforms serving pain management, wound healing, and dermatology treatment from a single capital purchase.
FDA 510(k) clearance requirements govern device commercialization in the United States while the EU Medical Device Regulation imposes stricter clinical evidence standards for phototherapy systems entering European markets. Japan's PMDA maintains distinct approval pathways that favor devices with demonstrated efficacy in nerve regeneration applications, creating asymmetric market access conditions across major economies. Stakeholders must monitor evolving reimbursement codes for photobiostimulation in sports medicine facilities and rehabilitation centers, as coverage decisions will determine addressable market expansion more directly than incremental wavelength innovations.
Market Dynamics
Superpulsed laser architectures are bifurcating the competitive landscape between professional rehabilitation settings and at-home wellness segments, forcing manufacturers to choose between clinical-grade specifications and consumer accessibility.
Growth Catalysts
- FDA 510(k) clearance pathways:The FDA's evolving clearance frameworks for low-level laser therapy devices are compressing product development timelines and accelerating commercialization for photobiostimulation systems targeting pain management applications.
- Dermatology center expansion:Dermatology centers across the United States, Germany, and Japan are expanding adoption of LED-based systems for non-invasive skin rejuvenation, driven by patient demand for outpatient aesthetic procedures.
- Reimbursement framework maturation:Reimbursement codes for phototherapy in sports medicine facilities and rehabilitation centers are maturing fastest in Japan, Germany, and the United States, expanding addressable market access for clinical-grade devices.
Market Restraints
- EU MDR clinical evidence standards:The EU Medical Device Regulation imposes stricter clinical evidence requirements for phototherapy systems entering European markets, creating regulatory friction and extending approval timelines compared with FDA pathways.
- LED versus laser capital cost differential:LED phototherapy devices command expanding share due to lower capital requirements, compressing margins for laser-based system manufacturers and constraining R&D reinvestment capacity.
- Substitution by pharmacological pain management:Opioid-sparing protocols and topical analgesics present substitution threats in musculoskeletal therapy applications, particularly where insurance coverage favors pharmaceutical interventions over device-based treatments.
Strategic Opportunities
- Japan's nerve regeneration preference:Japan's PMDA maintains distinct approval pathways favoring devices with demonstrated efficacy in nerve regeneration applications, creating asymmetric market access conditions for specialized photobiostimulation systems.
- Combination wavelength platforms:Devices integrating multiple wavelengths represent white space as clinicians seek versatile platforms serving pain management, wound healing, and dermatology treatment from single capital purchases.
- At-home wellness channel expansion:Direct-to-consumer distribution models for consumer-grade photobiostimulation devices are penetrating the wellness segment, bypassing traditional clinical procurement channels and capturing out-of-pocket spending.
Industry Challenges
- Operator training standardization:Reduced operator training burdens for LED devices versus laser-based alternatives are creating skill gaps in clinical settings, complicating workforce deployment across dermatology and physiotherapy workflows.
- Wavelength-specific certification timelines:FDA 510(k) clearance requirements for each wavelength configuration extend certification timelines, forcing manufacturers to prioritize development roadmaps and delaying multi-wavelength platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photobiostimulation Devices Market |
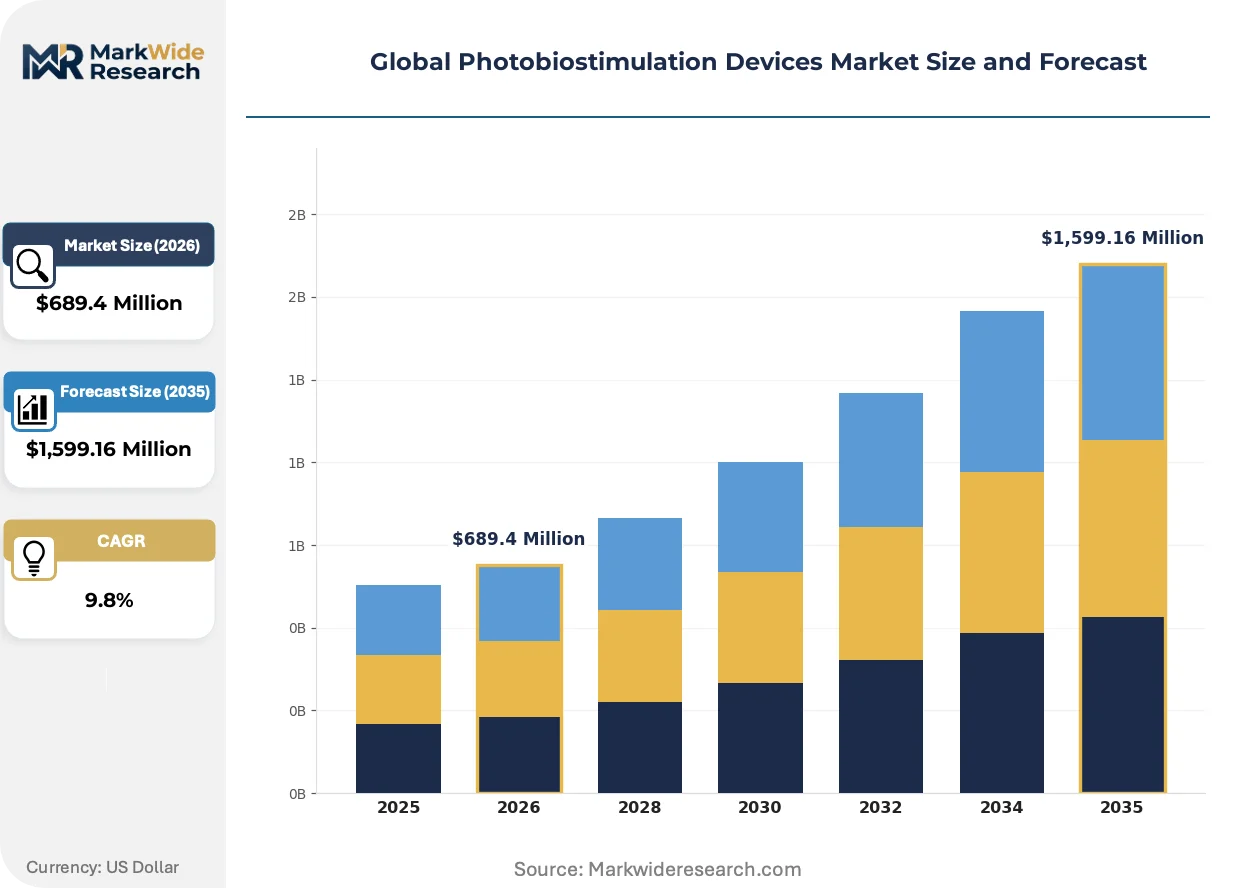
| Market Size in 2026 | $689.4 Million |
| Market Size in 2035 | $1,599.16 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Level Laser Therapy Devices, LED Phototherapy Devices, Infrared Light Therapy Devices, Combination Devices Technology: Continuous Wave, Pulsed Wave, Diode Laser, Superpulsed Laser, Solid-State Laser Application: Pain Management, Wound Healing, Dermatology Treatment, Musculoskeletal Therapy, Nerve Regeneration End User: Physiotherapy Clinics, Dermatology Centers, Sports Medicine Facilities, Rehabilitation Centers, Research Institutions |
| Companies Covered | THOR Photomedicine Ltd, Theralase Technologies, Erchonia Corporation, iRestore Laser, BTL Industries, Vielight Inc, BIOFLEX, Omega Laser Systems, BioLight Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photobiostimulation Devices Market Shifts & Advancements
Pulsed wave technology architectures are actively reshaping competitive positioning in musculoskeletal therapy, while regulatory divergence between FDA, EU MDR, and PMDA pathways is fragmenting product development strategies across major markets.
Superpulsed laser technology is decomposing the traditional power-density tradeoff in photobiostimulation by enabling higher peak intensities without thermal tissue damage. Sports medicine facilities and professional rehabilitation centers are adopting these systems at accelerating pace for deep tissue penetration in dense musculoskeletal structures. This technology is compressing the performance gap between clinical-grade lasers and high-power LED arrays, forcing manufacturers to differentiate on temporal modulation precision rather than raw optical output.
EU MDR clinical evidence standards are tightening post-market surveillance requirements for phototherapy systems entering European markets. The regulation mandates extended clinical follow-up data and strengthened notified body oversight, extending approval timelines by twelve to eighteen months for manufacturers previously certified under the Medical Device Directive. Combination devices integrating multiple wavelengths face disproportionate scrutiny, prompting developers to sequence regulatory submissions by single-wavelength configurations.
Certification-driven procurement preferences are rotating demand toward FDA-cleared devices in United States sports medicine facilities, displacing non-cleared wellness-grade systems previously purchased for off-label clinical use. Hospital procurement committees are tightening vendor qualification criteria, requiring 510(k) documentation for capital purchases above institutional thresholds. This behavioral shift concentrates demand among established manufacturers with extensive clearance portfolios, compressing market access for emerging competitors in the professional rehabilitation segment.
Global Photobiostimulation Devices Market Segmentation
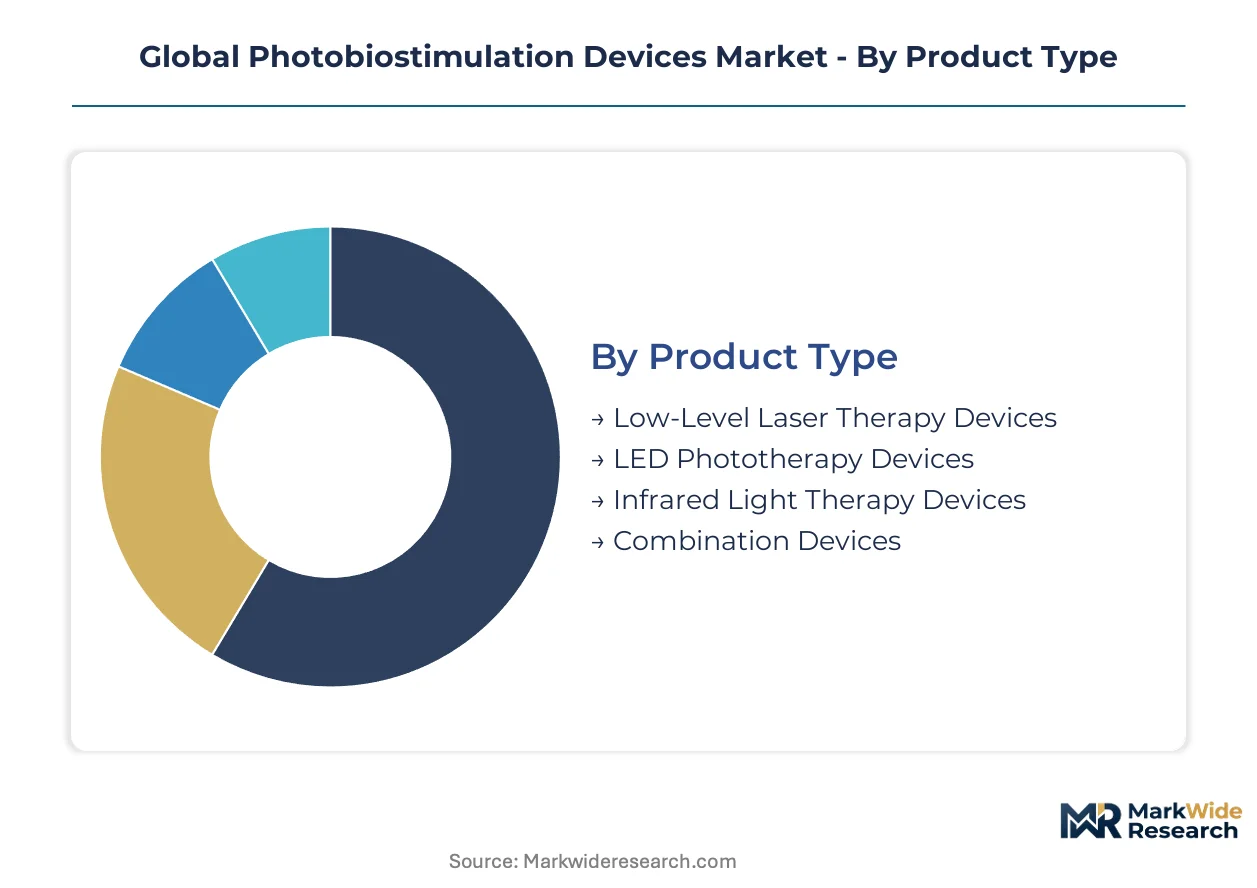
Photobiostimulation device manufacturers configure product portfolios around distinct procurement channels, with hospital procurement committees, direct-to-consumer platforms, and specialist clinic networks each favoring different specification tiers. Channel-specific demand patterns determine wavelength configurations, power densities, and regulatory certification strategies across the competitive landscape.
Product Type:
Distribution channels fragment sharply across product categories, with professional rehabilitation settings favoring laser-based systems while wellness platforms drive LED volume.
- Low-Level Laser Therapy Devices:These systems deliver coherent monochromatic light at precise wavelengths between 600 nm and 1000 nm with power densities calibrated for clinical tissue penetration. Demand concentrates in United States sports medicine facilities and German physiotherapy clinics where FDA 510(k) clearance and EU MDR certification govern procurement eligibility. Reimbursement code maturation in these geographies accelerates capital replacement cycles.
- LED Phototherapy Devices:Non-coherent narrow-band arrays operate at lower capital cost with reduced operator training requirements, expanding adoption in dermatology centers across Japan and outpatient aesthetic clinics. The technology's accessibility profile aligns with direct-to-consumer channel growth and wellness segment penetration.
- Infrared Light Therapy Devices:Systems emphasizing 800 nm to 1000 nm wavelengths target deep tissue applications in dense musculoskeletal structures.
- Combination Devices:Multi-wavelength platforms integrate red, near-infrared, and sometimes blue outputs for versatile clinical deployment from single capital purchases.
By volume, LED Phototherapy Devices leads. By growth pace, Combination Devices is climbing the fastest.
Technology:
Cost tiers separate technology selections, with premium superpulsed architectures commanding clinical-grade pricing and continuous wave systems dominating economy segments.
- Continuous Wave:Steady-state light delivery at fixed power densities serves baseline therapeutic applications with minimal temporal complexity. The architecture dominates entry-level device manufacturing and at-home wellness products where cost minimization outweighs penetration depth requirements.
- Pulsed Wave:Temporal modulation of light delivery enhances photon penetration in dense tissue structures without thermal accumulation, concentrating demand in musculoskeletal therapy applications across professional rehabilitation centers in the United States and Germany.
- Diode Laser:Semiconductor-based coherent sources offer compact form factors and wavelength precision for portable clinical devices.
- Superpulsed Laser:Peak intensity architectures enable higher instantaneous power without tissue heating, commanding premium positioning in deep-treatment protocols.
- Solid-State Laser:Crystal or glass host laser media deliver wavelength stability for research-grade and specialized nerve regeneration applications.
By installed base, Continuous Wave dominates. By revenue expansion, Superpulsed Laser is gaining share fastest.
Application:
Customer type determines application prioritization, with hospital systems emphasizing wound healing protocols and private aesthetic chains concentrating dermatology investment.
- Pain Management:Photobiostimulation for musculoskeletal and neuropathic pain reduction represents the most mature reimbursement category in United States sports medicine facilities. FDA 510(k) clearance pathways for pain indications are compressing commercialization timelines for device manufacturers targeting this segment.
- Wound Healing:Chronic wound protocols in rehabilitation centers and long-term care facilities drive demand for red-spectrum devices targeting cellular metabolism acceleration. German and Japanese clinical guidelines increasingly incorporate phototherapy into standard wound care pathways.
- Dermatology Treatment:Aesthetic applications including skin rejuvenation and acne management concentrate in outpatient clinics and medspa channels across Japan and the United States.
- Musculoskeletal Therapy:Deep tissue applications favor pulsed and superpulsed architectures for professional athletic and orthopedic rehabilitation settings.
- Nerve Regeneration:Peripheral nerve repair applications command specialized regulatory attention from Japan's PMDA, creating asymmetric market access conditions.
By procedure volume, Pain Management leads. By regulatory priority, Nerve Regeneration is expanding most quickly.
End User:
Geographic concentration shapes end user procurement patterns, with United States hospital networks, German outpatient chains, and Japanese specialist clinics each driving distinct specification requirements.
- Physiotherapy Clinics:Independent and chain-affiliated rehabilitation practices across Germany and the United States represent the core installed base for laser-based musculoskeletal systems. These facilities prioritize FDA-cleared and CE-marked devices with established reimbursement codes.
- Dermatology Centers:Aesthetic medicine practices and hospital-affiliated dermatology departments in Japan and the United States are expanding LED system adoption for non-invasive skin rejuvenation protocols with minimal downtime requirements.
- Sports Medicine Facilities:Professional athletic training centers and orthopedic practices concentrate demand for high-performance pulsed laser systems.
- Rehabilitation Centers:Post-acute and long-term care settings favor versatile combination devices serving multiple patient populations.
- Research Institutions:Academic medical centers and contract research organizations drive demand for wavelength-tunable and solid-state systems for clinical trial applications.
By device count, Physiotherapy Clinics leads. By investment intensity per site, Sports Medicine Facilities is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across major markets, with Japanese clinics absorbing premium superpulsed systems while German outpatient practices prioritize capital-efficient LED platforms. Reimbursement density and regulatory pathway efficiency determine where manufacturers can command margin versus competing on cost.
United States
Sports medicine facilities in Texas and Florida are accelerating procurement of FDA 510(k)-cleared laser systems for musculoskeletal therapy. The FDA's compressed clearance timelines for pain management indications are shortening commercialization cycles for device developers. Hospital procurement committees in the Northeast Corridor are tightening vendor qualification standards, displacing non-cleared wellness-grade systems from clinical settings.
Germany
Physiotherapy clinic chains across North Rhine-Westphalia favor LED phototherapy devices for their reduced operator training burdens and lower capital requirements. The EU Medical Device Regulation imposes stricter clinical evidence standards than FDA pathways, extending approval timelines for laser-based systems entering European markets. Munich and Stuttgart host specialized rehabilitation centers adopting combination wavelength platforms for versatile patient protocols.
Japan
Dermatology centers in Tokyo and Osaka are expanding LED system adoption for non-invasive skin rejuvenation with minimal downtime protocols. The PMDA maintains distinct approval pathways favoring devices with demonstrated efficacy in nerve regeneration applications, creating asymmetric market access conditions. Kansai region clinics concentrate demand for peripheral nerve repair phototherapy systems.
United Kingdom
Private aesthetic chains in London and the Southeast are driving LED phototherapy volume for outpatient cosmetic procedures. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR evidence requirements post-Brexit, maintaining stringent clinical data standards for device market entry. Manchester and Birmingham rehabilitation networks are piloting pulsed wave systems for musculoskeletal therapy protocols.
Australia
Sports medicine facilities in New South Wales and Victoria are adopting superpulsed laser architectures for deep tissue penetration in athletic rehabilitation. The Therapeutic Goods Administration requires conformity assessment procedures that parallel EU MDR stringency, filtering market access for lower-evidence devices. Melbourne academic medical centers drive demand for wavelength-tunable systems in clinical trial applications.
Global Photobiostimulation Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the photobiostimulation device market. The competitive structure bifurcates between premium-tier manufacturers with extensive regulatory clearance portfolios and volume-oriented suppliers serving wellness and direct-to-consumer channels. Three archetypes dominate: superpulsed laser specialists with deep R&D pipelines, flexible LED platform developers optimizing for clinic workflow efficiency, and combination device integrators pursuing single-purchase versatility. Dominant competitive moves include strategic partnerships with rehabilitation clinic networks and portfolio diversification across wavelength configurations to capture multi-segment demand.
Within the superpulsed laser specialist tier, THOR Photomedicine Ltd and Erchonia Corporation exemplify archetypes differentiated by regulatory positioning and application focus. Among North American developers, BIOFLEX occupies a position emphasizing flexible light delivery architectures designed for physiotherapy clinic integration. These three companies anchor distinct strategic vectors—intensive R&D investment, specialized FDA-cleared indications, and workflow-optimized system design—that define competitive positioning in professional rehabilitation settings.
| Leading Market Players |
|---|
| THOR Photomedicine Ltd |
| Theralase Technologies |
| Erchonia Corporation |
| iRestore Laser |
| BTL Industries |
| Vielight Inc |
| BIOFLEX |
| Omega Laser Systems |
| BioLight Technologies LLC |
| Others |
Supply & Pricing Matrix
Long-term service contracts with rehabilitation clinic networks lock in supply access and price visibility for manufacturers of FDA-cleared laser systems. These arrangements stabilize revenue streams while insulating vendors from spot-market volatility in LED component sourcing.
Pricing Analysis
FDA 510(k) clearance dictates the pricing tier structure across professional rehabilitation settings. Premium-mid-economy pricing differentiation separates superpulsed laser systems from continuous-wave LED arrays, with certification grade and after-sales service bundling as primary drivers. Cost compression in the LED segment is intensifying because Asian manufacturers are scaling wafer production. Direct-to-consumer wellness buyers exhibit highest price sensitivity, while United States hospital procurement committees prioritize clearance documentation over unit cost.
Supply Chain Analysis
Gallium arsenide wafer fabrication capacity in Taiwan underwrites semiconductor laser diode availability for medical-grade photobiostimulation systems. Component sourcing draws from Japan for precision optics, Germany for solid-state laser crystals, and China for LED array substrates. Single-source vulnerability concentrates in Taiwan's foundry ecosystem. Distribution runs through specialized medical device distributors serving physiotherapy clinics and hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photobiostimulation device economics increasingly hinge on recurring revenue from disposable light delivery pads and software subscription tiers for treatment protocol updates, both expanding faster than hardware unit sales.
For Market Incumbents: Shield installed base relationships by embedding workflow software that raises switching costs for physiotherapy clinics. Deepen upstream control over gallium arsenide wafer supply through captive sourcing agreements with Taiwanese foundries. Counter LED-based substitution threats by bundling training certification into superpulsed system purchases. For New Entrants and Emerging Players: Differentiate on nerve regeneration efficacy data to access Japan's PMDA-favored approval pathway. Target Germany's outpatient physiotherapy chains with capital-efficient LED platforms that minimize operator training burdens. Pursue direct-to-consumer wellness channel entry via influencer partnerships and subscription-based device rental models. For Investors and Strategic Acquirers: Capital is best deployed toward combination-device developers with multi-wavelength clearance pipelines spanning pain management and dermatology applications. Long-term viability favors platforms capable of serving both clinical reimbursement channels and out-of-pocket wellness spending. Watch FDA 510(k) clearance velocity for multi-wavelength submissions as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Unlocks Medicare reimbursement eligibility for pain management indications in United States sports medicine facilities. |
| EU MDR Certification Pathway | Extends market access to German physiotherapy chains under strengthened clinical evidence requirements. |
| Hospital System Partnership | Secures preferred vendor status with Northeast Corridor procurement committees tightening qualification standards. |
| Software Companion Development | Enables recurring revenue from treatment protocol subscriptions and remote patient monitoring dashboards. |
| Reimbursement Strategy | Aligns product positioning with maturing CPT codes for phototherapy in Japanese rehabilitation centers. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and physiotherapy clinic operators converged on the working assumptions underlying market sizing. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body filings, and Japanese PMDA approval records. Bottom-up triangulation across device shipment data and top-down reconciliation against reimbursement claims informed volume estimates.
Segmentation dimensions modeled span product type, technology architecture, application indication, and end-user channel across the projection horizon. CAGRs derive from weighted scenario analysis incorporating regulatory approval timelines and reimbursement code expansion trajectories. Wavelength-specific certification velocity and superpulsed laser adoption curves in sports medicine facilities served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance momentum and EU MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding reimbursement maturation and component cost trajectories. Practitioners should keep alternative scenarios live as PMDA pathway efficiency and LED-laser substitution dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Cell Proliferation Kit Market