
 Europe Beverage Market | 2026-2036
Europe Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beverage Market Insights
Spain's non-alcoholic beverage production expansion is reshaping southern European supply chains. Diageo PLC leverages its gin and premium spirits portfolio to dominate the United Kingdom's premiumization wave. Heineken Holding NV anchors its position through zero-alcohol brewing investments across the Netherlands and beyond. Nestlé S.A. competes aggressively in ready-to-drink coffee through Nescafé product lines.
Europe Beverage encompasses potable liquid formulations spanning carbonated soft drinks, fermented alcoholic brews, fruit-derived juices, and caffeine-infused energy products, typically manufactured through blending, fermentation, pasteurization, or carbonation processes to deliver hydration, stimulation, or refreshment. Soft Drinks and Beer represent mature volume pillars where margin pools concentrate in premium and craft sub-tiers. Energy Drinks sustain the fastest structural growth trajectory, driven by convenience channel expansion and on-the-go consumption patterns among younger demographics.
EMA food-contact material guidelines, the EU Green Deal packaging directives, and national excise frameworks across France and Germany shape product composition, recyclability mandates, and market access thresholds for new entrants. EFSA health claim assessments determine whether functional beverage positioning reaches retail shelves. Stakeholders must monitor how the EU AI Act and evolving digital labeling requirements will reshape consumer transparency obligations and competitive differentiation strategies.
Market Dynamics
The EU Green Deal packaging directives are forcing PET-to-rPET transitions across European beverage manufacturing, compressing margins while mandating circular supply chain investments that reshape competitive positioning.
Growth Catalysts
- Urban Millennial Demand:Premium ready-to-drink coffee adoption accelerates in metropolitan corridors, pulling functional beverage innovation toward convenience formats.
- EMA Food-Contact Guidelines:Harmonized safety standards streamline cross-border formulation approvals, reducing regulatory fragmentation for pan-European brands.
- Netherlands Zero-Alcohol Brewing:Heineken's capacity investments anchor a regional hub for non-alcoholic beer exports across northern Europe.
Market Restraints
- rPET Supply Concentration:Food-grade recycled polymer availability clusters with German and French chemical processors, creating bottle-grade material scarcity.
- Excise Framework Variability:France and Germany maintain divergent alcohol taxation structures, complicating unified pricing strategies.
- Sugar Substitution Technical Limits:EFSA health claim assessments reject numerous natural sweetener positioning requests, constraining reformulation pathways.
Strategic Opportunities
- Spain Production Expansion:Southern European supply chain reconfiguration creates export capacity for Mediterranean distribution.
- EU AI Act Digital Labeling:Smart packaging transparency mandates open competitive differentiation through blockchain traceability investments.
- Energy Drink Channel Innovation:Vending and convenience store penetration in eastern European markets remains underdeveloped relative to western benchmarks.
Industry Challenges
- Legacy System Integration:ERP migration to circular inventory tracking platforms strains mid-tier manufacturers with dated infrastructure.
- Food-Contact Certification Timelines:EFSA novel food assessments extend 18-24 months, delaying functional ingredient launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beverage Market |
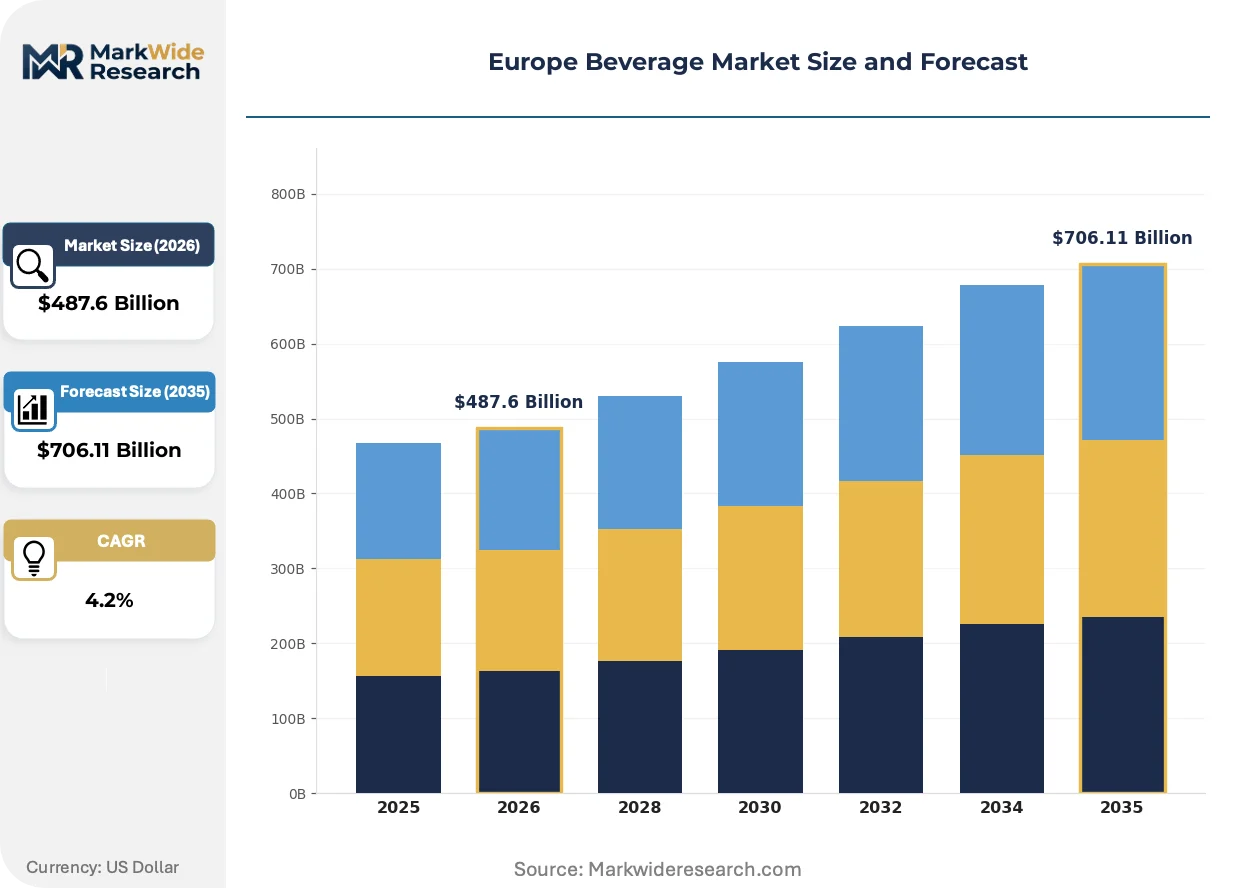
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $706.11 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juices, Beer, Energy Drinks Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Bars Package Type: Bottles, Cans, Tetra Packs, Kegs End User: Households, HoReCa, Offices, Events |
| Companies Covered | Diageo PLC, Anheuser-Busch InBev, Heineken Holding NV, Pernod Ricard, Carlsberg Breweries A/S, Bacardi Limited, Nestlé S.A., Danone S.A., Asahi Group Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beverage Market Trends and Innovations
Active packaging technologies and regulatory transparency mandates are compressing product development cycles while enabling premium positioning through verified sustainability claims.
Smart bottle technologies incorporating NFC-enabled consumer engagement are migrating from pilot programs to mainstream deployment. Premium spirits producers in the United Kingdom adopt connected packaging for authentication and cocktail recipe delivery. This migration from passive to interactive packaging is compressing traditional label-based marketing budgets while capturing first-party consumption data.
The EU Green Deal's Extended Producer Responsibility frameworks now mandate financial participation in post-consumer collection infrastructure. Beverage manufacturers face capital allocation decisions between compliance fees and direct recycling system investments. Germany's DSD dual system operators are absorbing operational complexity that smaller entrants cannot replicate internally.
Urban convenience consumption patterns favor chilled single-serve formats over traditional multi-pack retail. Younger demographics in France and the Netherlands purchase beverages through foodservice channels and automated retail at rates exceeding supermarket visitation. This channel rotation pressures legacy wholesale distribution relationships while rewarding direct-store-delivery investments in metropolitan clusters.
Europe Beverage Market Segmentation
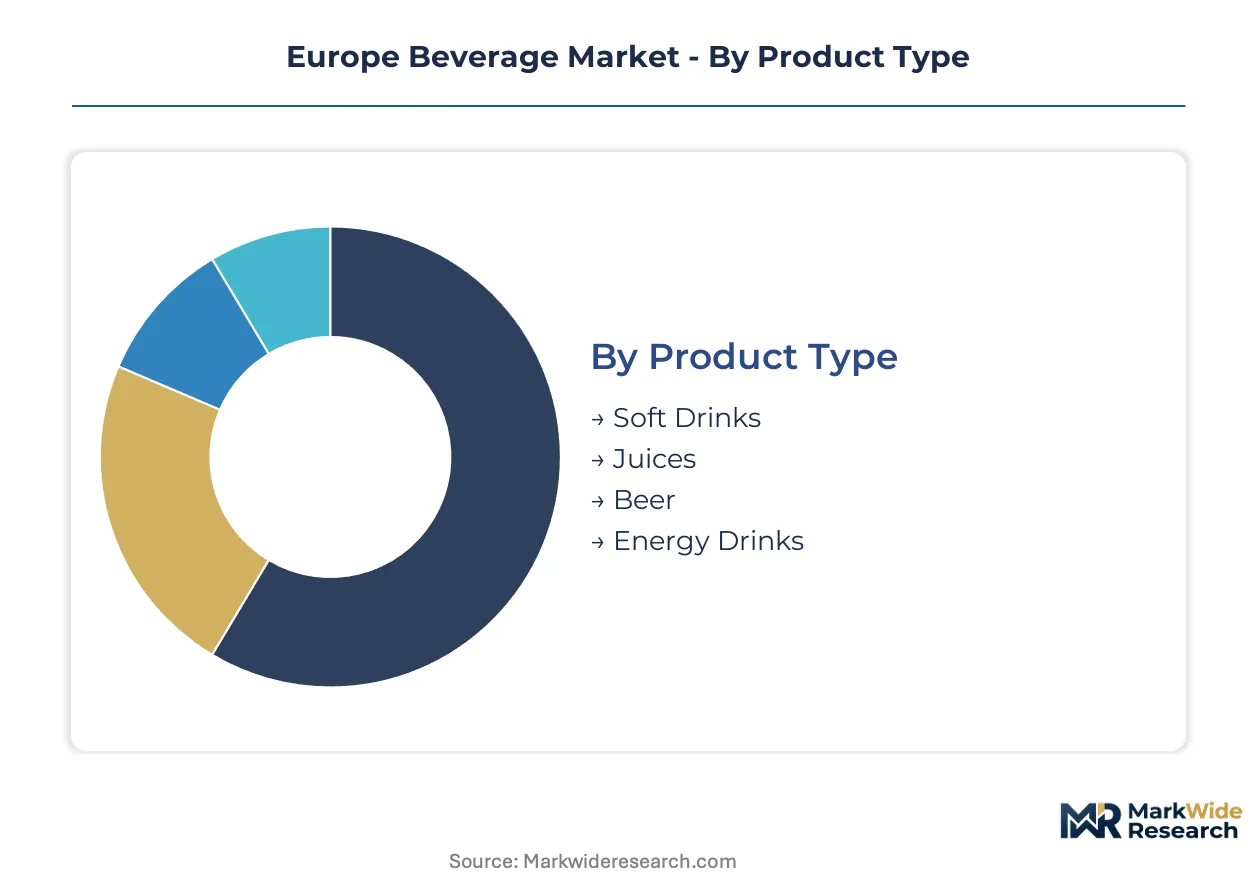
Segmentation in the Europe Beverage Market reveals divergent margin structures and inventory velocities across product formats and channel configurations. Understanding these stratifications enables targeted capital deployment toward premiumization opportunities and operational efficiency gains.
Product Type:
Cycle times vary dramatically across beverage categories, with perishable formats demanding rapid turnover while shelf-stable alternatives support extended distribution windows.
- Soft Drinks:Carbonated formulations with high-frequency replenishment cycles dominate volume throughput in continental retail networks. German supermarket chains push 7-10 day inventory turns, compressing working capital requirements for bottlers while squeezing margin recovery.
- Beer:Fermented malt beverages span mass-market lagers through craft ales with divergent temperature-controlled logistics needs. Heineken's Netherlands zero-alcohol brewing investments signal category pivot toward stable, non-perishable alternatives with lower excise burdens.
- Juices:Pasteurized fruit extracts with shorter shelf lives constrain geographic reach without aseptic processing investments.
- Energy Drinks:Caffeine-functional formulations targeting on-the-go urban consumption patterns in France and Netherlands metropolitan corridors.
Soft Drinks anchors the volume base while Energy Drinks gains share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply between high-touch foodservice operations and automated retail formats with divergent labor and real estate cost structures.
- Supermarkets:Full-format retail with extensive SKU breadth and promotional intensity driving price transparency. French hypermarket operators leverage beverage categories as traffic builders, accepting compressed category margins for basket expansion.
- Convenience Stores:Small-footprint urban outlets prioritizing chilled single-serve formats with premium price realization. Younger demographics in Netherlands cities purchase through convenience channels at rates exceeding supermarket visitation, rewarding direct-store-delivery infrastructure.
- Online Retailers:Digital-native fulfillment with heavy/bulky logistics constraints limiting penetration for glass-bottle formats.
- Bars:On-premise consumption with draught systems and mixology-driven premium spirits attachment.
Supermarkets maintain the volume foundation while Convenience Stores expands most quickly in urban catchments.
Package Type:
Material selection carries regulatory weight under EU Green Deal mandates, with recycled content thresholds reshaping procurement economics across format categories.
- Bottles:PET and rPET containers facing mandatory recycled content minimums with supply concentration among German and French chemical processors. EFSA food-contact assessments govern migration limits for recycled polymer integration.
- Cans:Aluminum formats with infinite recyclability and lighter transport economics favoring export-oriented production from Spain's expanding southern European supply base.
- Tetra Packs:Aseptic carton systems enabling ambient distribution for juices and dairy alternatives with complex multi-material recycling challenges.
- Kegs:Returnable stainless steel systems for on-premise beer distribution with high capital intensity and reverse logistics requirements.
Bottles retains the dominant volume position while Cans climbs the fastest on sustainability credentials and logistics efficiency.
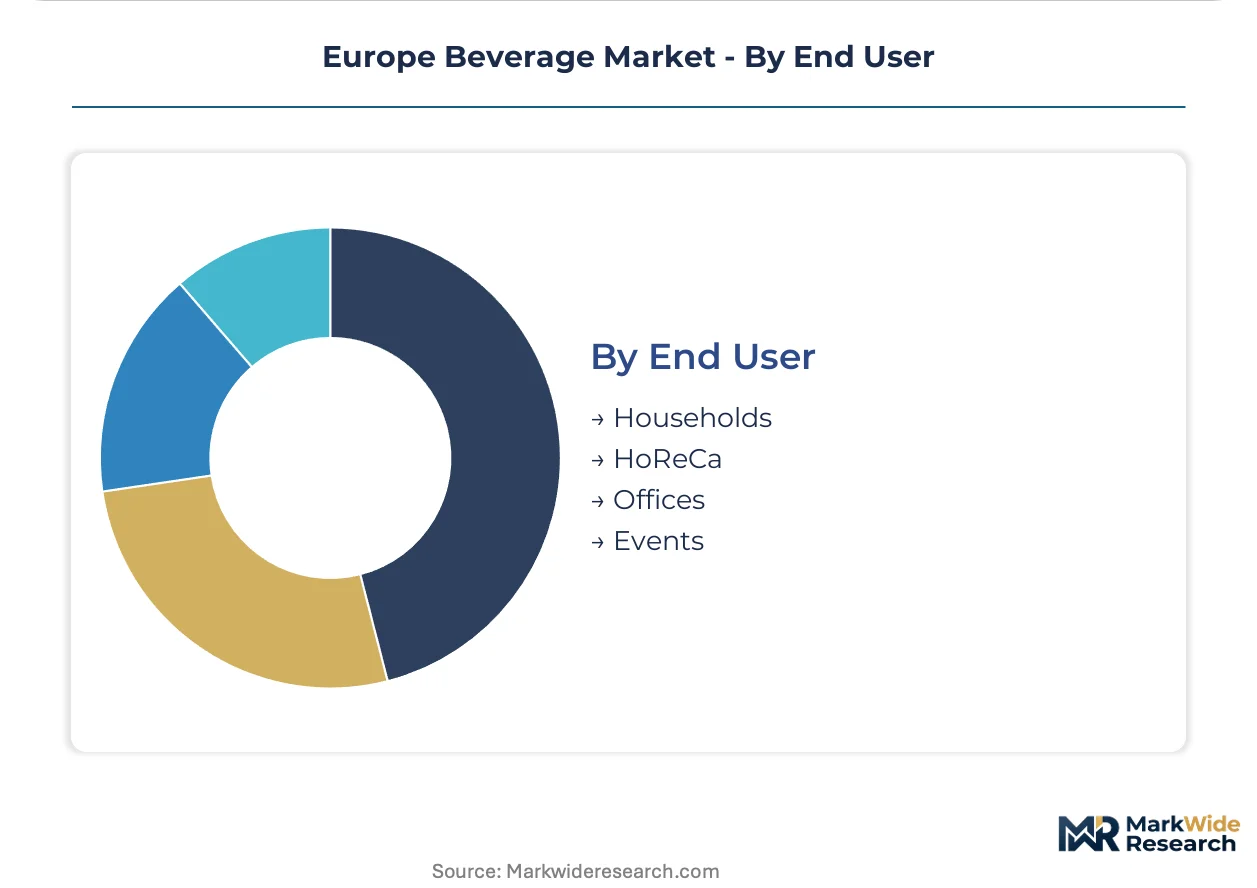
End User:
Demand concentration patterns diverge between institutional procurement with contract pricing discipline and fragmented household purchasing with brand loyalty volatility.
- Households:Individual consumers purchasing through retail channels with private-label penetration varying by market maturity. German households demonstrate higher willingness-to-pay for functional beverage premiums than southern European counterparts.
- HoReCa:Hotels, restaurants, and cafes with beverage-as-experience positioning and supplier consolidation toward integrated national distributors. Diageo's United Kingdom gin portfolio targets premium spirits placement in upscale London venues.
- Offices:Corporate refreshment services with vending and micro-market formats emphasizing convenience and contactless payment integration.
- Events:Temporary consumption occasions with mobile dispensing infrastructure and regulatory compliance for outdoor alcohol service permits.
Households anchors the volume base while HoReCa gains share at the steepest rate on experience-premium recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturing clusters concentrate in northwestern Europe, with rPET processing capacity clustering around German chemical processors and Dutch brewing infrastructure anchoring non-alcoholic export hubs. Southern European production expansion in Spain is reshaping Mediterranean distribution networks.
Germany
Functional beverage demand concentrates in metropolitan corridors, with urban millennials driving premium ready-to-drink coffee adoption. The country's national packaging regulator enforces EU Green Deal Extended Producer Responsibility frameworks through DSD dual system operators. Bavaria's brewing belt and North Rhine-Westphalia's chemical processing zones anchor rPET supply chains for food-grade recycled polymer integration.
United Kingdom
Premium spirits consumption accelerates in London's upscale venues, with gin portfolio positioning capturing experience-premium recovery. EFSA health claim assessments govern functional beverage reformulation pathways reaching retail shelves. Scotland's distilling clusters and England's southeast brewing belt concentrate craft and mass-market production capacity.
France
Hypermarket beverage categories function as traffic builders, accepting compressed margins for basket expansion across French retail networks. Divergent alcohol excise frameworks complicate unified pricing strategies with neighboring markets. The Île-de-France region and Provence-Alpes-Côte d'Azur corridor concentrate urban convenience consumption and foodservice channel penetration.
Netherlands
Zero-alcohol brewing investments anchor a regional hub for non-alcoholic beer exports across northern European markets. Younger demographics purchase through convenience channels and automated retail at rates exceeding supermarket visitation. The Randstad metropolitan cluster drives direct-store-delivery infrastructure deployment for chilled single-serve formats.
Spain
Southern European supply chain reconfiguration creates export capacity for Mediterranean distribution networks. EMA food-contact material guidelines streamline cross-border formulation approvals for pan-European brands. Catalonia and Andalusia beverage production zones expand aluminum can manufacturing for ambient distribution efficiency.
Europe Beverage Market Competitive Landscape
Multinational brewers and diversified beverage conglomerates split the market between alcohol-focused portfolios and functional non-alcoholic formats. Consolidation pressures concentrate volume leadership among scale-driven operators with integrated distribution networks. Three archetypes dominate: legacy brewing conglomerates with zero-alcohol pivots, spirits specialists targeting premiumization waves, and diversified nutrition giants competing in ready-to-drink coffee. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves reshaping positioning.
Within the legacy brewing tier, Heineken Holding NV and Anheuser-Busch InBev occupy positions as scale-driven operators with Netherlands and Belgium origins respectively. Carlsberg Breweries A/S represents the Scandinavian archetype with Danish corporate structure. Among spirits specialists, Diageo PLC exemplifies the United Kingdom-based premium positioning strategy. Nestlé S.A. and Danone S.A. sit within the diversified nutrition tier, with Swiss and French corporate structures anchoring their ready-to-drink and functional beverage portfolios.
| Leading Market Players |
|---|
| Diageo PLC |
| Anheuser-Busch InBev |
| Heineken Holding NV |
| Pernod Ricard |
| Carlsberg Breweries A/S |
| Bacardi Limited |
| Nestlé S.A. |
| Danone S.A. |
| Asahi Group Holdings |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Spain's aluminum can manufacturing zones is compressing supplier pricing power while accelerating procurement shifts toward Mediterranean-sourced formats. German chemical processors maintain tight rPET utilization rates, forcing beverage brands to absorb premium feedstock costs or reformulate packaging specifications.
Pricing Analysis
The EU Green Deal packaging directives dictate the pricing tier structure across European beverage manufacturing, separating premium rPET-compliant products from standard virgin-PET alternatives and economy-grade non-recyclable formats. Price differentiation hinges on recycled-content certification thresholds and regional delivery logistics, with German households showing lowest price sensitivity for functional premiums while southern European retail channels resist pass-through. Pricing pressure stems from rPET supply scarcity concentrated among French and German polymer processors. Mass-market lager segments exhibit highest buyer price sensitivity, while premium spirits and ready-to-drink coffee categories sustain markup recovery.
Supply Chain Analysis
Upstream feedstock for European beverage packaging draws from German and French chemical processors for rPET, Spanish aluminum smelters for can sheet, and Nordic timber pulp for aseptic carton barriers. Raw material dependencies center on food-grade recycled polymer, beverage-grade aluminum coil, and barrier-coated paperboard. Single-source vulnerability clusters around German rPET purification capacity, where three processors control majority food-contact supply. Distribution runs through integrated national distributors for HoReCa channels, direct-store-delivery networks for urban convenience, and centralized wholesale for hypermarket replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European beverage markets are approaching a platform-economics inflection where digital labeling interoperability under the EU AI Act will separate integrated data-capture players from legacy label-dependent competitors.
For Market Incumbents: Insulate premium positioning through captive rPET supply agreements with German chemical processors, locking in food-grade recycled polymer access before capacity constraints harden. Accelerate ERP migration to circular inventory tracking platforms to preempt mid-tier competitors stranded with dated infrastructure. The threat of EFSA novel food assessment delays requires early-stage functional ingredient pipeline investment to maintain launch velocity. For New Entrants and Emerging Players: Eastern European convenience channel penetration represents the most penetrable entry point, with vending and automated retail density running significantly below western benchmarks. Spain's expanding southern European supply base offers co-manufacturing partnerships for aluminum can formats targeting Mediterranean export markets. A direct-store-delivery go-to-market angle bypasses entrenched wholesale relationships that block new brand placement in German and French supermarket networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diversified nutrition giants with ready-to-drink coffee subscription platforms and functional beverage loyalty programs. Long-term viability over the coming decade favors operators with integrated rPET supply chains and digital labeling compliance infrastructure already deployed. Acquisition targets should demonstrate proven EFSA health claim navigation capabilities. The signal to watch is regulatory acceleration in EU AI Act implementation timelines, which would compress competitive differentiation windows for laggards.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Supply Integration | Captive access to German food-grade recycled polymer secures compliance with EU Green Deal mandates. |
| Digital Labeling Deployment | Blockchain traceability investments differentiate premium positioning under EU AI Act transparency requirements. |
| Zero-Alcohol Capacity Expansion | Netherlands brewing infrastructure anchors non-alcoholic export hub for northern European markets. |
| Direct-Store-Delivery Buildout | Urban convenience penetration in Randstad and Île-de-France corridors captures channel rotation from supermarkets. |
| Functional Ingredient Pipeline | Early EFSA novel food submissions preempt 18-24 month assessment delays blocking competitor launches. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA health claim databases, EU regulatory filings, and national excise frameworks across France and Germany. Primary interviews engaged beverage brand managers, category buyers at French hypermarket operators, supply planners at German bottling cooperatives, and regulatory affairs leads navigating EMA food-contact guidelines. Secondary validation drew from customs trade data, DSD dual system operator reports, and SEC filings of listed beverage conglomerates. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs include modeled trajectories across product type, distribution channel, package material, and end-user segmentation dimensions over the projection horizon. CAGRs derive from volume-demand elasticity analysis against pricing power indicators and channel shift velocities. Industry-specific inputs encompass rPET supply capacity expansion schedules and EFSA novel food assessment pipeline backlogs.
Practitioners should monitor regulatory acceleration in EU AI Act digital labeling mandates and rPET supply concentration dynamics for early signals of competitive repositioning requirements. Forecasts reflect assumptions around EMA guideline harmonization timelines and Extended Producer Responsibility fee structures. Material shifts in EFSA health claim rejection rates or German chemical processor capacity utilization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
India Sports Drinks Market
Beverages
Ready to Drink Premixes Market
Beverages
Dairy Based Beverages Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Flavored Powder Drinks Market
Beverages
Caffeine Mint Market
Beverages
Probiotic Beverage Market
Beverages
Aloe Vera Juice Market
Beverages
Baby Drinks Market
Beverages
China Orange Juice Market
Beverages
Milk Tea Powder Market
Beverages
Global Soda Maker Market
Beverages
Plant Based Beverages Market
Beverages
Mixers Market
Beverages
Europe Bottled Water Processing Market
Beverages
North America Sugar Free Energy Drinks Market