
 Global Soda Maker Market | 2026-2036
Global Soda Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soda Maker Market Outlook
Stainless steel is pivoting away from ABS plastic in premium soda maker chassis as raw material costs and durability expectations shift. SodaStream Inc. leverages captive CO2 exchange infrastructure across retail partnerships to sustain recurring revenue streams. Aarke AB anchors its position through design-forward stainless steel construction that commands premium positioning in European specialty retail. Hamilton Beach Brands Holding Company competes on mass-market volume through broad supermarket distribution and accessible price points.
A soda maker is a pressurized carbonation appliance that injects food-grade CO2 into water via a regulated valve system, typically operating at pressures between 30 and 60 bar to achieve desired fizz levels. The device serves commercial and residential users seeking on-demand sparkling water production without single-use bottle logistics. Compact and countertop product types dominate unit shipments due to apartment-friendly footprints and minimal kitchen counter space requirements. Built-in configurations capture the highest margin pools as they integrate with premium kitchen cabinetry and target luxury renovation projects. Commercial-grade systems serving restaurants and catering services represent the fastest-growing end user segment as foodservice operators seek to control beverage costs and reduce supplier dependency.
FDA food-contact substance regulations and EU REACH compliance on cylinder valve materials shape product design requirements for manufacturers selling across North America and Europe. ISO 7864 standards for CO2 cylinder thread compatibility influence interoperability and consumer safety expectations in multi-brand retail environments. Stakeholders must monitor evolving extended producer responsibility frameworks in France and Germany that could mandate take-back programs for disposable CO2 canisters.
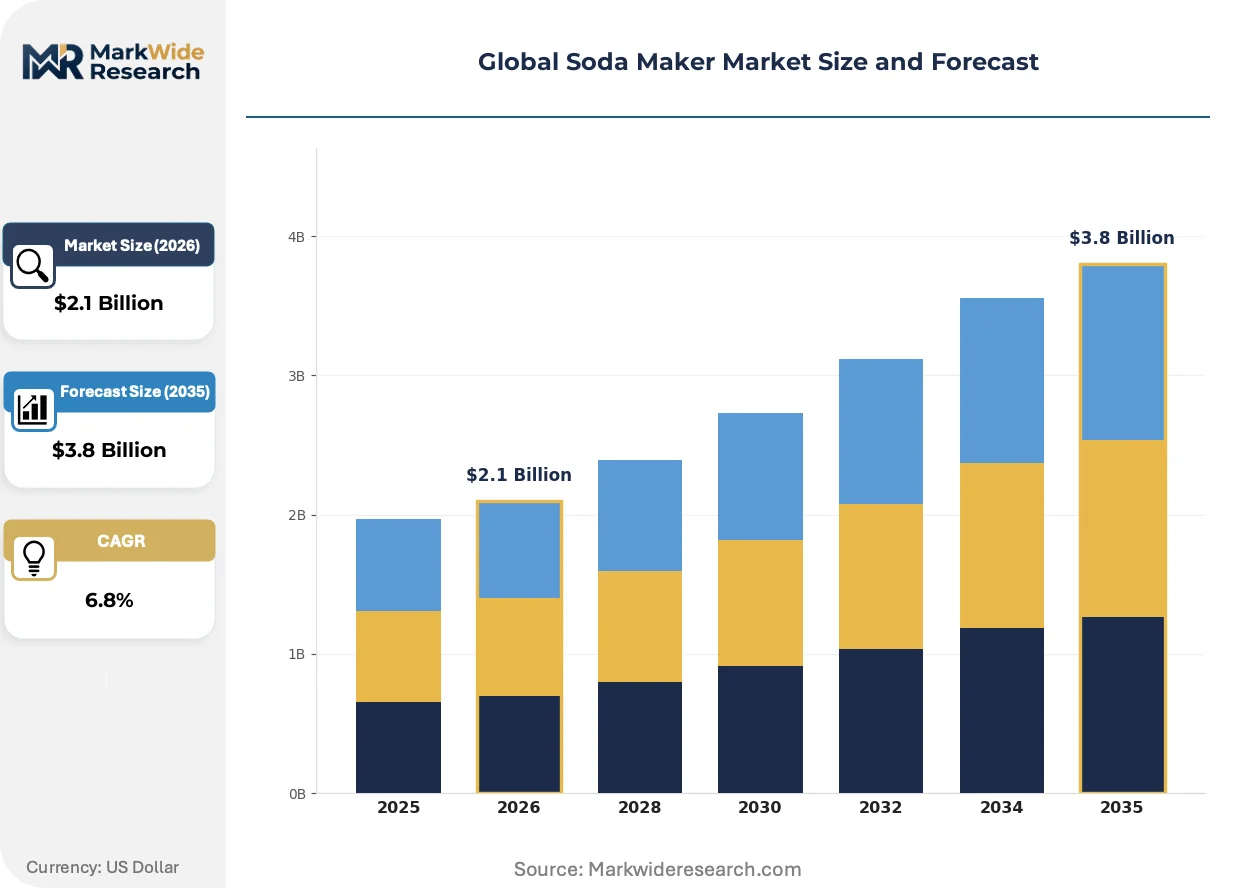
Market Dynamics
Household carbonation adoption is compressing single-use plastic demand while EU REACH compliance on food-contact materials and CO2 cylinder valve standards is forcing chassis material substitutions across manufacturing footprints.
Growth Catalysts
- Extended producer responsibility frameworks:France and Germany are advancing take-back mandates for disposable CO2 canisters, creating regulatory pull for refillable exchange infrastructure.
- Foodservice cost control:Restaurants and catering operators are deploying commercial-grade systems to reduce beverage supplier dependency and capture margin on in-house sparkling water production.
- Stainless steel chassis migration:Premium kitchen appliance manufacturers are pivoting from ABS plastic to stainless steel construction as durability expectations and raw material cost structures shift.
Market Restraints
- CO2 cylinder supply concentration:Food-grade CO2 canister production clusters among specialized industrial gas suppliers, creating vulnerability to input cost volatility and logistics disruption.
- Valve material compliance friction:EU REACH restrictions on food-contact substances limit compatible alloys for high-pressure valve components, constraining design flexibility and supplier pools.
- Tap water quality variability:Regional differences in municipal water mineral content and filtration standards affect carbonation performance consistency, limiting addressable markets without pre-treatment accessories.
Strategic Opportunities
- Built-in kitchen integration:Luxury renovation markets in Germany and Switzerland present white space for cabinetry-integrated systems targeting premium residential construction.
- ISO 7864 standardization tailwind:Thread compatibility standards for CO2 cylinders are enabling interoperability across brands, lowering consumer switching costs and expanding addressable base.
- Smart connectivity convergence:IoT-enabled carbonation systems with usage tracking and automatic reordering are penetrating connected kitchen ecosystems in North American and Western European households.
Industry Challenges
- Pressure vessel certification timelines:FDA food-contact substance approvals and EU CE marking for pressurized appliances extend product development cycles and delay market entry.
- Retrofit integration complexity:Built-in system installation requires coordination with kitchen designers and contractors, fragmenting sales cycles and complicating channel management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soda Maker Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Countertop, Built-in, Commercial End User: Households, Restaurants, Cafes, Catering Services Distribution Channel: Online Stores, Specialty Retail, Supermarkets, Wholesalers Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | SodaStream Inc., Aarke AB, I-Drink Products Inc., Hamilton Beach Brands Holding Company, Mysoda Oy, iSi GmbH, Drinkpod LLC, Sparkel Beverage Systems, SharkNinja Operating LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soda Maker Market Strategic Shifts
Material science advances and regulatory tightening on food-contact substances are reshaping product architecture, while distribution models adapt to recurring CO2 cylinder replenishment economics.
Electromechanical carbonation valves are integrating precision pressure sensors and automated dosing algorithms to replace manual lever systems. Premium residential buyers in Germany and Switzerland are adopting these systems at accelerated rates. This technology is integrating predictive maintenance capabilities and usage analytics that compress traditional after-sales service models into continuous data-driven relationships.
EU REACH restrictions on bisphenol-A and phthalates in food-contact applications are forcing valve housing material substitutions toward stainless steel and certified thermoplastics. Manufacturers serving European markets must reformulate component specifications and requalify supply chains. Stainless steel chassis producers targeting German specialty retail are responding fastest, leveraging existing metallurgy expertise to meet tightened compliance windows.
Subscription-based CO2 cylinder exchange programs are displacing single-transaction retail purchases in established markets. Direct-to-consumer channels and bundled replenishment apps are capturing recurring revenue relationships that supermarkets cannot replicate. This behavioral shift is most visible in US and UK urban markets where apartment-dwelling consumers prioritize convenience over unit economics.
Global Soda Maker Market Segmentation
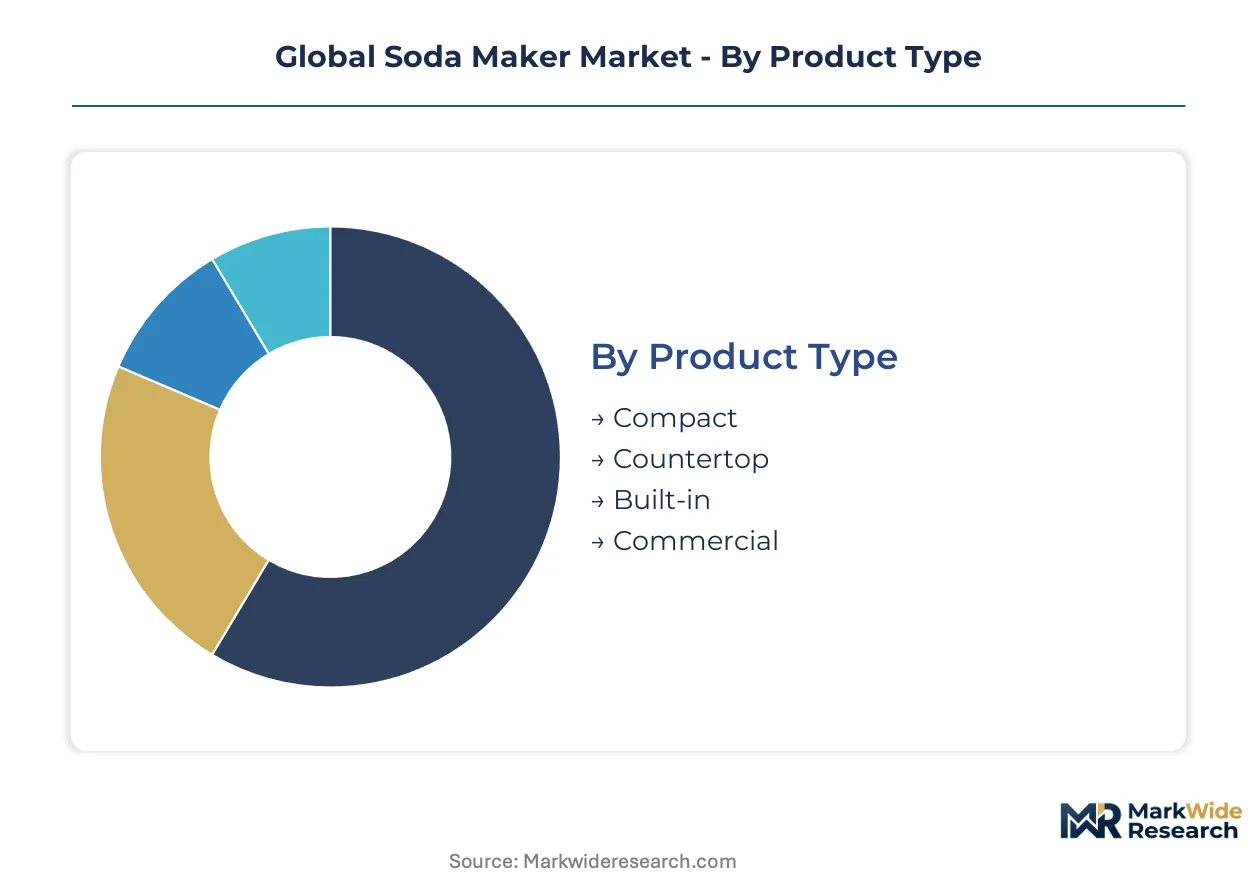
Soda maker segmentation reveals divergent compliance burdens across product architectures. Certification requirements for pressurized CO2 systems fragment addressable markets by distribution channel and end-use application.
Product Type:
FDA food-contact substance approvals and EU CE marking for pressurized appliances create tiered certification timelines across physical form factors.
- Compact:Apartment-optimized footprints under 15 centimeters wide operate at reduced pressure thresholds. Demand clusters in Tokyo and New York high-density residential where counter space commands premium pricing. CE marking requirements for portable pressurized devices remain less stringent than built-in alternatives.
- Countertop:Dominant unit volume segment featuring manual lever or electromechanical valve systems. German and UK households drive replacement cycles as stainless steel chassis displace ABS plastic predecessors. ISO 7864 cylinder thread compatibility enables cross-brand CO2 interoperability.
- Built-in:Cabinetry-integrated systems requiring coordinated installation with kitchen designers.
- Commercial:High-capacity carbonation for foodservice operators managing peak demand periods.
Leading the category by volume: Countertop. Growing fastest: Commercial.
End User:
Customer procurement patterns split between recurring CO2 replenishment economics and capital equipment depreciation schedules.
- Households:Subscription-based cylinder exchange programs displace single-transaction retail. US and UK urban apartment dwellers prioritize convenience over unit economics through direct-to-consumer replenishment apps.
- Restaurants:In-house sparkling water production reduces beverage supplier dependency. Operators in France and Italy deploy commercial-grade systems to capture margin on table water service.
- Cafes:Moderate-volume carbonation for menu diversification.
- Catering Services:Mobile event deployment requiring portable cylinder logistics.
Dominant revenue share: Households. Expanding most quickly: Restaurants.
Distribution Channel:
Channel economics diverge between recurring replenishment relationships and one-time hardware transactions.
- Online Stores:Direct-to-consumer platforms bundle hardware with subscription cylinder replenishment. Automated reordering algorithms based on usage tracking compress customer acquisition costs.
- Specialty Retail:Curated showroom experiences for premium stainless steel chassis. Swiss and German specialty kitchen retailers command highest average transaction values through design-forward positioning.
- Supermarkets:Mass-market volume through accessible price points and impulse placement.
- Wholesalers:B2B procurement for foodservice and commercial installations.
Highest margin capture: Specialty Retail. Steepest expansion trajectory: Online Stores.
Price Tier:
Material specifications and valve component alloys stratify pricing architecture across certification grades.
- Economy:ABS plastic chassis with basic manual valve systems. Price-sensitive penetration in emerging markets where EU REACH compliance is not mandated.
- Mid-range:Hybrid construction blending thermoplastic housings with stainless steel contact surfaces. Balances durability expectations against raw material cost pressures.
- Premium:Full stainless steel construction with electromechanical carbonation valves. German and Swiss residential buyers adopt precision pressure sensors and automated dosing algorithms at accelerated rates.
- Luxury:Custom finishes and cabinetry integration for renovation projects.
Volume concentration: Mid-range. Gaining share fastest: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in Germany, where premium kitchen appliance penetration and sustainability-conscious purchasing run highest among Western European markets. Household adoption of at-home carbonation systems is accelerating as consumers across multiple geographies reduce single-use plastic dependency. Regulatory frameworks in France and Germany are advancing extended producer responsibility mandates that reshape distribution economics.
Germany
Premium residential buyers in Munich and Hamburg adopt electromechanical carbonation systems with precision pressure sensors at accelerated rates. EU REACH restrictions on food-contact substances force valve housing material substitutions toward certified stainless steel and thermoplastics. The Stuttgart industrial corridor hosts manufacturers leveraging existing metallurgy expertise to meet tightened compliance windows.
United States
Urban apartment dwellers in New York and Chicago prioritize convenience over unit economics through direct-to-consumer replenishment apps. FDA food-contact substance regulations shape product design requirements for manufacturers selling across North American markets. Silicon Valley connected kitchen ecosystems are penetrating with IoT-enabled carbonation systems featuring usage tracking and automatic reordering.
France
Restaurants in Paris and Lyon deploy commercial-grade systems to capture margin on in-house sparkling water production and reduce beverage supplier dependency. Extended producer responsibility frameworks are advancing take-back mandates for disposable CO2 canisters, creating regulatory pull for refillable exchange infrastructure. The Île-de-France region concentrates foodservice operator procurement for high-capacity carbonation equipment.
Switzerland
Luxury renovation markets in Zurich and Geneva present white space for cabinetry-integrated systems targeting premium residential construction. Swiss specialty kitchen retailers command highest average transaction values through design-forward positioning of full stainless steel chassis. The country's national consumer protection regulator maintains stringent pressure vessel certification requirements that extend product development timelines.
United Kingdom
Subscription-based CO2 cylinder exchange programs displace single-transaction retail purchases in London and Manchester urban markets. ISO 7864 standards for CO2 cylinder thread compatibility enable interoperability across brands, lowering consumer switching costs. The Midlands manufacturing belt supplies hybrid construction chassis blending thermoplastic housings with stainless steel contact surfaces for mid-range price tiers.
Global Soda Maker Market Competitive Environment
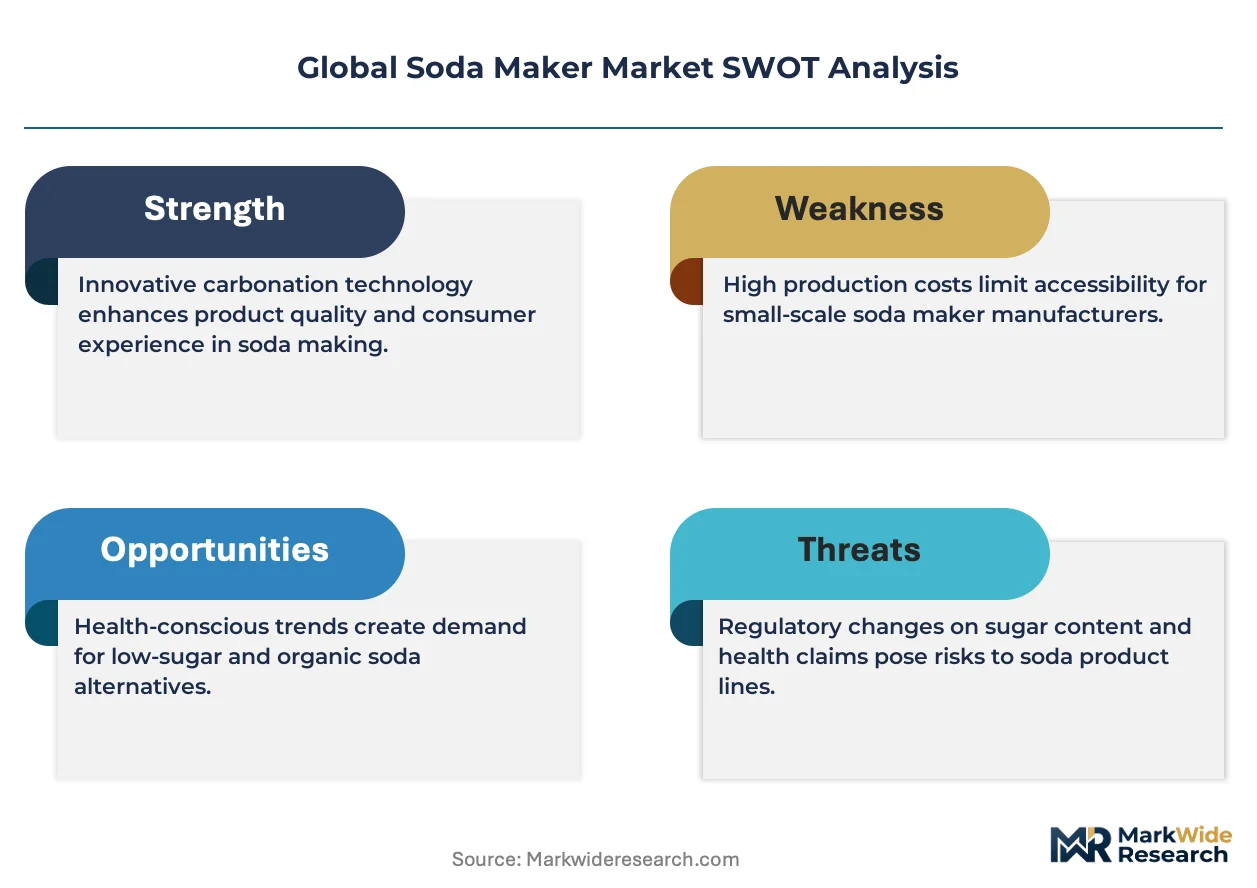
Strategic partnerships dominate the current landscape as manufacturers coordinate with retail networks to sustain recurring CO2 cylinder replenishment economics. The vendor base organizes across three tiers: mass-market volume players competing on supermarket distribution, premium design specialists commanding specialty retail placement, and commercial-grade fabricators serving foodservice operators. Two strategic archetypes have emerged—captive infrastructure builders investing in exchange logistics, and materials-science specialists pivoting chassis construction toward regulatory-compliant alloys. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants seek to offset input cost volatility.
Within the premium-tier vector, Aarke AB exemplifies design-forward positioning through stainless steel construction that commands elevated price points in European specialty retail. SodaStream Inc. anchors the captive infrastructure archetype, leveraging retail partnerships to sustain recurring revenue streams through cylinder exchange programs. Hamilton Beach Brands Holding Company occupies the mass-market position, competing on accessible price points and broad supermarket distribution. These three entities collectively illustrate the market's tripartite structure—premium design, recurring revenue infrastructure, and volume-driven accessibility—without any single archetype commanding definitive share.
| Leading Market Players |
|---|
| SodaStream Inc. |
| Aarke AB |
| I-Drink Products Inc. |
| Hamilton Beach Brands Holding Company |
| Mysoda Oy |
| iSi GmbH |
| Drinkpod LLC |
| Sparkel Beverage Systems |
| SharkNinja Operating LLC |
| Others |
Value Chain & Pricing Dynamics
Captive CO2 exchange infrastructure anchors supply positioning and pricing power for cylinder-dependent revenue streams. Manufacturers investing in retail partnership networks command recurring revenue premiums that transactional hardware sellers cannot replicate.
Pricing Analysis
Volume concentration in mass-market countertop units runs against margin capture in built-in and commercial configurations. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel electromechanical systems from hybrid chassis and basic ABS plastic alternatives. Price differentiation rests on certification grade for EU REACH compliance and after-sales service bundling through subscription replenishment programs. Pricing pressure stems from raw material cost volatility in food-grade CO2 cylinder production. Mass-market supermarket buyers exhibit highest price sensitivity, while German specialty retail purchasers show lowest elasticity for design-forward premium positioning.
Supply Chain Analysis
CE marking and FDA food-contact substance approvals gate supplier qualification, extending component sourcing timelines. Manufacturing concentrates in Germany, China, and the United States, with the Stuttgart corridor hosting metallurgy-advanced chassis fabricators. Raw material dependencies center on food-grade CO2, certified stainless steel alloys, and high-pressure valve thermoplastics. Single-source vulnerability clusters among specialized industrial gas suppliers for cylinder production. Distribution runs through retail partnerships for captive exchange infrastructure, direct-to-consumer platforms for subscription bundling, and specialty kitchen showrooms for premium placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade CO2 cylinder production capacity constraints prop pricing power for manufacturers with secured supply agreements. This supply-constrained structure favors incumbents with backward-integrated gas supplier relationships.
For Market Incumbents: To counter emerging IoT-enabled entrants from connected kitchen ecosystems, incumbents should deepen captive CO2 exchange infrastructure through exclusive retail partnerships and accelerate certification investment for EU REACH-compliant valve materials. Channel control through supermarket placement agreements remains essential for volume defense. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for bypassing incumbent retail lock-in. Target UK and US urban apartment dwellers with automated replenishment apps and usage-tracking hardware. White space exists in commercial-grade systems for mid-tier restaurant chains seeking margin capture on in-house carbonation. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified kitchen appliance conglomerates seeking recurring revenue streams. Long-term viability favors manufacturers with backward-integrated CO2 supply and certified European production footprints. Watch ISO 7864 standardization adoption rates as inflection indicator for interoperability-driven market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive CO2 Exchange Infrastructure Expansion | Retail partnerships in Germany and the United States lock in recurring revenue relationships competitors cannot displace. |
| Stainless Steel Chassis Certification Investment | EU REACH compliance on food-contact valve materials opens premium specialty retail placement in Swiss and German markets. |
| Commercial-Grade System Development | Foodservice operator procurement in France and Italy captures margin from beverage supplier displacement. |
| IoT Connectivity Integration | Silicon Valley connected kitchen ecosystems enable automatic reordering algorithms that compress customer acquisition costs. |
| Built-In Kitchen Integration Partnerships | Luxury renovation markets in Zurich and Geneva present white space for cabinetry-integrated premium positioning. |
Study Parameters
Multi-period observation of CO2 cylinder exchange volumes, chassis material substitution rates, and certification timeline extensions anchored the trend analysis, supplemented by interviews with appliance category managers at specialty retailers, procurement leads at foodservice operators, CO2 supply specialists at industrial gas firms, and regulatory affairs directors at manufacturers. Secondary validation drew from EU REACH substance restriction databases, FDA food-contact substance filings, ISO standardization committee records, and customs trade data on pressurized valve component imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-weighting across product type, end user, distribution channel, and price tier dimensions shaped the analytical framework across the analysis window. CAGRs were derived from regression-based trend extrapolation moderated by regulatory compliance timeline adjustments. Forecast inputs incorporated extended producer responsibility framework adoption schedules in France and Germany, plus ISO 7864 thread compatibility standardization penetration curves.
The model holds under stable regulatory compliance timelines and intact CO2 supply chain logistics; deviation in EU REACH substance restriction scope or food-grade gas production capacity would shift volume and value trajectories. A model refresh is warranted upon material change in extended producer responsibility mandate implementation or ISO 7864 interoperability certification rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Middle East Energy Drinks Market
Beverages
Beverage Premix Market
Beverages
Vegetable Juice Market
Beverages
Whole Grain Drinks Market
Beverages
Spring Water Market
Beverages
Chill Block Market
Beverages
Europe Yerba Mate Market
Beverages
Aloe Vera Juice Market
Beverages
Hydration Infusers Market
Beverages
Tonic Water Market
Beverages
Electrolyte Mixes Market
Beverages
US Bubble Tea Market
Beverages
Soft Serve Premix Market
Beverages
Recovery Drinks Market
Beverages
Bottled Deep Ocean Water Market
Beverages
India Bottled Water Market