
 Baby Drinks Market | 2026-2036
Baby Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Drinks Market Intelligence
The rise of direct-to-consumer subscription models is narrowing the competitive field for new entrants lacking established brand equity and supply chain scale. Nestlé leverages its extensive global distribution network and brand recognition to maintain market leadership in infant formula. Danone differentiates its portfolio through a focus on specialized nutrition products, including those for allergies and digestive health. Abbott competes on the basis of strong clinical research backing its product efficacy and safety claims.
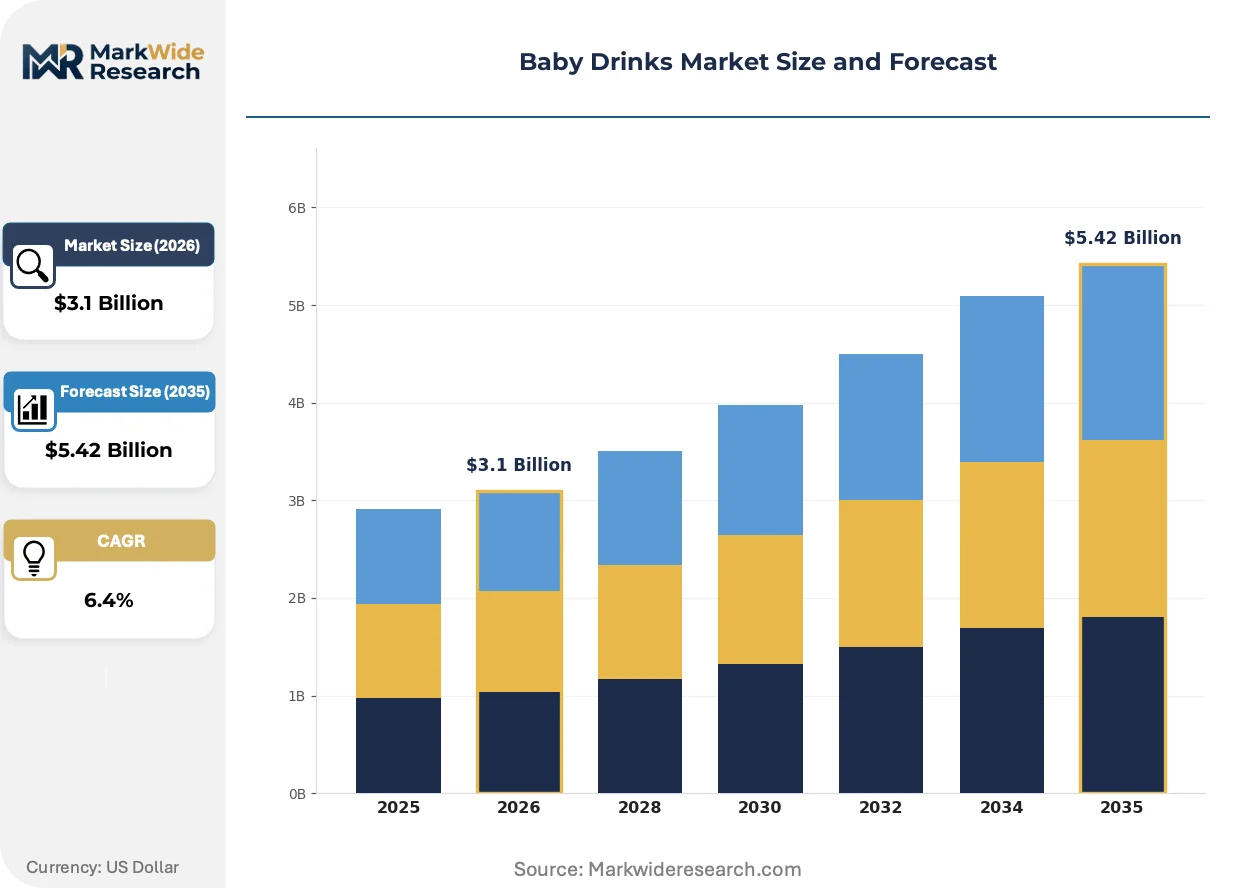
Baby drinks are commercially prepared beverages formulated to meet the nutritional requirements of infants and toddlers. These products are fortified with precise levels of iron, vitamin D, and DHA omega-3 fatty acids to support healthy cognitive and physical development. Infant formula remains the dominant product category, serving as a primary nutrition source. The ready-to-feed format is expanding rapidly, offering greater convenience for caregivers compared to traditional powder forms.
Regulatory oversight from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictates strict standards for nutrient composition and allergen labeling. In China, the National Medical Products Administration (NMPA) enforces rigorous registration processes for infant formula. Future success depends on innovating with plant-based ingredients and adopting sustainable packaging solutions.
Market Dynamics
The market's central tension arises from the collision between escalating parental demand for clean-label, functional nutrition and the tightening of global safety regulations. This dynamic forces constant reformulation and intensifies scrutiny on ingredient sourcing and product claims across all segments.
Growth Catalysts
- Nutrient Fortification Mandates:Health authority guidelines, including those from the WHO, promote the fortification of baby drinks with specific nutrients like iron, vitamin D, and DHA to support cognitive development, driving demand for enriched formulas.
- Urbanization and Convenience:The expansion of ready-to-feed formats is directly linked to the needs of time-constrained caregivers in dense urban centers, particularly across rapidly developing economies in Asia, offering unparalleled convenience over powdered alternatives.
- Plant-Based Formulations:Innovations using soy, oat, and pea proteins are creating new product categories. These address parental concerns over dairy allergies and cater to a growing preference for plant-centric diets, expanding the consumer base.
Market Restraints
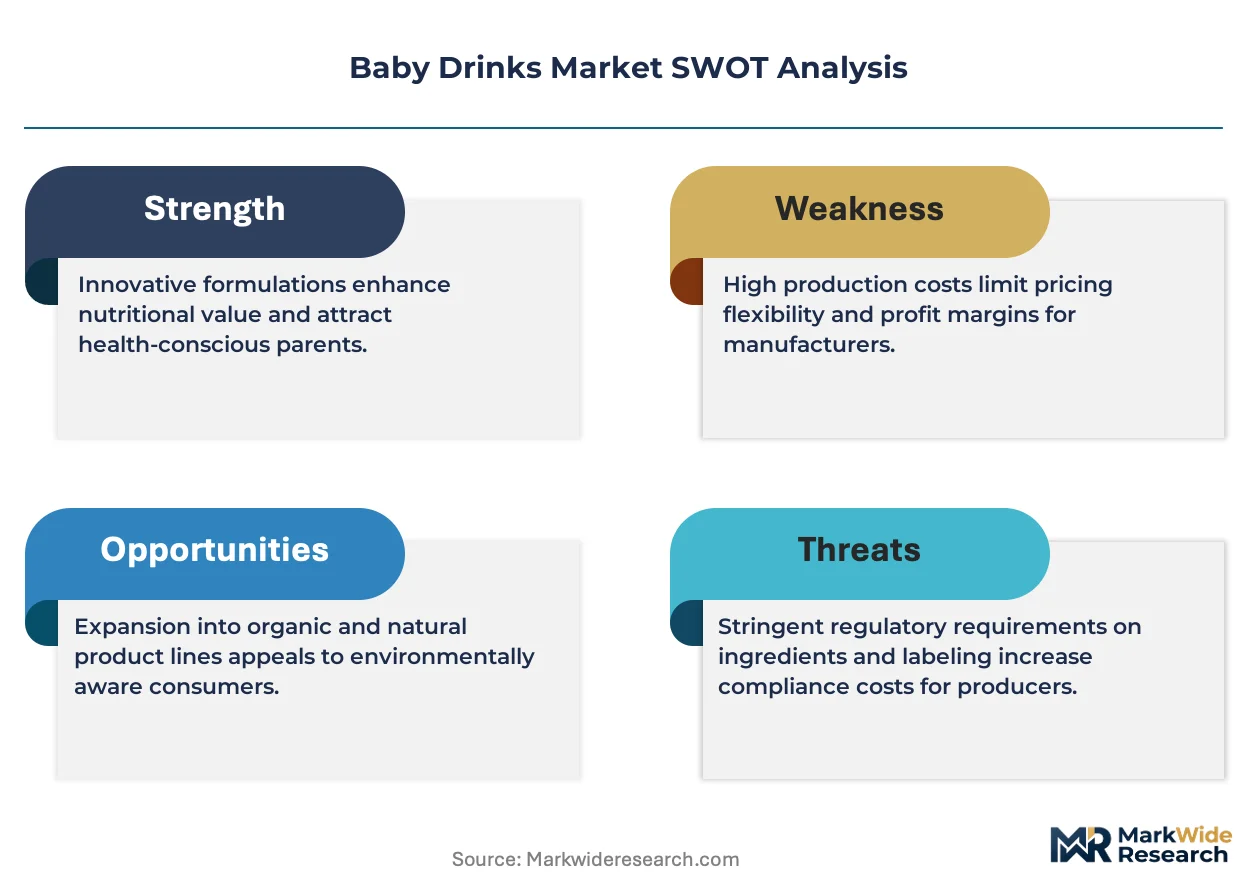
- Commodity Price Volatility:The price of dairy whey and other core ingredients is subject to significant fluctuation, which directly impacts production costs and creates margin instability for manufacturers of traditional milk-based formulas.
- Strict Regulatory Gatekeeping:Lengthy and expensive registration processes, such as those enforced by China’s NMPA, act as a significant barrier to entry and can delay the launch of new products from international brands.
- Breastfeeding Promotion:Sustained global campaigns by health organizations like UNICEF and the WHO advocating for breastfeeding as the optimal source of infant nutrition represent a fundamental and persistent substitution threat to the entire formula market.
Strategic Opportunities
- Specialized Toddler Nutrition:There is an opportunity to develop and market functional beverages for toddlers, targeting specific needs like digestive health, immune support, and cognitive function, extending product lifecycles beyond infancy.
- Direct-to-Consumer Subscriptions:Building DTC channels allows brands to establish direct relationships with consumers, offering personalized product bundles and creating a recurring revenue stream that bypasses competitive retail environments.
- Geographic Expansion in Southeast Asia:Markets such as Vietnam and Indonesia, with their rising disposable incomes and increasing female workforce participation, present significant untapped potential for both standard and premium baby drink products.
Industry Challenges
- Cold Chain Logistics Complexity:Ensuring the safety and quality of ready-to-feed liquid products requires an unbroken and costly cold chain from manufacturing to the point of consumption, posing a significant logistical challenge.
- Divergent Allergen Labeling:Manufacturers face operational complexity in managing packaging and formulations to comply with differing allergen labeling standards between major markets, such as those set by the FDA and EFSA.
- Sustainable Packaging Transition:The shift to environmentally friendly packaging materials is hampered by the technical need to maintain product sterility, prevent contamination, and ensure adequate shelf life for sensitive nutritional formulas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Drinks Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Formula, Fruit Juice, Vegetable Puree, Cereal-based Drinks Form: Powder, Liquid, Ready-to-Feed, Concentrate Packaging Type: Tetra Pack, Glass Bottle, Plastic Pouch, Jar Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Pharmacies |
| Companies Covered | Nestlé, Abbott, Danone, Mead Johnson & Company, FrieslandCampina, Arla Foods, Meiji Holdings, HiPP, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Drinks Market Strategic Shifts & Innovations
Product formulation is evolving to meet dual consumer demands for clinically supported nutritional benefits and absolute transparency in ingredient sourcing. This shift is driving innovation in packaging, regulatory compliance, and direct engagement with caregivers.
Smart packaging technology, including unique QR codes on product containers, provides verifiable data on provenance and composition. Parents are rapidly adopting this feature to confirm authenticity and access detailed batch-specific information before feeding. This capability is digitizing the consumer experience, creating a transparent and traceable link from the factory to the nursery and reinforcing brand trust.
New regulations from the US FDA and Europe's EFSA are imposing stricter limits on heavy metal contaminants like arsenic and lead in finished baby food products. This is forcing a complete re-evaluation of raw material sourcing and the implementation of more rigorous, multi-stage testing protocols. The organic segment is most impacted, as brands must now prove their products meet both organic standards and these new, lower contaminant thresholds.
A clear behavioral shift towards subscription-based purchasing is disrupting the market's traditional distribution structure. This direct-to-consumer model bypasses the need for shelf space in conventional retail channels like supermarkets and pharmacies, altering competitive dynamics. The trend is most visible in North America and Europe, where digitally savvy parents prioritize the convenience of automated, recurring deliveries.
Baby Drinks Market Segmentation
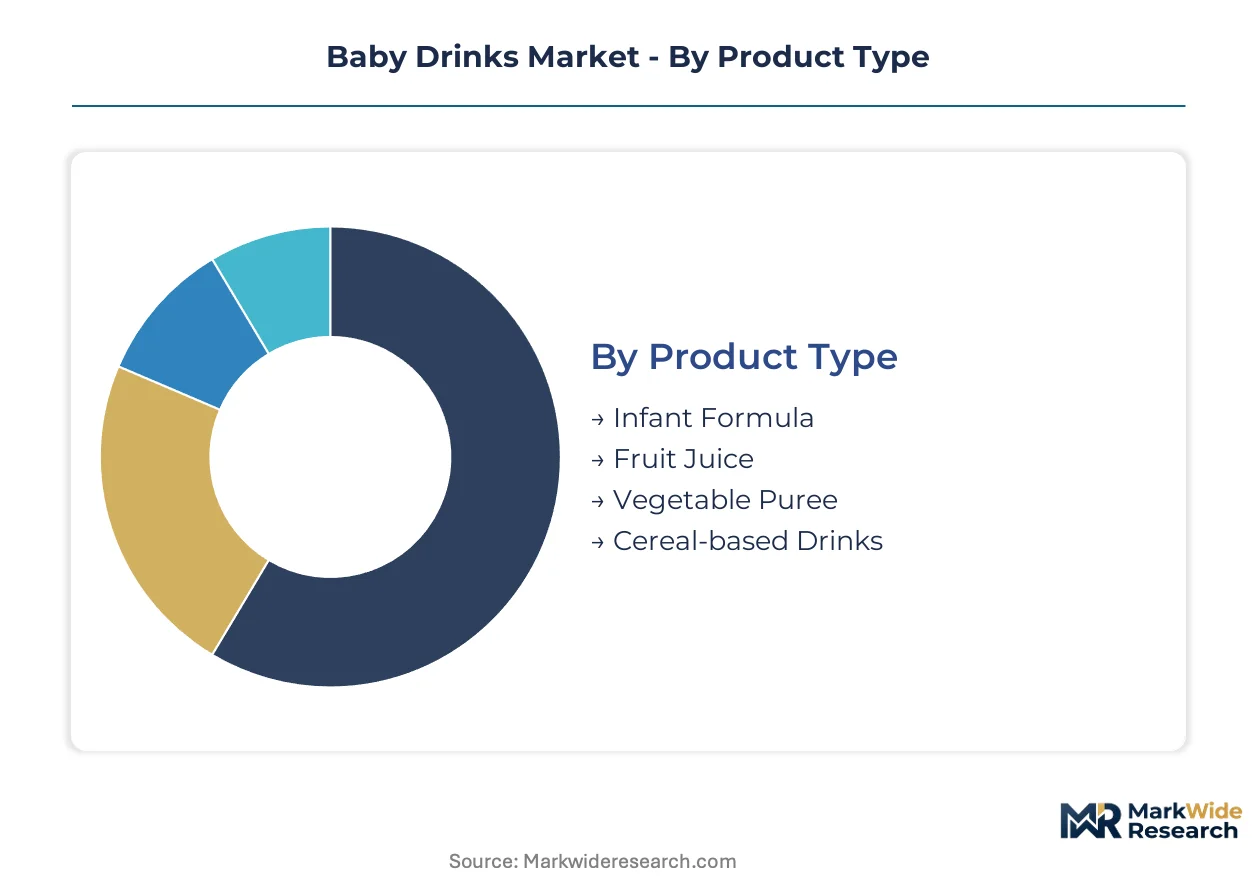
Segmentation within the baby drinks market highlights diverse product applications and delivery formats for infant nutrition. This granular breakdown enables manufacturers to tailor formulations and packaging to specific caregiver needs. Understanding these distinct segments is crucial for strategic market penetration and product development.
Product Type:
The spectrum of baby drink product types caters to various nutritional stages and dietary requirements from infancy through toddlerhood.
- Infant Formula:Infant formula provides complete nutritional support for babies, designed to mimic breast milk composition with precise levels of proteins, fats, carbohydrates, and micronutrients. Demand concentrates in urban centers globally, driven by convenience for working parents and specific dietary needs.
- Fruit Juice:Baby fruit juices offer supplementary hydration and introduce various fruit flavors, often fortified with vitamins like C. Consumption is high in North America and Europe, where parents seek convenient, palatable options for toddlers.
- Vegetable Puree:Vegetable purees in drinkable form introduce early solid food nutrients and diverse flavors to infants.
- Cereal-based Drinks:Cereal-based drinks provide additional calories and fiber, supporting satiety and energy levels for older infants.
The dominant share belongs to Infant Formula, while Fruit Juice is closing the gap fastest.
Form:
Different product forms directly influence preparation time and portability, addressing diverse caregiver routines and consumption scenarios.
- Powder:Powdered formulas require mixing with water, offering a cost-effective and shelf-stable solution for infant nutrition. This form maintains high demand in developing economies like India and Indonesia due to its affordability and extended usability.
- Ready-to-Feed:Ready-to-Feed products are pre-mixed and sterile, providing ultimate convenience for immediate consumption without preparation. Demand is accelerating in markets with high disposable incomes, such as the United States and Germany, catering to busy lifestyles.
- Liquid:Liquid formulations offer a convenient, pre-diluted option, reducing preparation time compared to powdered alternatives.
- Concentrate:Concentrate forms require dilution with water, balancing convenience with a more economical price point.
Powdered formulations maintain a significant market presence, but Ready-to-Feed products are gaining share fastest.
Packaging Type:
Packaging material choices impact product preservation, portability, and environmental footprint, influencing consumer preference and logistic chains.
- Tetra Pack:Tetra Pack packaging provides lightweight, aseptic storage, protecting nutritional integrity without refrigeration until opened. Its adoption is strong in European markets for on-the-go convenience and reduced environmental impact compared to plastic.
- Glass Bottle:Glass bottles offer a premium perception and inert material for preserving product purity, preferred by parents concerned about chemical leaching. Demand remains consistent in markets like France and Japan, valuing traditional, recyclable options.
- Plastic Pouch:Plastic pouches offer flexible, lightweight, and single-serve packaging, ideal for snacks and travel convenience.
- Jar:Jars are typically used for purees and thicker baby foods, providing sturdy, resealable storage.
Glass bottles retain a strong traditional appeal, while Tetra Pack solutions are expanding most quickly due to convenience and sustainability efforts.
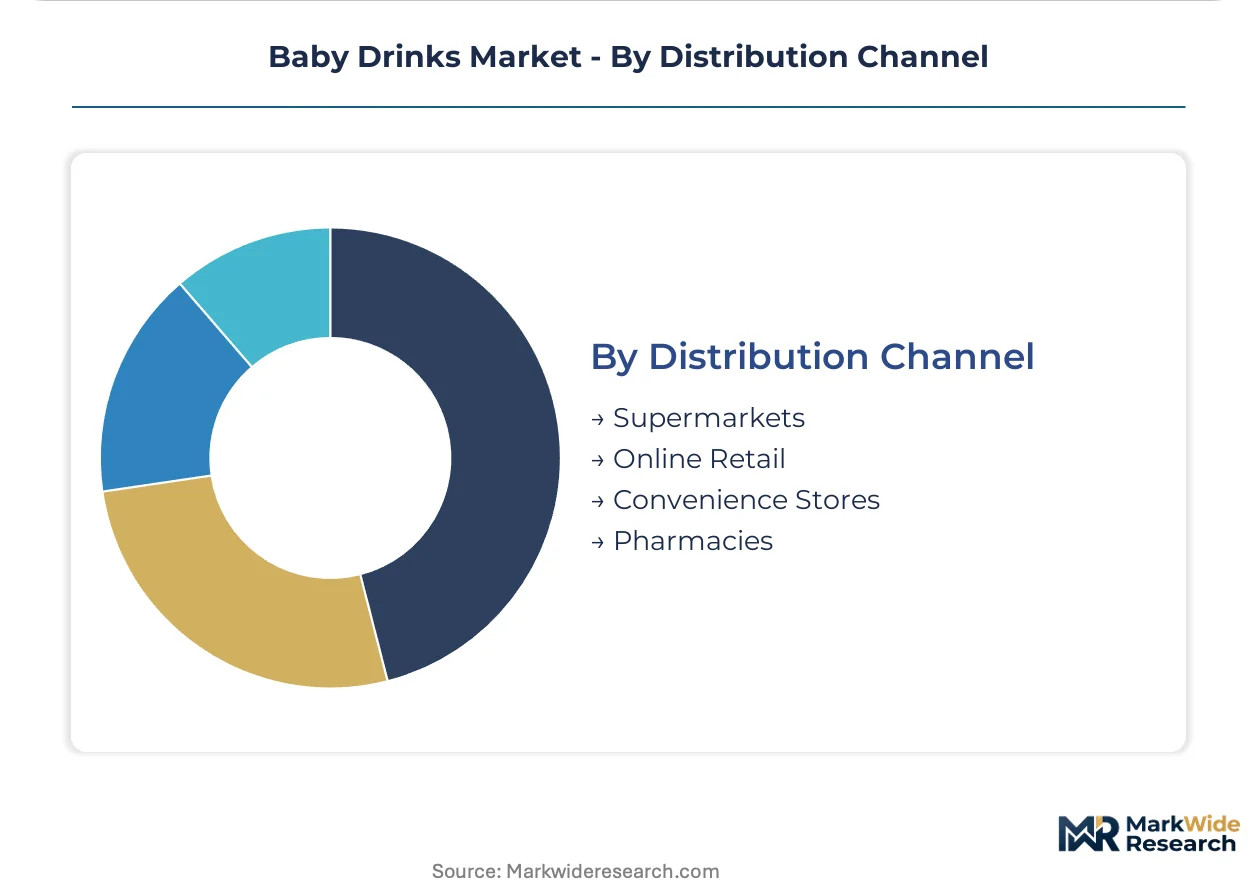
Distribution Channel:
The diversity of distribution channels reflects varied consumer purchasing habits and accessibility requirements across different demographics.
- Supermarkets:Supermarkets serve as the primary retail channel, offering broad product ranges and competitive pricing for baby drinks. This channel accounts for the largest sales volume across most developed and emerging economies, leveraging established consumer shopping patterns.
- Online Retail:Online retail platforms provide unparalleled convenience and direct-to-consumer options, facilitating subscription models and doorstep delivery. This channel is experiencing rapid growth in North America and China, driven by digital-savvy parents and extensive product availability.
- Convenience Stores:Convenience stores cater to immediate needs and impulse purchases, offering quick access to essential baby drink products.
- Pharmacies:Pharmacies distribute specialized and medical-grade baby formulas, often with professional advice and health-focused product selections.
Supermarkets command the largest share of sales, but online retail channels are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health authority guidelines promoting nutrient fortification drive regional market dynamics. These policies encourage the development and distribution of enriched baby drink formulations, directly influencing product availability and consumer choices across diverse economic landscapes.
China
Rising disposable incomes and rapid urbanization concentrate demand for fortified and functional baby drinks. The National Medical Products Administration (NMPA) enforces rigorous registration processes for infant formula, shaping product entry. Urban centers like Shanghai and Beijing represent significant consumption hubs for premium baby nutrition products.
United States
Parental demand for clean-label and non-GMO products fuels growth in the premium organic beverage segment. The US Food and Drug Administration (FDA) sets stricter contaminant limits, impacting raw material sourcing and formulation. Major metropolitan areas, including New York and Los Angeles, show high demand for convenient ready-to-feed options.
Germany
High disposable incomes and busy lifestyles accelerate the adoption of ready-to-feed formats. The European Food Safety Authority (EFSA) dictates stringent standards for nutrient composition and allergen labeling. Cities such as Berlin and Munich exhibit strong market penetration for specialized nutrition products.
India
Affordability and extended usability maintain high demand for powdered infant formulas, particularly in developing urban areas. The Food Safety and Standards Authority of India (FSSAI) regulates product safety and nutritional claims. Rapidly expanding urban centers like Mumbai and Delhi are key markets for cost-effective baby drink solutions.
Vietnam
Rising disposable incomes and increasing female workforce participation present significant untapped potential for standard and premium baby products. Local health authorities are progressively implementing guidelines for infant nutrition. Ho Chi Minh City and Hanoi are emerging as critical growth areas for convenient baby drink formats.
Baby Drinks Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established global conglomerates competing alongside specialized niche players. Market leadership is asserted through extensive distribution networks and strong brand recognition. Key archetypes include multinational nutrition giants, specialized allergy-focused providers, and clinically-driven efficacy leaders. Dominant competitive moves involve portfolio diversification and strategic geographic expansion into high-growth regions.
Multinational nutrition giants, such as Nestlé, leverage extensive global distribution networks and brand recognition to maintain market leadership in infant formula. Specialized nutrition providers like Danone differentiate their portfolios through a focus on products for allergies and digestive health. Abbott competes on the basis of strong clinical research backing its product efficacy and safety claims, occupying a premium tier in the market.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| Danone |
| Mead Johnson & Company |
| FrieslandCampina |
| Arla Foods |
| Meiji Holdings |
| HiPP |
| The Kraft Heinz Company |
| Others |
Cost & Logistics Intelligence
China's specialized infant formula production zones dictate global supply capacity. This concentration of manufacturing capability significantly influences downstream pricing power across diverse regional markets.
Pricing Analysis
Clean-label certification creates the primary spread in baby drink pricing, which operates on a per-unit transactional model with premium tiers for specialized nutrition products. Price differentiation stems from rigorous non-GMO verification and specific functional health claims. Pricing pressure intensifies due to escalating raw material costs and the investment required for sustainable packaging solutions. Caregivers in developing economies exhibit higher price sensitivity compared to urban consumers in North America seeking convenient ready-to-feed options.
Supply Chain Analysis
Manufacturing capacity for baby drinks concentrates among a few multinational players like Nestlé and Danone, primarily across facilities in Europe and North America. The industry relies on critical raw materials such as dairy whey, plant-based proteins, and DHA omega-3 fatty acids. Cold chain logistics complexity for ready-to-feed formats presents a significant structural risk, demanding unbroken temperature control. Distribution runs through a dual model, leveraging extensive supermarket networks and rapidly expanding online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby drinks market is experiencing a cyclical recovery, propelled by rising disposable incomes in key emerging economies. This economic uplift enables greater access to premium and fortified nutrition products for infants and toddlers.
For Market Incumbents: Insulate core market share by deepening investment in plant-based formulation R&D to meet evolving consumer preferences. Expand direct-to-consumer subscription models to counter new entrant agility and strengthen brand loyalty. This approach mitigates the threat from smaller, agile brands focusing on niche dietary needs. Prioritize certification investment for new contaminant limits to maintain regulatory compliance and product trust.
For New Entrants and Emerging Players: Specialized toddler nutrition in Southeast Asia represents the most penetrable entry point for new brands. Target functional beverages addressing specific needs like digestive health and immune support, extending product lifecycles beyond infancy. Leverage direct-to-consumer subscription models to build immediate customer relationships and bypass established retail channels. Focus on plant-based formulations to capture a growing, health-conscious consumer segment.
For Investors and Strategic Acquirers: Early-to-mid-cycle technology positioning favors specialized nutrition providers with strong R&D in plant-based ingredients. The market demonstrates long-term viability, driven by sustained parental demand for clean-label and functional products. Target acquisition profiles include agile companies innovating in sustainable packaging or direct-to-consumer distribution. The signal to watch is the accelerated consumer adoption of smart packaging for product traceability, indicating shifting trust metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Plant-Based R&D | This addresses growing parental preference for plant-centric diets and concerns over dairy allergies. |
| Expand Direct-to-Consumer (DTC) Channels | This establishes direct relationships with caregivers, creating recurring revenue streams and personalized offerings. |
| Sustainable Packaging Development | This meets environmental mandates and consumer demand for eco-friendly solutions while maintaining product sterility. |
| Geographic Expansion in Southeast Asia | This captures new consumer segments in high-growth markets with rising disposable incomes and female workforce participation. |
| Enhance Smart Packaging Integration | This provides verifiable product provenance and composition data, reinforcing brand trust among digitally savvy parents. |
Research Approach
Cross-validation between primary interviews and secondary market intelligence anchors the qualitative findings of this study. The research combined insights from product development executives, regulatory affairs specialists, supply chain managers, and marketing leads. Secondary validation drew from US FDA filings, EFSA reports, NMPA guidelines, and industry association publications. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecast framework calibrated market projections using a multi-variate regression model across the analysis window. Segmentation dimensions modeled included product type, form, packaging type, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical growth rates and projected market drivers. Key industry-specific forecast inputs included parental disposable income trends and evolving contaminant limit changes.
Practitioners should monitor global trade policies and raw material supply disruptions for early signals impacting market forecasts. Forecasts reflect documented assumptions regarding market dynamics and consumer behavioral shifts. Monthly review of raw material indices and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Latin America Sports and Energy Drinks Market
Beverages
United States and Australia Coconut Water Market
Beverages
Rose Floral Water Market
Beverages
Plant Based Protein Beverages Market
Beverages
Nitro-Infused Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Gluten Free Beverages Market
Beverages
Caffeinated Beverage Market
Beverages
Fiber Fortified Beverages Market
Beverages
Fermented Drinks Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Plant-Based Energy Drink Market
Beverages
Europe Smoothies Market
Beverages
Low Fat Drinks Market
Beverages
Beverage Dispenser Market
Beverages
Maple Water Market