
 Europe Alcoholic Beverage Market | 2026-2036
Europe Alcoholic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alcoholic Beverage Market Foresight
Spain's sherry triangle capacity build-out is fragmenting traditional supply networks across Southern Europe. Pernod Ricard leverages its heritage distillation infrastructure to sustain premium pricing in cognac and malt whisky. Heineken Holding NV anchors lager volumes through controlled distribution across the Netherlands and export corridors. Diageo Plc competes aggressively in gin and tequila through specialized brand architecture.
Europe alcoholic beverages encompass fermented and distilled products with ethanol concentrations typically ranging from 0.5% to 40% ABV, produced through controlled yeast fermentation, distillation, or fortification processes for commercial consumption and social ritual purposes. Beer retains volume leadership but faces margin compression as spirits capture value pools through premiumization. Wine segments show structural maturity in traditional markets while canned formats and ready-to-drink applications attract younger demographics. Online retail channels represent the fastest-growing end-user pathway, though bars and restaurants still control experiential brand building.
EMA guidelines on health claims, EU Green Deal sustainability mandates, and national excise frameworks collectively shape formulation standards, labeling requirements, and cross-border market access across member states. REACH compliance now extends to packaging materials and agricultural inputs, forcing reformulation investments. Stakeholders must monitor evolving low-alcohol thresholds and digital sales taxation as regulatory fragmentation intensifies.
Market Dynamics
The EU Green Deal is forcing capital reallocation across European beverage manufacturing, with REACH compliance costs now extending to agricultural inputs and packaging substrates. Distillers and brewers face simultaneous pressure from excise harmonization debates and carbon-border adjustment mechanisms.
Growth Catalysts
- EU Farm to Fork Strategy:Sustainability mandates are accelerating regenerative viticulture adoption across Spanish and Italian wine cooperatives. Producers securing early certification capture preferential listing in Dutch and German retail channels.
- On-trade premiumization:Specialized cocktail bars in Berlin, Paris, and Lisbon are expanding single-malt and small-batch gin allocations. This channel shift elevates average transaction values for heritage distillers.
- Controlled fermentation technologies:Precision yeast strains and temperature-monitoring systems are reducing spoilage rates in craft brewing operations. Danish and Czech microbreweries report improved batch consistency.
Market Restraints
- Barley and grape supply concentration:Ukrainian grain disruptions and Rhône Valley frost cycles expose input vulnerabilities. Sourcing managers face margin compression from agricultural commodity volatility.
- Excise duty fragmentation:National alcohol taxation frameworks create cross-border arbitrage complexity. Irish and Finnish spirits producers encounter distribution friction from divergent ad valorem structures.
- Low-alcohol substitution:Functional beverages and zero-ABV alternatives capture occasion-based consumption. Traditional lager volumes face displacement in weekday drinking segments.
Strategic Opportunities
- Eastern European craft penetration:Poland and Romania exhibit underdeveloped independent brewery density relative to Western benchmarks. First-mover brands can establish taproom networks before market saturation.
- Digital direct-to-consumer channels:Specialized subscription platforms bypass three-tier distribution constraints. French champagne houses and Scottish distillers are piloting blockchain-verified provenance sales.
- CSRD-aligned reporting:Mandatory sustainability disclosure creates competitive differentiation for early adopters. Integrated carbon-footprint labeling attracts ESG-mandated institutional buyers.
Industry Challenges
- Master distiller and brewmaster scarcity:Specialized fermentation expertise commands premium compensation. Training pipeline gaps constrain quality-controlled expansion for mid-sized producers.
- Legacy equipment retrofit costs:Water recovery and energy-efficiency upgrades demand seven-figure capital deployment. Family-owned distilleries face financing constraints against private-equity-backed competitors.
- Organic certification timelines:Three-year conversion periods delay revenue recognition for vineyard transitions. Spanish sherry producers risk market share erosion during qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alcoholic Beverage Market |
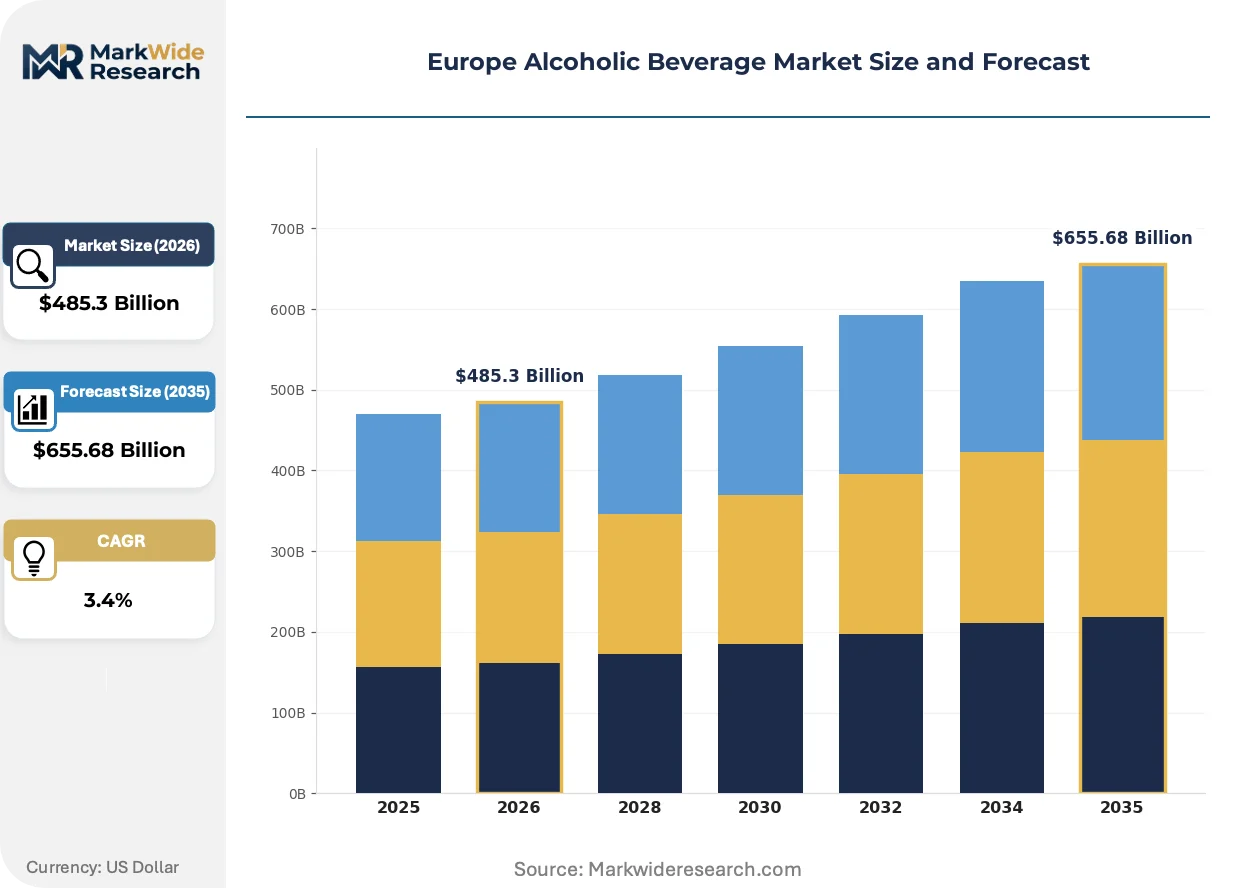
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $655.68 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider End User: Bars, Restaurants, Retailers, Online Retail Flavor Profile: Sweet, Bitter, Spicy, Fruity Packaging Type: Bottles, Cans, Kegs, Boxes |
| Companies Covered | Pernod Ricard, Bacardi Limited, Anheuser-Busch InBev, LVMH Moet Hennessy Louis Vuitton SE, Molson Coors Beverage Company, Heineken Holding NV, Carlsberg Breweries A/S, Asahi Group Holdings, Ltd., Diageo Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alcoholic Beverage Market Shifts & Advancements
Active fermentation control and alternative substrate processing are compressing traditional maturation cycles. Regulatory disclosure requirements and consumer transparency demands are simultaneously reshaping competitive positioning.
Precision bioreactor systems are hybridizing conventional barrel-aging with accelerated oak extraction and micro-oxygenation. Scottish and Irish whisky distillers deploy these hybrid installations to shorten time-to-market for premium expressions. The technology compresses inventory carrying costs while preserving sensory complexity benchmarks.
EMA guidelines on health claims and EU-wide alcohol labeling mandates are tightening permissible marketing language. Producers must reformulate packaging graphics and abandon certain lifestyle associations. Wine exporters to Nordic markets face the strictest interpretation thresholds, forcing portfolio-specific label runs.
Experiential retail and tasting-room direct sales are displacing traditional wholesale dependence for craft producers. Belgian farmhouse breweries and English vineyard estates invest in hospitality infrastructure to capture full margin. This channel pivot is most visible in rural tourism corridors of Tuscany, Bordeaux, and the Douro Valley.
Europe Alcoholic Beverage Market Segmentation
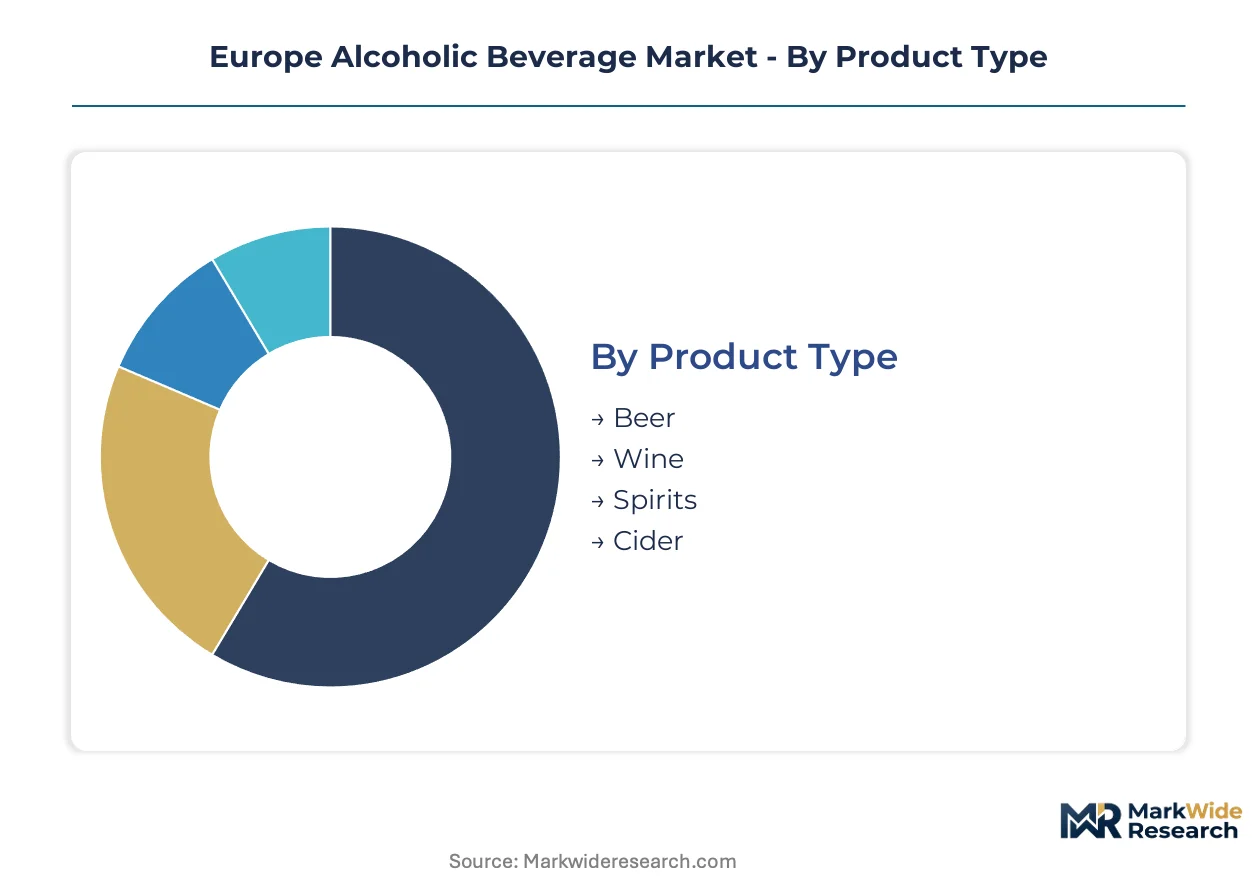
Segmentation reveals divergent growth mechanics across Europe's alcoholic beverage landscape. Product maturity varies dramatically by category, while channel and format preferences reshape profit pool distribution. Understanding these fault lines enables targeted resource allocation against shifting consumption occasions.
Product Type:
Maturity spreads across a wide spectrum, from centuries-old traditions to emerging craft revivals. Volume concentration and margin structure diverge sharply by category.
- Beer:Fermented malt beverages spanning lager, ale, and wheat styles, typically 4-6% ABV. German brewmasters and Czech pilsner traditions anchor continental volume, though craft microbreweries in Denmark and Poland are capturing premium occasions through experimental hop profiles and localized taproom experiences.
- Wine:Fermented grape products ranging from light sparkling to fortified dessert styles. Italian cooperatives and Spanish sherry houses dominate supply, yet regulatory pressure from EU Farm to Fork sustainability mandates is accelerating regenerative viticulture transitions across Rhône and Douro Valley estates.
- Spirits:Distilled ethanol products including whisky, gin, vodka, and cognac. Heritage distillers leverage controlled fermentation technologies to compress maturation cycles.
- Cider:Fermented apple or pear-based beverages, traditionally stronger in British and Norman markets. English orchard estates and Breton producers are expanding flavored variants.
Beer retains volume leadership; spirits hold the steepest expansion curve through premiumization.
End User:
Channel economics stratify sharply between experiential consumption and convenience purchasing. Margin capture and brand-building potential vary by access point.
- Bars:On-trade establishments specializing in cocktail craft and draft service. Berlin mixology venues and Lisbon gin palaces are elevating single-malt allocations, creating high-margin discovery occasions for heritage distillers.
- Restaurants:Food-paired beverage service across casual and fine-dining tiers. Tuscan vineyard estates and Bordeaux châteaux are embedding direct hospitality infrastructure to capture full margin through tasting-room conversions.
- Retailers:Supermarkets and specialty stores controlling shelf placement and promotional velocity. Dutch and German chains are prioritizing early sustainability certification holders under EU Green Deal procurement guidelines.
- Online Retail:Digital direct-to-consumer platforms bypassing traditional three-tier constraints. French champagne houses pilot blockchain-verified provenance sales through specialized subscription channels.
Retailers maintain volume throughput; online retail is climbing the fastest as regulatory frameworks adapt to digital taxation.
Flavor Profile:
Consumer palates are fragmenting across demographic cohorts, with occasion-based preferences driving formulation innovation. Traditional taste hierarchies face disruption from experimental profiles.
- Sweet:Sugar-forward formulations including dessert wines, liqueurs, and flavored spirits. Italian amaro producers and Belgian fruit beer brewers target younger demographics.
- Bitter:Hop-dominant beers, amaro, and dry vermouth styles. Craft brewing operations in the Czech Republic deploy precision yeast strains to achieve consistent bitterness thresholds.
- Spicy:Botanical-infused gins, peppery rye whiskies, and seasoned ciders. Scottish distillers experiment with hybrid bioreactor systems to accelerate oak extraction.
- Fruity:Berry-forward wines, citrus gins, and orchard fruit ciders. English vineyard estates invest in hospitality infrastructure to capture rural tourism corridors.
Bitter profiles dominate mature markets; fruity formulations are gaining share fastest among entry-level consumers.
Packaging Type:
Format selection increasingly reflects sustainability mandates and occasion portability rather than tradition alone. Material innovation and supply chain resilience factor into sourcing decisions.
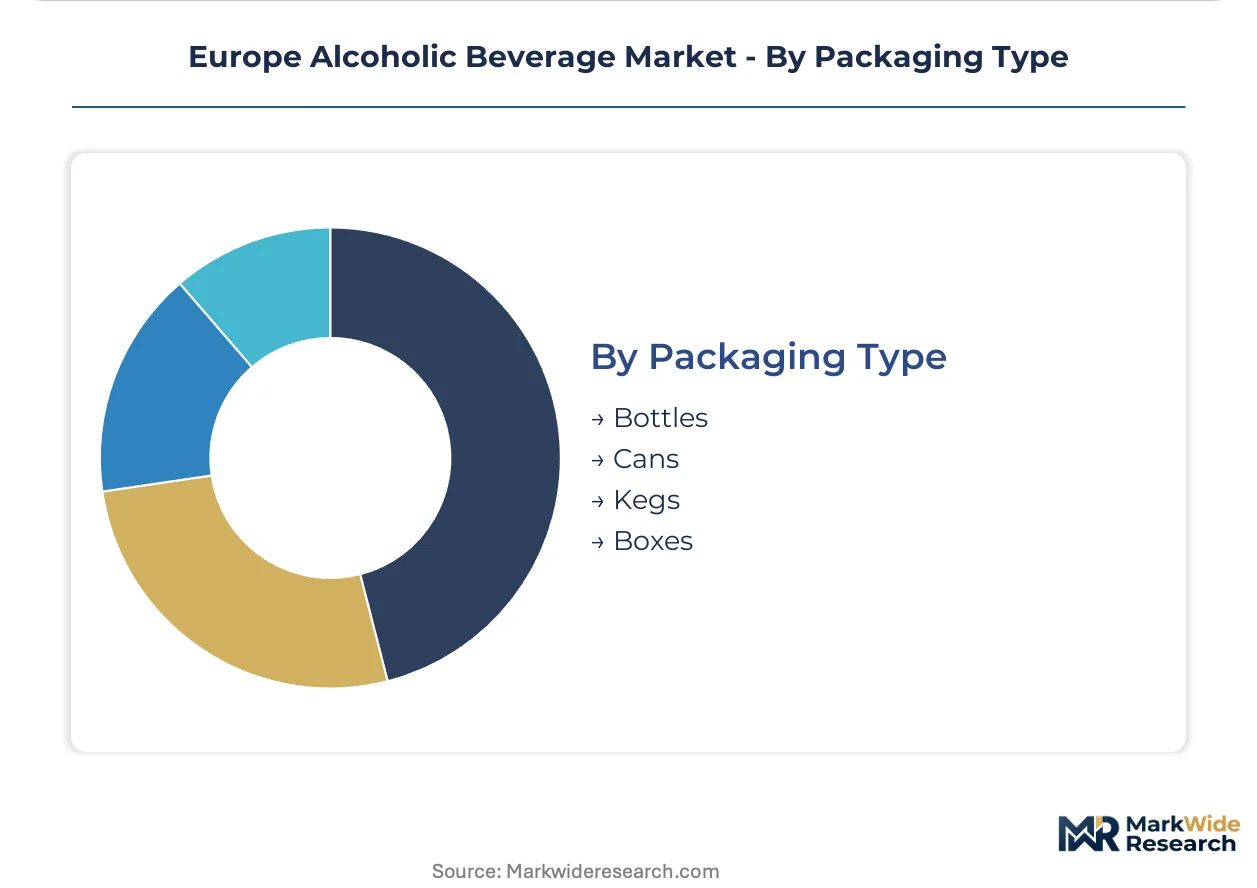
- Bottles:Glass containers dominating wine and premium spirits presentation. REACH compliance costs now extend to packaging substrates, forcing reformulation investments across Spanish and Italian cooperatives.
- Cans:Aluminum formats capturing craft beer and ready-to-drink expansion. Danish microbreweries report improved batch consistency with controlled fermentation technologies.
- Kegs:Stainless steel and disposable formats for on-trade draft service. Irish and Finnish producers face distribution friction from divergent excise structures affecting returnable container logistics.
- Boxes:Bag-in-box systems for volume wine and casual consumption. ESG-mandated institutional buyers favor integrated carbon-footprint labeling in this format.
Bottles command premium positioning; cans are expanding most quickly through portability and recycling efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance and EU Green Deal mandates anchor strategic positioning across German brewing and French distillation corridors. National excise frameworks fragment cross-border arbitrage opportunities.
Germany
Craft brewing density in Bavaria and North Rhine-Westphalia drives experimental hop procurement. The Federal Ministry of Food and Agriculture enforces strict purity law interpretations under the Biergesetz. Berlin mixology venues elevate single-malt allocations, creating high-margin discovery occasions for heritage distillers.
France
Champagne houses and Cognac distillers pilot blockchain-verified provenance sales through direct subscription channels. ANSM labeling mandates restrict permissible marketing language on lifestyle associations. Bordeaux châteaux embed hospitality infrastructure to capture full margin through tasting-room conversions.
United Kingdom
Scottish whisky distillers deploy hybrid bioreactor systems to compress maturation cycles while preserving sensory benchmarks. HMRC excise structures create friction for cross-border arbitrage with Irish producers. English vineyard estates in Kent and Sussex expand rural tourism corridors through experiential retail investments.
Spain
Sherry triangle capacity build-out fragments traditional supply networks across Andalusia. Ministry of Agriculture fisheries and food regulations enforce EU Farm to Fork sustainability transitions. Jerez cooperatives face market share erosion during three-year organic certification conversion windows.
Italy
Rhône Valley and Douro Valley estates accelerate regenerative viticulture adoption under sustainability mandates. EFSA interpretation thresholds force portfolio-specific label runs for Nordic market exports. Tuscan farmhouse breweries invest in hospitality infrastructure to displace wholesale dependence.
Europe Alcoholic Beverage Market Competitive Landscape
Heritage conglomerates and craft specialists split the market across volume and value vectors. Consolidation concentrates in spirits and brewing while fragmentation persists in regional wine cooperatives. Two archetypes dominate: integrated beverage multinationals controlling distribution infrastructure, and terroir-focused estates leveraging direct-to-consumer channels. Competitive moves center on portfolio diversification into low-alcohol alternatives and backward integration into agricultural supply.
Within the integrated multinational tier, Pernod Ricard and Diageo Plc exemplify archetype positioning through heritage distillation infrastructure and specialized brand architecture. Heineken Holding NV anchors lager volume control through managed distribution networks. These entities represent scale-driven consolidation patterns across European beverage manufacturing.
| Leading Market Players |
|---|
| Pernod Ricard |
| Bacardi Limited |
| Anheuser-Busch InBev |
| LVMH Moet Hennessy Louis Vuitton SE |
| Molson Coors Beverage Company |
| Heineken Holding NV |
| Carlsberg Breweries A/S |
| Asahi Group Holdings, Ltd. |
| Diageo Plc |
| Others |
Supply & Pricing Matrix
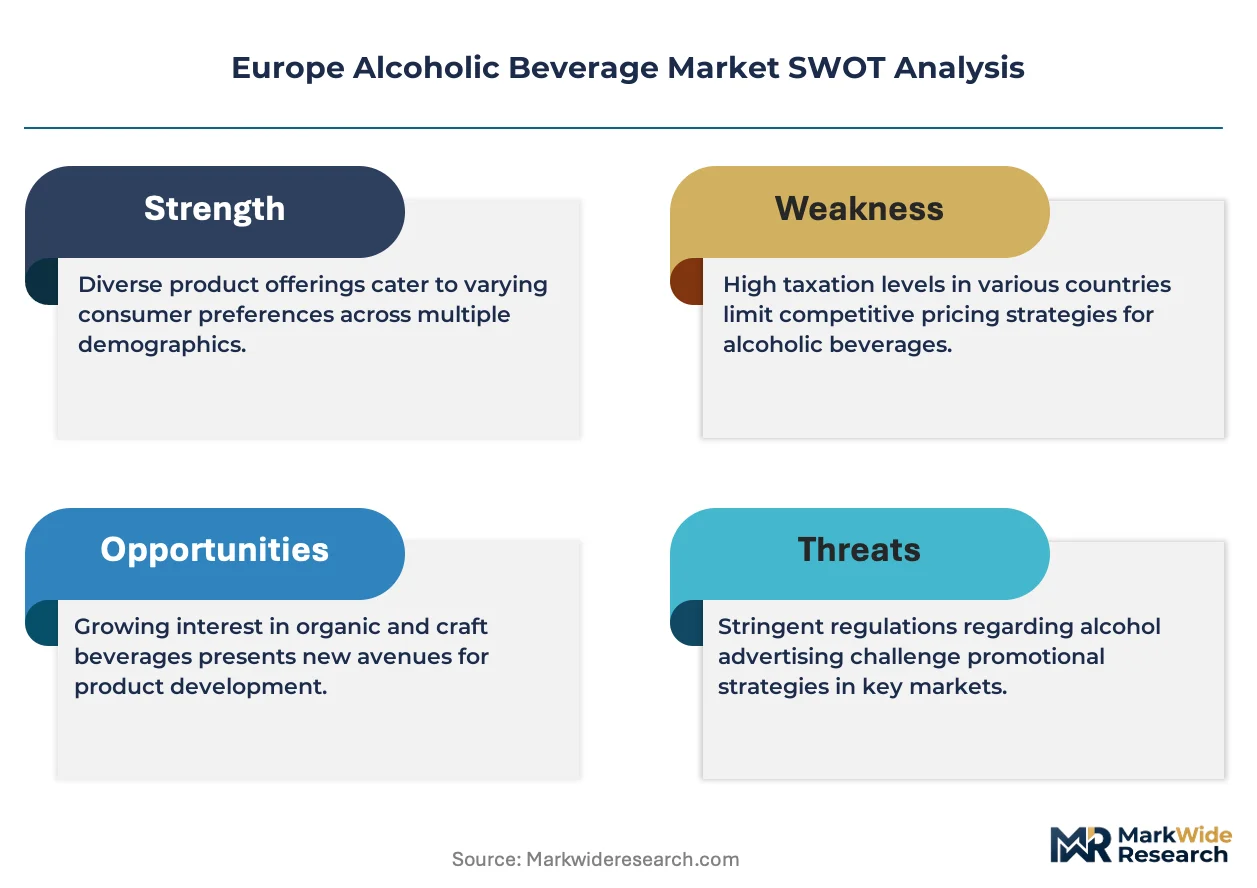
Jerez de la Frontera's sherry triangle capacity expansion is compressing margins for traditional cooperatives while elevating pricing power for early sustainability certifiers in Northern European retail channels.
Pricing Analysis
Cross-border price spreads between German retail chains and Spanish cooperatives reflect divergent excise structures and sustainability premium capture. Three-tier pricing structure across heritage reserve, estate-bottled, and cooperative bulk levels separates cognac houses from regional brandy distillers from commodity ethanol blenders. Pricing pressure stems from Ukrainian grain input volatility and REACH compliance cost pass-through requirements. Volume buyers in Dutch supermarket chains exhibit highest price sensitivity; heritage distillers with controlled allocation programs show lowest.
Supply Chain Analysis
Extended payment terms from French champagne houses to Burgundy vineyard subcontractors are straining working capital across cooperative networks. Agricultural input concentration rests on Ukrainian barley, French wheat, and Spanish grape must as primary fermentation substrates. Single-source vulnerability runs through Rhône Valley cooperatives dependent on frost-exposed vintage output. Distribution runs through controlled three-tier systems in Germany and France, direct-to-consumer hospitality in Italy and Spain, and emerging digital subscription platforms in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's alcoholic beverage market rewards service-attach strategies where experiential hospitality and subscription provenance verification expand recurring revenue faster than core liquid production.
For Market Incumbents: Build certification moats around EU Farm to Fork compliance and blockchain-verified origin tracking to defend against Polish and Romanian craft entrants. Secure backward integration into regenerative viticulture and precision fermentation technology to capture margin from input volatility. Channel control through owned hospitality infrastructure in Tuscany and Bordeaux creates pricing power independent of wholesale negotiation. For New Entrants and Emerging Players: Romania's underdeveloped independent brewery density relative to Czech benchmarks offers first-mover taproom network establishment before saturation. Target Polish craft beer subscription platforms and English vineyard estate hospitality conversions as penetrable white-space. Go-to-market through direct digital provenance sales bypasses three-tier distribution constraints that burden legacy players. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because EU Green Deal mandates and CSRD disclosure requirements are structurally advantaging early certifiers with integrated carbon-footprint labeling. Acquisition targets include mid-sized cooperatives with conversion-ready vineyard assets and distressed distilleries with heritage equipment suitable for bioreactor retrofit. Signal to monitor: acceleration of excise harmonization debates that would compress cross-border arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Investment | EU Farm to Fork compliance secures preferential listing in Dutch and German retail procurement. |
| Direct-to-Consumer Channel Launch | Bordeaux châteaux and Scottish distillers bypass three-tier margin extraction through subscription platforms. |
| Precision Fermentation Technology Deployment | Danish microbreweries achieve batch consistency that supports premium pricing in Berlin mixology venues. |
| Hospitality Infrastructure Expansion | Tuscan farmhouse breweries capture full margin through rural tourism corridor tasting-room conversions. |
| Regenerative Viticulture Transition | Rhône Valley estates meet ESG-mandated institutional buyer requirements for integrated carbon labeling. |
Research Methodology
Operator-level perspectives from master distillers, vineyard estate managers, retail category buyers, and on-trade procurement directors anchored the qualitative base. Primary fieldwork combined with secondary validation from EMA guideline filings, EU Green Deal implementation documents, national excise framework records, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Scenario-bracketing around regulatory acceleration and input cost volatility framed the projection horizon. Segmentation dimensions spanned product type, end-user channel, flavor profile, and packaging format across the modeling period. CAGRs derived from historical trajectory analysis adjusted for sustainability mandate implementation timelines and digital channel penetration curves. Forecast inputs incorporated barley and grape commodity price bands alongside excise harmonization probability assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed consolidators or platform-native digital entrants would shift outcomes. Macroeconomic deviation, regulatory fragmentation intensification, or breakthrough fermentation technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market