
 Europe Bottled Water Processing Market | 2026-2036
Europe Bottled Water Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bottled Water Processing Market Insights
Foodservice and hospitality procurement of premium bottled water is expanding across European metropolitan centers. Nestlé leverages its mineral water portfolio depth to anchor supply relationships with hotel chains and institutional buyers. Danone competes through specialized glass bottling lines that serve restaurant-tier accounts. GEA Group Aktiengesellschaft sustains equipment contracts with mid-sized regional processors seeking automated filling and capping upgrades.
Europe bottled water processing encompasses filtration, purification, mineralization, carbonation, and aseptic packaging operations that transform raw water into retail-ready beverages meeting potable and organoleptic standards. Reverse osmosis and ultraviolet sterilization systems typically reduce total dissolved solids below 500 ppm while preserving desired mineral profiles for natural spring claims. Still mineral water occupies the largest volume share as established brands defend shelf space in supermarkets and convenience stores. Sparkling water leads growth velocity as younger consumers in urban markets substitute carbonated variants for sugary soft drinks. Plastic bottles retain dominant packaging economics, though regulatory pressure on single-use polymers is redirecting capital toward rPET lines and alternative formats.
EFSA sets maximum contaminant thresholds and labeling requirements that processors must satisfy for market access across EU member states. REACH and the EU Green Deal constrain polymer inputs and mandate recycled content minimums that reshape packaging procurement decisions. National regulators in France, Germany, and Italy enforce origin-protected designations that limit sourcing geography and protect terroir-linked brands. Stakeholders must monitor evolving extended producer responsibility fees and deposit-return scheme expansions that will alter cost structures and format preferences before the forecast horizon closes.
Market Dynamics
REACH compliance deadlines and the EU Green Deal are compressing packaging procurement cycles across European bottling operations, forcing processors to requalify polymer inputs and retrofit lines for recycled content minimums ahead of enforcement milestones.
Growth Catalysts
- Deposit-return scheme expansion:Germany's DPG system and France's Citeo program are expanding collection infrastructure, creating guaranteed feedstock pipelines for rPET bottling lines.
- Carbonation technology:Precision CO2 injection systems enable processors to produce sparkling variants with mineral profiles matching natural sources, capturing substitution demand from soft drinks.
- Foodservice channel recovery:Premium hospitality procurement in Milan, Paris, and Barcelona is rebuilding pre-pandemic volumes for glass-bottled mineral water.
Market Restraints
- rPET supply concentration:European food-grade recycled polymer capacity clusters in Germany and Italy, exposing processors in peripheral markets to allocation risk and transport cost premiums.
- Natural spring designation limits:France's AOC and Italy's denominazione d'origine restrict sourcing geography for protected brands, constraining volume scaling for terroir-linked portfolios.
- Energy cost volatility:Bottling line sterilization and compressed air systems consume substantial electricity, making mid-sized processors vulnerable to continental grid price spikes.
Strategic Opportunities
- Central and Eastern Europe whitespace:Poland and Romania show underdeveloped per-capita consumption relative to Western benchmarks, with distribution infrastructure now reaching viability thresholds.
- Aseptic carton formats:SIG Combibloc and Tetra Pak barrier technologies are penetrating ambient-stable water segments previously dominated by PET, opening shelf-stable logistics.
- EFSA novel mineral claims:Approved health-related hydration positioning creates differentiation space for functional water variants with added electrolytes or magnesium.
Industry Challenges
- Automation engineering scarcity:Bottling line integration with MES and track-and-trace systems requires controls specialists in short supply across European industrial regions.
- Extended producer responsibility fees:France's Citeo and Italy's CONAI are recalibrating fee structures annually, complicating multi-year contract pricing for private-label processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bottled Water Processing Market |
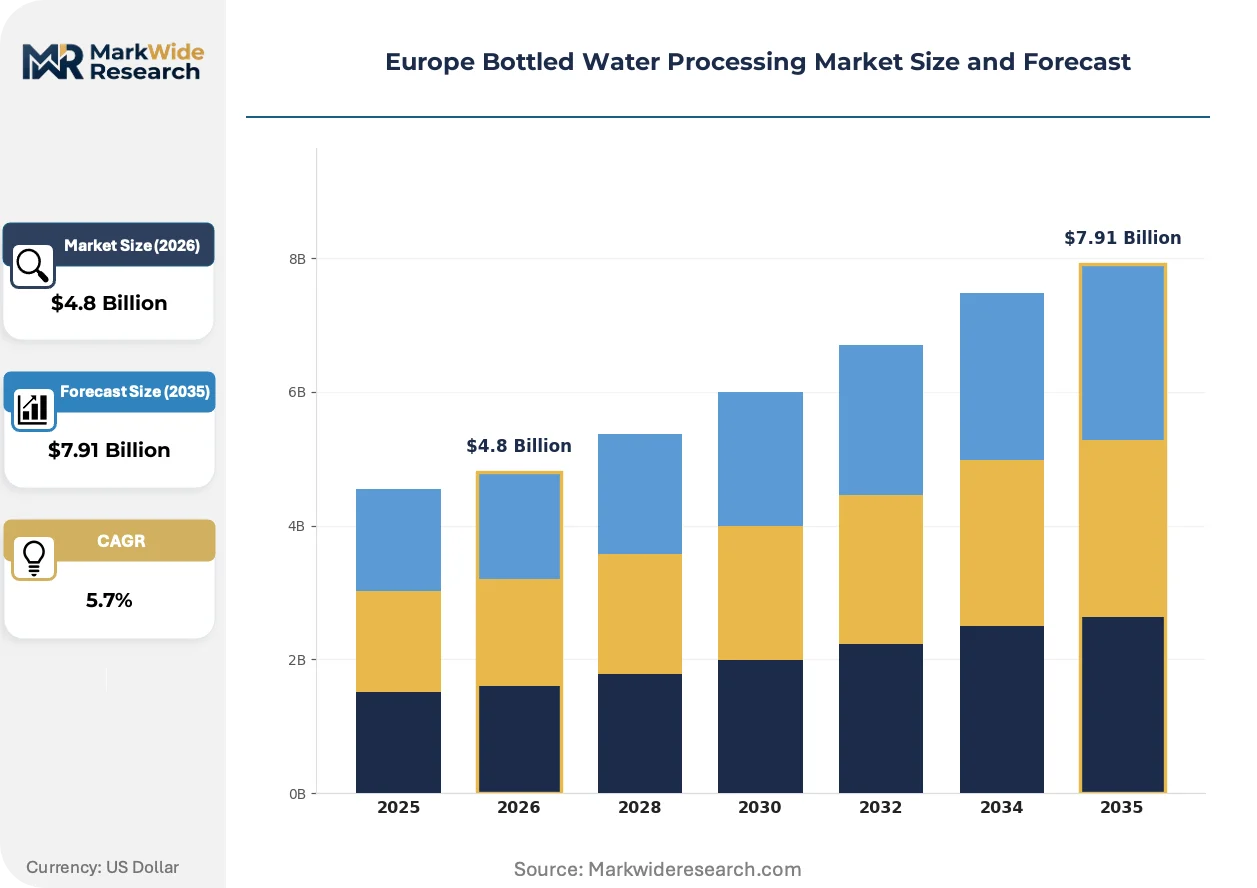
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Sparkling Water, Mineral Water, Flavored Water Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Retail Customers, Restaurants, Beverage Manufacturers, Fitness Centers |
| Companies Covered | Nestlé, Danone, The Coca-Cola Company, PepsiCo, Gerolsteiner Brunnen, Dow Chemical Company, Pall Corporation, GEA Group Aktiengesellschaft, Alfa Laval, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bottled Water Processing Market Trends and Innovations
Processing equipment and packaging materials are undergoing simultaneous transformation as regulatory pressure on polymer circularity intersects with precision manufacturing capabilities.
Membrane filtration is converging with real-time mineral monitoring sensors to enable dynamic adjustment of total dissolved solids during spring water processing. Mid-sized German and Italian processors are retrofitting existing lines with this capability to defend natural mineral claims while maintaining throughput. The technology is compressing the distinction between protected spring sourcing and controlled mineralization, enabling processors to replicate terroir-linked profiles from diverse feedstocks.
The EU Green Deal's packaging and packaging waste regulation revision is mandating recycled content minimums that escalate through the forecast period. This is forcing processors to requalify rPET suppliers and validate food-contact compliance documentation at unprecedented granularity. Sparkling water segments face particular pressure as colored and opaque bottles complicate optical sorting and decontamination protocols.
Urban foodservice buyers are consolidating procurement through specialized beverage distributors rather than direct relationships with individual bottlers. Paris and London restaurant groups now specify carbonation intensity, glass weight, and label substrate through centralized tendering platforms. This behavior is compressing margin structures for smaller regional processors unable to meet consolidated volume and specification requirements.
Europe Bottled Water Processing Market Segmentation
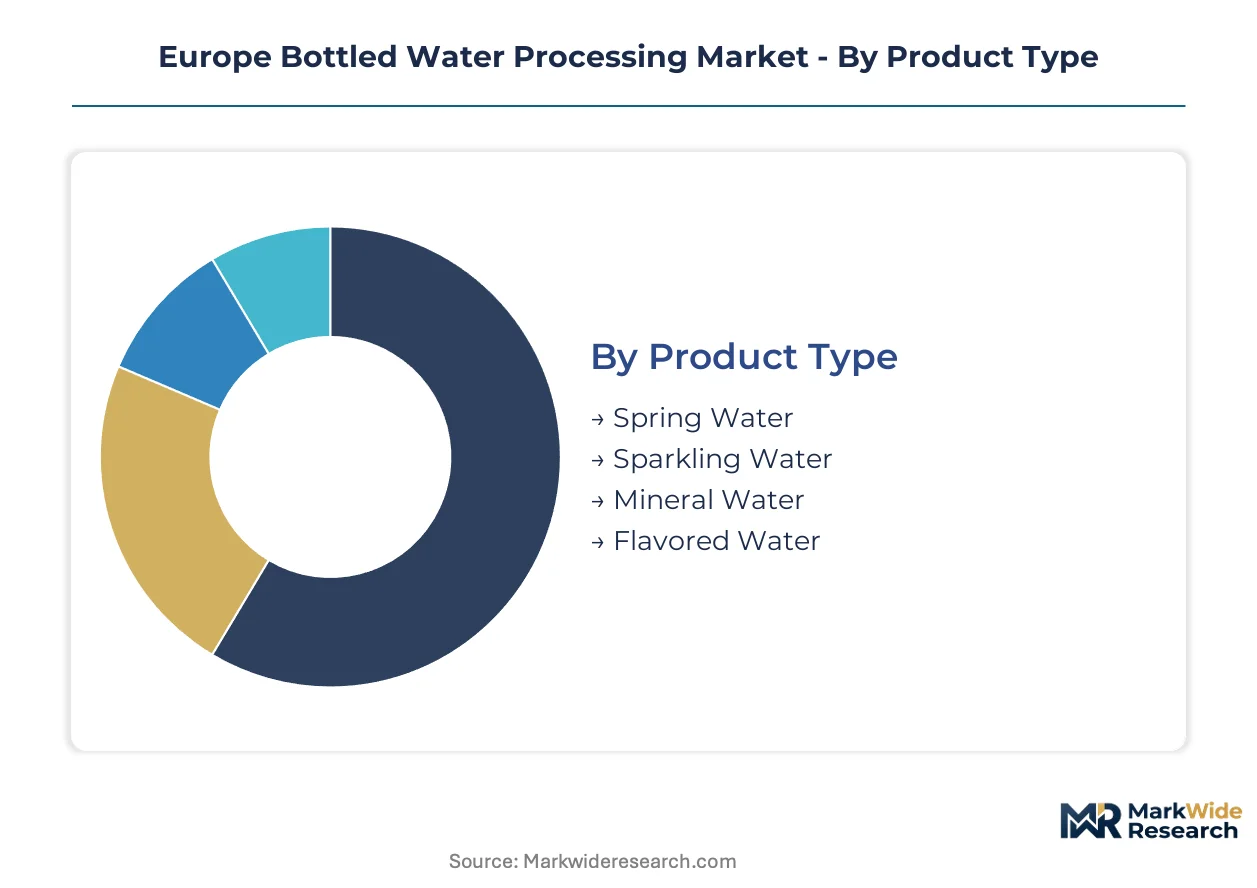
Europe's bottled water processing market fragments across product chemistry, packaging material, route-to-market, and end-user sophistication. Each dimension shapes capital deployment decisions for filtration infrastructure, line automation, and regulatory compliance investments.
Product Type:
Buyers differentiate by mineral composition claims and carbonation intensity, which dictate processing complexity and margin capture.
- Mineral Water:Naturally sourced from protected underground reservoirs with stable mineral profiles requiring minimal post-extraction treatment. German and Italian processors dominate volume through origin-protected designations that command retail shelf premiums and defend against commoditization.
- Sparkling Water:Precision carbonation systems inject food-grade CO2 to replicate natural effervescence or create controlled bubble structures. Urban foodservice accounts in Paris, Barcelona, and Milan specify carbonation intensity levels through centralized procurement platforms, compressing margin structures for smaller regional bottlers unable to meet consolidated volume requirements.
- Spring Water:Sourced from surface springs with variable mineral content requiring real-time TDS monitoring and dynamic filtration adjustment. REACH compliance documentation demands exhaustive contaminant testing for each source batch.
- Flavored Water:Incorporates natural extracts or essences post-sterilization, requiring aseptic blending capabilities and extended shelf-life validation under EFSA additive thresholds.
Mineral water leads volumes today; sparkling water is gaining share fastest.
Packaging Type:
Procurement cycles compress as EU Green Deal mandates force rapid requalification of recycled content sources and line retrofits.
- Plastic Bottles:rPET lines dominate new capital deployment as Germany's DPG and France's Citeo deposit-return schemes guarantee feedstock pipelines. Optical sorting complexity rises with colored and opaque variants favored by sparkling water brands.
- Glass Bottles:Premium hospitality channels in Milan, Paris, and London specify glass weight and label substrate through tendering platforms. Danone operates specialized glass lines serving restaurant-tier accounts with customized carbonation and mineral profiles.
- Cartons:SIG Combibloc and Tetra Pak barrier technologies penetrate ambient-stable segments previously PET-dominated, enabling shelf-stable logistics for private-label processors.
- Pouches:Flexible formats target fitness and on-the-go consumption with lower transport cost profiles, though EFSA food-contact compliance documentation requirements slow adoption for mainstream retail.
Plastic bottles retain volume leadership; cartons are climbing the fastest.
Distribution Channel:
Channel selection determines batch size requirements, label customization depth, and promotional spend allocation.
- Supermarkets:High-volume, low-margin throughput demanding automated palletizing and traceability systems integrated with retailer EDI platforms. German discounters and French hypermarkets drive standardization of bottle formats and cap geometries.
- HoReCa:Hotel and restaurant procurement consolidates through specialized beverage distributors specifying carbonation intensity, glass specifications, and delivery frequency. Nestlé anchors supply relationships with European hotel chains through portfolio breadth and logistics reliability.
- Convenience Stores:Smaller format, higher turnover velocity requiring compact case configurations and promotional multipacks suited to urban foot traffic patterns.
- Online Retail:Direct-to-consumer and platform sales demand damage-resistant packaging and consolidated last-mile logistics partnerships with temperature-controlled capabilities.
Supermarkets lead volumes today; HoReCa is expanding most quickly.
End User:
User sophistication shapes processing certification requirements and contract pricing structures.
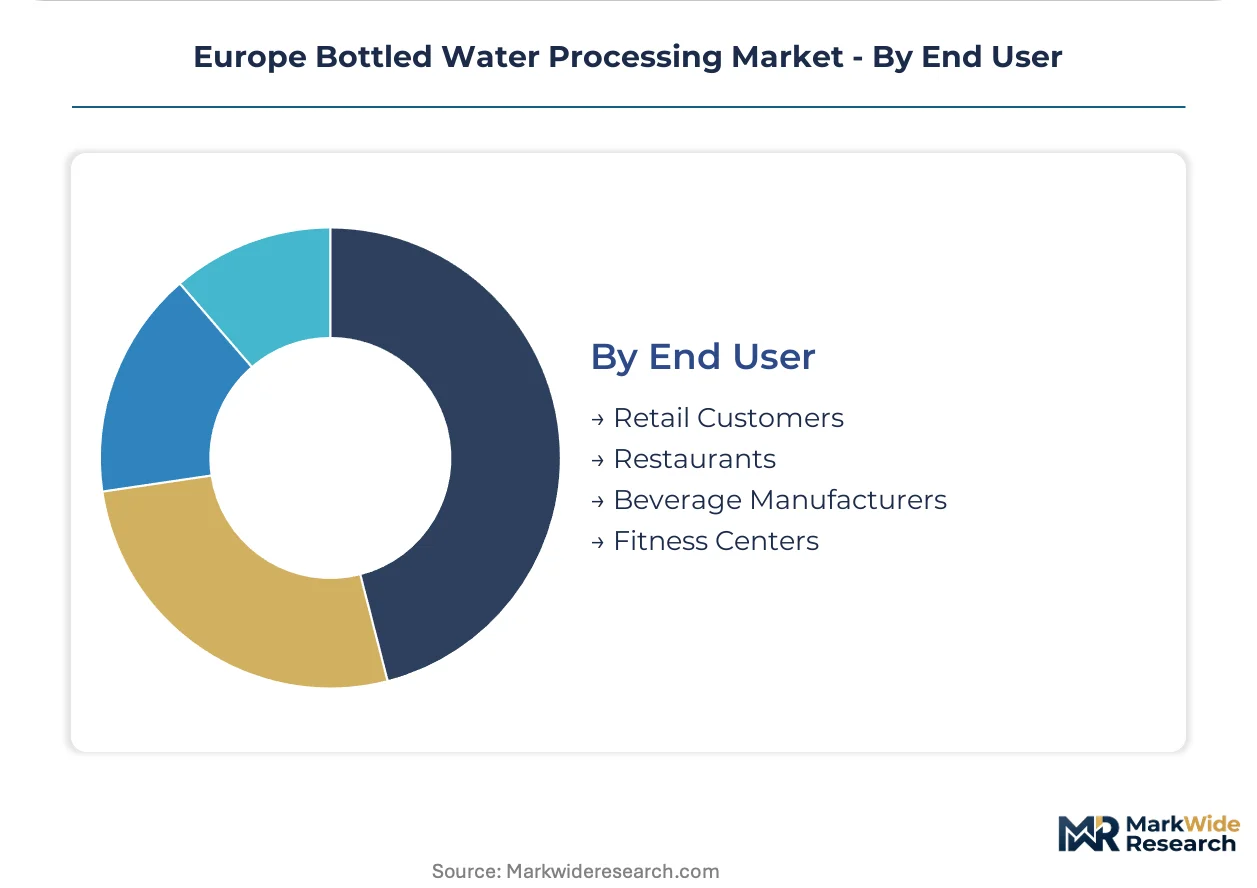
- Retail Customers:Mass-market consumption driving economies of scale in filtration and bottling line utilization. EFSA labeling requirements and extended producer responsibility fees recalibrate annually, complicating multi-year contract pricing.
- Restaurants:Premium positioning demands glass formats, customized mineral profiles, and sommelier-trained staff education on terroir-linked sourcing narratives.
- Beverage Manufacturers:Private-label and co-packing contracts requiring flexible line changeover capabilities and rapid formulation adjustment for seasonal variants.
- Fitness Centers:Functional water with added electrolytes or magnesium targeting hydration positioning approved under EFSA novel mineral claims frameworks.
Retail customers dominate volumes today; fitness centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity is migrating toward jurisdictions with established deposit-return infrastructure and lower EPR fee volatility, creating compliance-arbitrage opportunities for mid-sized bottlers seeking feedstock security.
Germany
DPG deposit-return guarantees rPET feedstock pipelines for bottlers in Rhineland-Palatinate and Bavaria. REACH enforcement timelines compress polymer requalification cycles, forcing processors to pre-validate alternative suppliers. The Munich-Stuttgart corridor hosts automated line retrofit specialists serving mineral water origin-protected brands.
France
AOC designation restrictions limit sourcing geography for terroir-linked portfolios in the Massif Central and Vosges. Citeo EPR fee recalibrations complicate multi-year contract pricing for private-label processors. Paris-based hospitality procurement platforms now specify carbonation intensity and glass weight through centralized tendering.
Italy
Denominazione d'origine constraints protect Lombardy and Tuscany spring sources while restricting volume scaling for protected brands. CONAI packaging fee structures shift annually, requiring processors to maintain flexible cost models. The Milan-Bergamo industrial zone concentrates glass bottling lines serving restaurant-tier accounts.
Spain
Per-capita consumption gaps versus Western benchmarks attract capital deployment to Catalonia and Madrid bottling infrastructure. National transposition of EU Green Deal packaging rules lags core markets, creating temporary compliance cost advantages. Barcelona foodservice recovery drives premium glass format demand from hospitality distributors.
Poland
Underdeveloped consumption relative to German benchmarks invites processing infrastructure investment in the Warsaw-Łódź corridor. Limited domestic food-grade rPET capacity exposes bottlers to German and Italian supplier allocation risk. Distribution network expansion into secondary cities now reaches viability thresholds for national brand entry.
Europe Bottled Water Processing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with portfolio breadth anchoring retail relationships and equipment specialization defending foodservice accounts. Market structure tilts toward consolidation at the branded tier while fragmentation persists among regional processors and private-label contractors. Three archetypes dominate: multinational beverage conglomerates with mineral water portfolios, mid-sized origin-protected specialists, and equipment-integrated engineering groups. Competitive moves concentrate on rPET line retrofits and automated filling system upgrades ahead of EU Green Deal enforcement milestones.
Among diversified beverage conglomerates, Nestlé and Danone occupy positions exemplifying portfolio-scale advantages in retail and hospitality procurement respectively. GEA Group Aktiengesellschaft anchors the equipment-integrated tier, representing engineering specialists sustaining automation contracts with regional processors. These three entities illustrate how scale, terroir-linked positioning, and technical integration each defend distinct competitive spaces.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| The Coca-Cola Company |
| PepsiCo |
| Gerolsteiner Brunnen |
| Dow Chemical Company |
| Pall Corporation |
| GEA Group Aktiengesellschaft |
| Alfa Laval |
| Others |
Pricing and Supply Chain Analysis
Hotel and restaurant procurement consolidation across Paris, Milan, and Barcelona dictates three-tier pricing structures across premium, standard, and economy levels, with centralized tendering platforms compressing distributor margins and forcing processors to absorb EPR fee volatility or lose volume.
Pricing Analysis
Distributor margin compression runs through HoReCa channels as beverage consolidators extract volume discounts for carbonation specification and glass weight compliance. Price differentiation hinges on origin-protected designation status and rPET line certification tier. Cost compression in private-label tiers is intensifying because Citeo and CONAI fee recalibrations hit annually. Discounters and hypermarkets show highest price sensitivity; terroir-linked mineral water commands lowest elasticity.
Supply Chain Analysis
Freight cost premiums expose peripheral market bottlers to German and Italian rPET supplier allocation risk, with feedstock pipelines anchored in DPG and Citeo deposit-return infrastructure. Raw material dependencies center on food-grade recycled polymer, CO2 injection systems, and aseptic barrier films. Single-source vulnerability concentrates in optical sorting equipment for colored sparkling water bottles. Distribution runs through specialized beverage distributors serving consolidated hospitality accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion rests on rPET integration cost-down curves and premium-tier hospitality positioning, with processors capturing value from EPR fee arbitrage and carbonation specification premiums.
For Market Incumbents: Cement feedstock security through backward integration into German and Italian rPET collection infrastructure ahead of EU Green Deal enforcement milestones. Anchor HoReCa relationships with logistics reliability and customized mineral profiles that resist distributor consolidation pressure. For New Entrants and Emerging Players: EU Green Deal packaging rules in Spain create a window for compliance-cost-advantaged capacity before national transposition closes. Target Poland and Romania whitespace with aseptic carton formats and fitness-center functional water positioning. Pursue co-packing contracts with beverage manufacturers seeking flexible line changeover capabilities. For Investors and Strategic Acquirers: Beverage conglomerates with mineral water portfolio gaps are the most active acquirer in this space. Mid-sized origin-protected specialists with automated retrofit capabilities offer viable five-to-ten-year holds. Watch rPET food-grade capacity expansion announcements as inflection indicator for processor margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Line Retrofit | EU Green Deal compliance secures market access across EFSA-regulated member states. |
| HoReCa Distribution Partnership | Consolidated procurement platforms in Paris and Milan demand specification flexibility. |
| Origin-Protected Brand Acquisition | AOC and denominazione d'origine status defends against private-label commoditization. |
| Central and Eastern Europe Expansion | Warsaw-Łódź corridor infrastructure reaches viability thresholds for national distribution. |
| Aseptic Carton Format Launch | SIG Combibloc barrier technology opens ambient-stable logistics for private-label processors. |
Research Methodology
Direct dialogue with bottling plant engineers, procurement leads at hospitality distributors, EFSA regulatory affairs specialists, and beverage brand managers grounded qualitative findings in operational reality. Secondary validation drew from EU packaging waste directive filings, CONAI and Citeo fee schedules, SEC 10-K disclosures of listed processors, and customs records of filtration equipment imports. Bottom-up capacity assessments and top-down consumption models triangulated volume estimates.
Segment-level outputs across the analysis window reflect product chemistry, packaging material, distribution channel, and end-user sophistication dimensions. CAGRs derived from trend extrapolation of per-capita consumption patterns, rPET adoption curves, and foodservice channel recovery trajectories. Industry-specific inputs included deposit-return scheme expansion timelines and EFSA novel mineral claim approval pipelines.
Revisions become necessary when EPR fee recalibration exceeds modeled ranges, rPET feedstock allocation disrupts regional supply, or EFSA contaminant thresholds tighten. Forecasts reflect documented assumptions about regulatory enforcement pacing and hospitality procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Europe Coconut Water Market
Beverages
Health Drinks Market
Beverages
Herb Infused Water Market
Beverages
Cold Pressed Juice Market
Beverages
GCC Coconut Water Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Fusion Beverages Market
Beverages
South America Dairy Based Beverages Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Adaptogenic Beverages Market
Beverages
Citrus Water Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Carbonated Beverages Market
Beverages
United States Smoothie Market