
 India Sports Drinks Market | 2026-2036
India Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
India Sports Drinks Market Foresight
FSSAI's Food Safety and Standards (Health Supplements, Nutraceuticals, Foods for Special Dietary Uses, Foods for Special Medical Purpose, Functional Foods and Novel Foods) Regulations is redrawing competitive boundaries for sports drink manufacturers in India. PepsiCo India Holdings leverages its bottling infrastructure and kirana network dominance to sustain volume leadership across North and West India. Coca-Cola India Private Limited anchors its portfolio through the Kinley and Sprite platforms while navigating premiumization via specialized hydration lines. Zydus Wellness differentiates through ayurveda-infused positioning that targets consumers seeking clean-label alternatives to synthetic formulations.
Sports drinks are isotonic or hypotonic beverages formulated with electrolytes—primarily sodium, potassium, and magnesium—alongside carbohydrates at concentrations of 6-8% to accelerate gastric emptying and fluid absorption during physical exertion. Electrolyte drinks occupy the largest volume share due to established consumption rituals among amateur runners and cricketers, while protein shakes represent the fastest-expanding category as whey-isolate formulations gain traction among urban gym members. Distribution through gyms captures the highest margin pool per liter sold, though supermarkets still aggregate the greatest absolute revenue given their geographic reach into tier-three towns.
FSSAI mandates strict permissible ingredient lists and health claim validations that constrain new entrants lacking regulatory affairs capabilities. BIS certification for packaged drinking water used in sports drink bases adds another compliance layer that filters out informal manufacturers. CDSCO oversight applies where products cross into therapeutic or recovery positioning with added vitamins or minerals. Stakeholders must monitor how FSSAI's evolving stance on caffeine and taurine limits reshapes permissible formulations for energy-sports hybrid products.
Market Dynamics
FSSAI's tightened labeling norms for functional beverages are forcing reformulation across India's sports drink landscape. Manufacturers must rebuild supply chains around certified ingredient sourcing while tier-two gym penetration accelerates demand for specialized hydration products.
Growth Catalysts
- Gym infrastructure expansion:Organized fitness centers in tier-two cities like Pune and Jaipur are creating first-time sports drink consumers among novice exercisers seeking electrolyte replenishment.
- FSSAI regulatory clarity:Standardized permissible ingredient lists under FSSAI's 2022 functional foods regulations are professionalizing manufacturing standards and filtering informal competitors from formal retail channels.
- Marathon culture institutionalization:Event organizers in Mumbai and Bengaluru are embedding branded hydration partnerships into race logistics, establishing ritualized consumption patterns among amateur endurance athletes.
Market Restraints
- Input cost volatility:Whey protein isolate and natural flavoring imports face currency fluctuation exposure that compresses margin predictability for protein shake formulations.
- Supply concentration risk:PET bottle and aseptic packaging capacity clusters around Maharashtra and Gujarat, creating geographic vulnerability for brands distributing to eastern and southern markets.
- BIS certification friction:Mandatory Bureau of Indian Standards validation for packaged water bases adds 4-6 month lead times that deter rapid product line extensions.
Strategic Opportunities
- Ayurveda-infused positioning:Clean-label formulations incorporating ashwagandha or tulsi extracts target consumers seeking alternatives to synthetic electrolyte compositions.
- Gym-direct distribution:Captive supply partnerships with fitness chains capture premium margin pools per liter compared to traditional kirana or supermarket channels.
- CDSCO therapeutic crossover:Recovery-positioned drinks with added vitamins and minerals can access medical channel distribution under drug regulator oversight.
Industry Challenges
- Regulatory affairs talent scarcity:FSSAI compliance documentation and health claim validation require specialized personnel that mid-tier manufacturers struggle to recruit.
- Refrigerated last-mile infrastructure:Temperature-controlled distribution to tier-three towns demands capex-heavy cold chain investments that strain working capital.
- Hybrid energy-sports positioning ambiguity:Evolving FSSAI stance on caffeine and taurine limits creates formulation uncertainty for products targeting dual-use consumption occasions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sports Drinks Market |
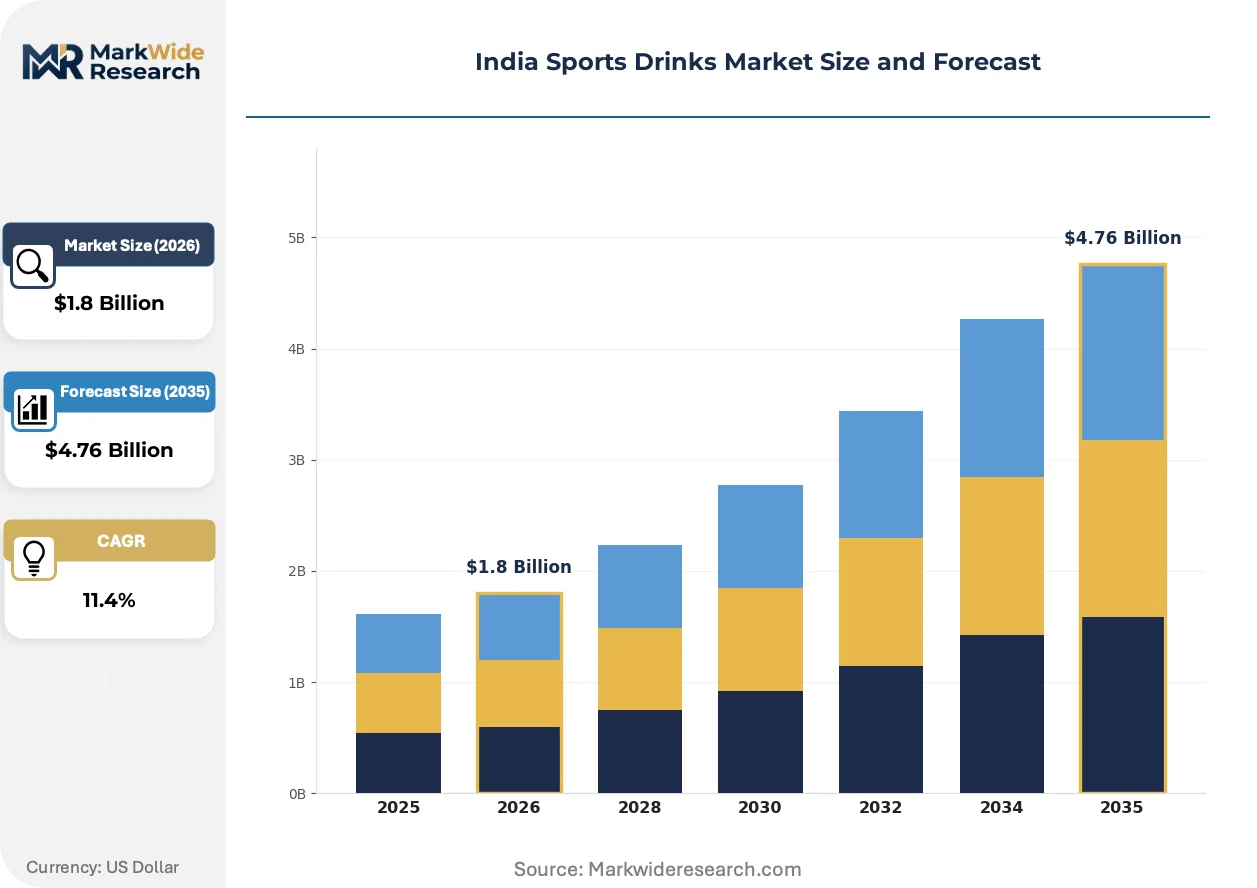
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Drinks, Protein Shakes, Nutrient-Rich Beverages, Herbal Infusions End User: Athletes, Fitness Enthusiasts, Recreational Users, Professionals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Gyms Packaging Type: Bottles, Tetra Packs, Sachets, Cans |
| Companies Covered | FDC Limited, Cipla Limited, PepsiCo India Holdings Pvt. Ltd., Zydus Wellness, Red Bull GmbH, Coca-Cola India Private Limited, Essen Nutrition Corporation, Fast & Up, Gujarat Cooperative Milk Marketing Federation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sports Drinks Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape competitive boundaries in India's functional beverage sector. Three distinct vectors are redefining how hydration products reach and retain consumers.
Electrolyte delivery systems employing micronized mineral suspensions are supplanting traditional sodium-potassium blends in premium formulations. Urban gym members in Delhi and Hyderabad are adopting these advanced compositions at accelerating rates. The technology is compressing differentiation timelines as patent-protected absorption claims become the primary battleground for margin defense.
FSSAI's evolving framework on caffeine thresholds is forcing energy-sports hybrid manufacturers into binary positioning decisions. Products exceeding 145mg per liter face reclassification under separate stimulant beverage regulations. Maharashtra-based formulators are responding by bifurcating portfolios into pure hydration and energy-plus lines to preserve distribution flexibility.
Subscription-based replenishment models are disrupting traditional supermarket purchasing among committed fitness enthusiasts. Digital-native brands are capturing recurring revenue through app-integrated delivery to home and gym locations. Bengaluru and Mumbai exhibit the highest penetration of this behavior shift, with marathon training cohorts driving seasonal subscription spikes.
India Sports Drinks Market Segmentation
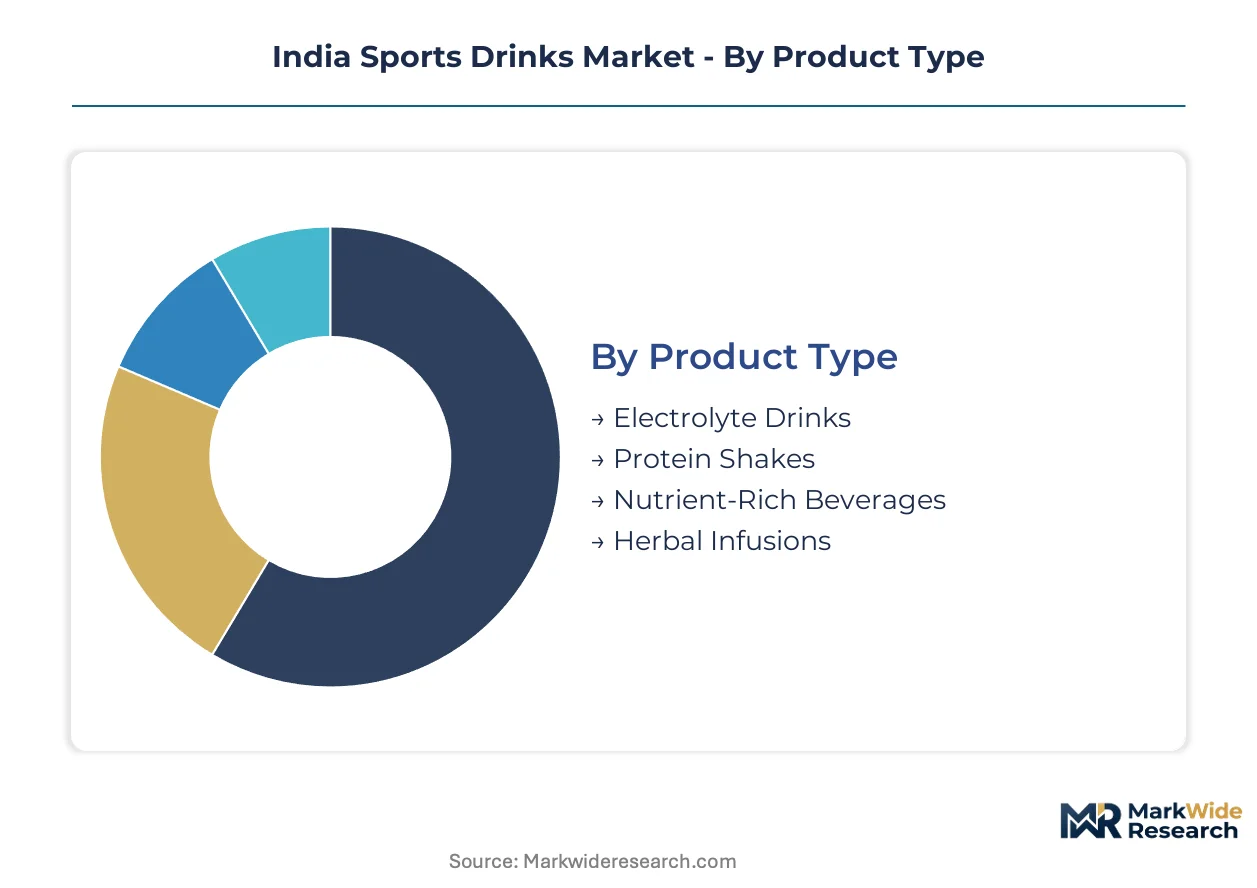
Sports drink segmentation in India reflects divergent margin economics across hydration technologies and channel architectures. Manufacturers optimize portfolio mix around electrolyte density, protein concentration, and direct-to-gym distribution premiums.
Product Type:
Electrolyte formulations command the deepest margin pools due to established BIS certification pathways and kirana network penetration, while protein platforms face input cost volatility from whey isolate import exposure.
- Electrolyte Drinks:Isotonic or hypotonic beverages containing sodium, potassium, and magnesium at 6-8% carbohydrate concentration for gastric emptying acceleration. Amateur cricketers and marathon runners in Maharashtra and Karnataka sustain volume leadership through ritualized pre- and post-event consumption patterns.
- Protein Shakes:Whey-isolate or concentrate-based formulations targeting muscle protein synthesis. Urban gym members in Delhi and Hyderabad are driving category expansion as organized fitness centers proliferate in tier-two cities with specialized recovery positioning.
- Nutrient-Rich Beverages:Vitamin-fortified hydration products requiring CDSCO oversight when therapeutic claims are asserted.
- Herbal Infusions:Ayurveda-positioned alternatives incorporating ashwagandha or tulsi extracts for clean-label differentiation.
Electrolyte Drinks holds installed capacity. Protein Shakes is rotating up the share rankings.
End User:
Customer archetypes stratify sharply by purchase frequency and price elasticity, with committed exercisers generating recurring revenue against occasional buyers.
- Fitness Enthusiasts:Regular gym attendees purchasing 3-4 times weekly through subscription models or gym-direct supply partnerships. Pune and Jaipur fitness center expansions are creating first-time category entrants seeking electrolyte replenishment guidance from trainers.
- Athletes:Competitive runners, cricketers, and endurance participants with event-tied consumption rituals. Mumbai and Bengaluru marathon institutionalization embeds branded hydration into race logistics with seasonal demand spikes.
- Recreational Users:Occasional exercisers purchasing through supermarkets during summer heat waves.
- Professionals:Corporate wellness program participants receiving employer-subsidized hydration products.
Fitness Enthusiasts anchors volume growth. Athletes maintains premium pricing power.
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with captive gym partnerships outperforming mass retail on per-liter profitability.
- Gyms:Direct supply agreements with fitness chains capturing highest margin per liter through exclusive placement and trainer recommendation authority. Temperature-controlled dispensing infrastructure in Delhi-NCR and Mumbai facilities supports premium pricing.
- Supermarkets:Aggregating greatest absolute revenue through geographic reach into tier-three towns despite kirana-level margins. FSSAI-compliant labeling visibility drives trial among first-time purchasers.
- Online Retail:Subscription-based replenishment models disrupting traditional purchasing among committed enthusiasts in Bengaluru and Mumbai.
- Convenience Stores:Impulse-driven single-serve purchases concentrated in urban heat-stress periods.
Supermarkets holds geographic coverage. Gyms is climbing the fastest on margin contribution.
Packaging Type:
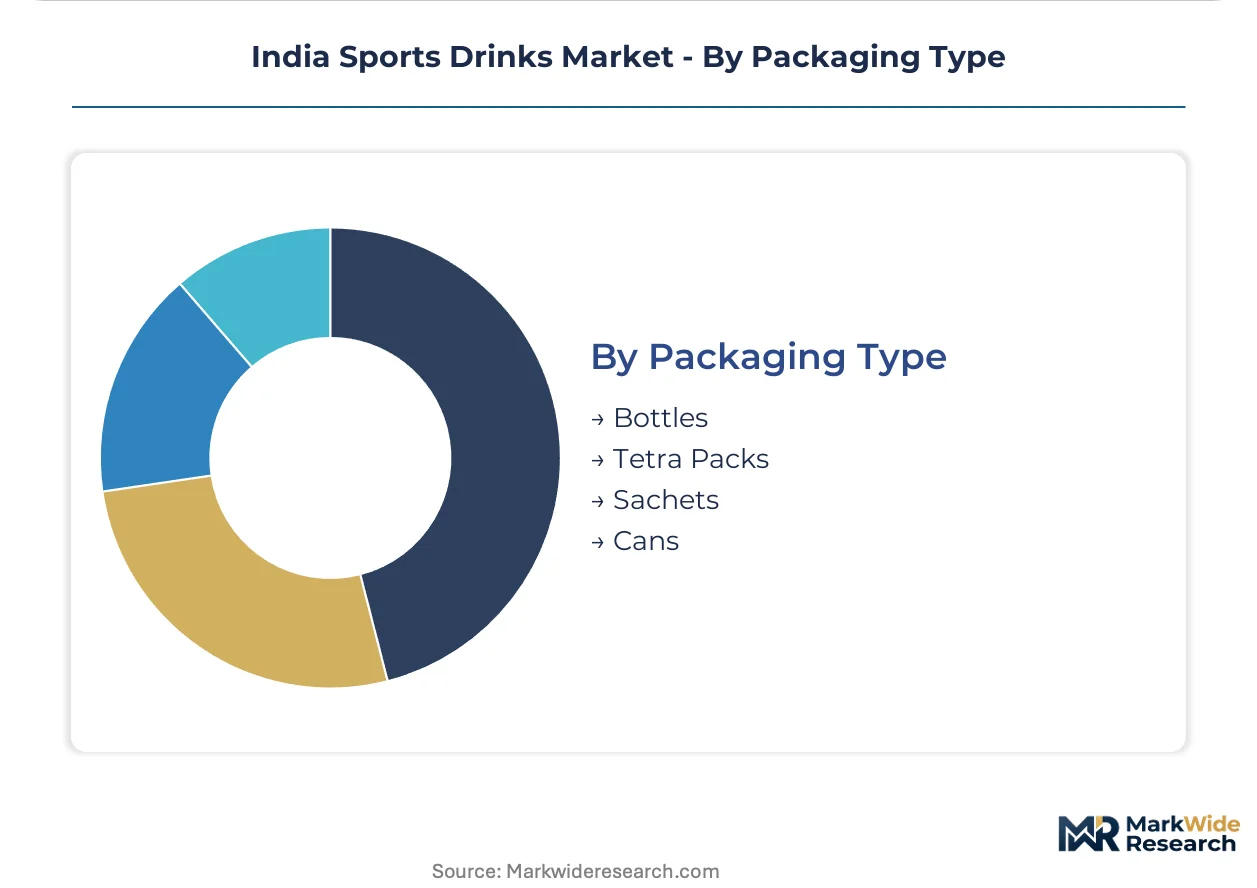
Format selection reflects consumption occasion specificity and cold chain infrastructure availability across eastern and southern distribution corridors.
- Bottles:PET-based standard format for electrolyte drinks with established recycling infrastructure in Maharashtra and Gujarat manufacturing clusters.
- Tetra Packs:Aseptic cartons enabling ambient distribution to tier-three towns lacking refrigerated last-mile capacity.
- Sachets:Powder formats for on-the-go mixing targeting runners and cyclists with weight-minimization priorities.
- Cans:Aluminum formats for premium protein shakes with extended shelf stability.
Bottles holds production scale. Sachets is gaining share fastest among endurance sports participants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts cluster disproportionately in western and southern India where organized gym infrastructure and marathon culture concentrate purchasing power. Tier-two city expansion is redrawing consumption geography as first-time exercisers in Pune and Jaipur enter the category.
Maharashtra
Mumbai's institutionalized marathon culture embeds branded hydration into race logistics with seasonal demand spikes from amateur endurance athletes. FSSAI's 2022 functional foods regulations enforce standardized labeling that professionalizes manufacturing standards statewide. Pune's organized fitness center proliferation creates first-time sports drink consumers seeking electrolyte replenishment guidance from trainers.
Karnataka
Bengaluru's tech workforce sustains premium protein shake adoption through subscription-based replenishment models integrated with gym-direct supply partnerships. BIS certification requirements for packaged water bases filter informal competitors from formal retail channels in the state. The city's marathon institutionalization establishes ritualized consumption patterns among amateur runners.
Delhi-NCR
Urban gym members in Delhi and Gurugram drive accelerating adoption of micronized mineral suspension formulations for enhanced absorption. CDSCO oversight applies to recovery-positioned drinks with added vitamins and minerals crossing into therapeutic claims. Temperature-controlled dispensing infrastructure in NCR facilities supports premium pricing capture.
Gujarat
PET bottle and aseptic packaging capacity clusters around Ahmedabad and Surat, creating supply-side concentration for brands distributing to eastern and southern markets. DGFT import regulations on whey protein isolate expose protein shake formulators to currency fluctuation risk. The state's manufacturing base anchors national production scale for electrolyte drink formats.
Telangana
Hyderabad's expanding organized fitness infrastructure creates demand for specialized hydration products among novice exercisers in tier-two catchments. FSSAI's evolving stance on caffeine thresholds forces energy-sports hybrid manufacturers into binary positioning decisions. The city's pharmaceutical manufacturing heritage supplies regulatory affairs talent for compliance-intensive formulation development.
India Sports Drinks Market Competitive Landscape
Player mix skews toward multinational beverage conglomerates with bottling infrastructure dominance and domestic wellness specialists with ayurveda-infused positioning. Tiered competition separates scale-driven hydration platforms from niche protein recovery formulations. Two strategic archetypes define the landscape: kirana-network volume leaders capturing mass-market electrolyte occasions and gym-direct premium specialists extracting margin through trainer recommendation authority. Dominant competitive moves include portfolio diversification into clean-label alternatives and captive supply partnerships with expanding fitness chains.
Among multinational beverage conglomerates, PepsiCo India Holdings Pvt. Ltd. and Coca-Cola India Private Limited anchor the volume-driven tier through established distribution architecture. Zydus Wellness occupies a distinct position exemplifying the ayurveda-infused specialist archetype targeting consumers seeking alternatives to synthetic formulations. These three companies represent the competitive spectrum from mass-market hydration infrastructure to clean-label wellness positioning.
| Leading Market Players |
|---|
| FDC Limited |
| Cipla Limited |
| PepsiCo India Holdings Pvt. Ltd. |
| Zydus Wellness |
| Red Bull GmbH |
| Coca-Cola India Private Limited |
| Essen Nutrition Corporation |
| Fast & Up |
| Gujarat Cooperative Milk Marketing Federation Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for whey protein isolate lock in supply access and price visibility for protein shake formulators navigating currency fluctuation exposure. These arrangements tether margin predictability to DGFT import regulations while insulating manufacturers from spot market volatility in global dairy derivatives.
Pricing Analysis
Cost-plus contracts with currency indexation dominate whey protein isolate procurement, anchoring protein shake manufacturing costs to USD-INR movements. Three-tier pricing structure across premium micronized formulations, standard electrolyte blends, and economy sachet formats stratifies margin capture by absorption technology tier. Pricing pressure stems from PET resin cost volatility concentrated in Maharashtra and Gujarat manufacturing clusters. Recreational users purchasing through kirana networks exhibit highest price sensitivity, while fitness enthusiasts in gym-direct channels accept premium positioning.
Supply Chain Analysis
Inbound logistics costs from Nhava Sheva port congestion and container availability constraints on Asia-Europe trade lanes compress working capital cycles for flavoring ingredient imports. Supply concentrates in India for electrolyte mineral compounding, China for packaging machinery, and New Zealand for whey protein isolate sourcing. Raw material dependencies span sodium-potassium blends, whey isolate, and natural flavoring extracts. Single-source vulnerability in aseptic carton packaging creates geographic concentration risk for eastern distribution. Distribution runs through kirana networks for volume aggregation and gym-direct partnerships for margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against homemade electrolyte solutions and coconut water positioning among price-sensitive recreational users. This threat intensifies as tier-three town consumers prioritize natural alternatives over synthetic formulations.
For Market Incumbents: Compound trainer recommendation authority through exclusive gym supply partnerships that embed products into fitness rituals. Deepen backward integration into BIS-certified water sourcing to compress certification lead times. Defend against ayurveda-positioned entrants by accelerating clean-label line extensions.
For New Entrants and Emerging Players: Lead with subscription-based replenishment models targeting marathon training cohorts in Bengaluru and Mumbai where consumption ritualization creates recurring revenue stickiness. Penetrate tier-two gym expansions in Pune and Jaipur through trainer education programs. Deploy app-integrated delivery infrastructure to bypass kirana network saturation.
For Investors and Strategic Acquirers: Capital is best deployed toward regulatory affairs-capable formulators with FSSAI compliance documentation expertise and established CDSCO pathways for therapeutic crossover positioning. Long-term viability hinges on portfolio diversification into protein platforms as gym penetration accelerates. Watch FSSAI's evolving caffeine threshold stance as the signal for energy-sports hybrid reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Ayurveda-Infused Line Extension | Clean-label positioning captures consumers seeking alternatives to synthetic electrolyte compositions. |
| Gym-Direct Distribution Partnership | Captive supply agreements with fitness chains extract premium margins through trainer recommendation authority. |
| BIS Certification Investment | Accelerated packaged water base validation filters informal competitors from formal retail channels. |
| Subscription Replenishment Model | Recurring revenue capture among marathon training cohorts in Bengaluru and Mumbai disrupts supermarket purchasing. |
| CDSCO Therapeutic Crossover | Recovery-positioned vitamin-fortified drinks access medical channel distribution under drug regulator oversight. |
Research Methodology
Desk research of FSSAI regulatory filings, BIS certification databases, and customs import records preceded structured interviews with sports drink formulators, gym chain procurement heads, and regulatory affairs consultants. Primary fieldwork captured supply chain configuration details from PET bottle manufacturers and flavoring ingredient distributors. Secondary validation drew from organized fitness center expansion databases and marathon event partnership disclosures. Bottom-up volume modeling triangulated against top-down category spending estimates.
Variance decomposition across product type, end user archetype, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate aggregation and cross-segment elasticity estimation. Modeled inputs included gym penetration trajectories in tier-two cities, FSSAI compliance cost pass-through assumptions, and whey protein isolate price index movements.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI regulatory clarity and continued organized fitness infrastructure investment would require recalibration. Forecasts reflect documented assumptions around marathon culture institutionalization pace and cold chain capex deployment into tier-three towns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hot Cocoa Mix Market
Beverages
North America Juices Market
Beverages
Fruit Beverages Market
Beverages
Europe Smoothies Market
Beverages
Aloe Vera Juice Market
Beverages
Dairy Based Beverages Market
Beverages
Adaptogenic Beverages Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Packaged Coconut Water Market
Beverages
Italy Bottled Water Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Water Bottle Market
Beverages
Sparkling Water Machine Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Premium Water Market