
 Calcium Hydrogen Sulphite Market | 2026-2036
Calcium Hydrogen Sulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Hydrogen Sulphite Market Analysis
The gap between pharmaceutical-grade and industrial-grade calcium hydrogen sulphite is expanding as purity specifications diverge and customer audit requirements harden. BASF SE leverages its integrated sulphur chemistry platform to sustain cost advantages across both tiers. AkzoNobel anchors European supply through its Rotterdam manufacturing complex, while Kemira Chemicals dominates Nordic pulp mill chemical contracts with specialized logistics networks.
Calcium hydrogen sulphite is an inorganic salt with the chemical formula Ca(HSO3)2, typically supplied as an aqueous solution or solid with controlled sulphur dioxide content, functioning primarily as a reducing agent and preservative in industrial processes. The food additive segment leads volume consumption due to widespread use in wine stabilization and fruit processing, while the bleaching agent category captures premium pricing from pulp mills seeking chlorine-free process chemicals. Water treatment applications are maturing in developed markets, though textile processing demand in South Asia is shifting toward higher-purity grades to meet export certification standards.
EPA effluent guidelines and OSHA permissible exposure limits shape US manufacturing and handling protocols, while REACH registration requirements govern European import and production thresholds. China's GB standards for food additives and industrial chemicals create parallel compliance tracks that multinational suppliers must navigate. Stakeholders should monitor regulatory alignment between food safety frameworks and industrial chemical classifications, as reclassification risk could abruptly alter addressable market boundaries and qualification costs.
Market Dynamics
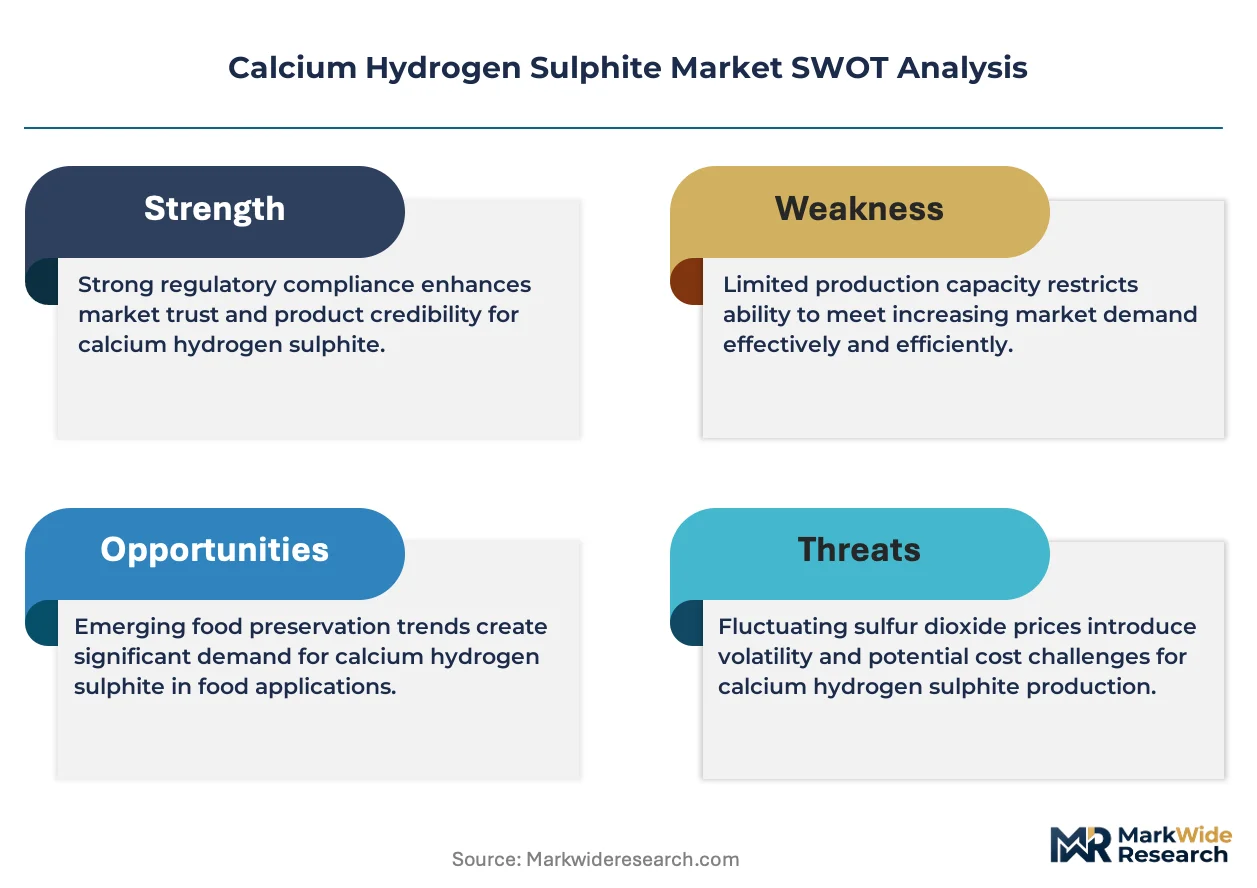
REACH registration requirements in Europe are forcing simultaneous purity upgrades across food additive and industrial chemical classifications, compressing supplier margins while erecting qualification barriers for new entrants.
Growth Catalysts
- Pulp mill bleaching demand:Packaging board output targets in China are expanding chlorine-free chemical consumption. Mills are substituting calcium hydrogen sulphite for elemental chlorine to meet export certification standards.
- Wine stabilization protocols:EFSA purity benchmarks for food additives are accelerating processor migration from synthetic preservatives. European vintners are qualifying dual-use suppliers capable of pharmaceutical-grade certification.
- Textile export compliance:GB standards alignment with OEKO-TEX requirements is displacing lower-purity grades in South Asian dyeing operations. Finishers are consolidating supplier bases to reduce audit burden.
Market Restraints
- Sulphur dioxide feedstock volatility:Smelter off-gas supply interruptions in key producing regions are transmitting price instability through aqueous solution contracts.
- Rotterdam supply concentration:European import dependency on a single major manufacturing complex creates vulnerability to logistics disruptions and qualification bottlenecks.
- Peracetic acid substitution:Cold sterilant alternatives are capturing share in fruit processing applications where residual sulphur tolerance is tightening.
Strategic Opportunities
- Indian food processing expansion:FSSAI additive approvals are unlocking volume growth in mango pulp and concentrated juice exports. Domestic blending capacity remains underdeveloped.
- Carbon capture integration:Sulphur chemistry platforms are converging with emissions reduction mandates. Captive SO2 from carbon capture byproduct streams offers feedstock cost advantages.
- Direct mill supply contracts:Nordic pulp operators are bypassing distributor networks for tanker-delivered bulk solutions, compressing working capital cycles for qualified logistics providers.
Industry Challenges
- Dual-track compliance engineering:Suppliers must maintain parallel quality systems for GB food additive standards and REACH industrial chemical registrations, doubling documentation overhead.
- Pharmaceutical-grade asset specificity:Stainless steel reactor investments for high-purity production lack fungibility with industrial-grade infrastructure, stranding capital during demand mix shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Hydrogen Sulphite Market |
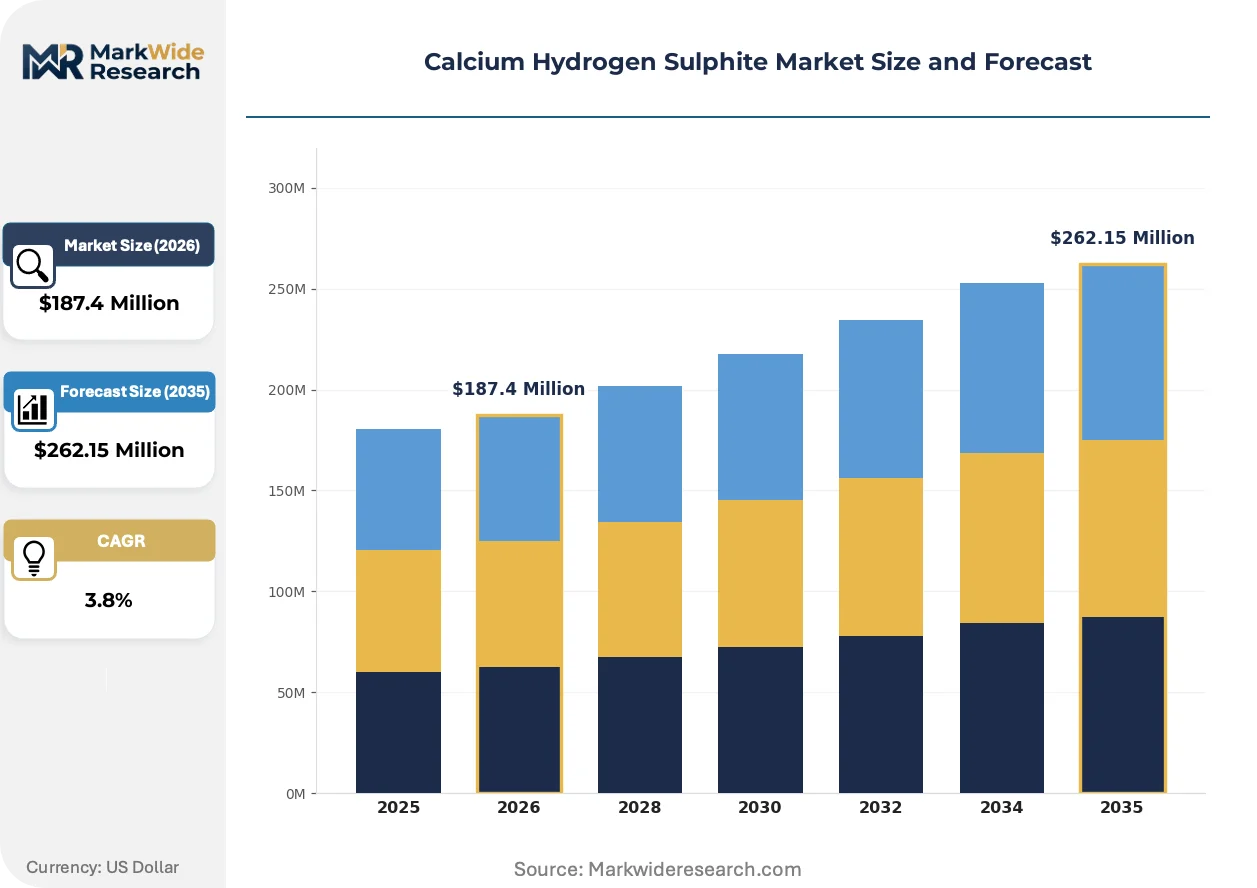
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Industrial Chemical, Laboratory Reagent, Bleaching Agent Application: Food Preservation, Pulp and Paper, Water Treatment, Textile Processing End User: Food Industry, Chemical Manufacturing, Textile Industry, Water Utilities Packaging Type: Drums, Bags, Totes, Bulk Containers |
| Companies Covered | AkzoNobel, BASF SE, Dow Chemical Company, Clariant AG, Lanxess AG, Kemira Chemicals, Triveni Interchem Pvt. Ltd., Henan Coreychem co., LTD, Hangzhou Dayang Chemical Industry Limited Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Hydrogen Sulphite Market Emerging Trajectories
Membrane filtration and continuous processing technologies are compressing production economics while regulatory reclassification risks are forcing anticipatory compliance investments across supplier tiers.
Continuous flow reactor technology is integrating real-time sulphur dioxide monitoring with automated pH adjustment to reduce batch-to-batch variation. European specialty chemical producers are retrofitting aqueous solution plants to capture pharmaceutical-grade output without dedicated asset lines. This capital-efficient approach is integrating food and industrial chemical production on shared infrastructure, eroding traditional purity-tier segmentation.
EU F-Gas Regulation phase-down schedules are accelerating scrutiny of sulphur-based process chemicals as indirect contributors to fluorinated gas alternatives in industrial refrigeration. Pulp mill energy recovery systems are requalifying heat exchanger materials to accommodate corrosive sulphite environments. Nordic producers are responding with upgraded metallurgy specifications in long-term maintenance contracts.
Consolidated procurement through integrated chemical management contracts is displacing spot purchasing in large-scale pulp operations. Finnish and Swedish mill groups are bundling bleaching chemical supply with logistics and inventory risk transfer to single-source providers. This concentration is most visible in the Baltic Sea coastal corridor where tanker access enables direct-to-mill delivery economics.
Calcium Hydrogen Sulphite Market Segmentation
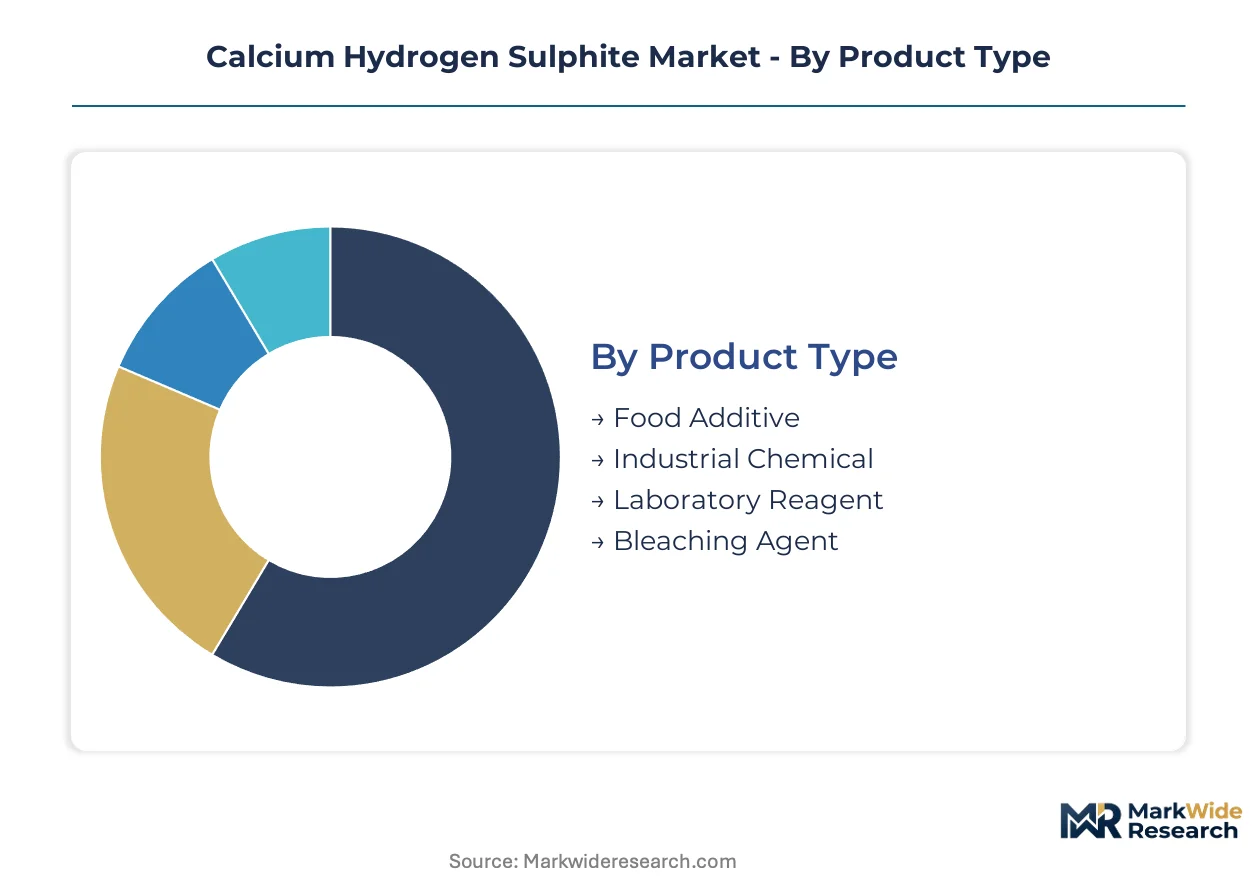
Calcium hydrogen sulphite serves divergent purity requirements across food safety and industrial process applications. Segment boundaries are hardening as REACH and GB standards force dedicated production lines and qualification systems.
Product Type:
Stainless steel reactor investments for pharmaceutical-grade output create the widest capital intensity spread across this dimension.
- Food Additive:Aqueous solutions and solids meeting EFSA purity benchmarks for wine stabilization and fruit preservation. European vintners are consolidating supplier bases around dual-use producers capable of pharmaceutical-grade certification.
- Industrial Chemical:Standard-grade material for pulp bleaching and water treatment with controlled sulphur dioxide release profiles. Chinese packaging board mills are expanding chlorine-free chemical consumption to meet export certification standards.
- Laboratory Reagent:High-purity grades for analytical and research applications with stringent impurity specifications.
- Bleaching Agent:Specialized formulations optimized for pulp mill process chemistry and textile pretreatment operations.
Most installed capacity flows through Industrial Chemical. Expansion is steepest in Food Additive.
Application:
Process integration requirements vary sharply, with pulp mill direct delivery demanding the most sophisticated logistics infrastructure.
- Food Preservation:Sulphite-based preservation in wine, fruit juices, and dried produce with strict residual limits. EFSA purity benchmarks are accelerating processor migration from synthetic preservatives toward qualified sulphite suppliers.
- Pulp and Paper:Chlorine-free bleaching sequences in packaging board production. Chinese mills are substituting calcium hydrogen sulphite for elemental chlorine to meet export certification standards.
- Water Treatment:Dechlorination and oxygen scavenging in municipal and industrial systems.
- Textile Processing:Bleaching and desizing operations with tightening export compliance requirements.
Volume concentrates in Pulp and Paper. Food Preservation is gaining share fastest.
End User:
Audit burden and qualification costs create the steepest customer tier differentiation in this dimension.
- Food Industry:Processors of wine, fruit pulp, and concentrated juices requiring dual-track GB and REACH compliance. FSSAI additive approvals are unlocking volume growth in Indian mango pulp exports.
- Chemical Manufacturing:Intermediate producers and specialty chemical blenders with flexible purity requirements.
- Textile Industry:Finishers and dye houses in South Asia consolidating supplier bases to reduce OEKO-TEX audit burden.
- Water Utilities:Municipal treatment operators with standardized procurement and lower purity thresholds.
Procurement consolidation is most advanced in Food Industry. Chemical Manufacturing shows the steepest expansion trajectory.
Packaging Type:
Tanker infrastructure and bulk handling systems represent the dominant capital deployment in this dimension.
- Drums:Standard 200-liter containers for mid-volume industrial and laboratory customers with established handling protocols.
- Bags:Solid product packaging for food additive and textile processing applications with moisture protection requirements.
- Totes:Intermediate bulk containers bridging drum and tanker economics for regional chemical distributors.
- Bulk Containers:Tanker and railcar deliveries for Nordic pulp mill direct supply contracts with inventory risk transfer.
Logistics investment clusters around Bulk Containers. Totes are expanding most quickly as distributors seek flexible scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineers and process specialists cluster around major sulphur chemistry hubs in Germany, China, and the Netherlands, anchoring regional production capacity and technical service networks for calcium hydrogen sulphite applications.
Germany
Specialty chemical producers in the Rhine-Ruhr corridor supply pharmaceutical-grade calcium hydrogen sulphite to European food processors and pharmaceutical manufacturers. REACH registration requirements enforced by ECHA mandate simultaneous purity upgrades across food additive and industrial classifications. Ludwigshafen and Leverkusen host integrated sulphur chemistry platforms serving dual-use certification demands.
China
Pulp and paper engineers in Shandong and Jiangsu provinces drive chlorine-free bleaching chemical consumption as packaging board mills expand output to meet export targets. GB standards for food additives and industrial chemicals create parallel compliance tracks that multinational suppliers must navigate. The Yangtze River Delta concentration of textile finishers is shifting toward higher-purity grades to satisfy OEKO-TEX export certification requirements.
Netherlands
Rotterdam's manufacturing complex anchors European calcium hydrogen sulphite supply through tanker-delivered bulk solutions and integrated logistics networks. The EU F-Gas Regulation phase-down schedules accelerate scrutiny of sulphur-based process chemicals in industrial refrigeration applications. The Port of Rotterdam chemical cluster enables direct mill supply contracts with inventory risk transfer to Nordic pulp operators.
India
Food technologists in Maharashtra and Gujarat unlock volume growth as FSSAI additive approvals expand mango pulp and concentrated juice export opportunities. Domestic blending capacity for sulphite-based preservatives remains underdeveloped relative to processing demand. The Mumbai-Pune industrial corridor attracts distributor investment in intermediate bulk container logistics bridging drum and tanker economics.
United States
Process safety engineers in the Gulf Coast chemical corridor navigate EPA effluent guidelines and OSHA permissible exposure limits governing manufacturing and handling protocols. Pulp mills in the Southeast evaluate chlorine-free bleaching sequences to meet retailer sustainability certification standards. The Texas-Louisiana petrochemical network provides sulphur dioxide feedstock integration opportunities for integrated producers.
Calcium Hydrogen Sulphite Market Vendor Landscape
Top-tier vendors anchor integrated sulphur chemistry platforms, while regional specialists and commodity traders occupy mid-market and spot-supply positions. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive feedstock, regional distributors with specialized logistics networks, and import-dependent traders serving price-sensitive segments. Two dominant competitive moves are reshaping positioning: backward integration into sulphur dioxide feedstock sources to dampen smelter off-gas price volatility, and carbon capture integration to secure low-cost SO2 from emissions reduction byproduct streams.
Within the integrated chemical conglomerate tier, BASF SE and AkzoNobel occupy positions defined by captive manufacturing infrastructure and dual-use certification capabilities. BASF SE exemplifies the sulphur chemistry platform archetype with cost advantages spanning pharmaceutical-grade and industrial-grade purity tiers. AkzoNobel anchors European supply through its Rotterdam manufacturing complex and tanker logistics specialization. Kemira Chemicals represents the regional logistics-integrated archetype, dominating Nordic pulp mill chemical contracts through dedicated supply chain infrastructure. Among Asia-Pacific fabricators, Triveni Interchem Pvt. Ltd. and Henan Coreychem co., LTD occupy positions serving food additive and industrial chemical demand across divergent regulatory compliance tracks.
| Leading Market Players |
|---|
| AkzoNobel |
| BASF SE |
| Dow Chemical Company |
| Clariant AG |
| Lanxess AG |
| Kemira Chemicals |
| Triveni Interchem Pvt. Ltd. |
| Henan Coreychem co., LTD |
| Hangzhou Dayang Chemical Industry Limited Company |
| Others |
Supply Flow & Price Mechanics
Chemical process engineers concentrated in Germany's Rhine-Ruhr corridor and China's Shandong province command wage premiums that widen spreads between pharmaceutical-grade and industrial-grade pricing tiers. Labor-cost differentials between these specialized workforce clusters and lower-skill blending operations in South Asia amplify the premium attached to dual-use certification capabilities.
Pricing Analysis
Bundled chemical-management contracts with inventory risk transfer command premium positioning against unbundled spot purchases. Three-tier pricing structure across pharmaceutical-grade, food-additive, and industrial-grade levels separates certified vintner suppliers from standard pulp-mill providers. Cost compression in industrial-grade aqueous solutions is intensifying because smelter off-gas feedstock volatility transmits through contract structures. Food processors with dual-track REACH and GB compliance requirements show least price sensitivity; commodity traders serving spot industrial demand exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI additive approval process are reshaping sourcing toward local blending investments. Manufacturing concentrates in Germany, China, and the Netherlands. Sulphur dioxide feedstock, stainless steel reactor capacity, and specialized tanker logistics anchor upstream dependencies. Single-source vulnerability around Rotterdam's manufacturing complex creates structural exposure. Distribution runs through integrated chemical management contracts with Nordic pulp operators and regional distributor networks serving fragmented food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium hydrogen sulphite market compounds steadily as chlorine-free bleaching mandates in packaging board production drive persistent substitution demand. Regulatory divergence between food safety and industrial chemical classifications sustains qualification barriers that protect incumbent returns.
For Market Incumbents: Hedge sulphur dioxide feedstock exposure through backward integration into smelter off-gas partnerships or carbon capture byproduct streams. Capture margin expansion by retrofitting aqueous solution plants for pharmaceutical-grade output without dedicated asset lines, countering peracetic acid substitution threats in fruit processing applications.
For New Entrants and Emerging Players: Continuous flow reactor technology with real-time SO2 monitoring offers a defensible entry wedge. Target Indian food processing expansion where FSSAI approvals unlock mango pulp export growth and domestic blending capacity remains underdeveloped. Lead with toll manufacturing partnerships that bypass captive logistics infrastructure requirements.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with integrated sulphur chemistry platforms are the most active acquirers in this space. Five-to-ten-year viability rests on dual-use certification capabilities that serve both food additive and industrial demand. Acquisition target archetype: regional distributors with specialized tanker logistics networks in Baltic Sea coastal corridors. Monitor REACH-GB regulatory alignment progress as inflection indicator for qualification cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulphur Dioxide Feedstock | Captive SO2 supply from smelter partnerships dampens price volatility transmitted through aqueous solution contracts. |
| Continuous Flow Reactor Retrofit | Real-time monitoring with automated pH adjustment reduces batch variation without dedicated pharmaceutical-grade asset lines. |
| Carbon Capture Integration | Emissions reduction byproduct streams offer feedstock cost advantages aligned with EU Green Deal mandates. |
| Direct Mill Supply Contracting | Tanker-delivered bulk solutions with inventory risk transfer compress working capital cycles for Nordic pulp operators. |
| Dual-Use Certification Investment | Parallel REACH and GB quality systems capture food processor consolidation toward qualified sulphite suppliers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included plant managers at sulphur chemistry platforms, procurement leads at Nordic pulp mills, distribution channel partners in the Baltic corridor, and technical R&D directors at specialty chemical producers. Secondary validation drew from customs and trade data, Cefic sector reports, SEC chemical company filings, and ECHA registration databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic anchoring.
Historical reference periods established baseline trajectories that the projection horizon extends through segmentation-specific growth patterning. Modeled dimensions span grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from weighted average growth rates across these segments. Forecast inputs incorporate pulp mill bleaching chemical substitution rates and food additive regulatory approval timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH-GB regulatory alignment, sulphur dioxide feedstock supply interruptions, and peracetic acid substitution penetration in fruit processing. Forecasts reflect documented assumptions about certification cost trajectories and mill direct-contract adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Europe Calcium Chloride Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market