
 Precipitated Fine Hydrate Market | 2026-2036
Precipitated Fine Hydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitated Fine Hydrate Market Analytics
Direct supply contracts between precipitated fine hydrate producers and industrial coating formulators is tilting toward longer-term, specification-locked agreements. Huber Engineered Materials leverages its captive bauxite refining network to anchor North American aluminum hydroxide supply. Evonik Industries AG specializes in high-purity precipitated silica for pharmaceutical excipient applications. Nabaltec AG dominates European flame-retardant grade distribution through integrated logistics hubs.
Precipitated fine hydrate denotes synthetically produced, high-surface-area metal hydroxide or carbonate particles typically ranging from sub-micron to several micrometers in median diameter, manufactured through controlled precipitation, filtration, and calcination or surface treatment steps. These materials function primarily as functional fillers, acid scavengers, flame retardants, and rheology modifiers across polymer, coating, and healthcare matrices. Aluminum hydroxide leads product type volume due to established halogen-free flame-retardant demand in wire and cable sheathing. Precipitated silica commands premium positioning within pharmaceutical applications where USP-NF compliance and batch consistency determine supplier qualification. Calcium carbonate remains mature in construction end uses, with margin pools shifting toward surface-coated grades for high-performance industrial coatings.
EPA TSCA Section 5 premanufacture notifications and REACH Annex XIV authorization requirements shape product entry barriers for novel hydrate chemistries in the United States and European Union respectively. FDA IIG (Inactive Ingredient Guide) listings and USP monograph conformance govern pharmaceutical-grade aluminum hydroxide and magnesium hydroxide market access. China's GB standards for industrial chemicals and evolving MEE emissions enforcement for precipitation facilities add compliance layers for import-dependent buyers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
REACH Annex XIV authorization requirements and EPA TSCA Section 5 premanufacture notifications are tightening purity specifications and documentation requirements for precipitated fine hydrate producers, forcing capital allocation toward compliance infrastructure and batch-level traceability systems.
Growth Catalysts
- Halogen-free flame-retardant mandates:Wire and cable sheathing manufacturers in automotive and construction sectors are expanding procurement of aluminum hydroxide grades to meet evolving fire safety standards without halogenated additives.
- REACH compliance in Europe:Tighter purity specifications for industrial chemicals are concentrating demand among qualified producers capable of delivering pharmaceutical-grade documentation and batch consistency.
- Specialized production clusters:Regional coating and pharmaceutical formulators in Germany, China, and the United States are anchoring demand through proximity to integrated logistics hubs and captive bauxite refining networks.
Market Restraints
- Bauxite supply concentration:Captive refining networks controlled by integrated majors limit independent access to feedstock for specialty hydrate producers without backward integration.
- Energy intensity of precipitation:China's MEE emissions enforcement for precipitation facilities adds cost layers and capacity constraints for import-dependent buyers sourcing from Chinese suppliers.
- Substitute flame retardants:Magnesium hydroxide and intumescent systems compete for share in polymer applications where processing temperature tolerance exceeds aluminum hydroxide decomposition thresholds.
Strategic Opportunities
- Pharmaceutical excipient qualification:USP-NF compliance and FDA IIG listings for high-purity precipitated silica create premium positioning opportunities for producers investing in dedicated pharmaceutical production lines.
- Surface-coated calcium carbonate:Construction end uses are shifting margin pools toward coated grades for high-performance industrial coatings, rewarding producers with surface treatment capabilities.
- Dual carbon goals in China:Domestic emissions reduction mandates are accelerating consolidation among precipitation facilities, creating acquisition opportunities for compliant operators with clean technology portfolios.
Industry Challenges
- Regulatory divergence management:Producers must monitor evolving EPA toxicity testing protocols, REACH authorization timelines, and GB standards simultaneously to avoid stranded inventory and qualification gaps across jurisdictions.
- Batch consistency certification:Pharmaceutical-grade aluminum hydroxide and magnesium hydroxide markets require sustained investment in analytical capabilities and quality systems to maintain USP monograph conformance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitated Fine Hydrate Market |
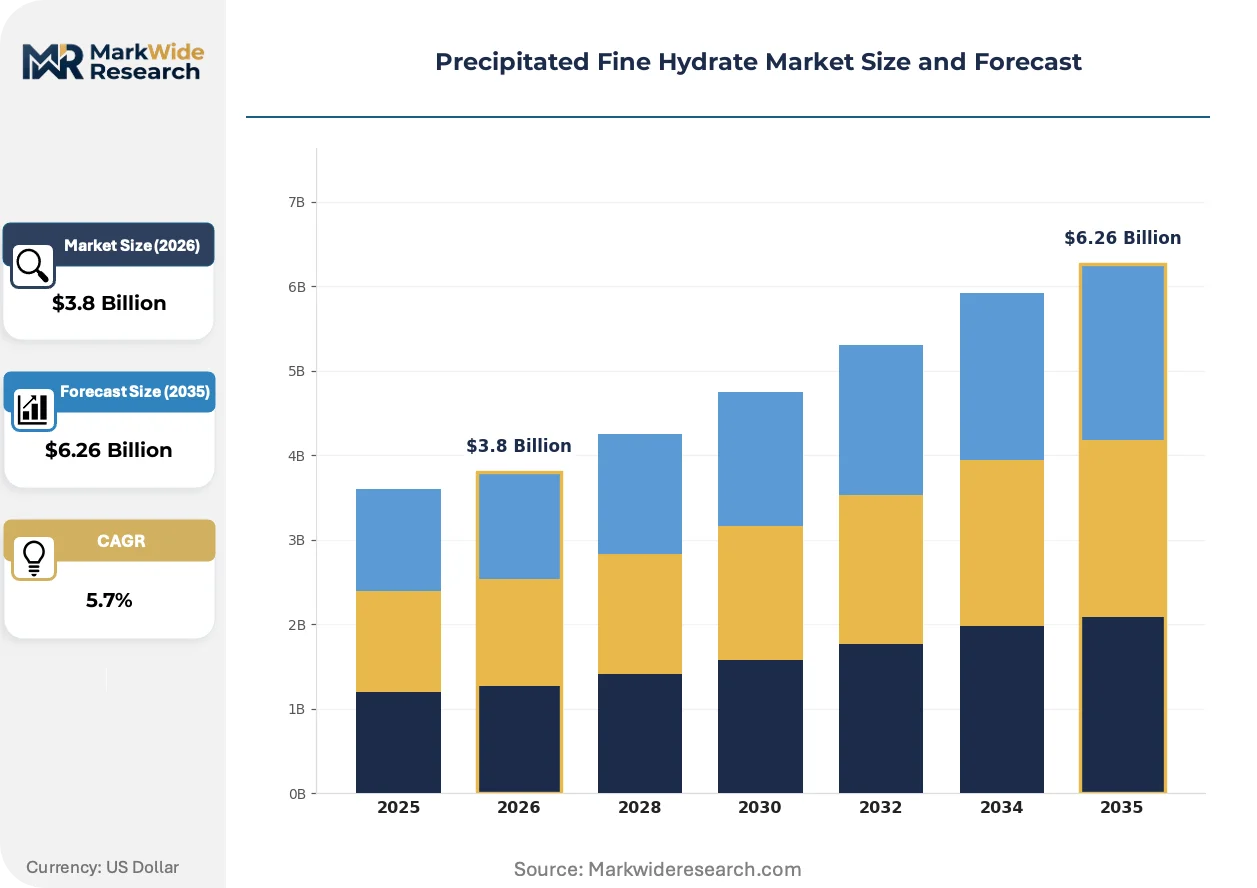
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Hydroxide, Aluminum Hydroxide, Calcium Carbonate, Precipitated Silica Application: Industrial Coatings, Pharmaceuticals, Personal Care Products, Food Additives End User: Construction, Healthcare, Cosmetics, Food & Beverage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | TOR Minerals International, Evonik Industries AG, Huber Engineered Materials, Imerys S.A., Solvay S.A., Nabaltec AG, J.M. Huber Corporation, PPG Industries, Inc., Showa Denko K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitated Fine Hydrate Market Evolving Landscape
Controlled precipitation and surface treatment technologies are reshaping product differentiation, with functional performance now trumping commodity pricing in buyer qualification decisions across polymer, coating, and healthcare matrices.
Surface modification chemistry for precipitated fine hydrate is migrating from simple stearate coating toward silane coupling and polymer encapsulation systems. Automotive underhood applications requiring thermal stability above 200°C are adopting these advanced grades despite 15-25% price premiums. The technology shift is compressing margins for uncoated commodity producers while rewarding integrated specialists with in-house surface treatment capabilities.
REACH Annex XIV authorization requirements for Substances of Very High Concern are forcing reformulation across European polymer compounding. Industrial consequences include accelerated qualification timelines for alternative hydrate chemistries and expanded documentation burdens for existing suppliers. Flame-retardant polymer manufacturers in Germany and Benelux are responding by locking multi-year supply agreements with REACH-authorized producers to secure regulatory continuity.
Buyer concentration among tier-one automotive and construction material suppliers is compressing switching cycles and unbundling technical service from product supply. Distributors serving mid-size coating formulators are losing share to direct mill relationships as procurement teams centralize spend and demand application-specific formulation support. This pattern is most visible in the United States, where Huber Engineered Materials and comparable integrated suppliers have built dedicated technical sales organizations to capture specification authority early in product development cycles.
Precipitated Fine Hydrate Market Segmentation
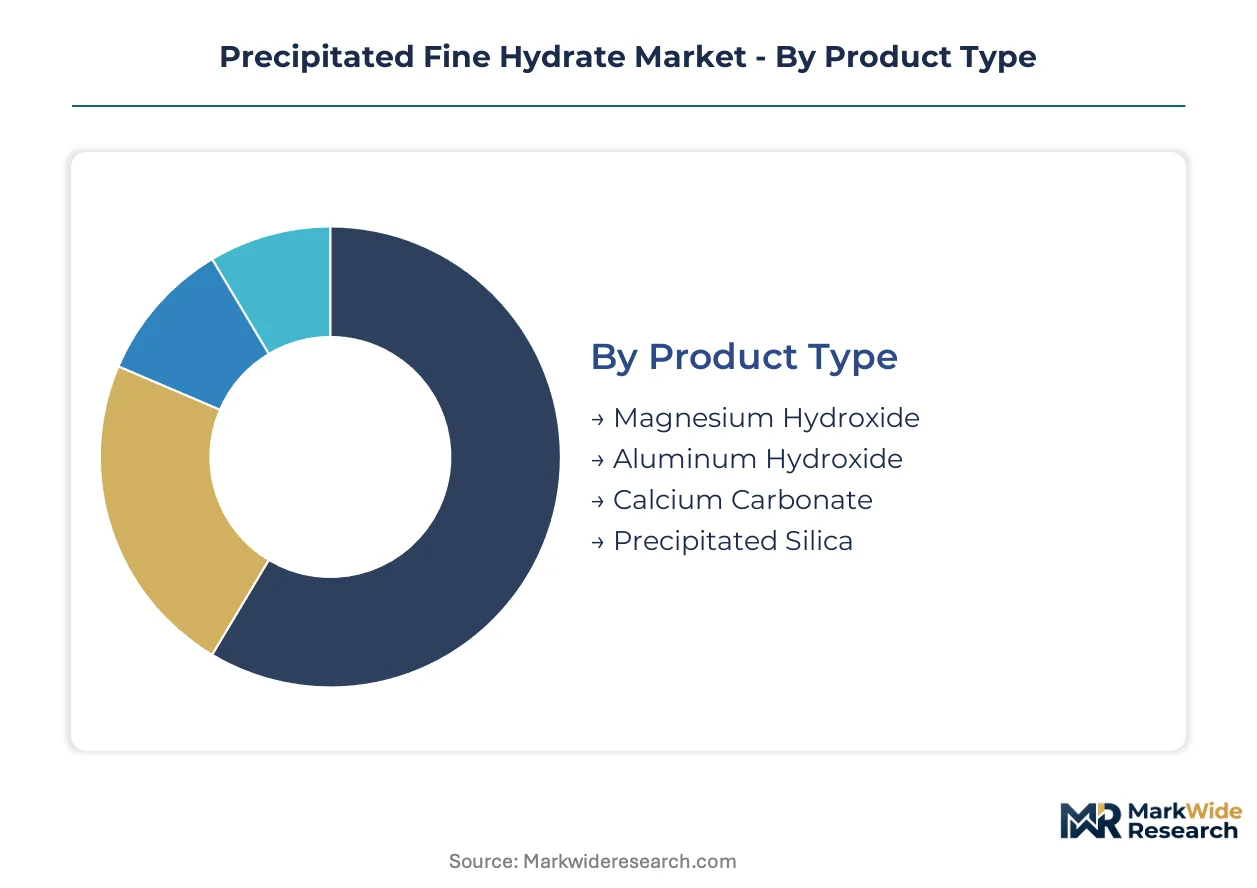
Segmentation in precipitated fine hydrate markets reflects divergent purity requirements and regulatory pathways across end-use matrices. Pharmaceutical and food-grade specifications demand dedicated production lines and analytical certification that commodity industrial grades bypass entirely.
Product Type:
Cost tier differentiation separates commodity flame-retardant grades from pharmaceutical and food-grade premiums requiring dedicated precipitation control and surface treatment infrastructure.
- Aluminum Hydroxide:Synthetic gibbsite-phase particles manufactured through controlled Bayer liquor precipitation deliver halogen-free flame retardancy in wire and cable sheathing. Wire and cable manufacturers in automotive and construction sectors anchor procurement volumes as fire safety standards tighten without halogenated additives.
- Precipitated Silica:High-surface-area amorphous silica produced via sodium silicate acidification commands premium positioning where USP-NF compliance and batch consistency determine supplier qualification. Pharmaceutical excipient applications in Germany and the United States concentrate demand among producers with dedicated pharmaceutical production lines and FDA IIG listings.
- Magnesium Hydroxide:Brucite-structure hydroxide offers higher decomposition temperature than aluminum hydroxide for polymer processing above 200°C.
- Calcium Carbonate:Precipitated rhombohedral particles remain mature in construction end uses with margin pools shifting toward surface-coated grades.
Aluminum Hydroxide holds installed capacity. Precipitated Silica is rotating up the share rankings.
Application:
Application segmentation tracks regulatory intensity gradients from industrial coatings through pharmaceutical and food matrices.
- Pharmaceuticals:Aluminum hydroxide and magnesium hydroxide function as active antacid ingredients and excipient carriers requiring USP monograph conformance and FDA IIG documentation. German and United States formulators concentrate procurement among qualified producers with sustained investment in analytical capabilities and quality systems.
- Industrial Coatings:Surface-coated calcium carbonate and precipitated silica modify rheology and opacity in high-performance protective coatings. Construction sector demand in China anchors volume through proximity to integrated logistics hubs and domestic precipitation facilities.
- Personal Care Products:High-purity precipitated silica serves as abrasive and thickening agent in toothpaste and cosmetic formulations.
- Food Additives:Calcium carbonate functions as anticaking agent and calcium fortifier under stricter purity protocols than industrial grades.
Industrial Coatings holds installed capacity. Pharmaceuticals is rotating up the share rankings.
End User:
End user concentration patterns reflect sector-specific procurement centralization and technical service requirements.
- Construction:Flame-retardant polymer manufacturers and industrial coating formulators drive aluminum hydroxide and calcium carbonate procurement through direct mill relationships. Tier-one construction material suppliers in the United States compress switching cycles and unbundle technical service from product supply.
- Healthcare:Pharmaceutical formulators and medical device manufacturers demand batch-level traceability systems for aluminum hydroxide and magnesium hydroxide excipients. REACH Annex XIV authorization requirements in Europe force reformulation and accelerate qualification timelines for alternative hydrate chemistries.
- Cosmetics:Personal care product manufacturers source precipitated silica through specialized distributors with formulation support capabilities.
- Food & Beverage:Processors procure calcium carbonate under national food safety regulations varying by jurisdiction.
Construction holds installed capacity. Healthcare is rotating up the share rankings.
Distribution Channel:
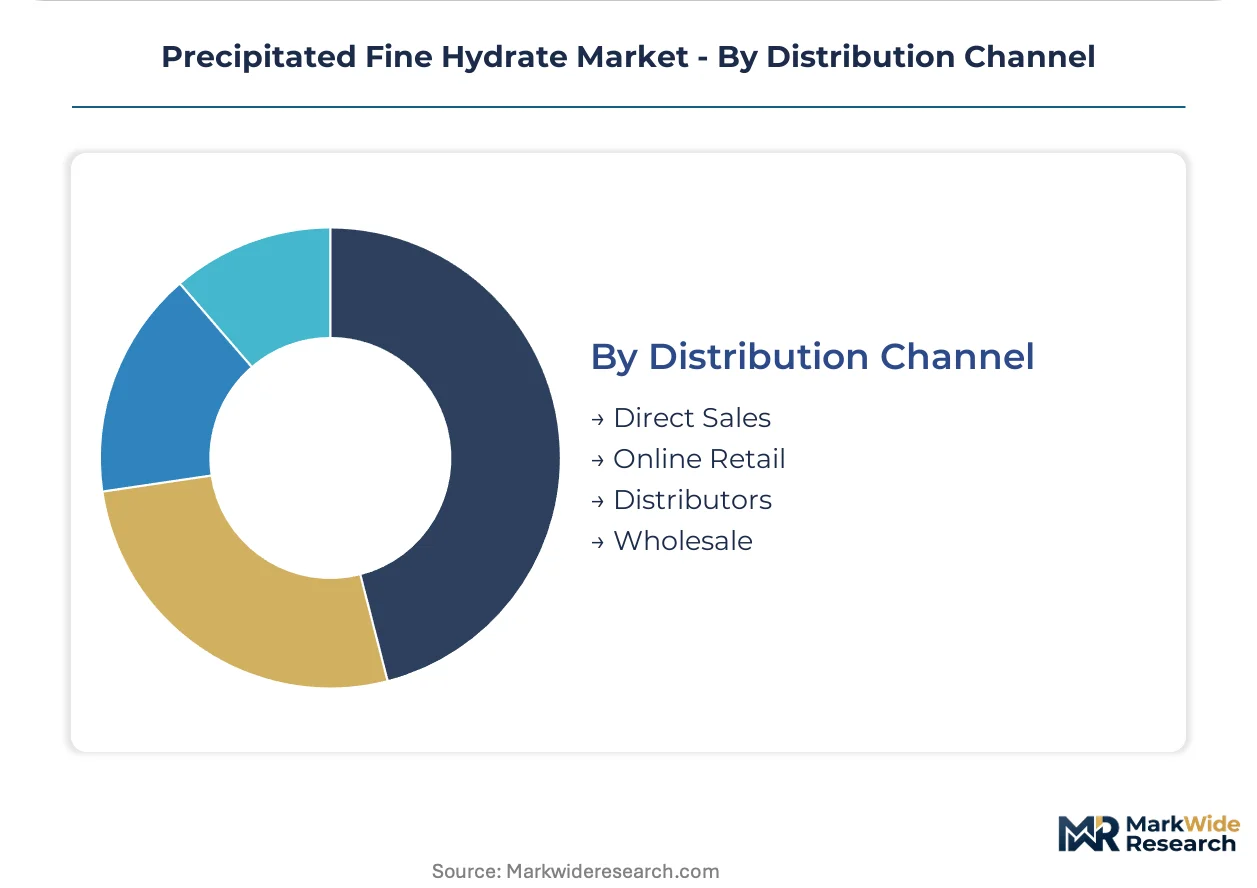
Channel structure tracks buyer concentration and specification complexity across customer tiers.
- Direct Sales:Integrated producers with captive technical sales organizations capture specification authority early in product development cycles for tier-one automotive and construction material suppliers. Huber Engineered Materials and comparable suppliers in the United States have built dedicated organizations to serve centralized procurement teams demanding application-specific formulation support.
- Distributors:Regional logistics hubs serve mid-size coating formulators and compounders with inventory buffering and local technical service. Nabaltec AG dominates European flame-retardant grade distribution through integrated logistics hubs serving Germany and Benelux polymer compounders.
- Online Retail:Digital procurement platforms capture small-volume laboratory and research-grade orders with standardized specifications.
- Wholesale:Bulk handlers move uncoated commodity grades to price-sensitive construction and industrial accounts.
Direct Sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor anchors European hydrate distribution, connecting Bavarian production clusters to North Sea ports and Mediterranean outlets.
United States
Wire and cable sheathing manufacturers in the Southeast and Midwest are expanding aluminum hydroxide procurement to meet automotive fire safety standards. EPA TSCA Section 5 premanufacture notifications tighten documentation requirements for novel hydrate chemistries. Houston and Gulf Coast petrochemical corridors concentrate precipitation capacity serving construction and coating formulators.
Germany
REACH Annex XIV authorization requirements are forcing reformulation across polymer compounding in the Rhine-Ruhr industrial belt. ECHA compliance timelines accelerate qualification for alternative hydrate suppliers. Bavarian integrated logistics hubs anchor flame-retardant grade distribution to Benelux compounders seeking regulatory continuity.
China
Dual carbon goals and MEE emissions enforcement are consolidating precipitation facilities in the Yangtze River Delta. GB standards for industrial chemicals add compliance layers for domestic producers and import-dependent buyers. Shandong Peninsula production clusters serve regional coating manufacturers with captive bauxite refining networks.
Japan
METI industrial standards govern pharmaceutical-grade precipitated silica production for excipient applications. PMDA documentation requirements concentrate demand among qualified producers with sustained investment in analytical capabilities. Kansai-region chemical complexes maintain dedicated pharmaceutical production lines for domestic and export formulators.
India
BIS certification requirements for industrial chemicals are tightening purity specifications for construction-grade calcium carbonate. CDSCO pharmaceutical regulations create parallel qualification pathways for aluminum hydroxide excipients. Gujarat and Maharashtra industrial corridors attract capacity expansion serving domestic coating and healthcare formulators.
Precipitated Fine Hydrate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying functional fillers to compounders and formulators. The vendor base stratifies between captive bauxite refiners, dedicated precipitation specialists, and diversified chemical conglomerates with hydrate divisions. Two dominant archetypes emerge: integrated miners with backward control over feedstock, and technology-focused specialists with surface treatment capabilities. Competitive moves concentrate on multi-year specification-locked supply agreements and geographic expansion through logistics hub integration.
Among integrated North American suppliers, Huber Engineered Materials anchors the captive refining archetype, while Evonik Industries AG exemplifies the pharmaceutical-grade specialization tier. Nabaltec AG occupies a position within European flame-retardant distribution, representing the logistics-integrated mid-cap model serving polymer compounders.
| Leading Market Players |
|---|
| TOR Minerals International |
| Evonik Industries AG |
| Huber Engineered Materials |
| Imerys S.A. |
| Solvay S.A. |
| Nabaltec AG |
| J.M. Huber Corporation |
| PPG Industries, Inc. |
| Showa Denko K.K. |
| Others |
Value Network & Pricing Analysis
Shandong Peninsula bauxite refining clusters tether margin pools to pharmaceutical-grade certification tiers in Germany and the United States. REACH-authorized producers capture 40-60% premiums over industrial-grade commodity suppliers through locked multi-year agreements with automotive wire and cable manufacturers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, flame-retardant industrial, and uncoated commodity levels dominates transactional patterns. Price differentiation rests on USP-NF certification status and batch-level traceability documentation for healthcare applications. Cost compression in uncoated calcium carbonate runs through Chinese MEE emissions enforcement and energy price volatility. Tier-one automotive compounders exhibit lowest price sensitivity due to specification-locked supply agreements, while mid-size coating formulators drive spot-market negotiation intensity.
Supply Chain Analysis
Huber Engineered Materials and Nabaltec AG hold captive precipitation capacity serving North American and European demand respectively. Geographic supply concentration centers on China, Germany, and the United States where integrated logistics hubs anchor regional distribution. Raw material dependencies draw from bauxite refining networks, sodium silicate feedstocks, and surface treatment chemical inputs. Single-source vulnerability in pharmaceutical-grade aluminum hydroxide creates qualification bottlenecks during supplier audits. Distribution runs through direct mill relationships for tier-one buyers and specialized distributors for mid-market compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified production capacity for USP-NF compliant precipitated silica remains scarce relative to expanding pharmaceutical excipient demand. Producers with dedicated analytical capabilities and FDA IIG listings command structural leverage in supplier qualification cycles.
For Market Incumbents: Entrench specification authority through backward integration into surface treatment capabilities and captive bauxite refining networks. Magnesium hydroxide substitutes threaten aluminum hydroxide share in high-temperature polymer processing above 200°C. Capacity addition in Bavarian logistics hubs secures REACH-authorized supply continuity for Benelux compounders facing reformulation mandates.
For New Entrants and Emerging Players: Establish a beachhead in surface-coated calcium carbonate for high-performance industrial coatings where margin pools are rotating away from uncoated commodity grades. China's dual carbon consolidation creates acquisition opportunities for compliant precipitation facilities with clean technology portfolios. Technical service bundling with application-specific formulation support unlocks mid-size coating formulator relationships bypassing distributor channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap precipitation specialists lacking pharmaceutical-grade certification infrastructure. Long-term viability hinges on sustained investment in analytical capabilities and quality systems across a 5-10 year regulatory tightening horizon. Target operators with surface modification chemistry expertise and existing REACH authorizations. Monitor ECHA Annex XIV timeline acceleration as inflection indicator for alternative hydrate chemistry qualification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive feedstock control secures margin stability against supply concentration in Shandong and Guinean extraction zones. |
| Pharmaceutical-Grade Production Line Investment | FDA IIG listing and USP-NF compliance unlock premium positioning in German and United States excipient markets. |
| Surface Modification Capability Expansion | Silane coupling and polymer encapsulation systems command 15-25% price premiums in automotive underhood applications. |
| REACH-Authorized Logistics Hub Integration | Bavarian hub acquisition anchors flame-retardant grade distribution to polymer compounders seeking regulatory continuity. |
| Long-Term Specification-Locked Supply Agreements | Multi-year contracts with tier-one wire and cable manufacturers compress switching cycles and stabilize revenue visibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at precipitation facilities, procurement leads at automotive wire and cable manufacturers, technical R&D directors at coating formulators, and regulatory affairs specialists at pharmaceutical excipient producers. Secondary validation drew from ECHA authorization databases, FDA IIG listings, SEC 10-K filings of listed chemical producers, customs trade data for hydrate imports, and GB standards documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Calibration against historical price realizations and capacity utilization rates anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry application, surface treatment complexity, and regional regulatory cluster. CAGRs were derived through regression analysis of demand drivers and supply elasticity parameters. Industry-specific forecast inputs incorporated REACH Annex XIV authorization timelines and MEE emissions enforcement intensity trajectories.
Stress conditions across bauxite supply disruptions, energy price volatility, and regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding qualification cycle durations and substitution elasticity thresholds. Quarterly review of ECHA authorization progress and Chinese precipitation facility operating rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Barite Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Sodium Gluconate Market