
 Vacuum Salts Market | 2026-2036
Vacuum Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Salts Market Analysis
The vacuum salts market is pivoting on a widening split between pharmaceutical-grade purity benchmarks and commodity industrial specifications. K+S Aktiengesellschaft leverages its Zielitz and Bernburg facilities to dominate European pharmaceutical-grade supply chains. Tata Chemicals anchors its position through backward integration into brine reserves across Gujarat and Kenya. Cargill Incorporated differentiates via food-grade certification depth, sustaining retail and foodservice channel control in North America.
Vacuum salts are sodium chloride crystals produced by evaporating brine under controlled vacuum and temperature conditions, yielding purity levels exceeding 99.9 percent with minimal calcium, magnesium, and sulfate contaminants. The process operates at reduced boiling points, typically 70 to 80 degrees Celsius, preserving crystal structure for uniform dissolution in pharmaceutical and chemical applications. Food-grade vacuum salts command premium positioning due to stringent anti-caking and iodization standards, while industrial-grade volumes compete on delivered cost for chlor-alkali and water-softening buyers. Pharmaceutical-grade supply is tightening as FDA and EMA bio-burden specifications harden, concentrating margin pools with certified European and North American refiners. Bulk packaging dominates chemical industry procurement, though sachet formats are expanding in foodservice and airline catering channels.
EPA effluent guidelines and OSHA workplace exposure limits shape industrial-grade product specifications and handling protocols in the United States. REACH registration requirements and ECHA substance evaluations restrict heavy-metal thresholds in European food and pharmaceutical applications, creating compliance barriers for non-EU suppliers. FDA food additive regulations and USP monograph standards govern pharmaceutical-grade purity and labeling. Stakeholders must monitor evolving PFAS testing mandates and iodine fortification policies, as these frameworks will determine which refiners retain market access across regulated end-use segments.
Market Dynamics
Pharmaceutical-grade purity specifications are hardening faster than commodity industrial standards, splitting procurement pools and concentrating margin capture with certified refiners capable of FDA and EMA bio-burden compliance.
Growth Catalysts
- REACH heavy-metal thresholds:European chemical buyers redirect volumes toward certified refiners meeting ECHA substance evaluations, tightening supplier lists and elevating pricing power for compliant producers.
- Chlor-alkali feedstock upgrading:Membrane cell technology expansion in water treatment and chemical processing demands ultra-low calcium and magnesium content, pulling specification-sensitive volumes toward vacuum salt.
- Germany's integrated refining clusters:Zielitz and Bernburg facilities anchor pan-European pharmaceutical supply chains, creating geographic concentration that accelerates certification-driven procurement consolidation.
Market Restraints
- Natural gas input volatility:Vacuum evaporation energy intensity exposes margins to European and Asian gas price swings, compressing returns for non-integrated refiners during input spikes.
- Solar salt price arbitrage:Open-pan solar evaporation in Australia and India delivers acceptable purity for water-softening at 30-40 percent lower delivered cost, capping industrial-grade pricing.
- Brine reserve access concentration:Captive underground reserves in Gujarat, Kenya, and Saskatchewan limit new entrant supply security, entrenching incumbents with backward-integrated positions.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO alignment with ICH guidelines creates demand for USP-grade vacuum salt in active pharmaceutical ingredient production, opening import substitution potential for domestic refiners.
- PFAS testing mandate preparation:Anticipated EPA and ECHA per- and polyfluoroalkyl substance screening protocols reward early analytical capability investments with preferred supplier status.
- Foodservice sachet channel growth:Airline catering and quick-service restaurant portion-control formats favor pre-measured vacuum salt packets over bulk dispensing, shifting packaging mix toward higher-margin units.
Industry Challenges
- EMA bio-burden certification timelines:Pharmaceutical-grade approval cycles extend 18-24 months, delaying revenue recognition for capacity expansions and straining working capital.
- Anti-caking additive reformulation:Shifting from ferrocyanide to citrate-based agents for food-grade compliance requires process revalidation without interrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Salts Market |
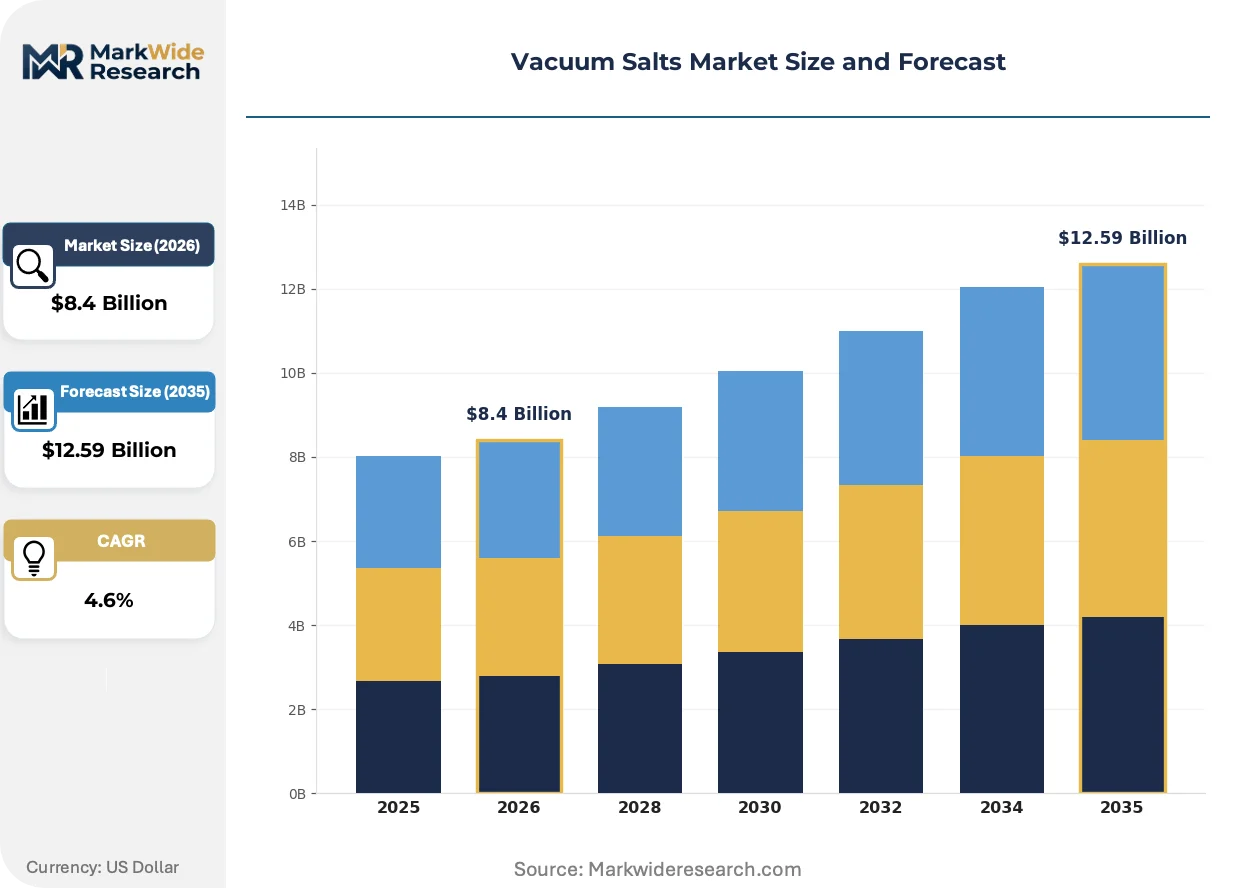
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade End User: Food Processing, Chemical Industry, Pharmaceuticals, Agriculture Packaging Type: Bags, Drums, Bulk, Sachets Application: Preservation, Flavoring, De-icing, Feed Supplement |
| Companies Covered | K+S Aktiengesellschaft, Tata Chemicals, AkzoNobel, CIECH, Cargill Incorporated, INEOS Group Limited, Compass Minerals International, Südwestdeutsche Salzwerke, Dominion Salt Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Salts Market Emerging Trajectories
Digital process control and analytical testing convergence is compressing batch-to-batch variation, enabling pharmaceutical buyers to tighten incoming inspection protocols and reduce safety stock holdings.
Membrane filtration pre-treatment is integrating with traditional vacuum evaporation circuits, reducing calcium and sulfate loads before crystallization. Chlor-alkali producers in Germany and the Netherlands adopt this hybrid configuration to extend membrane cell campaign lengths. The technology is integrating energy recovery from multiple-effect evaporators, cutting steam consumption per ton of salt output.
EMA's revised excipient risk assessment guidelines now require documented supply chain transparency down to brine source. European pharmaceutical manufacturers are qualifying secondary suppliers and demanding audit rights over evaporation facility hygiene zones. The policy compresses acceptable supplier lists and elevates documentation burdens for non-EU refiners seeking market access.
Specification-driven buyer consolidation is concentrating procurement volumes with fewer certified refiners capable of multi-grade production. Food manufacturers in North America now favor single-source relationships spanning food-grade, pharmaceutical-grade, and industrial-grade requirements. This pattern is most visible in the United States, where Cargill and Morton Salt leverage certification depth to displace commodity traders from premium accounts.
Vacuum Salts Market Segmentation
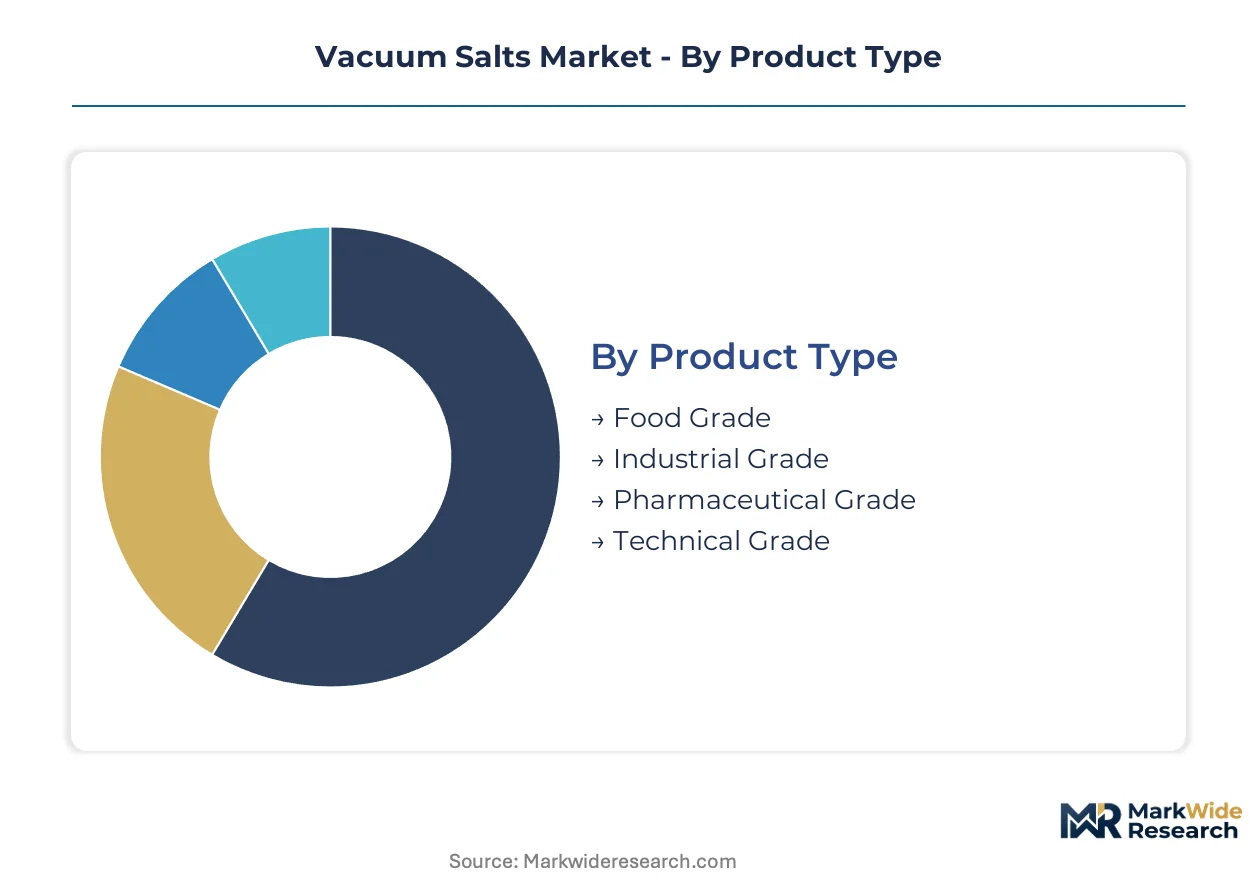
Vacuum salt buyers diverge sharply on purity thresholds, energy inputs, and regulatory documentation. Procurement patterns split between price-sensitive bulk chemical buyers and specification-driven pharmaceutical and food manufacturers who audit brine-to-crystal traceability.
Product Type:
Cost tier separates commodity buyers from premium-grade purchasers who absorb certification overhead.
- Pharmaceutical Grade:Purity exceeds 99.9 percent with documented bio-burden control and heavy-metal testing per USP and EMA excipient guidelines. German refiners at Zielitz and Bernburg dominate European supply, capturing margin from FDA-inspected API manufacturers who reject uncertified alternatives.
- Food Grade:Anti-caking additives and iodization compliance distinguish this tier, with citrate-based agents displacing ferrocyanide in European formulations under EFSA pressure. North American food manufacturers consolidate procurement with dual-certified suppliers who also serve pharmaceutical accounts.
- Industrial Grade:Chlor-alkali membrane cell feedstock with controlled calcium and magnesium limits.
- Technical Grade:Water-softening and process salt applications where solar salt purity suffices for non-critical uses.
Volume sits with Industrial Grade; growth tilts toward Pharmaceutical Grade.
End User:
Application maturity determines whether buyers prioritize delivered cost or specification compliance.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and tablet excipient applications demand lot-level traceability and EMA audit rights over evaporation hygiene zones. CDSCO alignment with ICH guidelines in India is opening import substitution opportunities for domestic USP-grade production.
- Chemical Industry:Chlor-alkali production consumes the largest tonnage, with membrane cell technology upgrading specifications toward vacuum salt purity. Dutch and German producers adopt membrane filtration pre-treatment to extend campaign lengths and reduce calcium loading.
- Food Processing:Cured meats, dairy, and bakery applications require FSSAI or FDA food additive compliance with documented iodine fortification levels.
- Agriculture:Animal feed supplements and soil conditioning represent price-sensitive volume with minimal purity premiums.
Chemical Industry commands tonnage; Pharmaceuticals climbs fastest on certification premiums.
Packaging Type:
Customer scale and handling infrastructure dictate format selection across the value chain.
- Bulk:Rail and vessel shipments dominate chlor-alkali and municipal water-softening procurement, with dedicated silo infrastructure at receiving sites. German integrated refiners leverage captive brine and on-site evaporation to serve pan-European industrial buyers at lowest delivered cost.
- Sachets:Airline catering and quick-service restaurant portion-control formats shift mix toward higher-margin units, with pre-measured packets replacing bulk dispensers in hygiene-sensitive environments.
- Bags:Intermediate scale for food processors and regional chemical distributors.
- Drums:Pharmaceutical and laboratory applications requiring sealed containment and lot tracking.
Bulk handles volume; sachets expand share fastest in foodservice channels.
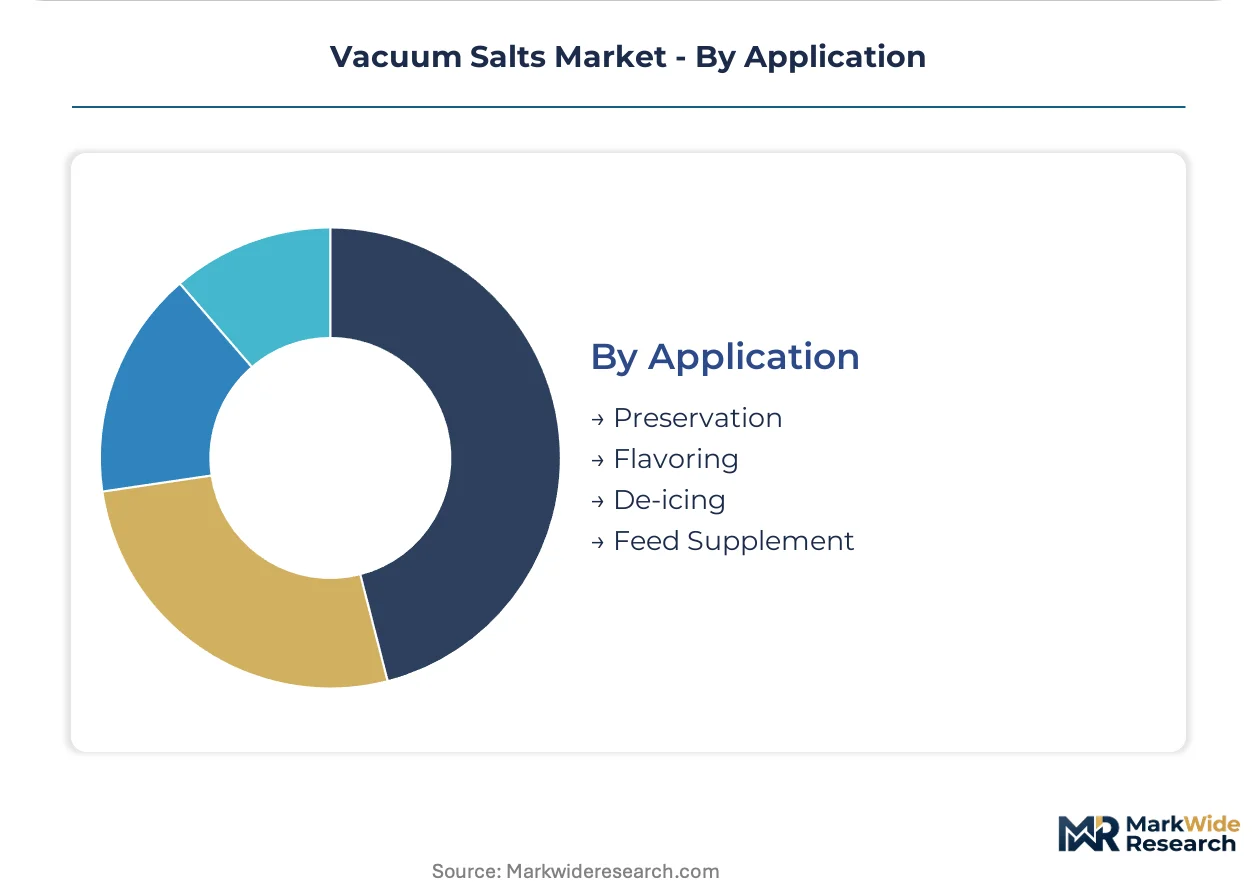
Application:
Functional performance requirements separate preservation and de-icing commodity markets from flavoring and feed premium segments.
- Flavoring:Fine crystal structure and rapid dissolution kinetics command premium positioning in gourmet and specialty food. Uniform grain size from controlled vacuum evaporation preserves mouthfeel in premium applications where solar salt irregularity is rejected.
- Preservation:Curing and pickling applications balance purity with cost, driving specification divergence between artisan producers who specify vacuum salt and mass manufacturers who accept refined rock salt.
- De-icing:Road salt applications favor lowest-cost supply, with solar salt and rock salt displacing vacuum grades except where environmental regulations restrict insoluble residue.
- Feed Supplement:Animal nutrition applications require mineral-balanced formulations with controlled iodine levels per national veterinary standards.
Preservation holds volume; flavoring gains fastest on premium food positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zielitz and Bernburg anchor European pharmaceutical-grade vacuum salt supply, with integrated refining complexes serving membrane cell chlor-alkali producers across the continent. Regulatory divergence between FDA bio-burden standards and REACH heavy-metal thresholds is fragmenting procurement routes by destination market.
Germany
Membrane cell technology upgrades at Ludwigshafen and Marl chemical parks pull specification-sensitive volumes toward ultra-low calcium vacuum salt. ECHA substance evaluations under REACH restrict heavy-metal thresholds below 2 ppm for pharmaceutical excipients. K+S Aktiengesellschaft and Südwestdeutsche Salzwerke maintain captive brine-to-crystal operations at Zielitz and Heilbronn, consolidating pan-European supply security.
United States
Chlor-alkali producers along the Gulf Coast adopt vacuum salt pre-treatment to extend membrane campaign lengths beyond 36 months. EPA effluent guidelines and OSHA workplace exposure limits shape industrial-grade handling protocols at Texas and Louisiana receiving terminals. Cargill Incorporated leverages food-grade certification depth to control retail and foodservice channels across the Midwest and Southeast.
India
Active pharmaceutical ingredient manufacturers in Hyderabad and Ahmedabad drive USP-grade vacuum salt demand as CDSCO aligns with ICH Q7 guidelines. FSSAI iodization mandates and anti-caking additive regulations create compliance barriers for uncertified imports. Tata Chemicals anchors supply security through backward integration into Gujarat brine reserves, serving domestic chlor-alkali and pharma synthesis markets.
Netherlands
Rotterdam-Antwerp chemical corridor demand concentrates on membrane filtration pre-treatment hybrids that reduce calcium loading before crystallization. EU Green Deal carbon border adjustments expose non-integrated refiners to margin compression from natural gas price volatility. INEOS Group Limited operations at Rotterdam integrate energy recovery from multiple-effect evaporators, cutting steam consumption per ton of output.
China
Chlor-alkali capacity expansion in Ningbo and Tianjin pulls industrial-grade volumes toward vacuum salt purity as membrane cell technology displaces mercury cells. NMPA pharmaceutical excipient registration requirements harden documentation burdens for imported USP-grade supply. Domestic refiners in Shandong and Jiangsu provinces invest in analytical testing capability to capture import substitution opportunities from European-certified competitors.
Vacuum Salts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and brine reserve integration, with FDA-inspected and EMA-audited refiners capturing 40-60 percent pricing premiums over uncertified alternatives. The market structures into three tiers: integrated majors with captive underground reserves, regional specialists with single-grade certification focus, and commodity traders dependent on spot solar salt arbitrage. Dominant competitive moves include membrane filtration technology licensing for hybrid evaporation circuits and multi-grade portfolio expansion to capture single-source procurement relationships.
Among German integrated refiners, K+S Aktiengesellschaft and Südwestdeutsche Salzwerke exemplify the captive-reserve archetype, anchoring European pharmaceutical-grade supply chains through Zielitz and Bernburg facilities. Tata Chemicals represents backward-integrated positioning into Gujarat and Kenya brine reserves, while Cargill Incorporated occupies the North American food-grade certification depth tier. These three entities illustrate how geographic concentration of underground reserves and regulatory compliance capability determine sustainable margin capture across fragmented end-use segments.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| Tata Chemicals |
| AkzoNobel |
| CIECH |
| Cargill Incorporated |
| INEOS Group Limited |
| Compass Minerals International |
| Südwestdeutsche Salzwerke |
| Dominion Salt Limited |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade procurement consolidation across European API manufacturers is forcing supply responses from certified refiners capable of EMA audit rights and documented brine-to-crystal traceability, compressing supplier lists and elevating pricing power for compliant German and North American producers.
Pricing Analysis
Yield-linked pricing anchors pharmaceutical-grade contracts, with membrane cell chlor-alkali producers paying premiums tied to extended campaign lengths and reduced calcium-induced downtime. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates certified excipient supply from commodity water-softening volumes. Pricing pressure stems from solar salt arbitrage in technical applications, capping industrial-grade margins. Chemical buyers exhibit highest price sensitivity; pharmaceutical manufacturers absorb certification premiums without volume elasticity.
Supply Chain Analysis
Regional distribution centers at Rotterdam, Hamburg, and Houston anchor hub-and-spoke patterns for bulk chlor-alkali feedstock delivery. Supply concentrates in Germany, India, and the United States, with captive brine reserves in Gujarat, Saskatchewan, and Zielitz anchoring upstream security. Production draws from natural gas-fired evaporation, exposing margins to European and Asian energy volatility. Single-source vulnerability concentrates in pharmaceutical-grade certification, where EMA approval cycles extend 18-24 months. Distribution runs through dedicated silo infrastructure at membrane cell facilities, with rail and vessel shipments dominating tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA bio-burden certification timelines and REACH heavy-metal compliance are forcing weaker traders and uncertified refiners toward exit, consolidating procurement volumes with integrated majors possessing captive reserves and multi-grade production flexibility.
For Market Incumbents: To counter solar salt price arbitrage in industrial segments, deepen backward integration into captive brine reserves while expanding membrane filtration pre-treatment licensing to chlor-alkali producers seeking campaign length extension. Prioritize multi-grade portfolio breadth to capture single-source pharmaceutical and food manufacturing relationships. For New Entrants and Emerging Players: Capture import substitution potential in Indian pharmaceutical manufacturing as CDSCO aligns with ICH Q7 guidelines, targeting USP-grade supply gaps currently filled by European imports. Enter through analytical testing capability investments that anticipate PFAS screening mandates, qualifying as preferred suppliers before protocol hardening. For Investors and Strategic Acquirers: The window for entry favors integrated refiners with EMA-audited facilities and documented supply chain transparency down to brine source. Target acquisition archetypes include regional specialists with single-grade certification depth that can scale into multi-grade production. Watch for EPA PFAS testing mandate finalization as inflection signal compressing acceptable supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Reserves | Tata Chemicals anchors supply security through Gujarat and Kenya captive reserves, displacing import-dependent competitors. |
| Membrane Filtration Pre-Treatment Licensing | INEOS Group Limited at Rotterdam integrates energy recovery from multiple-effect evaporators, cutting steam consumption per ton. |
| Multi-Grade Certification Expansion | Cargill Incorporated leverages food-grade depth to control retail channels while qualifying for pharmaceutical excipient supply. |
| PFAS Analytical Capability Investment | Early analytical testing investments reward refiners with preferred supplier status under anticipated EPA and ECHA protocols. |
| Foodservice Sachet Channel Development | Airline catering and quick-service restaurant portion-control formats shift packaging mix toward higher-margin pre-measured units. |
Methodological Framework
Document review covered EMA excipient guidelines, REACH substance evaluations, FDA USP monographs, and chlor-alkali industry technical specifications, complemented by interviews with plant managers at membrane cell facilities, procurement leads at European chemical parks, pharmaceutical quality assurance directors, and food-grade salt distributors. Secondary validation drew from customs trade data, SEC filings of listed refiners, and energy consumption disclosures from integrated chemical complexes. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers and end-use segments.
Segmented outputs across pharmaceutical, food, industrial, and technical grades were modeled against chlor-alkali capacity expansion, membrane cell technology penetration, and regulatory compliance timelines throughout the forecast period. CAGRs were derived from regression analysis of historical price-volume relationships and forward projections of certification-driven procurement consolidation. Key inputs included natural gas price volatility scenarios and EMA audit approval cycle distributions.
The model holds under stable regulatory compliance timelines and continued membrane cell technology adoption; deviation in PFAS mandate acceleration or brine reserve access restrictions would shift supply concentration and pricing power. Forecasts reflect stated assumptions on certification barrier persistence and energy input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Global Hexamethylenediamine Market