
 Global Crumb Rubber Market | 2026-2036
Global Crumb Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crumb Rubber Market Analysis
The EU Green Deal is pivoting procurement criteria across European construction and automotive supply chains toward verified recycled content thresholds. Genan A/S leverages its Danish processing scale to supply tire-derived crumb for infrastructure projects across Northern Europe. Liberty Tire Recycling anchors North American collection networks, converting end-of-life tires into feedstock for asphalt and sports surface manufacturers. Lehigh Technologies specializes in cryogenically micronized rubber powders that compete with virgin polymers in high-performance compounds.
Crumb rubber consists of granulated material processed from end-of-life tires through ambient grinding or cryogenic reduction, typically screened to particle sizes between 0.4 mm and 4.7 mm for industrial applications. The material functions primarily as an asphalt binder modifier, sports field infill, and feedstock for molded rubber products, reducing reliance on virgin synthetic elastomers. Tyre rubber dominates volume flows given the sheer feedstock availability from automotive discard streams, while recycled rubber commands premium positioning where certification to REACH and state procurement standards is mandatory. Fine grade material leads in asphalt modification applications where surface area drives binder interaction, whereas coarse grade occupies construction fill and drainage layers where gradation stability matters more than chemical reactivity.
EPA guidelines on tire-derived aggregate influence state-level procurement specifications for civil engineering applications in the United States. ECHA's REACH restrictions on polycyclic aromatic hydrocarbons in rubber infill products shape product liability and market access conditions for European sports surface suppliers. ASTM standards and ISO 9001 quality protocols govern material consistency for buyers in construction and automotive end-use segments. Stakeholders must monitor evolving state-level procurement mandates and infill restriction proposals to anticipate demand shifts between asphalt modification and alternative outlet markets.
Market Dynamics
State highway agencies in the United States are mandating rubber-modified asphalt for pavement rehabilitation, compressing procurement timelines and forcing processors to secure tire-derived feedstock under long-term offtake agreements. This demand concentration is restructuring supplier relationships across the value chain.
Growth Catalysts
- Rubber-Modified Asphalt Mandates:State-level transportation departments in the United States are specifying crumb rubber binder modifiers for highway resurfacing contracts, creating durable offtake channels for tire-derived material processors.
- EU Green Deal Circular Economy Mandates:Extended producer responsibility frameworks are accelerating tire collection infrastructure and setting mandatory recycled content thresholds for construction materials across Northern Europe.
- Synthetic Turf Infill Specification:Sports surface installers are expanding procurement of cryogenically processed crumb rubber for artificial field systems, driven by shock absorption performance requirements and player safety protocols.
Market Restraints
- Feedstock Supply Volatility:End-of-life tire collection volumes fluctuate with automotive discard cycles and seasonal driving patterns, creating input cost instability for ambient grinding operations.
- Processing Energy Intensity:Cryogenic micronization requires liquid nitrogen consumption that tracks industrial gas pricing, compressing margins for fine-grade rubber powder producers competing with virgin polymers.
- ECHA REACH PAH Restrictions:Polycyclic aromatic hydrocarbon limits in rubber infill products are creating compliance friction for European sports surface suppliers and triggering product liability exposure.
Strategic Opportunities
- India Infrastructure Build-Out:National highway expansion programs and the Bureau of Indian Standards' emerging recycled material protocols are opening specification windows for tire-derived aggregate in sub-base applications.
- Automotive Underbody Compounds:Cryogenically processed rubber powders are penetrating molded automotive components as virgin synthetic elastomer prices rise, creating substitution opportunities in NVH dampening parts.
- Direct-to-Contractor Digital Platforms:B2B marketplaces are disintermediating traditional distributor networks for construction-grade crumb rubber, enabling processors to capture margin from asphalt paving contractors.
Industry Challenges
- Cryogenic Processing Technician Scarcity:Specialized knowledge of liquid nitrogen system operation and micronized powder classification is concentrated among aging workforces in Denmark and Germany.
- Multi-Jurisdiction Certification Timelines:REACH compliance for European infill markets, EPA state-delegated programs for US highway applications, and ASTM D5644 testing protocols create overlapping approval cycles that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crumb Rubber Market |
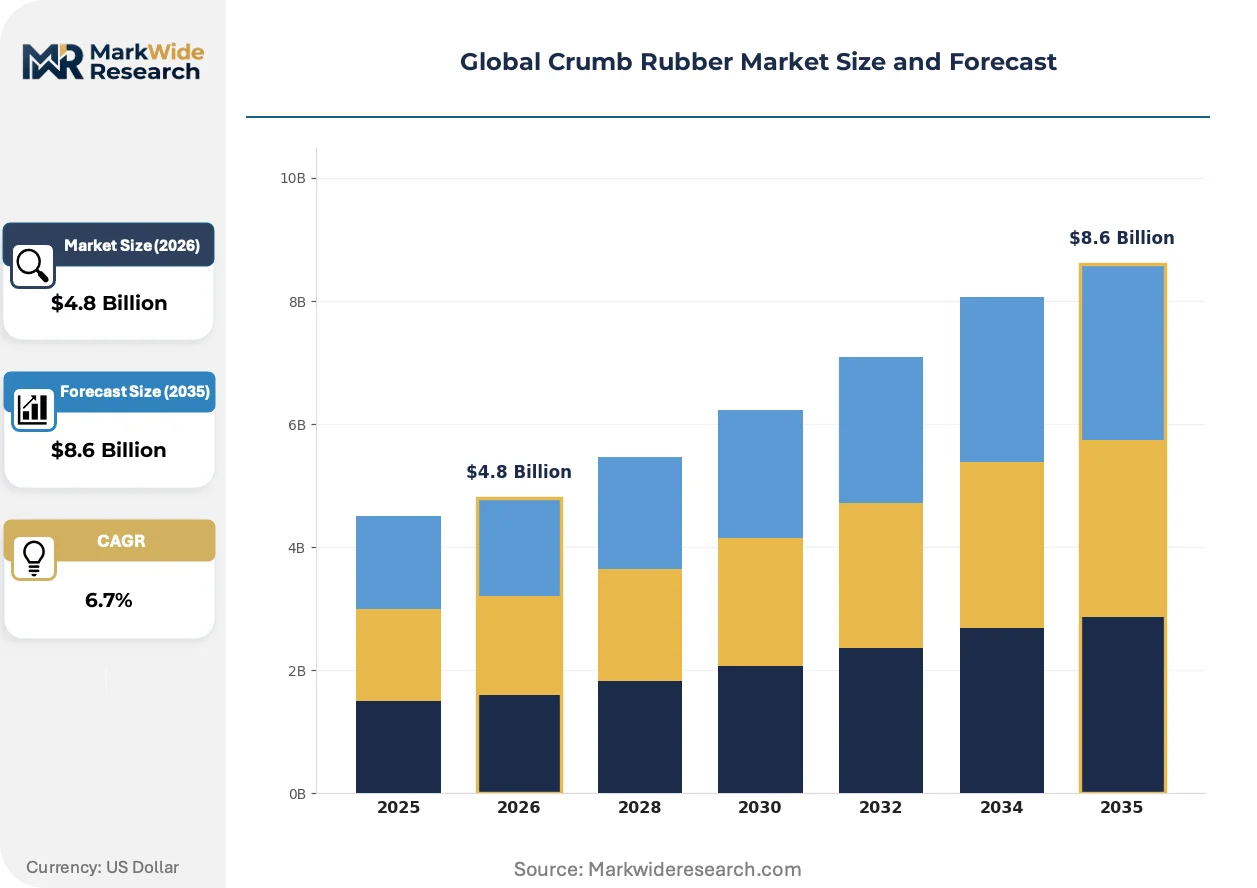
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyre Rubber, Recycled Rubber, High-Abrasion Rubber, Synthetic Rubber Application: Sports Surfaces, Flood Control, Asphalt Modification, Playground Surfaces Size: Fine Grade, Medium Grade, Coarse Grade, Crumb Size End User: Construction, Automotive, Sports Industry, Recycling Industry |
| Companies Covered | Genan A/S, Liberty Tire Recycling, Lehigh Technologies, Granutech-Saturn Systems, Klean Industries, Marubeni Corporation, Tinna Rubber And Infrastructure, Lakin Tire, Ecore International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crumb Rubber Market Emerging Trajectories
Processing technology is fragmenting into scale-optimized configurations, with ambient grinding systems competing against cryogenic micronization for distinct particle size applications. Equipment suppliers are embedding sensor arrays for real-time gradation control.
Cryogenic micronization systems are modularizing around containerized nitrogen supply units and compact classifier trains. Asphalt binder modifier producers in Texas and California are adopting these scaled configurations to locate processing closer to tire collection hubs. This distributed architecture is compressing logistics costs for fine-grade material destined for rubberized asphalt terminals.
EPA guidelines on tire-derived aggregate are cascading into state procurement specifications, with California and Texas transportation departments embedding recycled content minimums into pavement rehabilitation contracts. The industrial consequence is locked-in offtake volumes for processors holding state-approved supplier status. Asphalt modification grade material is experiencing the tightest supply allocation as highway agencies accelerate rehabilitation schedules.
Specification-driven purchasing is displacing spot-market procurement for construction-grade crumb rubber. Municipal highway departments and sports field contractors are migrating to multi-year supply agreements with certified processors. Germany and the Netherlands exhibit the most advanced contract structures, with verified chain-of-custody documentation now standard for public infrastructure tenders.
Global Crumb Rubber Market Segmentation
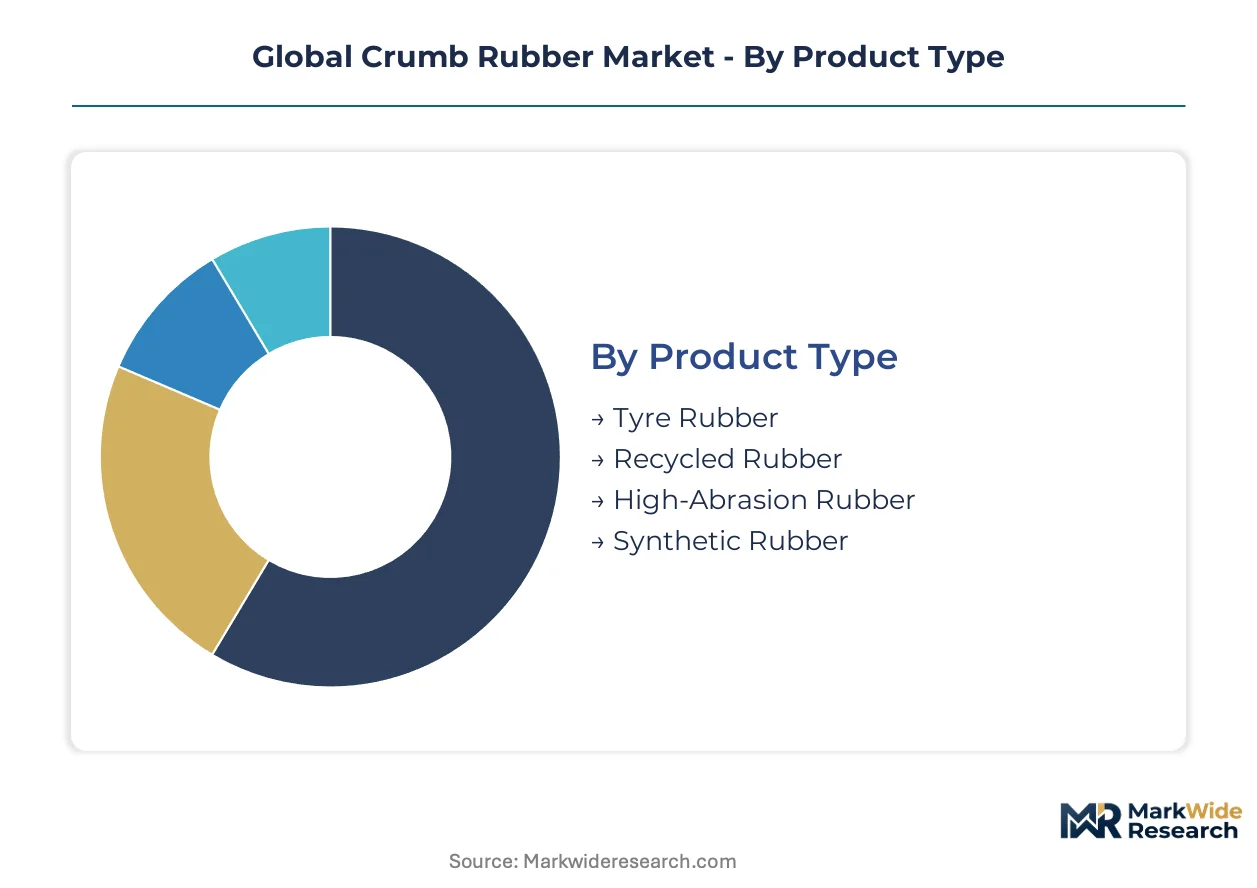
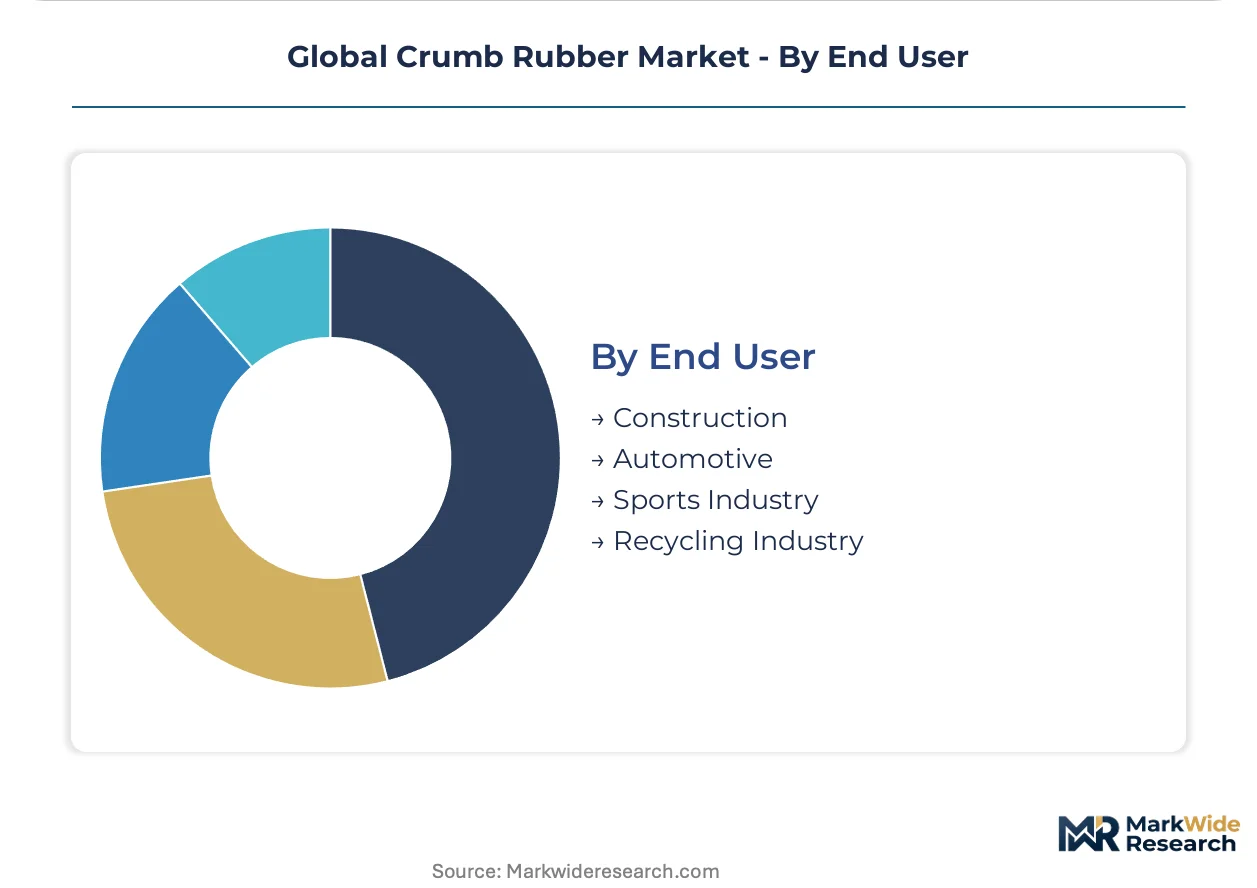
Crumb rubber processors configure production lines around distinct particle specifications and end-use certification requirements. Each segmentation axis governs equipment selection, feedstock sourcing, and margin capture differently.
Product Type:
Technology intensity separates commodity processors from specialty compounders.
- Tyre Rubber:Derived from ambient grinding of passenger and truck tires, this feedstock dominates volume flows through established collection infrastructure. Demand concentrates in United States highway rehabilitation programs where state transportation departments mandate rubber-modified asphalt for pavement durability.
- Recycled Rubber:Post-consumer and post-industrial streams undergo secondary processing to meet REACH and EPA procurement standards. European sports surface installers are concentrating procurement here, driven by ECHA PAH compliance requirements and chain-of-custody verification protocols.
- High-Abrasion Rubber:Processed from commercial vehicle tires with enhanced polymer content for demanding wear applications.
- Synthetic Rubber:Virgin elastomer blends compete in premium compounds where consistent performance specifications override recycled content mandates.
Mature deployment sits with Tyre Rubber. Newer deployment is concentrated in Recycled Rubber.
Application:
Specification stringency varies sharply across civil engineering versus recreational end-uses.
- Asphalt Modification:Fine-grade crumb rubber functions as binder modifier in hot mix and terminal blend applications. Texas and California transportation departments are locking in multi-year offtake agreements, compressing spot market availability for this specification tier.
- Sports Surfaces:Cryogenically processed infill meets Gmax impact attenuation standards for synthetic turf fields. German and Dutch municipal contractors are driving specification adoption, with verified recycled content thresholds now embedded in public tender documentation.
- Playground Surfaces:Impact-absorbing bonded rubber surfaces for fall protection in recreational installations.
- Flood Control:Tire-derived aggregate provides permeable fill for drainage structures and erosion control.
Volume leadership belongs to Asphalt Modification. Margin expansion is concentrated in Sports Surfaces.
Size:
Particle distribution determines chemical reactivity and mechanical interlock performance.
- Fine Grade:Screened below 0.8 mm, this material maximizes surface area for asphalt binder interaction. Cryogenic micronization systems in Denmark and Germany supply Northern European infrastructure projects where REACH-compliant processing is mandatory.
- Coarse Grade:Particles between 2.0 mm and 4.7 mm provide gradation stability for construction fill and drainage layers. United States civil engineering contractors specify this tier for tire-derived aggregate in sub-base applications.
- Medium Grade:Intermediate sizing for molded rubber products and industrial matting applications.
- Crumb Size:Unspecified gradation for low-specification fill and energy recovery feedstock.
Technology investment clusters in Fine Grade. Price-sensitive volume flows through Coarse Grade.
End User:
Procurement sophistication divides institutional buyers from spot-market purchasers.
- Construction:Highway agencies and civil engineering contractors specify certified crumb rubber for asphalt modification and aggregate applications. EPA state-delegated programs and ASTM D5644 protocols govern supplier qualification in the United States.
- Sports Industry:Field installers and facility managers source infill material against player safety protocols and environmental liability standards. ECHA restrictions on polycyclic aromatic hydrocarbons are reshaping European supplier relationships.
- Automotive:Molded component manufacturers substitute micronized rubber powders for virgin elastomers in NVH dampening parts.
- Recycling Industry:Secondary processors and material brokers manage feedstock flows between collection networks and end-use markets.
Contract discipline is strongest in Construction. Specification evolution is fastest in Sports Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Northern Europe and North America, while consumption concentrates in highway rehabilitation and sports surface installations across multiple jurisdictions. This geographic split creates arbitrage opportunities for processors with cross-border logistics capabilities.
United States
State transportation departments in Texas and California mandate rubber-modified asphalt for pavement rehabilitation, locking in multi-year offtake agreements. EPA state-delegated programs govern tire-derived aggregate specifications for civil engineering applications. Houston and Los Angeles anchor the largest processing clusters, where Liberty Tire Recycling operates collection networks feeding regional asphalt terminals.
Germany
ECHA REACH restrictions on polycyclic aromatic hydrocarbons reshape procurement criteria for sports surface infill and construction materials. The country's national highway regulator specifies recycled content thresholds for federal road maintenance contracts. The Rhine-Ruhr industrial corridor hosts cryogenic micronization facilities supplying REACH-compliant material to Dutch and Belgian contractors.
India
National highway expansion programs under the Bureau of Indian Standards' emerging recycled material protocols open specification windows for tire-derived aggregate. The central government's infrastructure build-out targets sub-base applications for crumb rubber. Gujarat and Maharashtra industrial zones concentrate ambient grinding operations serving western India construction markets.
Denmark
EU Green Deal circular economy mandates accelerate tire collection infrastructure and mandatory recycled content requirements for public procurement. Genan A/S leverages Danish processing scale to supply tire-derived crumb for infrastructure projects across Northern Europe. Copenhagen anchors the Nordic region's largest cryogenic processing hub.
Japan
METI industrial standards govern crumb rubber quality protocols for automotive and construction applications. JIS certification requirements create entry barriers for imported material in molded rubber product segments. The Kanto region around Tokyo concentrates sports surface installers specifying cryogenically processed infill for synthetic turf fields.
Global Crumb Rubber Market Vendor Landscape
The competitive structure tilts toward scale-driven processors with integrated collection networks. Market concentration varies by specification tier, with cryogenic micronization exhibiting tighter supply-side control than ambient grinding commodity segments. Two strategic archetypes dominate: vertically integrated tire collectors with downstream processing assets, and specialized compounders focusing on high-grade powders for premium applications. Capacity expansion and strategic partnerships represent the dominant competitive moves, as processors secure long-term feedstock agreements with state highway agencies.
Within the integrated collection-processing tier, Genan A/S and Liberty Tire Recycling exemplify scale-driven positioning across European and North American markets respectively. Lehigh Technologies occupies a specialist position in cryogenically micronized rubber powders. These three entities represent distinct strategic postures: Nordic infrastructure scale, North American collection network density, and premium-grade material technology specialization.
| Leading Market Players |
|---|
| Genan A/S |
| Liberty Tire Recycling |
| Lehigh Technologies |
| Granutech-Saturn Systems |
| Klean Industries |
| Marubeni Corporation |
| Tinna Rubber And Infrastructure |
| Lakin Tire |
| Ecore International |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circular economy mandates gate both qualified supply and premium-tier pricing access, as processors holding verified chain-of-custody documentation capture asphalt modification contracts while uncertified competitors face spot-market relegation. State transportation departments in Texas and California lock in multi-year offtake agreements with REACH-compliant suppliers, compressing margins for ambient grinding operations lacking certification investment.
Pricing Analysis
Outcome-based pricing tied to pavement performance metrics anchors premium tiers, with rubber-modified asphalt contractors paying for documented durability rather than tonnage alone. Price differentiation separates cryogenically micronized powders meeting ASTM D5644 protocols from commodity ambient-ground material, while certification to ECHA PAH limits commands additional premiums in European sports surface markets. Cost compression in coarse-grade construction fill is intensifying because feedstock collection volatility forces processors to absorb input price swings. Municipal highway agencies exhibit lowest price sensitivity given mandate-locked procurement, whereas spot-market playground surface installers negotiate aggressively on volume.
Supply Chain Analysis
End-of-life tire reverse-logistics networks in the United States, Germany, and Denmark feed processing clusters with collection density determining feedstock cost structures. Raw material flows draw from automotive discard streams, seasonal driving patterns, and commercial fleet replacement cycles, with liquid nitrogen supply for cryogenic operations resting on industrial gas pricing. Single-source vulnerability concentrates in specialized micronization equipment sourced from Danish and German manufacturers. Distribution runs through state-approved asphalt terminals, sports field contractors, and direct-to-paver digital platforms disintermediating traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH polycyclic aromatic hydrocarbon restrictions erect a compliance moat that rewards certified processors with locked-in offtake while excluding capital-constrained entrants lacking testing infrastructure investment.
For Market Incumbents: Lock in multi-year feedstock agreements with state highway agencies before procurement windows close, and deepen backward integration into tire collection networks to secure input cost predictability against seasonal discard volatility. Cryogenic processing capacity expansion in Texas and California reinforces positioning where rubber-modified asphalt mandates are accelerating. Certification maintenance to evolving EPA state-delegated programs preserves supplier status in civil engineering applications. For New Entrants and Emerging Players: The mid-market price-point gap between premium REACH-certified material and economy-grade construction fill offers white-space targeting for regional processors investing in modular ambient grinding systems. India's Bureau of Indian Standards emerging protocols present the most penetrable geography for tire-derived aggregate specification. A direct-to-contractor digital platform go-to-market angle bypasses entrenched distributor relationships in fragmented construction segments. For Investors and Strategic Acquirers: State transportation department multi-year offtake announcement velocity is the leading indicator that asphalt modification grade supply is tightening and margin expansion is transferring to processors with approved supplier status. Acquisition targets should emphasize cryogenic micronization capability and existing state certification portfolios over pure collection scale. Monitor EPA guideline cascade into additional state procurement specifications as the inflection signal for demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Collection | Captive feedstock supply from Liberty Tire Recycling-style networks insulates processors from seasonal discard volatility. |
| Cryogenic Micronization Capacity Expansion | Modular nitrogen-supply systems in Texas and California compress logistics costs for fine-grade asphalt modifier production. |
| REACH Compliance Certification Investment | ECHA PAH testing infrastructure unlocks European sports surface procurement and premium-tier pricing access. |
| Direct-to-Contractor Digital Platform Launch | B2B marketplaces disintermediate traditional distributors and capture margin from asphalt paving contractors. |
| State-Approved Supplier Status Acquisition | EPA state-delegated program qualification locks in multi-year highway rehabilitation offtake volumes. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning tire collection network operators, asphalt terminal procurement managers, sports field installation contractors, and cryogenic processing plant engineers. Secondary sources incorporated EPA state-delegated program documentation, ECHA REACH restriction updates, Bureau of Indian Standards draft protocols, and ASTM D5644 testing records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation across volume shipments, certification database entries, and state contract award notices informed the analytical framework. Segmentation dimensions modeled include particle size grade, processing technology intensity, end-use application specification, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of historical procurement volumes weighted by mandate implementation timelines. Cryogenic processing capacity utilization rates and state highway agency rehabilitation schedule acceleration served as industry-specific forecast inputs.
Inputs from EPA state-delegated programs and ECHA compliance registries were available through the study window; gaps in real-time tire collection volume reporting introduce uncertainty bands around feedstock cost assumptions. Forecasts reflect documented mandate implementation trajectories and processor capacity expansion announcements. Practitioners should monitor state-level rubber-modified asphalt specification adoption rates and ECHA PAH limit enforcement intensity for early demand shift signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Europe Silicone Rubber Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Choppers Market
Rubber
Rubber Molding Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Rubber Conveyor Belt Market
Rubber
Rubber Sand Market
Rubber
FKM Elastomers Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Tire Chemicals Market
Rubber
Polyisoprene Market
Rubber
Butyl Rubber Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Masterbatch Market
Rubber
Rubber Gloves Market
Rubber
Isoprene Rubber (IR) Latex Market