
 Muconic Acid Market | 2026-2036
Muconic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Muconic Acid Market Analysis
Biocatalytic fermentation pathways is rewriting production economics for muconic acid, displacing petroleum-derived routes with sugar-based feedstocks. Thermo Fisher Scientific Inc. leverages its analytical reagent portfolio to dominate high-purity segments for research applications. Amyris Inc. anchors its position through microbial strain engineering that improves yield titers. Merck KGaA competes across pharmaceutical-grade supply chains with integrated quality systems.
Muconic acid is a dicarboxylic acid with conjugated double bonds, typically produced at 95-99% purity through microbial fermentation of glucose or chemically via oxidation of aromatic precursors; it serves as a platform chemical for producing adipic acid, terephthalic acid, and other polymer intermediates. Bio-based muconic acid captures premium positioning as brand owners enforce Scope 3 emissions targets, while synthetic variants retain cost advantages in commodity plastics. Pharmaceutical applications command the highest margin pools due to stringent purity certifications, whereas adhesives and coatings segments absorb volume as construction and automotive sectors expand bio-content requirements.
The EPA administers bio-preferred procurement mandates that steer federal purchasing toward certified biobased chemicals, while REACH registration in Europe imposes toxicity documentation burdens on importers. FDA oversight of pharmaceutical-grade muconic acid constrains supplier qualification timelines for drug intermediate applications. Stakeholders must track fermentation yield improvements against petrochemical price volatility to determine optimal capacity timing.
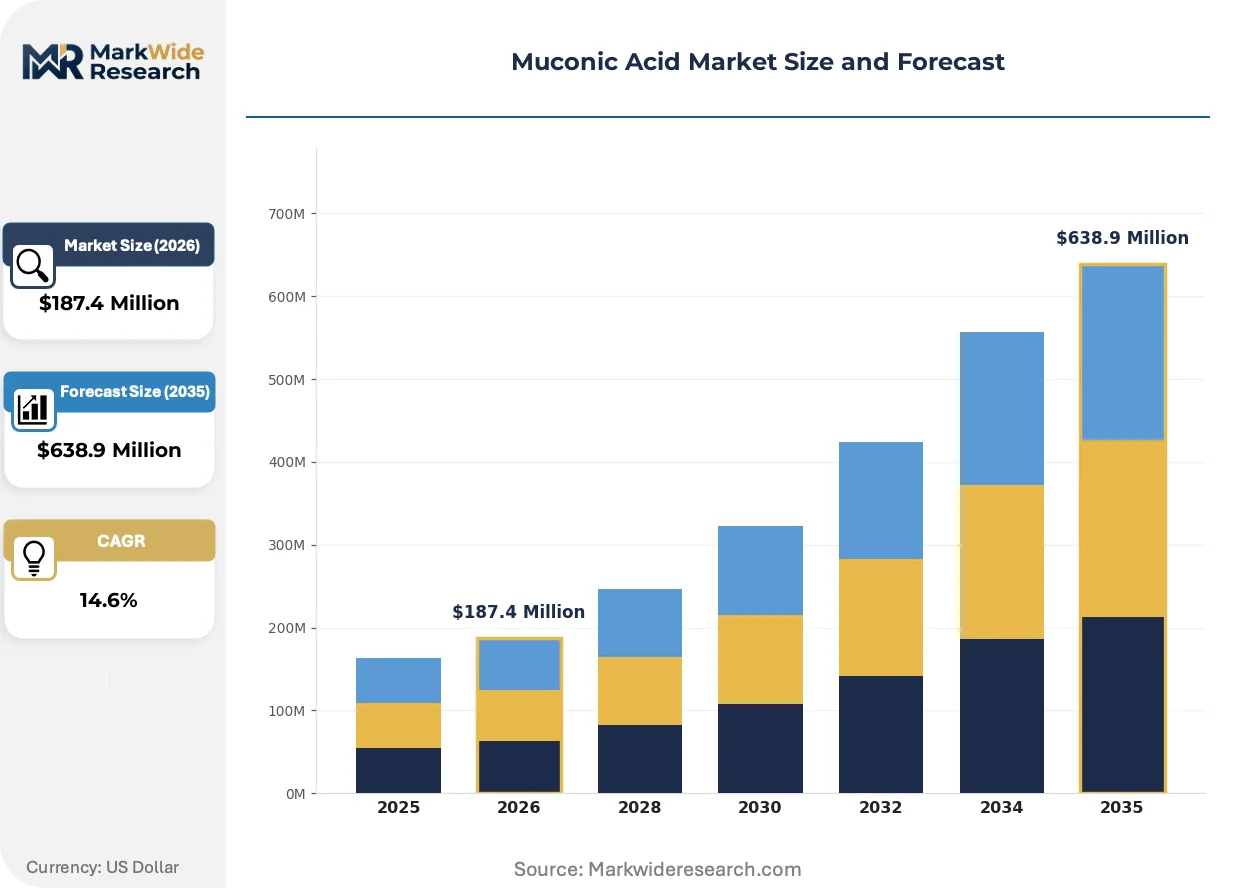
Market Dynamics
Biocatalytic fermentation is compressing production costs for muconic acid, forcing petroleum-derived routes into niche high-volume applications as sugar-based feedstocks achieve cost parity.
Growth Catalysts
- EPA Bio-Preferred Mandates:Federal procurement rules in the United States steer institutional purchasing toward certified biobased chemicals, creating guaranteed offtake for fermentation-derived supply.
- Automotive Lightweighting:OEMs in Germany's industrial corridor are substituting petroleum-based adipic acid precursors with bio-muconic acid to meet Scope 3 emissions targets for interior polymer components.
- Glucose Feedstock Infrastructure:Corn belt processing clusters in the United States provide integrated sugar supply chains that reduce logistics costs for fermentation facilities.
Market Restraints
- Petrochemical Price Volatility:Benzene oxidation routes retain cost advantages when crude oil prices dip below fermentation breakeven thresholds, pressuring bio-based margins.
- REACH Documentation Burdens:ECHA registration requirements in Europe impose toxicity testing costs that disproportionately burden small-volume importers versus integrated producers.
- Purification Bottlenecks:Crystallization and chromatographic separation steps limit batch throughput for pharmaceutical-grade material, constraining high-margin supply expansion.
Strategic Opportunities
- Adipic Acid Displacement:Nylon 6,6 producers in China are piloting muconic acid as a direct terephthalic acid precursor, opening polymer intermediate markets beyond traditional specialty applications.
- CSRD-Aligned Sourcing:The EU Corporate Sustainability Reporting Directive creates procurement incentives for Scope 3 traceable chemicals, favoring fermentation routes with verified carbon accounting.
- Continuous Fermentation Systems:Integration of cell retention technology with real-time metabolite monitoring is hybridizing batch and continuous processing, promising yield improvements.
Industry Challenges
- Strain Engineering Talent Scarcity:Microbial metabolic pathway optimization requires rare combinations of synthetic biology and chemical engineering expertise, lengthening R&D timelines.
- FDA Qualification Durations:Pharmaceutical-grade muconic acid requires 18-24 month drug master file approvals, delaying revenue recognition for new production capacity.
- Downstream Integration Complexity:Polymer manufacturers face reformulation costs when switching from petroleum-derived to bio-based acid inputs, slowing adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muconic Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Muconic Acid, Synthetic Muconic Acid, Biofuel, Biopolymers Application: Adhesives, Coatings, Plastics, Pharmaceuticals End User: Automotive, Consumer Goods, Textile, Electronics Distribution Channel: Online, Direct Sales, Wholesalers, Retail |
| Companies Covered | Thermo Fisher Scientific Inc., Tokyo Chemical Industry Co. Ltd., Santa Cruz Biotechnology Inc., PTT Global Chemicals (Myriant), Toronto Research Chemicals Inc., Merck KGaA, Sigma-Aldrich, Deinove, Amyris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muconic Acid Market Emerging Trajectories
Fermentation technology convergence with synthetic biology tools is rewriting process economics, while regulatory carbon accounting and automotive material specifications reshape demand patterns.
Metabolic engineering platforms are hybridizing CRISPR-based strain development with automated bioreactor control systems. Specialty chemical manufacturers in Germany are deploying these integrated systems to push muconic acid titers past conventional thresholds. The technology is compressing capital requirements for commercial-scale facilities by reducing bioreactor volume needs.
REACH registration deadlines in Europe are tightening toxicity documentation requirements for imported aromatic chemicals. ECHA enforcement actions against incomplete dossiers are redirecting supply chain sourcing toward EU-registered fermentation producers. Pharmaceutical intermediates face the steepest compliance cost escalations, accelerating vertical integration by drug manufacturers.
Automotive OEMs are mandating mass-balance certified bio-content for interior polymer components. Tier-1 suppliers in Germany are restructuring procurement contracts to require third-party verified Scope 3 emissions data for acid precursors. This specification shift is visible across luxury vehicle platforms where brand positioning depends on sustainability credentials.
Muconic Acid Market Segmentation
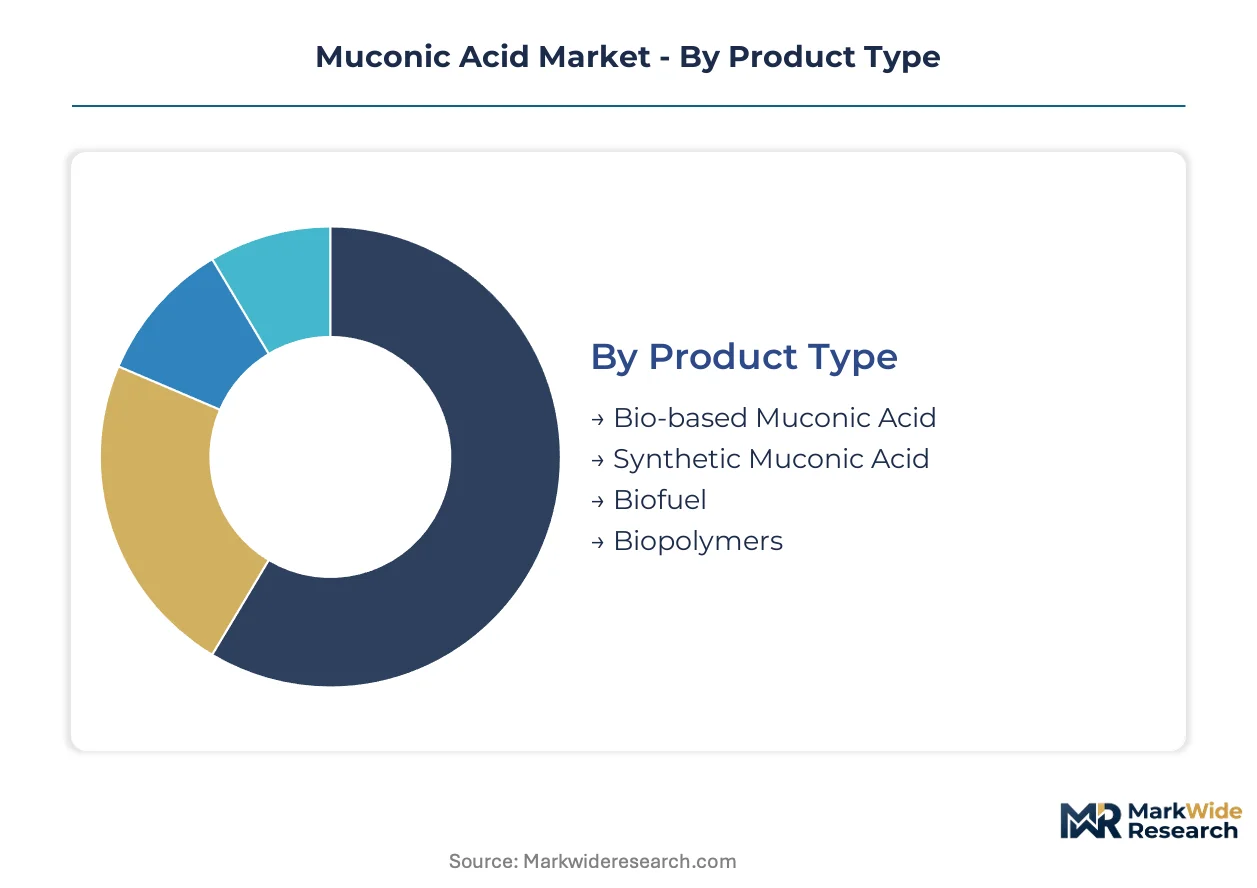
Muconic acid segmentation reveals how production chemistry, application requirements, and end-use specifications fragment pricing and procurement patterns across industrial supply chains.
Product Type:
Product chemistry determines carbon accounting eligibility and regulatory qualification pathways across downstream applications.
- Bio-based Muconic Acid:Fermentation-derived material from glucose feedstocks qualifies for EPA bio-preferred procurement and EU CSRD-aligned Scope 3 reporting. German automotive OEMs in the industrial corridor specify mass-balance certified bio-content for interior polymer components to meet emissions targets.
- Synthetic Muconic Acid:Benzene oxidation routes retain cost advantages during periods of crude oil price depression. Petrochemical manufacturers leverage existing aromatic infrastructure to serve commodity plastics producers in China where price sensitivity dominates procurement decisions.
- Biofuel:Lower-purity fermentation output serves energy applications with reduced purification overhead.
- Biopolymers:Polymer-grade material feeds specialty resin production for packaging and film applications.
The dominant share belongs to bio-based muconic acid, while synthetic variants are closing the gap fastest through cost volatility hedging.
Application:
Application tiers stratify by purity certification burden and margin capture potential.
- Pharmaceuticals:Drug intermediate applications demand 99%+ purity with FDA drug master file documentation. Amyris and Merck KGaA compete through integrated quality systems that compress 18-24 month qualification timelines.
- Plastics:Nylon 6,6 and polyester precursor markets absorb the highest volume volumes as Chinese producers pilot muconic acid as direct terephthalic acid replacement.
- Adhesives:Construction sector bio-content mandates in Germany drive specification shifts.
- Coatings:Automotive refinish and industrial protective applications require intermediate purity grades.
Pharmaceuticals commands premium positioning, while plastics is expanding most quickly through polymer intermediate substitution.
End User:
End-user concentration tracks regional manufacturing clusters and material specification enforcement.
- Automotive:OEM lightweighting programs in Germany substitute petroleum-based adipic acid precursors with bio-muconic acid for interior components. Tier-1 suppliers restructure procurement contracts around third-party verified Scope 3 emissions data.
- Consumer Goods:Brand owners enforce packaging bio-content thresholds that cascade to acid precursor sourcing.
- Textile:Nylon fiber producers evaluate muconic acid for sustainable apparel supply chains.
- Electronics:Specialty polymer encapsulants for circuit boards create niche high-purity demand.
Automotive anchors current volume, with consumer goods gaining share fastest through brand sustainability commitments.
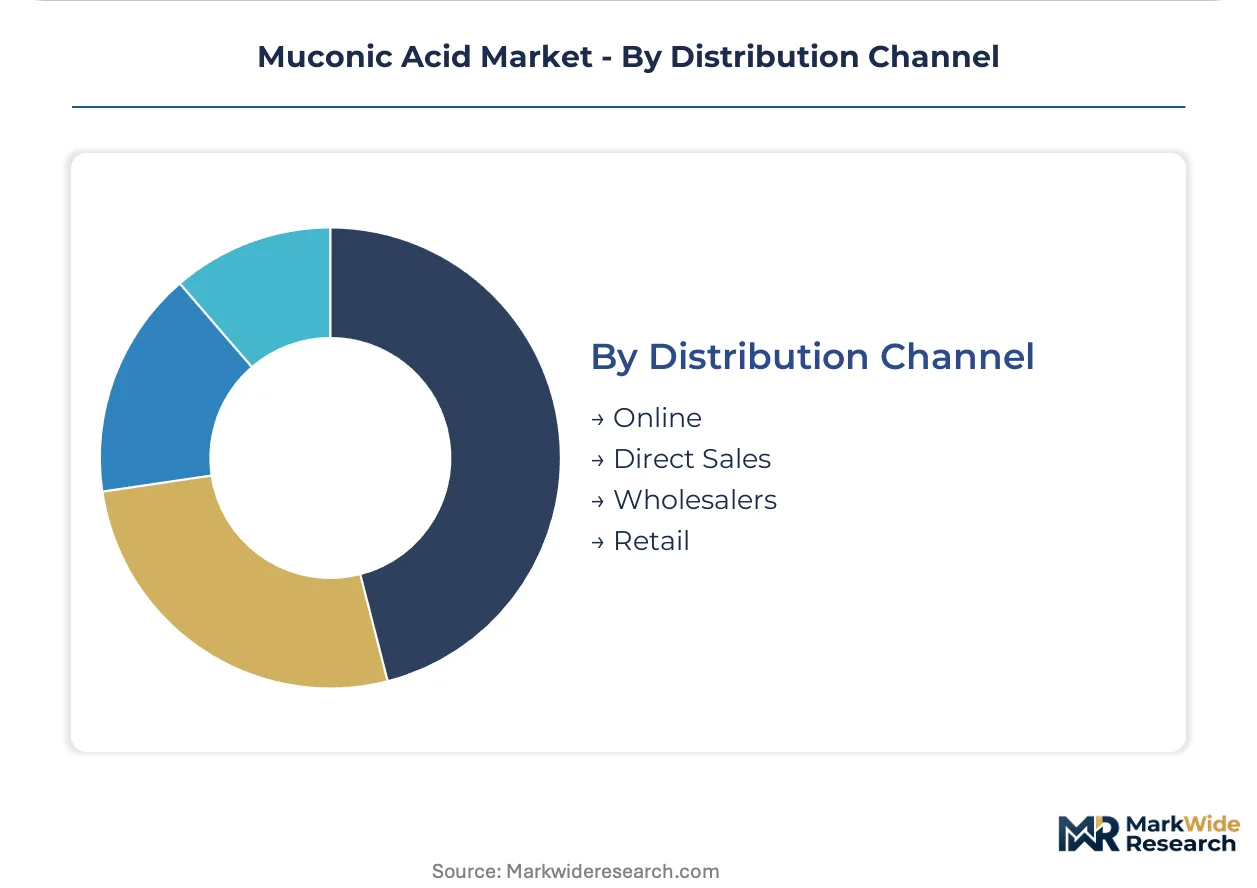
Distribution Channel:
Channel structure reflects customer scale and technical service requirements.
- Direct Sales:Integrated producers like Thermo Fisher Scientific and Amyris serve pharmaceutical and research customers through dedicated technical account management.
- Wholesalers:Regional chemical distributors stock standard grades for mid-volume plastics and coatings processors.
- Online:Digital platforms capture small-laboratory and research-scale procurement with rapid fulfillment.
- Retail:Limited to specialty chemical outlets serving individual researchers and educational institutions.
Direct sales captures the dominant share, while online channels are climbing the fastest through research customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in muconic acid track fermentation capacity buildouts against petrochemical arbitrage windows. The United States runs a structural surplus in bio-based grades through corn belt processing clusters, while Germany and China compete for import share across European and Asian polymer supply chains respectively.
United States
EPA bio-preferred procurement mandates steer federal purchasing toward certified biobased chemicals, creating guaranteed offtake for fermentation-derived supply. The USDA administers loan guarantee programs for biorefinery construction in corn belt states. Iowa and Illinois processing clusters provide integrated glucose supply chains that reduce logistics costs for commercial-scale facilities.
Germany
Automotive OEM lightweighting programs substitute petroleum-based adipic acid precursors with bio-muconic acid for interior polymer components. ECHA REACH registration requirements impose toxicity documentation burdens that favor domestic fermentation producers over importers. The industrial chemical corridor around Ludwigshafen and Leverkusen clusters specialty manufacturers near feedstock infrastructure and automotive tier-1 suppliers.
China
Nylon 6,6 producers pilot muconic acid as a direct terephthalic acid precursor, opening polymer intermediate markets beyond traditional specialty applications. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for petrochemical oxidation routes. The Yangtze River Delta concentration of polyester manufacturers creates demand pull for alternative acid precursors.
Japan
Pharmaceutical-grade muconic acid demand concentrates in drug intermediate applications requiring 99%+ purity certification. METI administers biomanufacturing competitiveness programs that subsidize fermentation technology adoption. The Kansai region around Osaka hosts specialty chemical producers serving domestic pharmaceutical supply chains with integrated quality systems.
India
Construction sector bio-content mandates in infrastructure projects drive specification shifts toward bio-based adhesives and coatings. The Bureau of Indian Standards develops biopolymer certification frameworks that cascade to acid precursor sourcing requirements. Gujarat's chemical manufacturing belt attracts fermentation facility investments through port infrastructure and feedstock access.
Muconic Acid Market Vendor Landscape
On the supply side, the industry is consolidating around integrated fermentation specialists and diversified chemical conglomerates with quality system capabilities. Thermo Fisher Scientific and Merck KGaA anchor premium-tier positioning through analytical reagent portfolios and pharmaceutical-grade supply chains. Amyris and Deinove represent pure-play biomanufacturing archetypes competing on strain engineering yield titers. Strategic moves concentrate on backward integration into glucose feedstock sourcing and capacity expansion in corn belt processing clusters.
Within the diversified chemical conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions spanning research reagents through pharmaceutical intermediates. Among pure-play biomanufacturing specialists, Amyris Inc. and Deinove exemplify microbial strain engineering approaches. Tokyo Chemical Industry Co. Ltd. anchors the fine chemical distributor archetype serving laboratory-scale demand across Asia-Pacific markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Tokyo Chemical Industry Co. Ltd. |
| Santa Cruz Biotechnology Inc. |
| PTT Global Chemicals (Myriant) |
| Toronto Research Chemicals Inc. |
| Merck KGaA |
| Sigma-Aldrich |
| Deinove |
| Amyris Inc. |
| Others |
Supply Flow & Price Mechanics
REACH documentation burdens for ECHA registration concentrate pricing power among integrated fermentation producers with captive analytical capabilities, compressing spreads between pharmaceutical-grade and industrial-grade tiers while reshaping procurement toward EU-registered supply chains.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical-grade material commanding substantial premiums over polymer-grade supply due to FDA drug master file certification requirements. Price differentiation hinges on purity thresholds and mass-balance carbon accounting verification, with automotive tier-1 suppliers in Germany showing least price sensitivity for Scope 3-compliant feedstocks. Cost compression in commodity synthetic grades intensifies when crude oil prices dip below fermentation breakeven thresholds.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for fermentation equipment and specialty separation media. Production gravity centers on Iowa and Illinois corn belt clusters for glucose feedstock access, Germany's Ludwigshafen corridor for automotive integration, and China's Yangtze River Delta for polymer intermediate demand. The chain draws from corn wet milling infrastructure, microbial strain libraries, and chromatographic purification resins. Distribution runs through direct technical account management for pharmaceutical customers and regional chemical distributors for standard industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The muconic acid market sits at a platform-economics inflection where metabolic engineering toolkits are commoditizing strain development, eroding proprietary yield advantages and shifting value capture toward downstream formulation integration and carbon accounting verification systems.
For Market Incumbents: Entrench position through backward integration into corn belt glucose supply chains and captive analytical certification capabilities that compress customer qualification timelines. Amyris and Merck KGaA demonstrate how integrated quality systems defend against emerging strain engineering specialists by locking pharmaceutical customers into 18-24 month drug master file approval cycles.
For New Entrants and Emerging Players: Pursue white-space opportunities in continuous fermentation technology licensing and CSRD-aligned carbon accounting software layers that attach to commodity acid supply. The most penetrable entry point sits with Chinese nylon 6,6 producers piloting terephthalic acid substitution, where technical service partnerships circumvent incumbent qualification barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated biomanufacturing platforms with demonstrated pharmaceutical-grade production histories. Long-term viability over the next decade rests on fermentation yield trajectories outpacing petrochemical cost volatility. The signal to watch is FDA drug master file submission velocity by emerging producers as an indicator of qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Corn belt processing clusters in Iowa reduce logistics exposure and secure EPA bio-preferred certification pathways. |
| Continuous Fermentation Technology Deployment | Cell retention systems with real-time metabolite monitoring compress capital requirements for commercial-scale facilities. |
| Pharmaceutical-Grade Certification Investment | FDA drug master file approvals create 18-24 month customer lock-in for high-margin drug intermediate supply. |
| CSRD-Aligned Carbon Accounting Verification | Third-party Scope 3 emissions documentation captures procurement mandates from German automotive OEMs. |
| Joint Venture with Polymer Manufacturers | Reformulation cost-sharing agreements accelerate bio-muconic acid adoption in nylon 6,6 and polyester precursor markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, automotive tier-1 procurement leads, pharmaceutical regulatory affairs directors, and specialty chemical distribution partners; and secondary validation against ECHA REACH registration databases, EPA bio-preferred certified product listings, USDA biorefinery loan guarantee disclosures, and SEC filings by publicly traded biomanufacturing specialists. Bottom-up capacity buildout tracking triangulated against top-down demand modeling from automotive lightweighting specifications and pharmaceutical intermediate consumption patterns.
Forecast inputs incorporated fermentation yield improvement curves, crude oil price scenario modeling, and regulatory procurement mandate enforcement timelines across the projection horizon. Segmentation dimensions included production chemistry type, purity grade tier, end-use application, and regional manufacturing cluster. CAGRs were derived from S-curve adoption modeling for bio-based polymer intermediates and elasticity-adjusted demand functions for pharmaceutical-grade supply.
Sensitivities concentrate around strain engineering breakthroughs that displace current titers, petrochemical price volatility breakeven recalculations, and ECHA enforcement intensity against incomplete REACH dossiers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Diisopropylbenzene Market