
 Global Sodium Sulfate Market | 2026-2036
Global Sodium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Sulfate Market Foresight
Multi-source procurement among sodium sulfate consumers is broadening as buyers diversify away from concentrated lake-mineral dependence. Solvay leverages its synthetic production expertise to supply European detergent and glass makers with consistent, high-purity material. Tata Chemicals sustains a formidable position through backward integration into Sambhar Lake brine operations in India. Nouryon Chemicals competes on specialized anhydrous grades tailored to pharmaceutical and fine chemical applications.
Sodium sulfate, whether extracted as Glauber salt from natural brine deposits or manufactured synthetically via the Mannheim or Hargreaves process, functions primarily as an inert filler, viscosity modifier, and processing aid across industrial formulations. The anhydrous variant dominates volume flows into glass manufacturing, where its low iron content and thermal stability prove critical to molten batch chemistry. Detergent applications still anchor the largest demand pool, though pulp and paper processing represents a faster-growing outlet as mills reformulate bleaching sequences. Packaging in bulk and super sacks captures the margin concentration, reflecting the commodity economics of high-volume, low-unit-value chemical distribution.
China's MEE enforces stricter wastewater discharge limits on Glauber salt extraction, while India's CEA monitors brine withdrawal rates at Rajasthan lake beds. REACH compliance in Europe restricts heavy metal thresholds in detergent-grade material, reshaping import sourcing patterns. Stakeholders must track how regulatory tightening on natural brine extraction interacts with synthetic capacity expansion decisions.
Market Dynamics
China's MEE wastewater discharge limits on Glauber salt extraction are compressing natural brine output while Indonesia's consumer goods corridor pulls synthetic capacity expansion toward Southeast Asia.
Growth Catalysts
- Detergent formulation expansion:Southeast Asian consumer goods manufacturers are scaling sodium sulfate loading as a builder ingredient in powder detergents.
- REACH heavy metal thresholds:European compliance mandates on detergent-grade material are redirecting import sourcing toward certified synthetic producers.
- Pulp mill bleaching reformulation:Kraft processors are substituting chlorine dioxide sequences with sodium sulfate-dependent oxygen delignification stages.
Market Restraints
- Natural brine withdrawal limits:India's CEA monitors extraction rates at Rajasthan lake beds, constraining seasonal output variability.
- Energy cost volatility:Synthetic Mannheim process operations face natural gas price swings that compress margin structures.
- By-product gypsum displacement:Flue gas desulfurization waste streams compete as low-cost filler alternatives in construction applications.
Strategic Opportunities
- Pharmaceutical-grade anhydrous white space:Fine chemical manufacturers in Germany seek high-purity material for injectable excipient applications.
- Dual carbon policy alignment:China's synthetic process investments qualify for provincial green financing under national decarbonization targets.
- Direct mill procurement channels:Glass manufacturers are bypassing distributors to contract directly with synthetic producers for molten batch supply.
Industry Challenges
- Brine chemistry expertise scarcity:Lake-based extraction operations lack trained process engineers capable of managing seasonal crystallization cycles.
- Multi-jurisdiction certification timelines:REACH, BIS, and GB standard compliance requires parallel testing protocols that extend product qualification windows.
- Legacy bulk handling infrastructure:Port terminals and inland depots need pneumatic conveying upgrades to handle anhydrous material without moisture contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Sulfate Market |
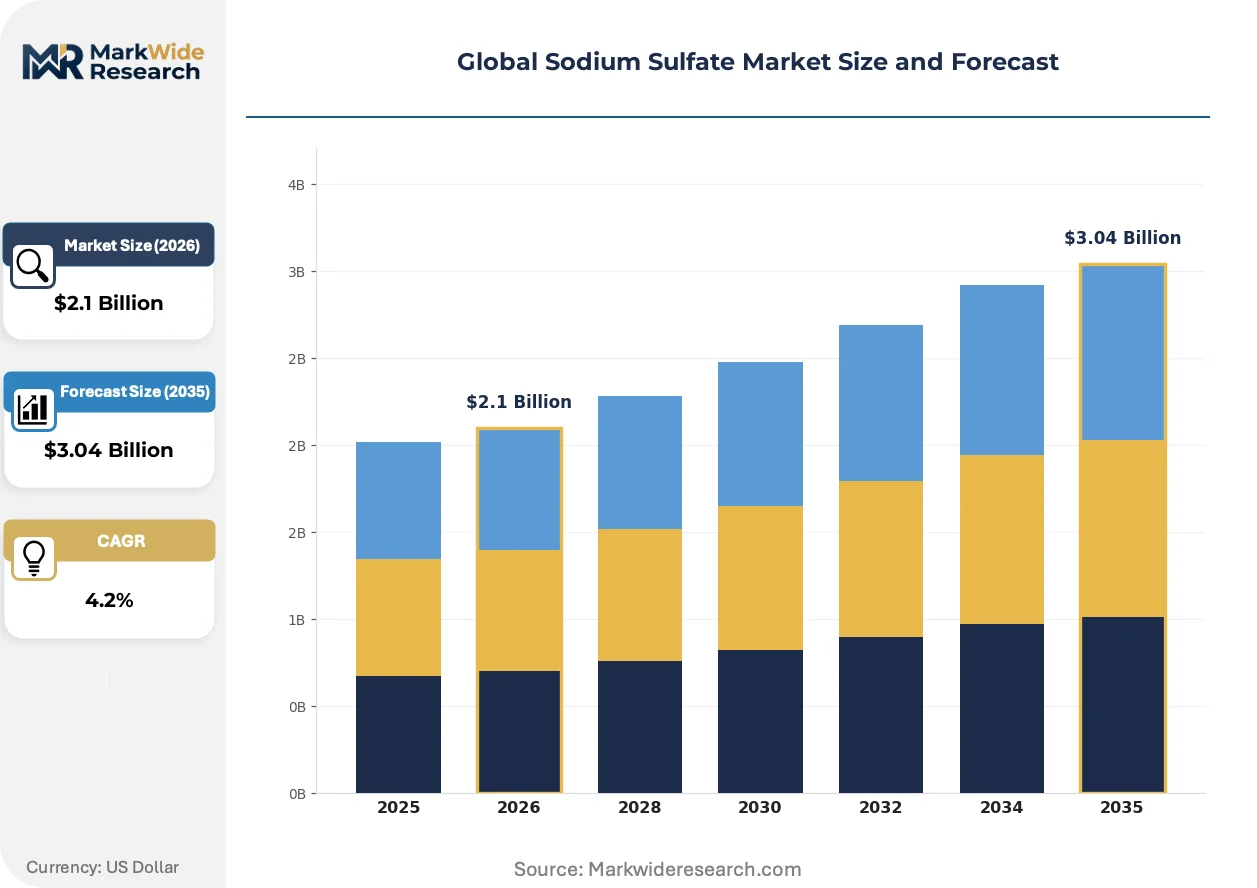
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decahydrate, Anhydrous, Glauber Salt, Thenardite End Use Industry: Detergents, Glass Manufacturing, Pulp & Paper, Textile Processing, Chemical Processing Application: Builder in Detergents, Filler in Glass, Drying Agent, Additive in Dyeing, Catalyst Carrier Packaging Type: Bags, Bulk, Drums, Super Sacks, Boxes |
| Companies Covered | Tata Chemicals Limited, Solvay, BASF, Searles Valley Minerals, Nouryon Chemicals, Nippon Chemical Industrial, Nirma Limited, Gujarat Alkalies and Chemicals Limited, Elementis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Sulfate Market Shifts & Advancements
Process intensification and regulatory tightening are compressing the cost advantage of natural brine extraction while synthetic producers capture margin through purity differentiation.
Membrane filtration technology is integrating into synthetic sodium sulfate crystallization circuits. European detergent compounders are adopting ceramic membrane systems to reduce energy consumption in anhydrous production. This integration is compressing the capital cost gap between lake-derived and manufactured material.
REACH heavy metal thresholds are tightening import specifications for detergent-grade sodium sulfate entering European ports. The regulation forces Asian exporters to certify batch-level contamination limits before customs clearance. Glass manufacturers in Italy and Germany now require supplier documentation tracing iron content below 50 ppm.
Glass manufacturers are consolidating purchase volumes through direct mill contracts rather than regional distributors. Container glass producers in Turkey and Egypt negotiate annual tonnage commitments with synthetic producers in Spain and Russia. This channel compression is visible most acutely in Mediterranean basin procurement patterns.
Global Sodium Sulfate Market Segmentation
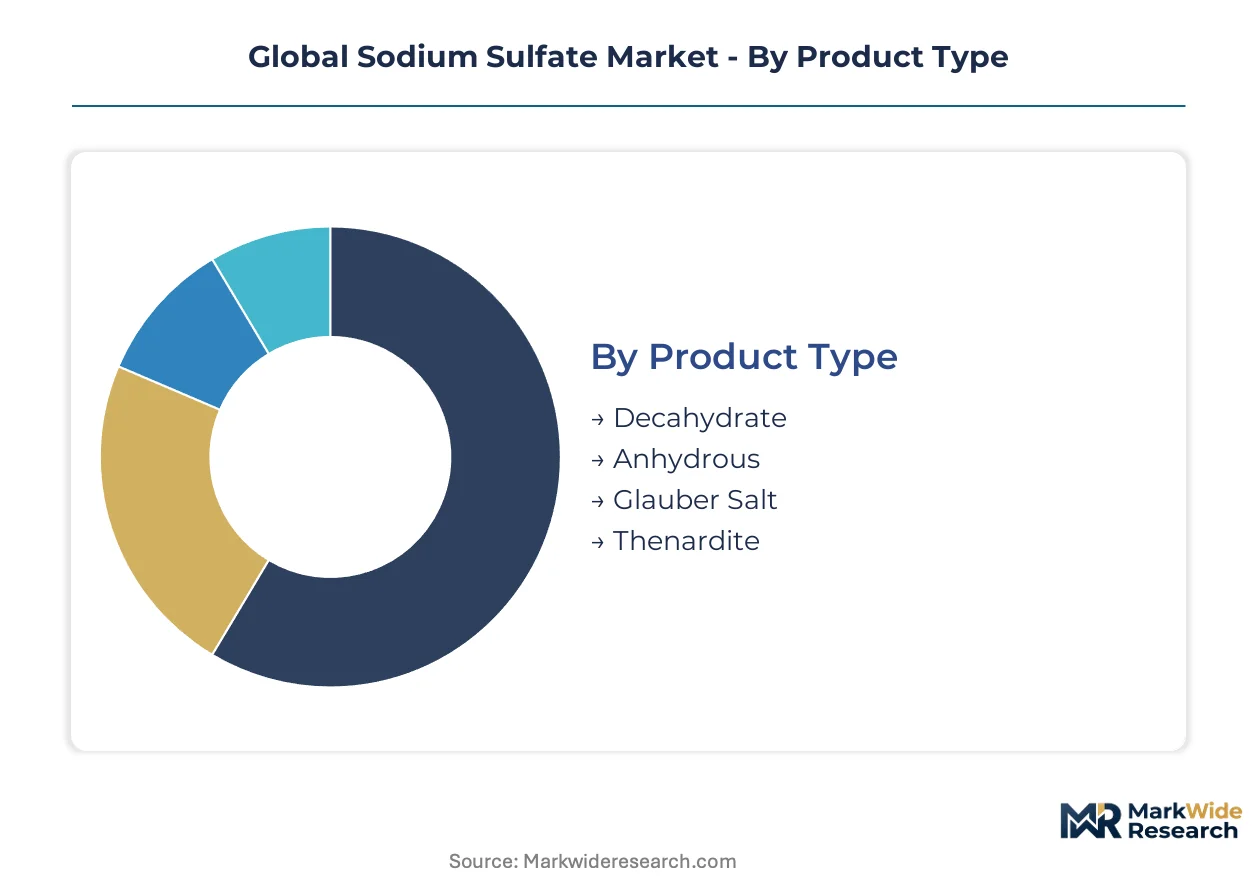
Sodium sulfate segmentation reflects divergent purity requirements across industrial applications. Certification burdens vary sharply between pharmaceutical-grade anhydrous and commodity detergent fillers.
Product Type:
Anhydrous and Glauber salt grades carry distinct certification obligations under REACH and GB standards, with hydrate forms facing additional moisture-content verification.
- Anhydrous:White crystalline powder with maximum 0.1% moisture content. Glass manufacturers in Italy and Germany specify iron content below 50 ppm for molten batch chemistry. This grade commands premium positioning through thermal stability in high-temperature processing.
- Glauber Salt:Decahydrate crystal extracted from natural brine deposits at Sambhar Lake and Chinese salt lakes. China's MEE wastewater discharge limits are compressing output from traditional lake-bed operations while synthetic capacity expands.
- Decahydrate:Ten-water hydrate serving lower-specification detergent and textile applications where moisture tolerance exists.
- Thenardite:Naturally occurring anhydrous mineral form with limited commercial extraction, primarily sourced from evaporite deposits in Spain and Chile.
Anhydrous sits at the top of the volume ranking, with Glauber salt climbing the fastest as Southeast Asian detergent manufacturers scale powder formulation output.
End Use Industry:
Cost tier stratification separates premium pharmaceutical and glass applications from commodity detergent and textile processing.
- Detergents:Builder ingredient in powder formulations, functioning as inert filler and viscosity modifier. Indonesia's consumer goods corridor is pulling synthetic capacity expansion toward Southeast Asia as manufacturers increase sodium sulfate loading.
- Glass Manufacturing:Critical molten batch component where low iron content and thermal stability determine optical clarity. Container glass producers in Turkey and Egypt now negotiate direct annual tonnage commitments with synthetic producers.
- Pulp & Paper:Oxygen delignification sequences in Kraft mills are substituting chlorine dioxide stages, creating faster expansion in this outlet than traditional detergent demand.
- Textile Processing:Dyeing auxiliary and leveling agent in fiber treatment, operating at lower purity thresholds than glass or pharmaceutical grades.
- Chemical Processing:Intermediate feedstock and process aid across fine chemical synthesis, with specialized anhydrous grades serving pharmaceutical excipient applications in Germany.
Glass manufacturing commands the highest margin tier, with pulp and paper gaining share fastest through bleaching sequence reformulation.
Application:
Volume concentration tracks toward high-throughput industrial processes with standardized material specifications.
- Builder in Detergents:Primary functional role as inert filler in powder detergent matrices. Southeast Asian consumer goods manufacturers are scaling loading rates as builder ingredient.
- Filler in Glass:Molten batch constituent providing sulfate source for refining and fining operations. Direct mill procurement channels are compressing distributor margins in Mediterranean basin patterns.
- Drying Agent:Desiccant applications in organic synthesis and gas drying, requiring anhydrous specification.
- Additive in Dyeing:Leveling agent and salt carrier in textile coloration processes.
- Catalyst Carrier:Support material in petrochemical and fine chemical catalysis, with pore structure requirements.
Builder in detergents anchors volume flows, with filler in glass expanding most quickly through direct procurement consolidation.
Packaging Type:
Customer type determines packaging economics, with bulk handling infrastructure investments favoring synthetic producers serving large-volume glass and detergent compounders.
- Bulk:Unpackaged material delivered via pneumatic conveying systems to integrated manufacturing sites. Legacy port terminals and inland depots require moisture contamination prevention upgrades.
- Super Sacks:Intermediate bulk containers capturing margin concentration in commodity distribution. European detergent compounders favor this format for ceramic membrane-equipped crystallization facilities.
- Bags:Standard 25-50 kg woven polypropylene units for mid-scale textile and chemical processors.
- Drums:Sealed steel or fiber containers for anhydrous pharmaceutical and fine chemical grades requiring contamination control.
- Boxes:Corrugated packaging for specialty and sample quantities in laboratory and pilot-scale applications.
Bulk dominates tonnage flows, with super sacks climbing fastest as regional detergent compounders upgrade handling infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial corridor concentrates the world's largest synthetic sodium sulfate capacity, with provincial green financing accelerating Mannheim process investments under national dual carbon targets.
China
MEE wastewater discharge limits on Glauber salt extraction are compressing natural brine output from Qinghai and Inner Mongolia salt lakes. Synthetic producers in Jiangsu and Shandong provinces capture displaced volume through membrane-equipped crystallization circuits. The dual carbon policy framework qualifies these investments for preferential lending rates.
Germany
REACH heavy metal thresholds redirect detergent-grade import sourcing toward certified synthetic producers with documented batch-level contamination controls. BASF and Solvay anchor the Rhine-Ruhr chemical cluster, supplying anhydrous material to container glass manufacturers in Bavaria and Baden-Württemberg. ECHA compliance documentation now traces iron content below 50 ppm for molten batch applications.
India
CEA-monitored brine withdrawal rates at Rajasthan's Sambhar Lake constrain seasonal output variability from Tata Chemicals' backward-integrated operations. Gujarat Alkalies and Chemicals Limited sustains synthetic capacity in the Gulf of Khambhat industrial zone. Detergent compounders in Maharashtra and Tamil Nadu diversify procurement across lake-derived and manufactured sources.
United States
Searles Valley Minerals operates the country's largest natural brine extraction complex in California's Searles Lake basin. EPA discharge permits govern seasonal crystallization pond management. Glass manufacturers in Ohio and Pennsylvania negotiate direct annual tonnage commitments, bypassing regional distributors.
Indonesia
The consumer goods corridor spanning Jakarta, Surabaya, and Bandung pulls synthetic capacity expansion toward Southeast Asia. Powder detergent manufacturers scale sodium sulfate loading as a builder ingredient. Import dependence on Chinese and Indian supply creates procurement vulnerability during monsoon logistics disruptions.
Global Sodium Sulfate Market Competitive Landscape
Global majors compete with regional champions across production technology and certification depth. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive synthetic capacity, lake-based specialists dependent on seasonal brine chemistry, and regional compounders serving detergent and textile markets. Dominant competitive moves include direct mill procurement channel compression and membrane filtration technology licensing.
Within the integrated chemical tier, Solvay and BASF occupy positions exemplifying European REACH compliance leadership, while Tata Chemicals anchors the natural brine extraction archetype through Sambhar Lake operations. Nouryon Chemicals represents the specialized anhydrous grade segment serving pharmaceutical and fine chemical applications.
| Leading Market Players |
|---|
| Tata Chemicals Limited |
| Solvay |
| BASF |
| Searles Valley Minerals |
| Nouryon Chemicals |
| Nippon Chemical Industrial |
| Nirma Limited |
| Gujarat Alkalies and Chemicals Limited |
| Elementis |
| Others |
Supply & Pricing Matrix
Natural gas feedstock costs for synthetic Mannheim process operations transmit directly through to anhydrous grade premiums, while lake-derived Glauber salt pricing fluctuates with seasonal crystallization yields at Rajasthan and Qinghai extraction sites. This input-cost architecture stratifies buyer procurement choices between contract-stabilized synthetic supply and spot-market natural brine dependence.
Pricing Analysis
Input-cost pass-through from energy and brine chemistry dominates pricing formation across the sodium sulfate market. Three-tier pricing structure across pharmaceutical-grade anhydrous, detergent-grade standard, and industrial-economy Glauber salt levels separates premium purity certification from commodity filler applications. Cost compression in standard detergent grades is intensifying because membrane filtration technology narrows the capital gap between synthetic and natural extraction. Detergent compounders in Southeast Asia exhibit highest price sensitivity, while German pharmaceutical manufacturers accept substantial premiums for sub-50 ppm iron documentation.
Supply Chain Analysis
Reverse-logistics flows for super sack returns and bulk pneumatic system cleaning cycles add handling cost layers that synthetic producers absorb through integrated terminal operations. Supply concentrates in China, India, and the United States, with Jiangsu province and Sambhar Lake anchoring respective synthetic and natural output. Raw material dependencies center on natural gas for Mannheim process heat, sulfuric acid for chemical conversion, and seasonal brine chemistry for crystallization yields. Single-source vulnerability persists where Indonesian detergent manufacturers rely on monsoon-disrupted import channels. Distribution runs through direct mill procurement for glass manufacturers and regional distributor networks for textile processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium sulfate market represents a late-cycle quality story as REACH iron thresholds and pharmaceutical excipient specifications concentrate margin in certified anhydrous production. Glass manufacturers in Italy and Germany now mandate supplier documentation that only synthetic membrane-equipped facilities can reliably deliver.
For Market Incumbents: Hedge against natural brine withdrawal constraints by expanding synthetic capacity in Jiangsu and Shandong provinces where China's dual carbon policy unlocks green financing. Defensive consolidation through backward integration into sulfuric acid supply secures margin against energy volatility. Incumbents should deepen certification investments for REACH and BIS parallel compliance to extend qualification windows for pharmaceutical-grade contracts.
For New Entrants and Emerging Players: Begin with specialized anhydrous production for fine chemical and pharmaceutical applications in Germany, where ECHA documentation requirements create barrier-protected white space. The most penetrable segment lies in injectable excipient supply to Bavarian and Baden-Württemberg manufacturers. A go-to-market angle anchored to ceramic membrane technology licensing from European equipment suppliers accelerates qualification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale synthetic producers with membrane-equipped crystallization circuits because regulatory tightening on natural brine extraction is permanently displacing seasonal lake-dependent output. Long-term viability over the coming decade rests on acquiring facilities with existing REACH batch-certification protocols. The signal to watch is CEA withdrawal rate enforcement at Sambhar Lake, which would accelerate synthetic substitution and revalue Jiangsu-based capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive acid supply shields Solvay and BASF from feedstock volatility in Rhine-Ruhr operations. |
| Membrane Filtration Technology Licensing | Ceramic membrane adoption reduces energy consumption for European detergent compounders competing on carbon intensity. |
| Direct Mill Procurement Channel | Container glass producers in Turkey bypass distributors to contract annual tonnage with Spanish synthetic suppliers. |
| Pharmaceutical-Grade Certification Investment | Sub-50 ppm iron documentation opens injectable excipient supply to German fine chemical manufacturers. |
| Provincial Green Financing Qualification | Jiangsu synthetic investments capture preferential lending rates under China's national dual carbon targets. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at detergent compounders, technical R&D directors at glass manufacturers, and distribution channel partners — were reconciled against customs trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated chemical producers. Bottom-up capacity assessments at Sambhar Lake and Qinghai extraction sites were triangulated with top-down demand modeling across detergent, glass, and pulp end-use segments.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, packaging format preference, and regional production hub classification. CAGRs were derived through regression analysis of historical capacity utilization and forward-looking regulatory impact scenarios. Industry-specific forecast inputs incorporated MEE wastewater discharge enforcement timelines and CEA withdrawal rate monitoring protocols.
Several conditions sit outside the modeled scope, including abrupt natural gas price spikes, force majeure disruptions at Searles Lake operations, and unanticipated REACH threshold amendments. Forecasts reflect documented assumptions about synthetic capacity commissioning schedules and brine chemistry seasonal patterns. Practitioners should monitor CEA extraction permits, MEE enforcement actions, and Indonesian import logistics during monsoon periods for early signals of supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Stilbene Market