
 Asia-Pacific Airport Ground Handling Systems Market | 2026-2036
Asia-Pacific Airport Ground Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airport Ground Handling Systems Market Outlook
ISO 9001 certification for ground handling equipment manufacturing is rotating supplier eligibility across the Asia-Pacific region. BEUMER Group leverages its belt loader automation portfolio to anchor European-origin technology in Australian and Southeast Asian hubs. Weihai Guangtai Airport Equipment Co Ltd dominates electric ground power unit production for China's domestic airport expansion. John Bean Technologies Corporation competes through specialized de-icing and aircraft servicing platforms tailored to high-altitude Himalayan operations.
Asia-Pacific airport ground handling systems encompass the motorized, electronic, and software-driven equipment used to service aircraft during turnaround intervals, including belt loaders rated for 600-800 bags per hour and towbarless tugs handling narrow-body jets up to 75 metric tons. These systems minimize gate occupancy time and reduce fuel burn from auxiliary power units during ground operations. Ramp services represent the most equipment-intensive segment, with automated guided vehicles capturing expanding share in Singapore Changi and Incheon International configurations. Ground power units remain the mature hardware category where price competition from Chinese manufacturers compresses margins, while software integration for fleet telematics commands premium pricing from airlines seeking real-time turnaround analytics.
Japan's METI enforces JIS standards for ground support equipment electromagnetic compatibility, while China's MIIT mandates GB certification for electric tugs operating within domestic airport perimeters. Australia's Civil Aviation Safety Authority imposes strict occupational safety protocols that shape tow tractor design specifications. Stakeholders must weigh certification reciprocity gaps between national aviation authorities when configuring multi-country maintenance networks and spare parts logistics.
Market Dynamics
Automated guided vehicle deployment across Southeast Asian hub airports is compressing turnaround windows and forcing legacy equipment suppliers to accelerate software integration roadmaps or exit ramp services entirely.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for aviation infrastructure are accelerating domestic procurement of electric cargo loaders and towbarless tugs at tier-one airports undergoing modernization.
- Full-service carrier outsourcing:Southeast Asian legacy airlines are unbundling ground operations and awarding multi-year handling contracts to specialized service providers, expanding fleet refresh cycles.
- Electrification mandates:China's MIIT GB certification requirements for electric ground support equipment are displacing diesel-powered units from domestic airport perimeters.
Market Restraints
- Lithium battery supply concentration:Cathode and cell manufacturing for electric tugs and belt loaders concentrates in Chinese industrial clusters, exposing procurement to input cost volatility and export licensing friction.
- Certification reciprocity gaps:JIS electromagnetic compatibility standards enforced by Japan's METI lack mutual recognition with Australia's Civil Aviation Safety Authority protocols, fragmenting spare parts logistics across multi-country maintenance networks.
- Skilled technician scarcity:Automated guided vehicle fleets require mechatronics specialists capable of integrating mechanical, electrical, and software subsystems, a competency pool that remains shallow across Indonesian and Philippine aviation hubs.
Strategic Opportunities
- Vietnamese airport greenfield development:Long Thanh International Airport and Van Don International Airport expansions create first-mover openings for electric ground power unit suppliers establishing local service presence.
- Fleet telematics convergence:Integration of IoT sensors with predictive maintenance software enables real-time turnaround analytics, commanding premium pricing from full-service carriers seeking auxiliary power unit fuel burn reduction.
- Thailand's aviation infrastructure incentives:Board of Investment tax privileges for smart airport equipment manufacturing are attracting regional assembly operations for belt loader automation systems.
Industry Challenges
- Legacy system integration complexity:Automated guided vehicle deployment at established hubs like Singapore Changi and Incheon International requires retrofitting existing ramp control software, extending commissioning timelines.
- GB-to-JIS certification timeline compression:Equipment manufacturers serving both Chinese and Japanese markets face parallel compliance tracks with divergent electromagnetic testing protocols, stretching R&D resource allocation.
- High-altitude operational validation:De-icing and aircraft servicing platforms deployed at Himalayan airports must undergo specialized performance certification, limiting supplier eligibility for these contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airport Ground Handling Systems Market |
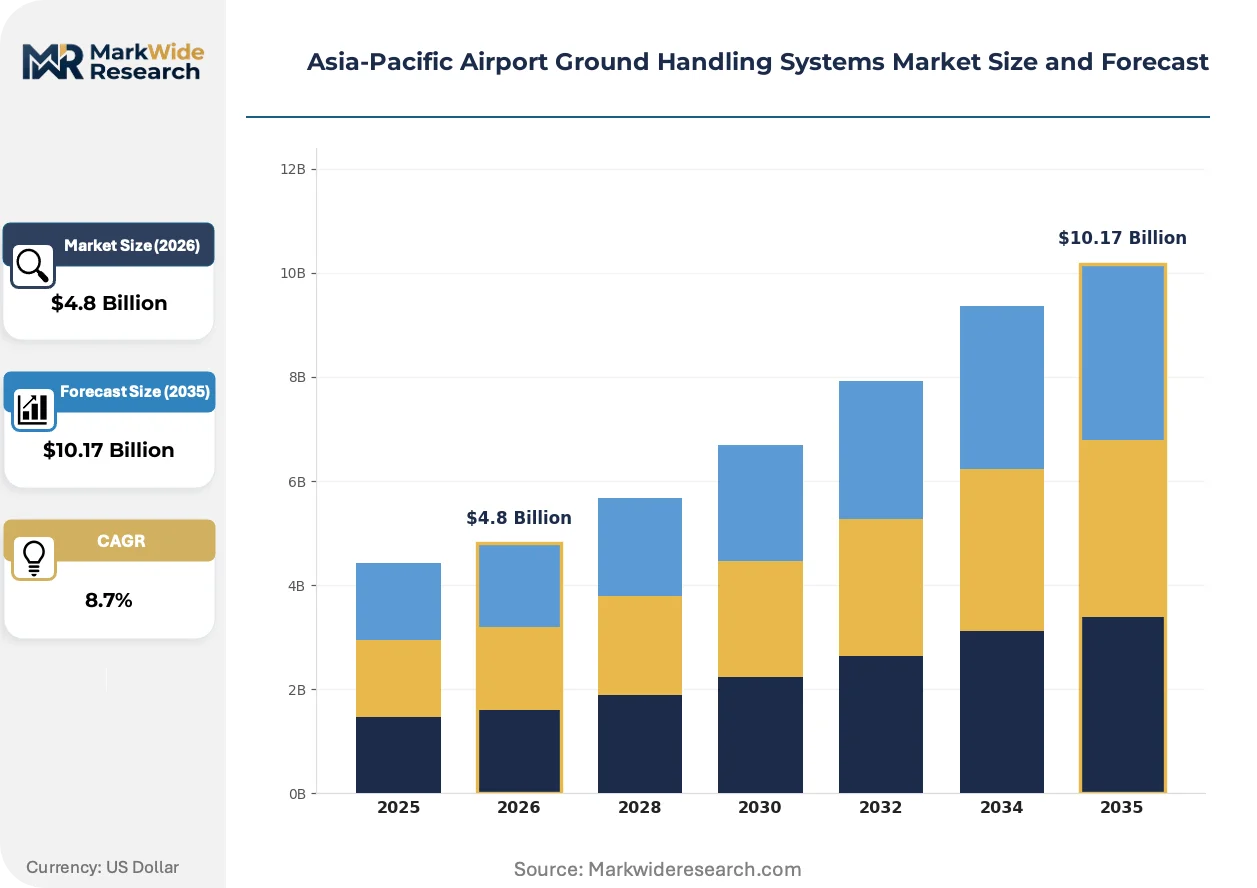
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Services, Ramp Services, Cargo Handling, Aircraft Maintenance Technology: Automated Systems, Belt Loaders, Tugs, Ground Power Units End User: Airports, Airlines, Ground Handling Companies, Third-Party Providers Solution: Software Integration, Fleet Management, Resource Allocation, Training Services |
| Companies Covered | Mototok International GmbH, BEUMER Group, John Bean Technologies Corporation, Weihai Guangtai Airport Equipment Co Ltd, Kalmar Motor AB, ADELTE Group S.L., Tronair Inc., ITW Inc, Cavotec SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airport Ground Handling Systems Market Strategic Shifts
Battery-electric propulsion and autonomous navigation are splitting equipment categories into distinct performance tiers, while regulatory pressure on carbon intensity accelerates hardware refresh cycles across major Asia-Pacific aviation hubs.
Electric ground power units rated for narrow-body and wide-body aircraft are bifurcating the mature hardware segment. Full-service carriers at Singapore Changi and Sydney Airport are specifying lithium-iron-phosphate variants for their 400Hz output stability, while budget operators at secondary Indian airports prioritize lead-acid alternatives for acquisition cost containment. This technology divergence is compressing margin structures for mid-tier suppliers caught between premium telematics integration and commodity price competition.
Japan's METI JIS C 1010 electromagnetic compatibility standards are tightening radiated emission limits for ground support equipment operating within 30 meters of aircraft navigation systems. Manufacturers must redesign motor controller shielding and cable routing to comply, adding 8-12 weeks to product validation timelines. Australian suppliers serving both Japanese and domestic markets are responding by establishing parallel certification tracks rather than pursuing mutual recognition agreements.
Ground handling service contracts are fragmenting from bundled full-ramp packages into discrete equipment-hour arrangements. Airlines at Kuala Lumpur International and Bangkok Suvarnabhumi are unbundling de-icing, cargo loading, and pushback services, awarding each to specialized operators. This disintermediation of integrated handlers is most visible in Southeast Asia, where new entrants with single-equipment expertise are capturing share from legacy full-service ground handlers.
Asia-Pacific Airport Ground Handling Systems Market Segmentation
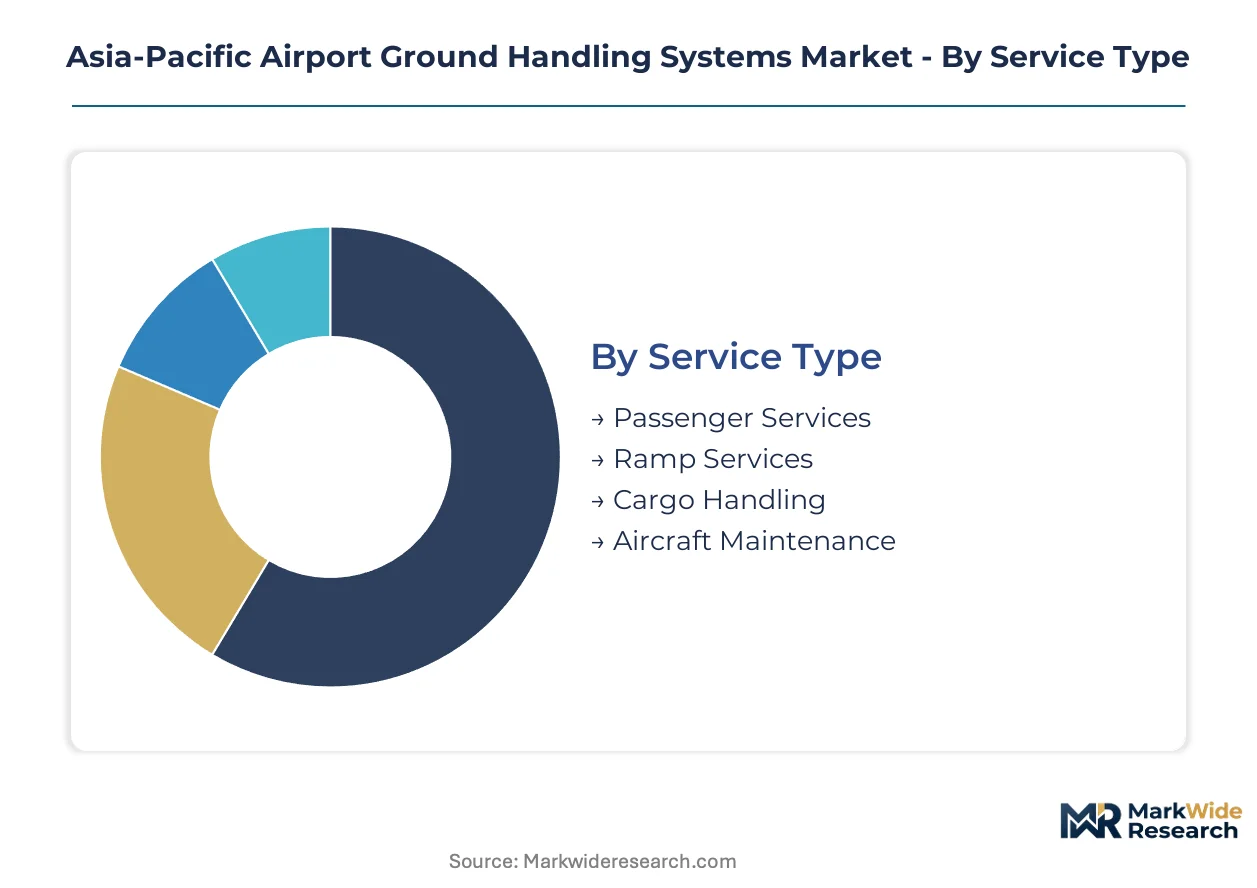
Segmentation in Asia-Pacific airport ground handling systems reveals where capital deployment concentrates and which technology categories face displacement from electrification mandates. Equipment buyers across tier-one hubs prioritize segments offering measurable turnaround compression and regulatory compliance pathways.
Service Type:
Substitution pressure runs strongest against labor-intensive segments where automated alternatives demonstrate quantifiable gate-time reduction at Singapore Changi and Incheon International.
- Ramp Services:Motorized equipment deployment including towbarless tugs and belt loaders dominates capital expenditure. Indian tier-one airport modernization programs under the PLI scheme are accelerating procurement of electric cargo loaders and automated guided vehicles for narrow-body turnaround operations.
- Cargo Handling:Automated cargo loaders rated for 600-800 bags per hour anchor fleet investment. China's MIIT GB certification requirements for electric ground support equipment are displacing diesel-powered units from domestic airport perimeters, reshaping supplier qualification.
- Passenger Services:Passenger boarding bridges and apron buses fall under this category. Equipment specifications vary by climate zone across Australian and Southeast Asian hubs.
- Aircraft Maintenance:Specialized de-icing and servicing platforms serve high-altitude Himalayan operations. Japan's METI JIS electromagnetic compatibility standards constrain supplier eligibility for equipment operating near aircraft navigation systems.
Ramp Services retains volume leadership; Cargo Handling holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium telematics-integrated systems from commodity hardware where Chinese manufacturing compresses margins.
- Ground Power Units:400Hz output systems for narrow-body and wide-body aircraft bifurcate into lithium-iron-phosphate variants at Singapore Changi and Sydney Airport versus lead-acid alternatives at secondary Indian airports. Full-service carriers specify premium stability; budget operators prioritize acquisition cost containment.
- Automated Systems:Autonomous guided vehicles and fleet telematics command premium pricing from airlines seeking real-time turnaround analytics. Deployment at established hubs requires retrofitting existing ramp control software, extending commissioning timelines.
- Belt Loaders:Equipment rated for 600-800 bags per hour serves cargo and baggage operations. Thailand's Board of Investment tax privileges are attracting regional assembly operations for automation systems.
- Tugs:Towbarless configurations handling narrow-body jets up to 75 metric tons dominate pushback operations. Electric variants face lithium battery supply concentration risks from Chinese industrial clusters.
Ground Power Units retains volume leadership; Automated Systems holds the steepest expansion curve.
End User:
Customer type determines contract structure, with unbundling trends fragmenting integrated service packages into discrete equipment-hour arrangements.
- Ground Handling Companies:Specialized operators capture disintermediated contracts for single-equipment expertise at Kuala Lumpur International and Bangkok Suvarnabhumi. Multi-year outsourcing awards from Southeast Asian legacy airlines are expanding fleet refresh cycles.
- Airlines:Full-service carriers specify premium telematics integration for auxiliary power unit fuel burn reduction. Unbundling of de-icing, cargo loading, and pushback services creates procurement complexity.
- Airports:Tier-one modernization programs in India and Vietnamese greenfield developments at Long Thanh International Airport drive capital equipment procurement. Regulatory compliance mandates shape specification requirements.
- Third-Party Providers:New entrants with focused equipment capabilities are capturing share from legacy integrated handlers across Indonesian and Philippine aviation hubs.
Ground Handling Companies retains volume leadership; Third-Party Providers holds the steepest expansion curve.
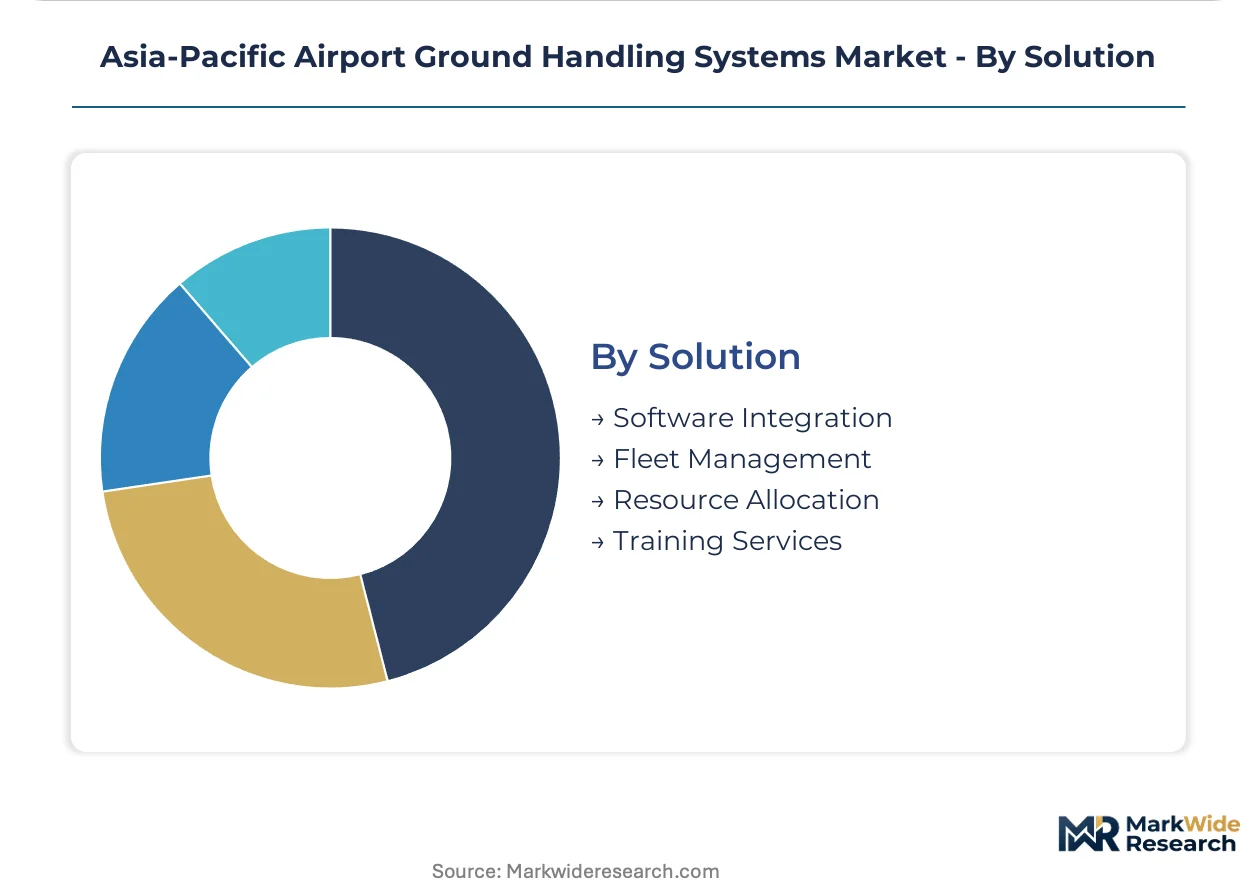
Solution:
Application maturity varies sharply, with software integration commanding premium pricing against commoditized training offerings.
- Software Integration:IoT sensor convergence with predictive maintenance platforms enables real-time turnaround analytics. Japan's METI JIS C 1010 electromagnetic compatibility standards add 8-12 weeks to product validation timelines for motor controller shielding redesigns.
- Fleet Management:Telematics systems track equipment utilization and maintenance scheduling across multi-airport networks. Certification reciprocity gaps between Japan's METI and Australia's Civil Aviation Safety Authority fragment spare parts logistics.
- Resource Allocation:Gate assignment and turnaround optimization software coordinates ground handling assets. Deployment complexity increases at established hubs requiring legacy system retrofit.
- Training Services:Mechatronics specialist development addresses automated guided vehicle maintenance requirements. Competency pools remain shallow across Indonesian and Philippine aviation hubs.
Software Integration retains volume leadership; Fleet Management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long Thanh International Airport anchors Vietnam's emergence as a ground handling systems demand center, with its 2025 phased opening triggering procurement of electric towbarless tugs and automated cargo loaders across Southeast Asian hub development.
China
Domestic airport perimeter electrification mandates from MIIT are displacing diesel-powered ground support equipment at Beijing Capital and Shanghai Pudong. GB certification requirements for electric tugs concentrate manufacturing in Shandong and Jiangsu industrial clusters. Weihai Guangtai anchors electric ground power unit production for tier-one hub modernization.
India
PLI scheme incentives for aviation infrastructure accelerate procurement of automated cargo loaders at Delhi Indira Gandhi and Mumbai Chhatrapati Shivaji. CEA mandates for airport electrification reshape specification requirements. Tier-one modernization programs concentrate demand in Maharashtra and Karnataka state airport authorities.
Japan
METI JIS C 1010 electromagnetic compatibility standards tighten radiated emission limits for equipment operating near aircraft navigation systems at Narita and Haneda. Eight-to-twelve-week validation extensions constrain supplier eligibility. Kanto region manufacturing clusters redesign motor controller shielding for compliance.
Australia
Civil Aviation Safety Authority occupational safety protocols shape tow tractor design specifications at Sydney and Melbourne Tullamarine. Certification reciprocity gaps with Japanese METI standards fragment spare parts logistics. Equipment procurement concentrates in New South Wales and Victoria state airport networks.
Singapore
Changi Airport automated guided vehicle deployment compresses turnaround windows and forces legacy equipment suppliers toward software integration. Real-time turnaround analytics command premium pricing from full-service carriers. The city-state's hub status drives fleet telematics convergence across Southeast Asian ground handling networks.
Asia-Pacific Airport Ground Handling Systems Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and technology tiers. The vendor base separates into three concentration levels: European-origin automation specialists, Chinese electric equipment fabricators, and diversified industrial conglomerates with aviation divisions. Strategic archetypes include certification-heavy incumbents defending multi-country maintenance networks, price-competitive electric hardware suppliers, and software-integrated platform providers. Dominant competitive moves center on parallel certification track establishment for JIS-GB dual compliance and regional assembly localization for Thai and Vietnamese market access.
Among European-origin specialists, BEUMER Group and Mototok International GmbH exemplify the automation-focused tier, while Weihai Guangtai Airport Equipment Co Ltd anchors Chinese electric ground power unit production. John Bean Technologies Corporation occupies a position representing specialized platform requirements for high-altitude operational validation. These three company structures illustrate the geographic and technological stratification defining competitive positioning across the region's certification-fragmented procurement environment.
| Leading Market Players |
|---|
| Mototok International GmbH |
| BEUMER Group |
| John Bean Technologies Corporation |
| Weihai Guangtai Airport Equipment Co Ltd |
| Kalmar Motor AB |
| ADELTE Group S.L. |
| Tronair Inc. |
| ITW Inc |
| Cavotec SA |
| Others |
Value Chain & Pricing Dynamics
Multi-year equipment-hour contracts lock in supply access for ground handling service providers while compressing price visibility for buyers facing lithium battery cost volatility. This contract-structure pattern concentrates procurement leverage with operators at Singapore Changi and Incheon International who can commit fleet-scale volumes.
Pricing Analysis
Certification level (JIS/GB/ISO tier) creates the primary spread between premium telematics-integrated systems and commodity electric hardware. Project-based procurement dominates tier-one airport modernization, with price differentiation driven by electromagnetic compliance grade and after-sales service bundling. Cost compression in lead-acid ground power units is intensifying because Chinese manufacturing capacity expansion outpaces Indian budget-operator demand. Budget carriers at secondary Indian airports exhibit highest price sensitivity; full-service carriers at Sydney Airport and Singapore Changi show lowest.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and motor controllers prevails among Japanese and Australian ground handling operators facing JIS certification backlog risks. Manufacturing concentrates in China's Shandong and Jiangsu industrial clusters for electric tugs, with South Korean and Japanese suppliers anchoring automated guided vehicle production. Cathode materials and battery management systems draw from Chinese industrial bases. Single-source vulnerability in lithium-iron-phosphate cell supply exposes procurement to export licensing friction. Distribution runs through regional assembly hubs in Thailand serving Vietnamese and Indonesian airport developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification regimes and unbundling of full-ramp service contracts create specialist niches for equipment suppliers with single-category depth. Airlines disaggregating de-icing, cargo loading, and pushback into discrete awards multiply entry points beyond legacy integrated handlers.
For Market Incumbents: Secure parallel JIS-GB certification tracks to defend multi-country maintenance network eligibility against emerging Chinese electric equipment fabricators. Invest in captive lithium battery supply arrangements to offset cathode cost volatility eroding margin structures in ground power unit segments. For New Entrants and Emerging Players: Anchor in Vietnamese greenfield airport developments at Long Thanh International Airport and Van Don International Airport where first-mover electric ground power unit presence establishes local service relationships. Target fleet telematics integration as the go-to-market angle, leveraging predictive maintenance software gaps at Indonesian and Philippine aviation hubs. For Investors and Strategic Acquirers: The market sits at a certification-divergence phase that favors specialists with dual JIS-GB compliance capabilities over diversified industrial conglomerates. Long-term viability over the next decade hinges on software-integrated platform providers capturing real-time turnaround analytics demand. Watch for automated guided vehicle commissioning timeline compression at established hubs as inflection signal for retrofit service market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Certification Track Establishment | JIS-GB dual compliance unlocks multi-country maintenance contracts across Japanese and Chinese airport perimeters. |
| Regional Assembly Localization | Thai Board of Investment tax privileges reduce landed cost for belt loader automation serving Southeast Asian hubs. |
| Fleet Telematics Platform Integration | IoT sensor convergence commands premium pricing from full-service carriers at Singapore Changi and Sydney Airport. |
| Captive Lithium Battery Supply | Upstream control over cathode sourcing insulates electric tug margins from Chinese industrial cluster export licensing friction. |
| High-Altitude Operational Validation | Specialized de-icing platform certification limits supplier eligibility for Himalayan airport contracts. |
Study Parameters
The analysis maps ramp services, cargo handling, passenger services, and aircraft maintenance segments, each validated through primary interviews with ground handling operations directors, airport procurement managers, airline fleet planners, and maintenance technicians. Secondary sources include MIIT GB certification filings, METI JIS standard documentation, Australian Civil Aviation Safety Authority protocols, PLI scheme disbursement records, and customs trade data for electric ground support equipment. Bottom-up equipment procurement tallies triangulate against top-down airport modernization budget allocations.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, technology category, end-user archetype, and solution application. CAGRs derive from equipment replacement cycle analysis and electrification mandate compliance timelines. Forecast inputs incorporate lithium battery cost trajectory assumptions and certification reciprocity gap resolution probabilities.
Material uncertainties — regulatory timeline shifts, battery supply chain disruptions, certification reciprocity negotiations — sit outside the modeled envelope. Forecasts reflect documented assumptions about PLI scheme continuation and MIIT electrification enforcement intensity. Revision becomes warranted when JIS-GB mutual recognition agreement progress crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Smart Airport Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market