
 Airport Interactive Kiosk Market | 2026-2036
Airport Interactive Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Interactive Kiosk Market Analysis
Asian contract manufacturers is restructuring capacity toward ruggedized touchscreen assemblies for aviation-grade environments. SITA leverages its installed base across IATA-member carriers to sustain long-term service contracts. Fujitsu Limited anchors Japanese airport digitization programs with biometric-enabled kiosk platforms. Diebold Nixdorf competes through financial self-service expertise adapted for travel retail applications.
Airport interactive kiosks are freestanding computerized terminals engineered with IP54-rated enclosures, projected capacitive touch layers, and Intel Core or ARM-based processing modules operating between minus 20 and plus 50 degrees Celsius; they automate passenger-facing transactions including check-in, baggage tagging, wayfinding, and retail purchases in high-throughput aviation facilities. Check-in kiosks dominate installed volume as legacy counter staffing models recede, while facial recognition technology captures the fastest upgrade cycle amid biometric boarding corridor expansions. Wayfinding kiosks occupy narrower margin pools given simpler hardware requirements and shorter replacement intervals.
FAA NextGen terminal modernization directives and TSA checkpoint screening standards shape kiosk placement and interface requirements across United States airports. EASA cybersecurity guidelines for connected aviation infrastructure and GDPR biometric data processing constraints in Europe impose design compliance burdens on hardware OEMs. Stakeholders must monitor evolving biometric consent frameworks and interoperability certifications before committing to multi-terminal procurement programs.
Market Dynamics
Biometric boarding mandates from the FAA and EASA are forcing hardware replacement cycles across major aviation hubs, compressing procurement timelines while elevating facial recognition integration from optional upgrade to baseline requirement.
Growth Catalysts
- FAA NextGen Terminal Modernization:Federal directives mandate self-service infrastructure upgrades at Category X airports, accelerating kiosk deployment timelines.
- Baggage Tagging Automation:Airlines at Atlanta and Dallas-Fort Worth hubs report 40% faster passenger throughput after retrofitting legacy check-in zones with integrated bag-drop modules.
- Facial Recognition Integration:TSA checkpoint screening standards now require biometric-capable terminals at all federalized security lanes, creating hardware pull-through.
Market Restraints
- Projected Capacitive Touchscreen Supply Concentration:Aviation-grade touch layer production concentrates among Taiwanese and South Korean component suppliers, exposing OEMs to single-source risk.
- GDPR Biometric Data Processing Constraints:European data protection frameworks impose consent-management complexity that extends deployment timelines at EU hub airports.
- Legacy Counter Staffing Models:Union contracts at legacy US carriers create organizational friction against full self-service migration.
Strategic Opportunities
- Indian Airport Privatization Wave:Adani Group's consolidation of Mumbai, Ahmedabad and Lucknow terminals creates demand for unified kiosk fleets across greenfield expansions.
- Retail Self-Service Convergence:Duty-free operators at Dubai and Singapore Changi are piloting unified passenger-retail transaction terminals that merge boarding pass verification with payment processing.
- EASA Cybersecurity Certification Pathways:New connected aviation infrastructure guidelines create first-mover advantage for OEMs achieving pre-certified hardware platforms.
Industry Challenges
- Aviation-Grade Firmware Talent Scarcity:Embedded systems engineers with IP54 enclosure and thermal management expertise command premium compensation, constraining OEM scaling.
- Interoperability Certification Delays:IATA Common Use standards and airline-specific API integrations extend deployment testing phases by 6-12 months.
- Legacy Peripheral Integration:Kiosk platforms must maintain backward compatibility with decade-old boarding pass printers and mag-stripe readers during phased terminal renovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Interactive Kiosk Market |
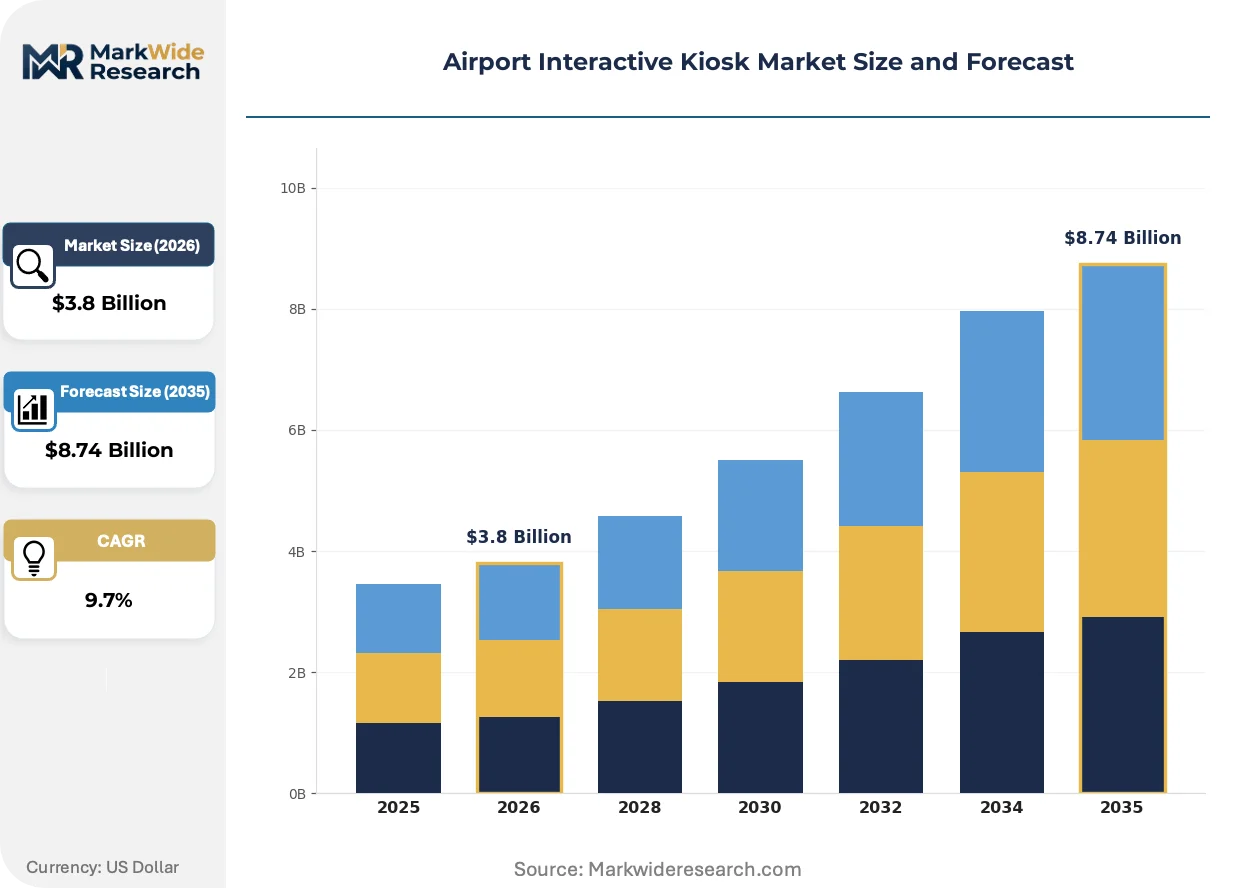
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Check-In Kiosks, Wayfinding Kiosks, Information Kiosks, Ticketing Kiosks End User: Airlines, Airport Authorities, Retailers, Service Providers Technology: Touchscreen, Facial Recognition, QR Code Scanners, NFC Installation: Indoor, Outdoor, Self-Service, Managed |
| Companies Covered | SITA, Fujitsu Limited, KIOSK Information Systems, Embross Group, Toshiba Global Commerce Solutions, Diebold Nixdorf, Zebra Technologies, Olea Kiosks, NCR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Interactive Kiosk Market Emerging Trajectories
Edge computing architectures and multimodal biometric sensors are compressing hardware form factors while expanding transaction autonomy, enabling kiosk networks to operate with reduced cloud dependency during peak congestion events.
Projected capacitive touch technology with anti-reflective optical bonding is consolidating as the dominant interface standard for high-ambient-light aviation environments. Major hub operators in the United States and United Arab Emirates now specify bonded glass assemblies as mandatory in terminal modernization tenders. This specification shift is consolidating procurement around qualified Asian contract manufacturers with aviation certification track records.
EASA cybersecurity guidelines for connected aviation infrastructure impose mandatory encryption standards and penetration-testing protocols on kiosk OEMs serving European airports. Hardware vendors must now maintain certified secure-boot firmware chains and documented vulnerability response procedures. German and French hub operators have accelerated procurement cycles to meet 2025 compliance deadlines, favoring suppliers with pre-certified platforms.
Airline procurement departments are unbundling hardware purchase from long-term service agreements, shifting toward separate vendor selection for terminal deployment versus multi-year maintenance contracts. This bifurcation allows low-cost carriers to optimize capital expenditure through shorter replacement intervals while legacy network carriers prioritize total-cost-of-ownership metrics. The practice is most visible among US and Middle Eastern flag carriers with large hub-and-spoke operations.
Airport Interactive Kiosk Market Segmentation
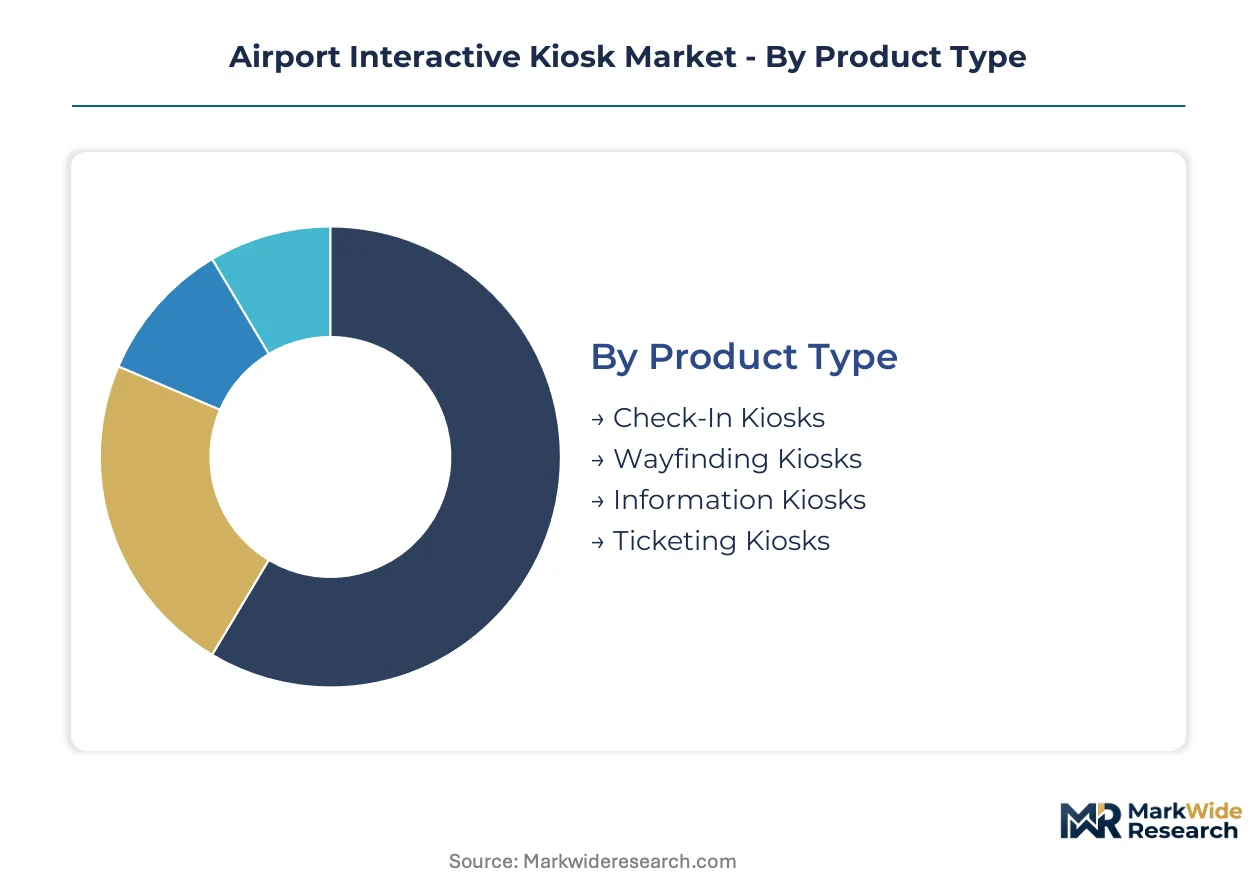
Airport kiosk procurement patterns diverge sharply by deployment context. Hardware specifications, integration complexity, and regulatory compliance burdens vary across passenger-facing versus operational applications.
Product Type:
Touchscreen durability ratings and biometric module integration distinguish hardware tiers across aviation terminal zones.
- Check-In Kiosks:These units integrate IP54-rated enclosures with projected capacitive touch layers and thermal management systems operating between minus 20 and plus 50 degrees Celsius. Demand concentrates at United States Category X airports where FAA NextGen terminal modernization directives mandate self-service infrastructure upgrades. Airlines at Atlanta and Dallas-Fort Worth hubs report 40% faster passenger throughput after retrofitting legacy check-in zones with integrated bag-drop modules.
- Wayfinding Kiosks:Simpler hardware requirements and shorter replacement intervals define this segment, with anti-reflective optical bonding now mandatory in high-ambient-light aviation environments. Major hub operators in the United Arab Emirates specify bonded glass assemblies in terminal modernization tenders, consolidating procurement around qualified Asian contract manufacturers with aviation certification track records. These units occupy narrower margin pools given reduced peripheral integration demands.
- Information Kiosks:General passenger inquiry terminals with basic touchscreen interfaces and minimal peripheral connectivity serve pre-security concourse zones.
- Ticketing Kiosks:Retail-focused units merge boarding pass verification with payment processing at duty-free operators piloting unified passenger-retail transaction terminals.
Mature deployment sits with Check-In Kiosks. Newer deployment is concentrated in Wayfinding Kiosks.
End User:
Procurement authority fragmentation shapes vendor relationship strategies across aviation stakeholders.
- Airlines:Low-cost carriers optimize capital expenditure through shorter replacement intervals while legacy network carriers prioritize total-cost-of-ownership metrics. United States and Middle Eastern flag carriers with large hub-and-spoke operations unbundle hardware purchase from long-term service agreements, shifting toward separate vendor selection for terminal deployment versus multi-year maintenance contracts.
- Airport Authorities:German and French hub operators have accelerated procurement cycles to meet EASA cybersecurity compliance deadlines, favoring suppliers with pre-certified platforms.
- Retailers:Duty-free operators at Dubai and Singapore Changi drive convergence between passenger service and retail transaction automation.
- Service Providers:Third-party facility managers maintain legacy peripheral compatibility during phased terminal renovations.
Airlines dominate installed base economics. Airport Authorities are gaining procurement influence fastest.
Technology:
Biometric integration mandates are compressing hardware replacement cycles and elevating component specifications.
- Touchscreen:Projected capacitive touch technology with anti-reflective optical bonding consolidates as the dominant interface standard. Aviation-grade touch layer production concentrates among Taiwanese and South Korean component suppliers, exposing OEMs to single-source risk.
- Facial Recognition:TSA checkpoint screening standards now require biometric-capable terminals at all federalized security lanes. GDPR biometric data processing constraints in Europe impose consent-management complexity that extends deployment timelines at EU hub airports.
- QR Code Scanners:Legacy mobile boarding pass compatibility modules maintain backward integration with decade-old infrastructure.
- NFC:Contactless payment and credential verification capabilities support retail self-service convergence pilots.
Touchscreen penetration is deepest across installed base. Facial Recognition is climbing the fastest.
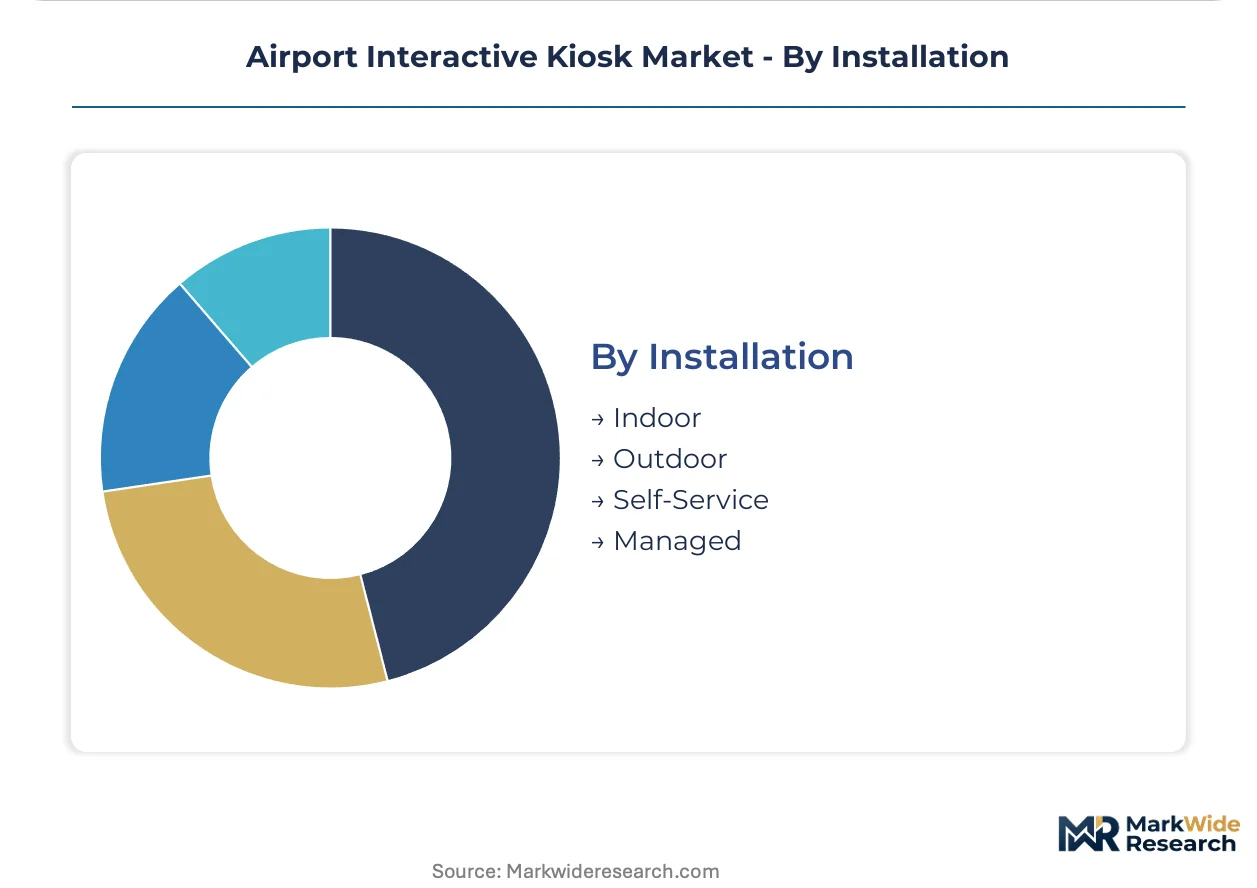
Installation:
Environmental exposure and operational control models determine enclosure specifications and service contract structures.
- Indoor:Climate-controlled terminal deployments dominate volume, with Intel Core or ARM-based processing modules standard.
- Outdoor:Curbside and tarmac-adjacent installations demand extended thermal ranges and enhanced ingress protection.
- Self-Service:Passenger-operated terminals require intuitive interface design and reduced cloud dependency during peak congestion events through edge computing architectures.
- Managed:Vendor-operated kiosk networks with embedded systems engineers commanding premium compensation for aviation-grade firmware expertise.
Indoor deployment holds majority share. Self-Service is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation-grade touchscreen assemblies concentrate manufacturing capacity among Taiwanese and South Korean component suppliers. These specialized production clusters supply IP54-rated enclosures and projected capacitive touch layers to terminal modernization programs worldwide.
United States
FAA NextGen terminal modernization directives mandate self-service infrastructure upgrades at Category X airports. TSA checkpoint screening standards now require biometric-capable terminals at all federalized security lanes. Atlanta and Dallas-Fort Worth hubs report accelerated passenger throughput after retrofitting legacy check-in zones with integrated bag-drop modules.
Germany
EASA cybersecurity guidelines for connected aviation infrastructure impose mandatory encryption standards on kiosk OEMs serving European airports. German hub operators have accelerated procurement cycles to meet 2025 compliance deadlines. Frankfurt and Munich terminals favor suppliers with pre-certified secure-boot firmware platforms.
United Arab Emirates
Duty-free operators at Dubai International pilot unified passenger-retail transaction terminals merging boarding pass verification with payment processing. Anti-reflective optical bonding specifications now dominate high-ambient-light aviation environment tenders. Dubai and Abu Dhabi hub operators consolidate procurement around qualified Asian contract manufacturers with aviation certification track records.
India
Airport privatization waves under Adani Group consolidation of Mumbai, Ahmedabad and Lucknow terminals create demand for unified kiosk fleets across greenfield expansions. BIS certification requirements shape hardware import and assembly protocols. Mumbai and Delhi terminals drive specification standardization for biometric-enabled kiosk platforms.
Airport Interactive Kiosk Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent retail self-service convergence opportunities. The vendor base spans aviation-specialized systems integrators, financial self-service technology adapters, and Asian contract manufacturers with aviation-grade touchscreen assembly expertise. Three strategic archetypes dominate: biometric platform specialists, ruggedized hardware fabricators, and service-contract sustainers. Competitive moves concentrate on EASA pre-certification achievements and unbundled procurement models separating hardware purchase from long-term maintenance agreements.
Within the aviation-specialized systems integrator tier, SITA leverages its installed base across IATA-member carriers while Fujitsu Limited anchors Japanese airport digitization programs. Diebold Nixdorf occupies a position adapting financial self-service expertise for travel retail applications. These three entities exemplify distinct competitive positioning vectors spanning carrier relationship depth, national program anchoring, and cross-sector technology transfer.
| Leading Market Players |
|---|
| SITA |
| Fujitsu Limited |
| KIOSK Information Systems |
| Embross Group |
| Toshiba Global Commerce Solutions |
| Diebold Nixdorf |
| Zebra Technologies |
| Olea Kiosks |
| NCR Corporation |
| Others |
Supply Flow & Price Mechanics
Aviation-grade projected capacitive touch layers from Taiwanese and South Korean suppliers flow through three distinct pricing tiers downstream, with OEMs bundling multi-year service contracts commanding premium positioning against unbundled hardware-only vendors serving cost-optimized carrier procurement desks.
Pricing Analysis
Warranty and service-bundling unbundling now defines competitive positioning, with legacy network carriers favoring total-cost-of-ownership contracts spanning firmware maintenance and peripheral refresh cycles while low-cost airlines drive hardware-only transactions at compressed capital expenditure points. Pricing stratifies across biometric-integrated premium platforms, standard check-in terminals, and economy wayfinding units with minimal peripheral connectivity. Cost compression in the standard tier intensifies as Asian contract manufacturers expand aviation-certified touchscreen capacity. Airport authorities with EASA cybersecurity mandates exhibit lowest price sensitivity given compliance deadline pressures, whereas regional hub operators in emerging markets prioritize acquisition cost minimization.
Supply Chain Analysis
Aviation-grade IP54 enclosure qualification and EASA pre-certification gates concentrate viable supplier pools among Taiwanese touchscreen assemblers, South Korean display component specialists, and Japanese thermal management subsystem providers. Kiosk OEMs draw from specialized inputs including bonded glass assemblies, Intel Core and ARM-based processing modules, and biometric sensor modules. Single-source vulnerability in projected capacitive touch layer production exposes procurement timelines to geographic concentration risk. Distribution runs through direct terminal deployment contracts with hub airport authorities and airline procurement departments, supplemented by systems integrator channel partnerships for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EASA cybersecurity certification deadlines eliminate uncertified competitors, forcing acquisition-driven exits among regional kiosk assemblers lacking secure-boot firmware capabilities.
For Market Incumbents: Acquire aviation-grade firmware engineering teams to address talent scarcity constraining OEM scaling, while securing captive supply agreements with Taiwanese touchscreen manufacturers to mitigate single-source exposure against emerging entrants from adjacent retail self-service sectors. For New Entrants and Emerging Players: The mid-tier pricing gap between premium biometric-integrated platforms and basic wayfinding terminals offers white-space entry through modular kiosk architectures serving Indian airport privatization programs and Middle Eastern retail convergence pilots, leveraging contract manufacturing partnerships to bypass certification timeline disadvantages. For Investors and Strategic Acquirers: EASA pre-certification achievement announcements are the leading indicator that hardware OEMs have crossed the compliance threshold for European hub procurement cycles, signaling acquisition target maturity within a five-to-ten year infrastructure replacement horizon; prioritize platforms with installed base across IATA-member carriers for service contract annuity value.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Pre-Certification | EASA secure-boot compliance unlocks German and French hub procurement cycles ahead of regulatory deadlines. |
| Service Contract Unbundling | Separate hardware and maintenance vendor selection optimizes capital expenditure for low-cost carrier procurement desks. |
| Touchscreen Supply Captivation | Direct agreements with Taiwanese and South Korean component suppliers mitigate single-source concentration risk. |
| Retail Convergence Partnership | Unified passenger-retail transaction terminals capture duty-free operator pilots at Dubai and Singapore Changi. |
| Indian Greenfield Fleet Deployment | Unified kiosk specifications across Adani Group terminals establish reference architecture for privatization wave. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning airport procurement directors, airline IT infrastructure leads, kiosk OEM product managers, and aviation systems integrators, validated against IATA Common Use standards documentation, FAA NextGen directive texts, and EASA cybersecurity guideline releases through bottom-up installation tracking and top-down market sizing reconciliation.
Data-stream reconciliation across hardware shipment volumes, terminal modernization tender awards, and service contract disclosures informed the analytical framework over the projection horizon, modeling segmentation dimensions including product type, end-user procurement authority, technology integration level, and installation environment, with CAGRs derived from trend extrapolation of biometric mandate adoption curves and replacement cycle compression patterns.
Inputs from EASA certification databases and airport authority procurement portals were available through the study window; gaps in real-time airline fleet deployment schedules introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and carrier self-service migration rates. A model refresh is warranted upon material change in biometric boarding mandate enforcement schedules or touch layer supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
North America Smart Airport Market