
 Global Airport Baggage Handling System Market | 2026-2036
Global Airport Baggage Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airport Baggage Handling System Market Foresight
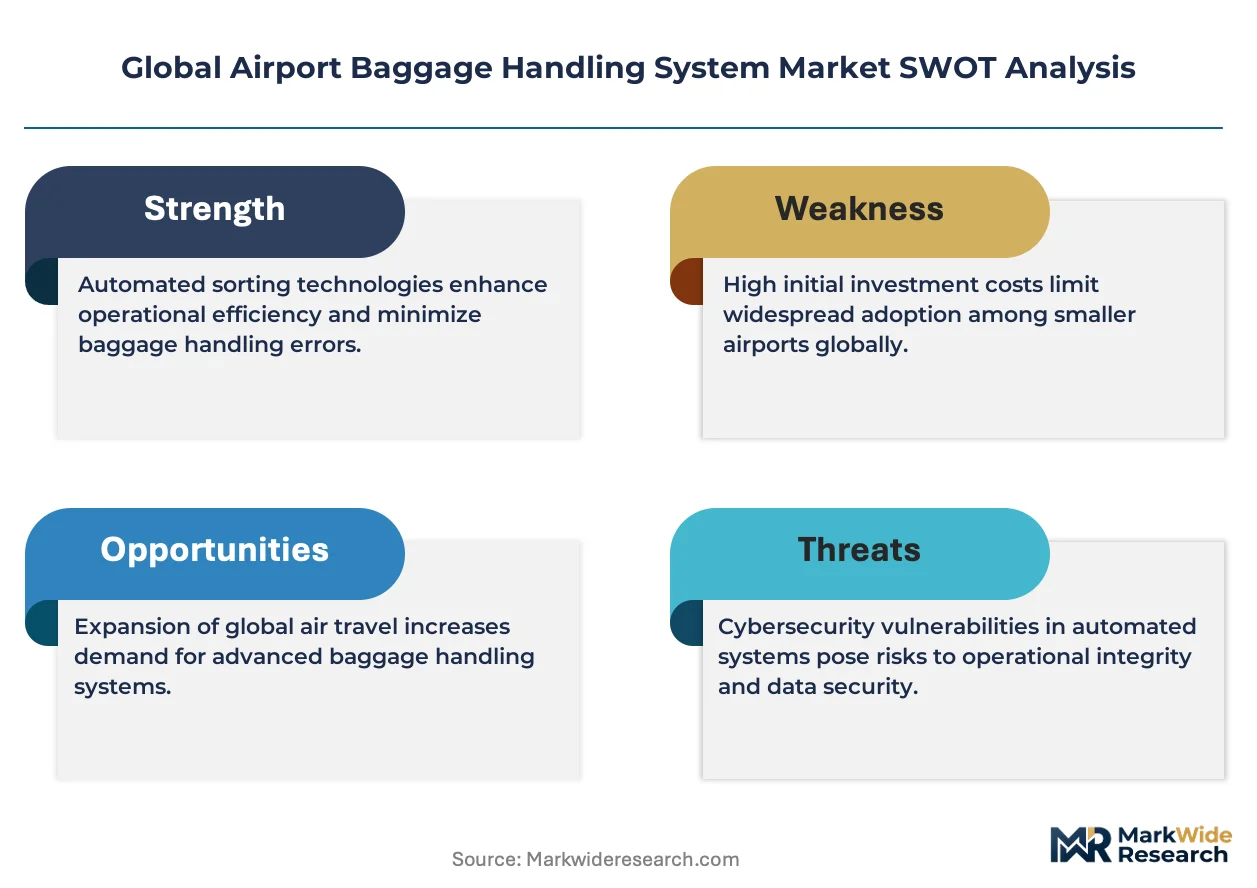
Passenger baggage screening is decoupling from legacy manual processes as airport operators prioritize throughput and traceability. Vanderlande Industries leverages its installed base across European hubs to sustain service revenue streams. Daifuku Co., Ltd. anchors Asian expansion through manufacturing scale in automated sortation. Siemens AG differentiates by integrating optical character recognition with centralized control software.
An airport baggage handling system comprises conveyor networks, sorting mechanisms, barcode and RFID identification equipment, and transport vehicles engineered to process items from check-in through aircraft loading at speeds exceeding standard manual throughput. These systems employ belt drives, tilt-tray sorters, and destination-coded vehicles to achieve routing accuracy and minimize mishandled baggage rates in high-volume terminal environments. Sorting systems capture the dominant share of capital expenditure as airports replace legacy tilt-tray installations with cross-belt technology. RFID scanners represent the fastest-expanding identification segment, displacing barcode readers where real-time location tracking justifies hardware premiums. Conveyor systems remain the volume backbone, though margin pools increasingly concentrate in software layers that optimize flow control.
The Federal Aviation Administration mandates baggage screening compliance through certified explosive detection integration, while the EU Green Deal drives electrification standards for ground support equipment including transport vehicles. REACH and RoHS frameworks restrict hazardous substances in conveyor electronics and motor housings, shaping supplier qualification requirements. Stakeholders must monitor how the EU AI Act classifies automated decision systems in baggage routing, as this will determine liability frameworks and insurance structures for unmanned sortation operations.
Market Dynamics
Cross-belt sortation technology is electrifying conveyor architectures across major hub expansions, compressing capital deployment timelines while forcing incumbent tilt-tray suppliers to requalify for electrified tender specifications.
Growth Catalysts
- EU Green Deal electrification mandates:The EU F-Gas Regulation and parallel electrification standards for ground support equipment are accelerating replacement cycles for diesel-powered transport vehicles and belt drives across European hub airports.
- RFID real-time location tracking:Baggage mishandling liability costs are pushing operators toward RFID scanner deployments that displace legacy barcode infrastructure where traceability justifies hardware premiums.
- China's greenfield airport construction:Massive terminal expansions in Beijing, Chengdu, and Shenzhen are absorbing automated sortation capacity as state-owned operators modernize legacy manual handling infrastructure.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electrified conveyor motors and transport vehicle drivetrains face input cost pressure from concentrated upstream mining operations in Chile and the Democratic Republic of Congo.
- German engineering supplier concentration:Precision gearbox and drive component manufacturing clusters heavily around Baden-Württemberg and Bavaria, creating single-source vulnerability for system integrators.
- Legacy tilt-tray asset stranding:Existing installations in US hub airports carry substantial undepreciated book value, delaying replacement decisions despite superior cross-belt performance metrics.
Strategic Opportunities
- India's underpenetrated secondary airports:The country's PLI scheme for manufacturing and DGFT import substitution policies are opening tender opportunities for domestic assembly of modular conveyor systems.
- Predictive maintenance software convergence:Integration of machine learning with optical character recognition is enabling new recurring revenue streams from performance-based service contracts.
- EU AI Act liability frameworks:Early compliance with automated decision system classifications for unmanned sortation operations will secure preferred supplier status as liability insurance structures formalize.
Industry Challenges
- Mechatronics technician scarcity:Electrified cross-belt sorters and destination-coded vehicles require specialized maintenance skills that outpace vocational training output in Germany, the United States, and Japan.
- Explosive detection certification timelines:FAA and EASA recertification requirements for integrated screening modules extend project delivery schedules, compressing installation windows during live terminal operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airport Baggage Handling System Market |
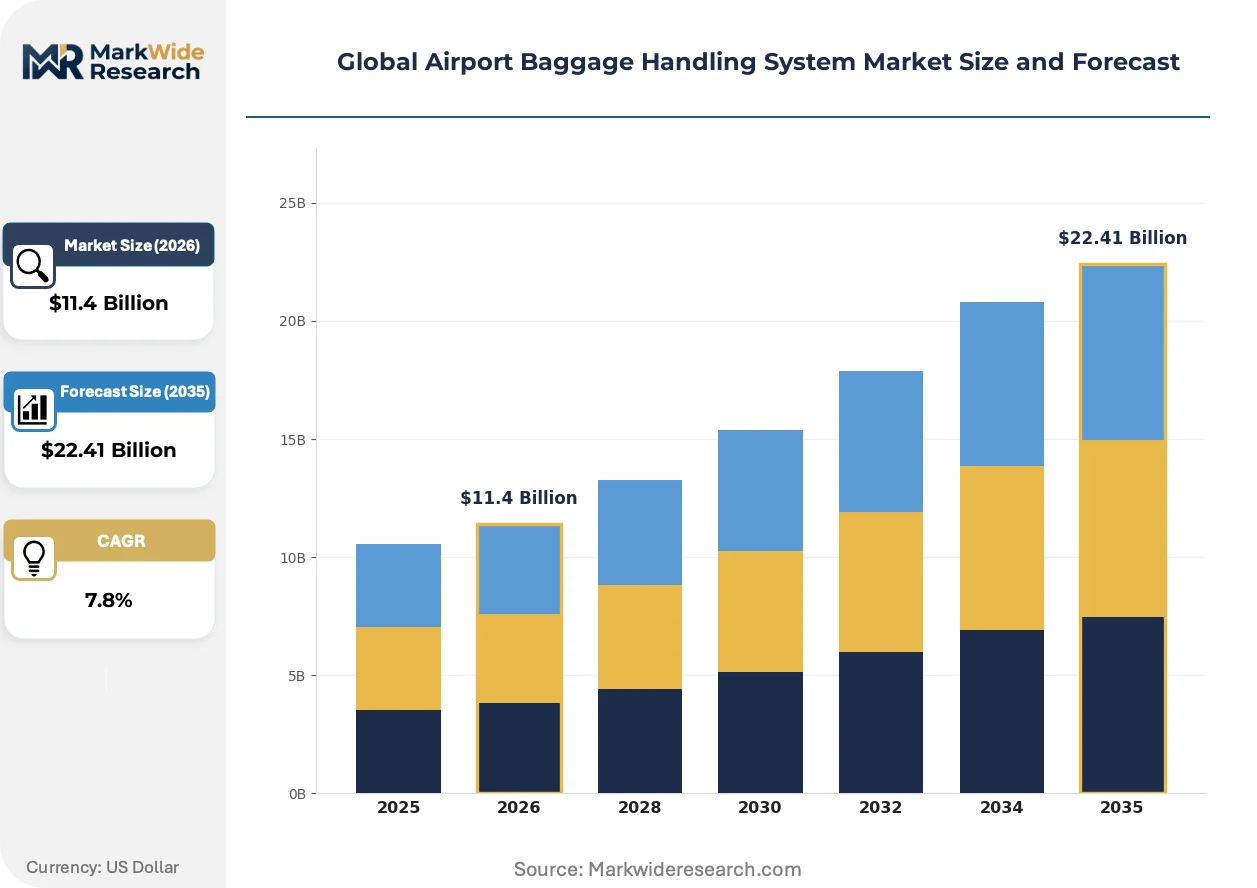
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorting Systems, Conveyor Systems, Barcode Readers, RFID Scanners, Transport Vehicles Technology: Automated Sortation, Manual Handling, Optical Character Recognition, Radio Frequency Identification, Voice Recognition Application: Passenger Baggage Screening, Cargo Handling, Security Inspection, Transfer Baggage Management, Lost Baggage Tracking End User: Airport Operators, Airlines, Ground Handling Services, Customs Agencies, Security Providers |
| Companies Covered | Vanderlande Industries, Daifuku Co., Ltd., Beumer Group, Siemens AG, Alstef Group, Pteris Global Limited, Fives Group, G&S Airport Conveyor, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airport Baggage Handling System Market Shifts & Advancements
Software-defined flow control is compressing hardware differentiation cycles, forcing suppliers to defend margin pools through predictive analytics and remote diagnostics rather than mechanical engineering alone.
Permanent magnet synchronous motors are electrifying conveyor belt drives and transport vehicle propulsion systems. Airport operators in Germany and the United States are specifying these units for new-build terminals and major retrofits. The technology is electrifying what had been a mature electromechanical supply base, compressing incumbent motor supplier margins while opening qualification pathways for specialized drivetrain vendors.
The EU AI Act's classification of automated decision systems in baggage routing is reshaping liability allocation between system integrators and airport operators. Manufacturers must now document algorithmic transparency and human oversight protocols for unmanned sortation operations. European hub airports and their insurers are demanding contractual indemnification structures that reflect these emerging compliance burdens.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete performance modules. Airport operators in China and the United States are purchasing predictive analytics subscriptions separately from spare parts and field labor. This shift is most visible among large hub operators with in-house engineering capabilities, who prefer software access fees over bundled full-service agreements.
Global Airport Baggage Handling System Market Segmentation
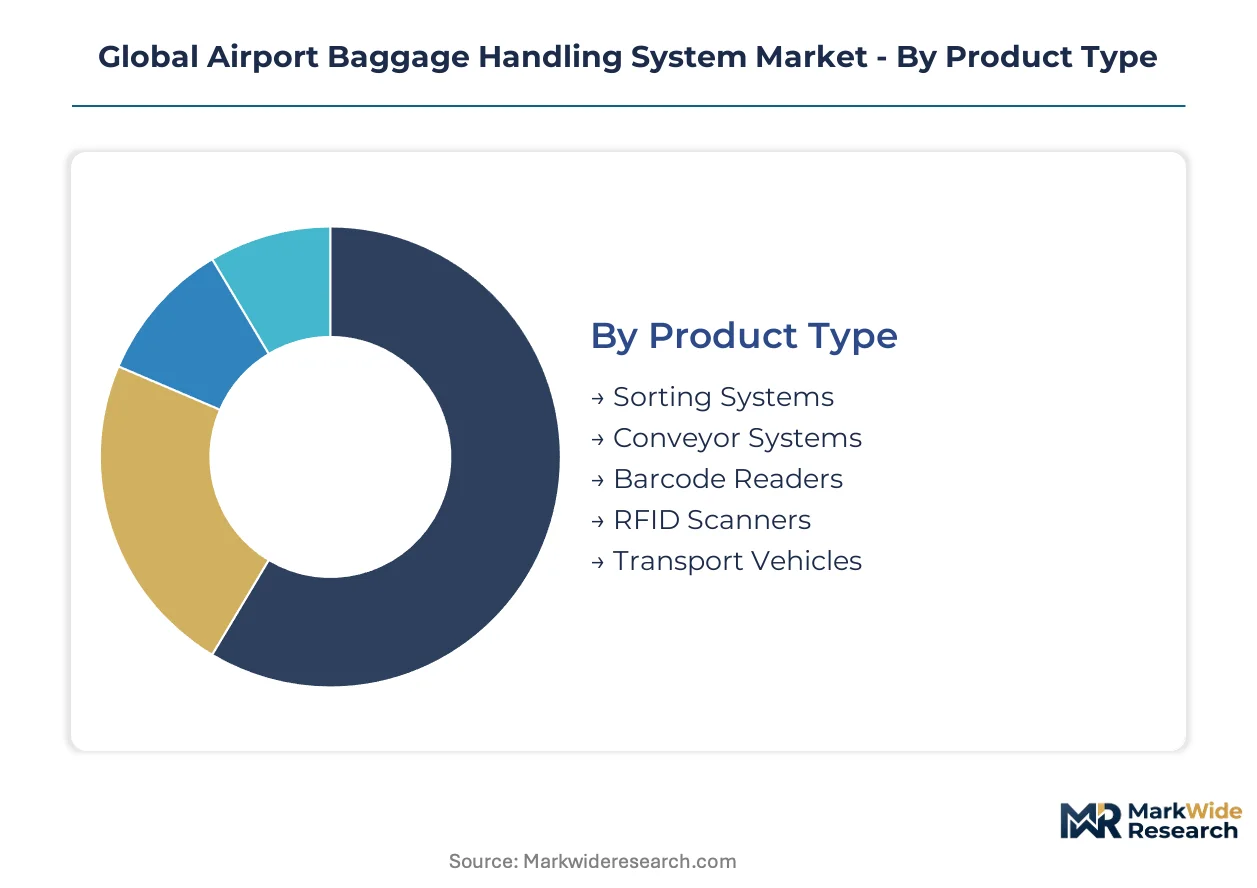
Baggage handling procurement fractures across mechanical hardware, control software, and service layers. Each segment carries distinct margin profiles and vendor qualification barriers that reshape competitive positioning.
Product Type:
Supply concentrates in electromechanical components where German and Japanese drivetrain clusters dominate precision manufacturing.
- Sorting Systems:Cross-belt sorters and tilt-tray mechanisms route baggage through destination-coded logic. Demand concentrates in China and Germany as Beijing Daxing and Munich hub expansions displace legacy manual infrastructure.
- Conveyor Systems:Belt-driven networks form the volume backbone of terminal operations, processing items from check-in through make-up areas. US and European operators prioritize electrified belt drives under FAA and EU Green Deal mandates, compressing diesel-equipment replacement cycles.
- Barcode Readers:Laser-based optical scanners capture baggage tag data at induction points.
- RFID Scanners:Radio-frequency identification equipment enables real-time location tracking across conveyor networks.
- Transport Vehicles:Destination-coded vehicles and electric tugs move baggage between terminal zones and aircraft stands.
Today's leader: Conveyor Systems. Tomorrow's challenger: RFID Scanners.
Technology:
Cost tiers separate legacy electromechanical installations from software-defined control architectures.
- Automated Sortation:Cross-belt and tilt-tray systems execute high-speed routing without manual intervention. China's greenfield airports in Chengdu and Shenzhen absorb capacity as state-owned operators modernize legacy infrastructure.
- Optical Character Recognition:Image-processing software extracts tag data from damaged or poorly printed labels. Siemens AG anchors this segment through integration with centralized control platforms, differentiating against pure hardware competitors.
- Manual Handling:Human-operated baggage transport persists in secondary airports and retrofit-constrained terminals.
- Radio Frequency Identification:UHF and HF RFID protocols enable item-level tracking throughout the baggage journey.
- Voice Recognition:Speech-directed picking and sorting commands supplement handheld terminal operations.
Automated Sortation commands current capital deployment. Optical Character Recognition gains share fastest through software-layer margin capture.
Application:
Volume concentrates in passenger-facing operations where throughput metrics determine terminal capacity planning.
- Passenger Baggage Screening:Checked luggage processing from check-in through explosive detection and aircraft loading. US hub airports drive specification under FAA certification mandates, while EU Green Deal standards accelerate electrification of integrated screening lines.
- Security Inspection:Hold baggage and carry-on screening for threat detection. German and French regulators enforce EASA recertification timelines that extend project delivery schedules.
- Cargo Handling:Freight and mail sortation through dedicated terminal facilities.
- Transfer Baggage Management:Interline luggage routing between connecting flights.
- Lost Baggage Tracking:Tracing and reconciliation systems for mishandled items.
Passenger Baggage Screening anchors infrastructure investment. Security Inspection climbs fastest as liability costs reshape procurement priorities.
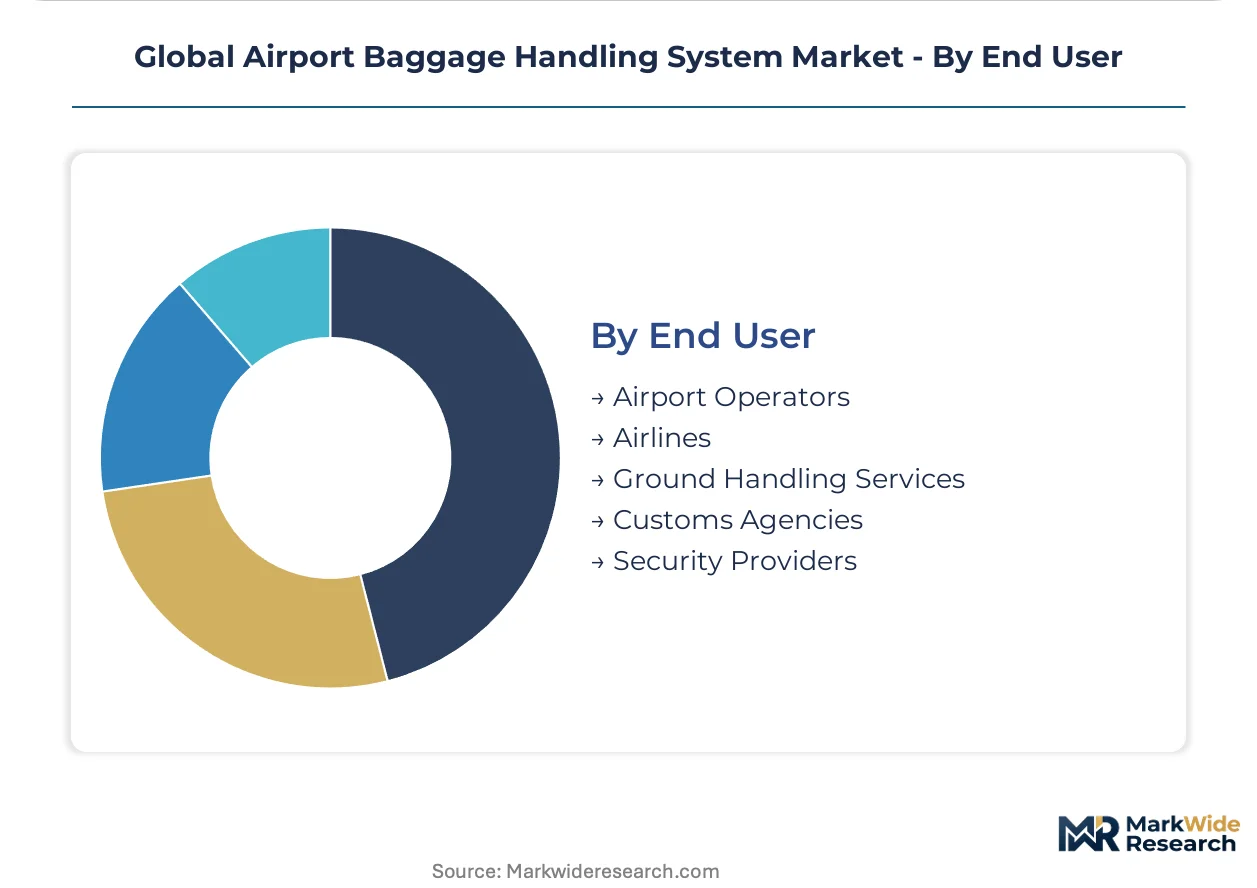
End User:
Customer type determines contract structure, with airport operators consolidating procurement and airlines unbundling service tiers.
- Airport Operators:Terminal owners specifying integrated baggage systems for hub expansions and retrofits. China's state-owned airport groups and Germany's Fraport drive cross-belt adoption through centralized capital planning.
- Ground Handling Services:Third-party ramp and baggage contractors purchasing modular equipment for airline contracts. Swissport and dnata in the UAE specify transport vehicles and make-up equipment separately from fixed infrastructure.
- Airlines:Network carriers investing in proprietary tracking and priority handling capabilities.
- Customs Agencies:Government authorities requiring inspection integration for international baggage flows.
- Security Providers:Private screening contractors operating explosive detection systems under regulatory certification.
Airport Operators control capital allocation today. Ground Handling Services represent the fastest-expanding procurement channel as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision manufacturing cluster anchors European supply chains for electrified conveyor drives and destination-coded vehicles. China's state-owned airport groups absorb the largest share of new cross-belt sortation capacity. The United States retains substantial installed base of legacy tilt-tray systems awaiting replacement decisions.
United States
FAA explosive detection mandates and aging hub infrastructure in Atlanta and Chicago drive replacement demand for integrated screening lines. The FAA recertification timeline extends project delivery schedules for system integrators. Dallas-Fort Worth and Denver concentrate greenfield terminal expansions specifying electrified belt drives under federal sustainability procurement guidelines.
China
Beijing Daxing, Chengdu Tianfu, and Shenzhen Bao'an greenfield terminals absorb automated sortation capacity as state-owned operators modernize legacy manual handling. MIIT dual carbon goals accelerate electrification specifications for transport vehicles and conveyor networks. The Yangtze River Delta manufacturing base supplies precision gearbox components for domestic system integrators.
Germany
Fraport's hub expansions at Frankfurt and Munich displace legacy tilt-tray installations with cross-belt technology under EU Green Deal electrification mandates. The EU F-Gas Regulation and REACH frameworks restrict hazardous substances in motor housings and conveyor electronics. Bavaria and Baden-Württemberg engineering clusters face mechatronics technician scarcity despite sustained order backlogs.
India
PLI scheme incentives and DGFT import substitution policies open tender opportunities for domestic assembly of modular conveyor systems at secondary airports. The CEA electrification standards shape ground support equipment procurement specifications. Maharashtra and Karnataka host emerging manufacturing partnerships between global integrators and local fabricators.
United Arab Emirates
Dubai International and Abu Dhabi Zayed expansions specify destination-coded vehicles and automated sortation for transfer baggage management. MOHAP security integration requirements align with EASA-equivalent certification timelines. The Jebel Ali industrial zone concentrates regional distribution and service capabilities for Middle East hub operators.
Global Airport Baggage Handling System Market Competitive Landscape
Strategic partnerships dominate the current landscape as system integrators seek to secure preferred supplier status for electrified tender specifications. The vendor base fragments across three tiers: full-stack integrators owning mechanical and software layers, specialized drivetrain component suppliers concentrated in German and Japanese industrial clusters, and regional fabricators serving secondary airports with modular conveyor assemblies. Two competitive moves define positioning: technology licensing agreements that transfer cross-belt IP to emerging market partners, and geographic expansion through local assembly joint ventures in India and Southeast Asia.
Among full-stack integrators, Vanderlande Industries leverages its installed base across European hubs to sustain service revenue streams, while Daifuku Co., Ltd. anchors Asian expansion through manufacturing scale. Siemens AG occupies a differentiated position integrating optical character recognition with centralized control software. These three exemplify the strategic archetypes now competing for electrified airport infrastructure contracts.
| Leading Market Players |
|---|
| Vanderlande Industries |
| Daifuku Co., Ltd. |
| Beumer Group |
| Siemens AG |
| Alstef Group |
| Pteris Global Limited |
| Fives Group |
| G&S Airport Conveyor |
| Leonardo S.p.A. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FAA-integrated screening systems and standard conveyor modules splits both procurement budgets and supplier qualification pathways. Premium tiers command hardware premiums through explosive detection certification timelines, while commodity belt-drive assemblies face cost compression from electrification mandates issued by the EU Green Deal.
Pricing Analysis
Input-cost pass-through from copper and rare-earth magnet volatility compresses margins on electrified conveyor motors and destination-coded vehicle drivetrains. Three-tier pricing structure across certified screening-integrated, electrified standard, and legacy diesel equipment segments reflects divergent compliance burdens. Pricing pressure stems from Chinese state-owned operators consolidating procurement at greenfield terminals, squeezing European integrators on volume tenders. Ground handling services in the UAE and India exhibit highest price sensitivity, while German hub operators prioritize certification reliability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by Fraport and Beijing Daxing procurement specifications force system integrators to qualify secondary gearbox vendors beyond Baden-Württemberg precision clusters. Manufacturing gravity centers on Germany, Japan, and China's Yangtze River Delta for precision drive components and control electronics. Supply chains draw from Chilean copper and Congolese rare-earth operations for motor windings and permanent magnets. Single-source vulnerability in Bavarian mechatronics technician availability threatens delivery schedules. Distribution runs through regional service hubs at Dubai Jebel Ali and Singapore for Middle East and Southeast Asia hub operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-layer margin capture is accelerating as predictive maintenance subscriptions displace bundled service contracts, expanding recurring revenue pools beyond hardware depreciation cycles.
For Market Incumbents: Anticipate cross-belt technology commoditization by locking in long-term service contracts with European hub operators before electrification tenders saturate. Incumbent tilt-tray suppliers face asset stranding risk at US airports carrying undepreciated legacy installations; defend position through retrofit upgrade pathways that preserve existing mechanical infrastructure. Certification investment in EU AI Act compliance for automated decision systems will secure preferred supplier status as liability frameworks formalize. For New Entrants and Emerging Players: Regional fabricators in India's Maharashtra and Karnataka clusters offer the most penetrable entry channel, leveraging PLI scheme incentives and DGFT import substitution policies for modular conveyor assembly. Secondary airports in India's tier-2 cities present white-space demand with lower qualification barriers than Chinese state-owned tenders. Partner with established German or Japanese drivetrain suppliers for technology licensing agreements that transfer cross-belt IP without captive manufacturing investment. For Investors and Strategic Acquirers: Consolidation pressure builds where predictive maintenance software convergence fragments traditional maintenance contracts into discrete performance modules. Mid-cap specialists owning optical character recognition integration capabilities present viable acquisition targets as full-stack integrators seek software-layer differentiation. Watch for FAA recertification timeline extensions as the inflection signal: compressed installation windows during live terminal operations favor incumbents with established regulatory relationships over capital-backed entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Cross-belt IP transfer to Indian regional fabricators accelerates local assembly qualification under PLI schemes. |
| Predictive Maintenance Platform Launch | Machine learning integration with optical character recognition enables performance-based service contract unbundling. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation secures preferred supplier status for unmanned sortation liability frameworks. |
| Electrified Drive Manufacturing Scale-Up | Permanent magnet synchronous motor production expansion captures EU Green Deal and FAA sustainability procurement mandates. |
| Regional Service Hub Joint Venture | Local assembly partnerships in UAE and India reduce delivery timelines for Middle East and Southeast Asia hub expansions. |
Research Methodology
Multiple input streams — primary interviews with airport engineering directors, system integrator procurement leads, and ground handling operations managers; secondary validation through FAA certification databases, EASA regulatory filings, and EU Green Deal implementation reports; plus customs trade data on conveyor component imports — were reconciled through bottom-up installation tracking and top-down infrastructure investment triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including sortation technology type, identification equipment protocol, integration complexity tier, and regional regulatory cluster. CAGRs were derived from infrastructure investment pipelines and replacement cycle analysis. Forecast inputs incorporated electrification mandate compliance timelines and explosive detection recertification schedule impacts on project delivery.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and rare-earth price volatility, mechatronics technician training pipeline expansion, and EU AI Act liability framework finalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Smart Airport Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Airport Baggage Conveyor System Market