
 Europe 3D Mapping and Modeling Market | 2026-2036
Europe 3D Mapping and Modeling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D Mapping and Modeling Market Intelligence
Project finance for geospatial infrastructure is narrowing the competitive field to firms with balance-sheet capacity for multi-year public contracts. Hexagon AB leverages its sensor-to-software vertical stack to dominate European defense and surveying accounts. Autodesk, Inc. competes through cloud-native platforms that lower entry costs for mid-sized engineering consultancies. Dassault Systemes SE anchors its position in France through deep integration with aerospace and automotive OEM workflows.
Europe 3D Mapping and Modeling encompasses the acquisition, processing, and visualization of spatial data through lidar point clouds, photogrammetric meshes, and satellite-derived digital elevation models, typically achieving centimeter-to-meter accuracy for terrain and infrastructure representation. The technology serves urban planners, environmental regulators, and construction engineers who require georeferenced volumetric analysis for asset design, compliance verification, and operational monitoring. Cloud-based deployment is capturing the fastest expansion as sovereign data requirements ease and latency improves across EU fiber networks. Lidar technology sustains premium pricing in precision applications despite photogrammetry's cost advantages at scale. Environmental monitoring applications are deepening as CSRD disclosure rules force corporates to quantify land-use change and carbon stock.
EMA, ECHA, and the EU Green Deal framework collectively shape market access by mandating environmental impact digitization and chemical site documentation standards that require 3D spatial baselining. REACH compliance and the F-Gas Regulation further direct investment toward non-invasive surveying methods that reduce field personnel exposure and eliminate drone-mounted refrigerant-based sensors. Stakeholders must weigh the pace of EU AI Act implementation against lidar-AI fusion development timelines to preserve competitive positioning.
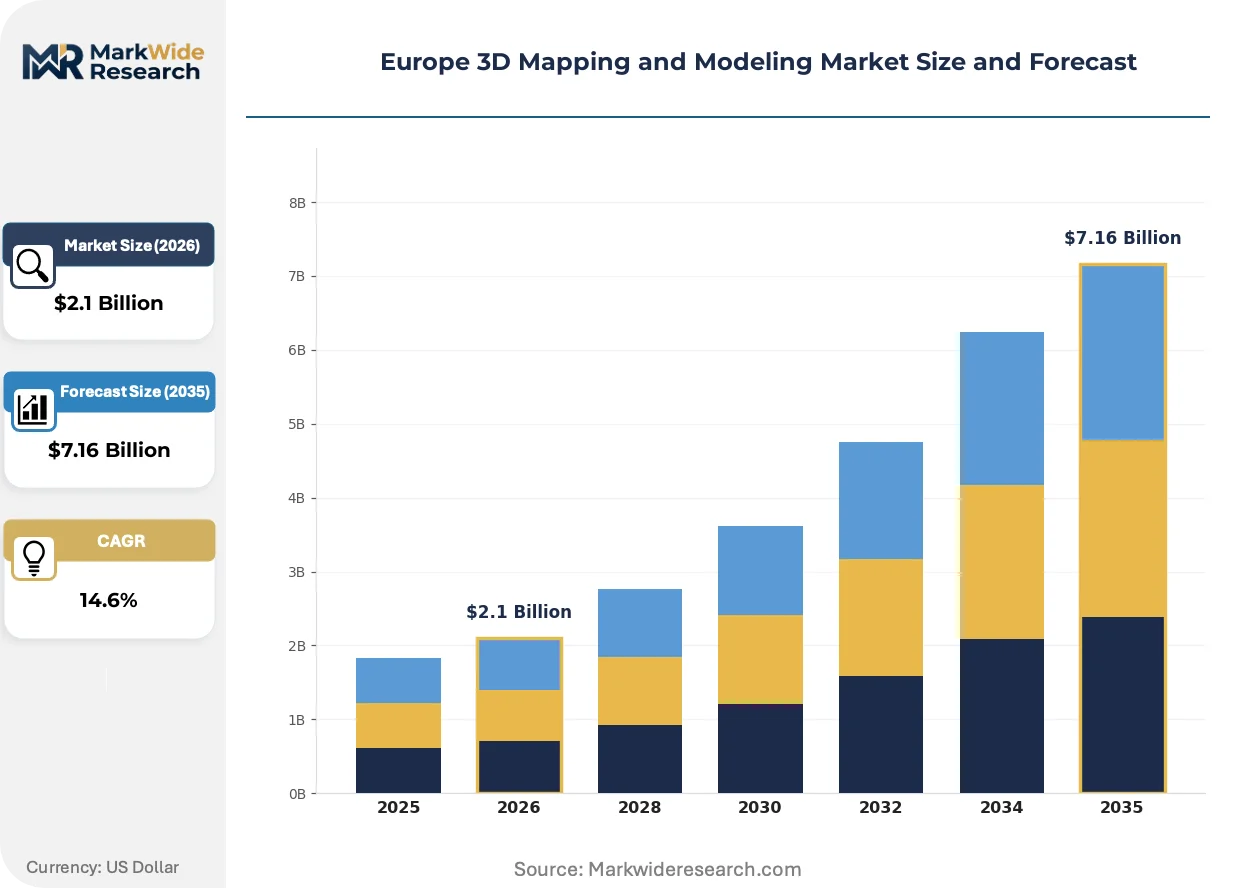
Market Dynamics
The EU Green Deal's digital twin mandates for environmental monitoring are compressing procurement cycles across municipal governments and industrial operators, forcing vendors to reconfigure delivery models around multi-year public infrastructure contracts.
Growth Catalysts
- CSRD disclosure rules:Corporates in France and Germany must quantify land-use change and carbon stock, creating mandatory demand for lidar-derived elevation models and photogrammetric baselining.
- Smart city infrastructure:Municipal governments in Germany's Ruhr region and France's Lyon corridor are bundling 3D spatial data into urban planning tenders for flood modeling and traffic simulation.
- Photogrammetry cost curves:Drone-captured mesh processing now undercuts lidar point clouds at scale, opening mid-budget surveying to mid-sized engineering consultancies previously priced out.
Market Restraints
- Sensor supply concentration:High-precision lidar modules depend on German and Swedish component suppliers, exposing integrators to allocation risk during automotive sector demand surges.
- F-Gas Regulation compliance costs:REACH-aligned restrictions on refrigerant-based cooling systems eliminate certain drone-mounted thermal sensors, forcing hardware refresh cycles.
- Cloud latency in Eastern Europe:Fiber network density gaps in Poland and Romania delay real-time point cloud processing, limiting SaaS platform penetration outside Western EU nodes.
Strategic Opportunities
- EU AI Act alignment:Vendors who pre-certify lidar-AI fusion pipelines for high-risk system classification will capture defense and critical infrastructure accounts before compliance deadlines.
- Environmental monitoring white space:Spain and Italy show underpenetrated demand for satellite-derived digital elevation models in agricultural water management and coastal erosion tracking.
- Edge computing convergence:On-device mesh processing on survey-grade tablets is collapsing field-to-office latency, enabling same-day deliverables for construction site verification.
Industry Challenges
- Geospatial data scientist scarcity:European universities produce insufficient graduates trained in point cloud classification and photogrammetric mesh optimization, inflating specialist compensation.
- Legacy CAD integration friction:Municipal planning departments in older industrial cities maintain decades-old Bentley or AutoCAD installations, complicating cloud-native platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D Mapping and Modeling Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Mobile Technology: Lidar, Photogrammetry, Satellite Imagery, GIS Application: Urban Planning, Environmental Monitoring, Construction, Transportation End User: Government, Construction Companies, Real Estate, Environmental Agencies |
| Companies Covered | Hexagon AB, Dassault Systemes SE, Bentley Systems, Inc., Autodesk, Inc., Airbus SE, Esri, Inc., Trimble Inc., Google LLC, Topcon Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D Mapping and Modeling Market Strategic Shifts & Innovations
Cloud-native deployment architectures are redrawing competitive boundaries between sensor manufacturers and software platforms, while regulatory digitization mandates force technology convergence across previously siloed surveying disciplines.
Neural radiance fields (NeRFs) are collapsing the cost structure for volumetric scene reconstruction from sparse photographic inputs. French aerospace suppliers and German automotive designers are adopting NeRF-derived meshes for rapid prototyping workflows previously reserved for lidar scans. The technology is compressing hardware procurement budgets for mid-accuracy applications while redirecting capital toward compute infrastructure.
The EU AI Act's risk classification framework is reshaping procurement specifications for automated feature extraction from point clouds. Defense ministries and rail operators now require algorithmic audit trails and training data documentation that legacy black-box models cannot satisfy. Vendors are responding by modularizing AI pipelines to isolate high-risk classification steps from standard preprocessing workflows.
Subscription pricing for photogrammetry platforms is displacing perpetual license models among mid-sized civil engineering consultancies. Buyers in the Netherlands and Belgium now prioritize operational expenditure predictability over capital ownership, pressuring incumbents to unbundle sensor sales from software access. This shift is most visible in infrastructure inspection verticals where project-based contracting dominates vendor selection.
Europe 3D Mapping and Modeling Market Segmentation
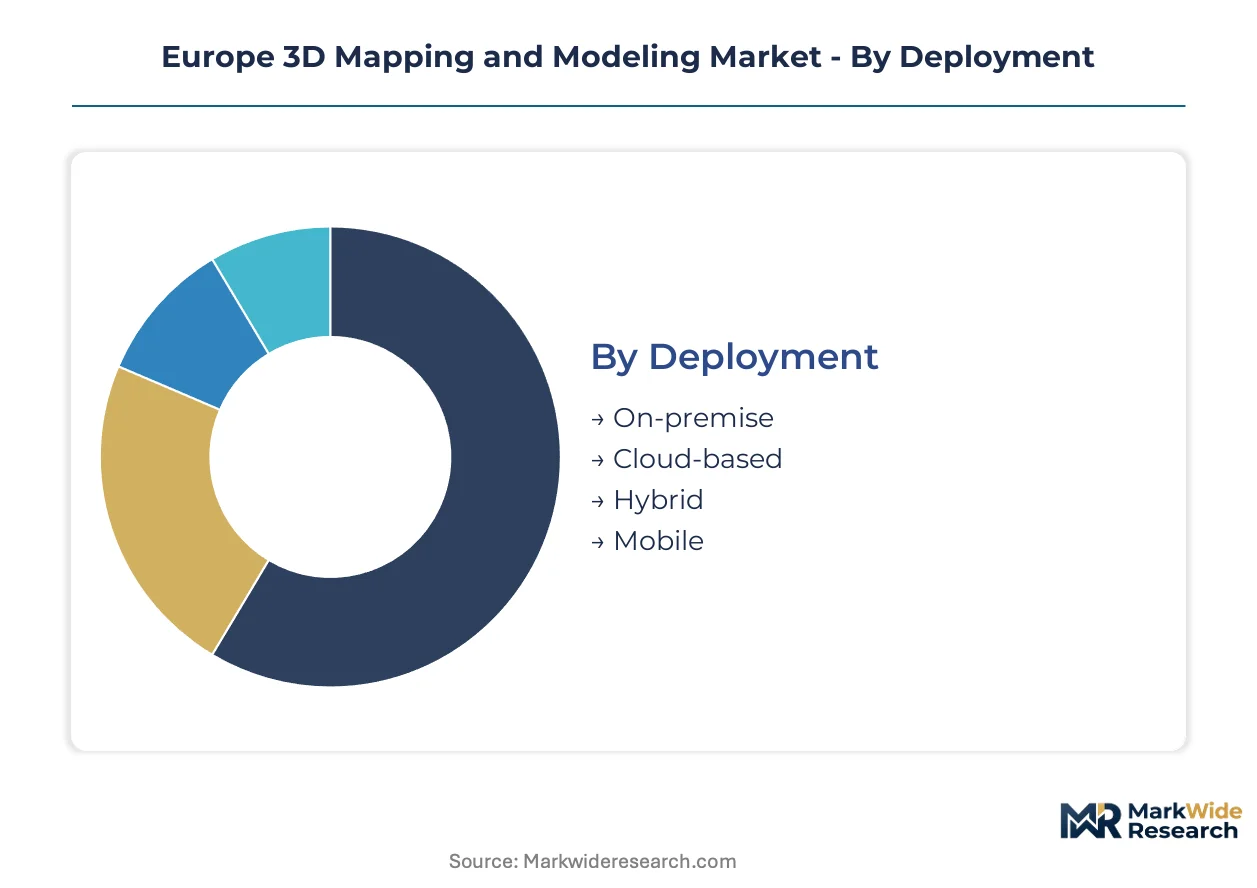
Segmentation in the Europe 3D Mapping and Modeling Market reveals how procurement priorities diverge across infrastructure maturity, regulatory pressure, and data sovereignty requirements. Each dimension exposes distinct vendor positioning strategies and buyer risk tolerances.
Deployment:
Use-case spectrum spans classified defense projects requiring air-gapped processing to agile construction sites demanding real-time collaboration.
- On-premise:Air-gapped installations serve defense ministries and critical infrastructure operators in France and Germany with classified point cloud processing. EMA and national security protocols mandate sovereign data custody, preserving premium pricing despite higher total cost of ownership.
- Cloud-based:SaaS platforms capture municipal governments and mid-sized engineering consultancies in the Netherlands and Belgium prioritizing operational expenditure predictability. CSRD disclosure deadlines compress procurement cycles, favoring rapid deployment without capital commitment.
- Hybrid:Sensitive preprocessing occurs locally while visualization and collaboration layers shift to EU-hosted cloud infrastructure. This architecture satisfies GDPR data residency requirements for cross-border infrastructure projects.
- Mobile:On-device mesh processing on survey-grade tablets collapses field-to-office latency for construction site verification in Germany's automotive manufacturing belt.
The dominant share belongs to On-premise, while Cloud-based is closing the gap fastest.
Technology:
Cost tier differentiation separates precision-critical applications from budget-constrained volume deployments.
- Lidar:Active laser scanning achieves centimeter accuracy for rail alignment, aerospace component inspection, and flood modeling. German and Swedish component suppliers concentrate sensor manufacturing, exposing integrators to allocation risk during automotive sector demand surges.
- Photogrammetry:Drone-captured dense mesh reconstruction now undercuts lidar at scale, opening mid-budget surveying to Spanish agricultural water management and Italian coastal erosion monitoring previously priced out of precision spatial data.
- Satellite Imagery:Stereo pair-derived digital elevation models support continental-scale environmental baselining for EU Green Deal compliance without field deployment.
- GIS:Geospatial information systems integrate multi-source data layers for municipal planning departments maintaining decades-old Bentley or AutoCAD installations.
Lidar retains the revenue concentration, though Photogrammetry is expanding most quickly among new market entrants.
Application:
Customer type maturity determines workflow integration depth and procurement cycle length.
- Urban Planning:Municipal governments in Germany's Ruhr region and France's Lyon corridor bundle 3D spatial data into tenders for flood modeling, traffic simulation, and zoning compliance. Legacy CAD friction complicates cloud-native platform rollouts in older industrial cities.
- Environmental Monitoring:CSRD disclosure rules force French and German corporates to quantify land-use change and carbon stock, creating mandatory demand for lidar-derived elevation models and photogrammetric baselining.
- Construction:Same-day deliverables for site verification drive edge computing adoption among contractors serving Germany's automotive manufacturing belt.
- Transportation:Rail operators require algorithmic audit trails under EU AI Act risk classification frameworks that legacy black-box models cannot satisfy.
Environmental Monitoring commands the steepest expansion trajectory, while Urban Planning holds the installed base.
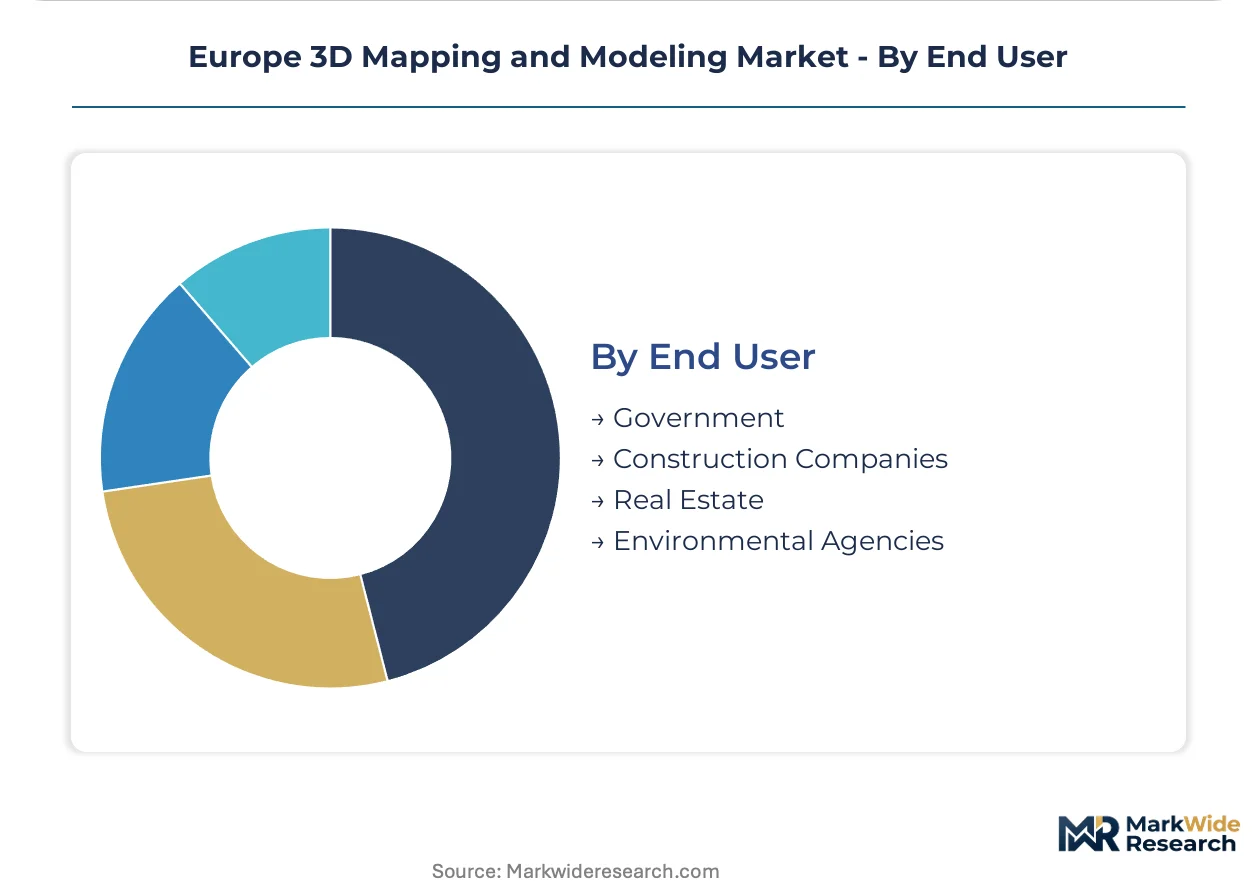
End User:
Volume concentration aligns with public infrastructure spending cycles and regulatory enforcement intensity.
- Government:Municipal procurement in France and Germany accelerates through EU Green Deal digital twin mandates compressing multi-year contract timelines.
- Construction Companies:Project-based contracting dominates vendor selection, favoring subscription pricing over perpetual licenses.
- Real Estate:Property developers in the Netherlands and Belgium prioritize operational expenditure predictability for portfolio digitization.
- Environmental Agencies:ECHA documentation standards and REACH compliance direct investment toward non-invasive surveying methods reducing field personnel exposure.
Government accounts anchor procurement volume, while Environmental Agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal governments and aerospace manufacturers concentrate procurement across Germany, France, and the Netherlands, while Spain and Italy present underpenetrated terrain for agricultural and coastal applications.
Germany
Automotive OEMs in Baden-Württemberg and North Rhine-Westphalia drive demand for millimeter-accurate lidar verification of production tooling. The EU Green Deal's digital twin mandates compress procurement cycles for municipal flood modeling in the Ruhr region. Stuttgart's manufacturing belt sustains premium sensor allocation despite automotive sector demand surges.
France
Aerospace suppliers in the Toulouse corridor and Île-de-France adopt neural radiance fields for rapid prototyping workflows. CSRD disclosure rules force corporates to quantify land-use change through photogrammetric baselining. Lyon's urban planning offices bundle 3D spatial data into infrastructure tenders for traffic simulation and zoning compliance.
Netherlands
Mid-sized engineering consultancies in Randstad prioritize subscription pricing for operational expenditure predictability. GDPR data residency requirements favor hybrid deployment architectures with EU-hosted cloud infrastructure. Rotterdam's port authority deploys real-time point cloud processing for container terminal optimization.
Spain
Agricultural water management in Andalusia and Catalonia generates underpenetrated demand for satellite-derived digital elevation models. REACH compliance directs investment toward non-invasive surveying methods reducing field personnel exposure. Valencia's coastal erosion tracking programs lag Western EU adoption curves by three to five years.
Italy
Environmental agencies in Lombardy and Emilia-Romagna require 3D spatial baselining for chemical site documentation under ECHA standards. Photogrammetry cost curves open mid-budget surveying for agricultural cooperatives previously priced out of precision spatial data. Milan's construction sector experiments with edge computing for same-day site verification deliverables.
Europe 3D Mapping and Modeling Market Key Industry Players
Channel-controlling players compete with product-specialist players across deployment modes, creating a tiered structure where sensor-to-software vertical integration anchors premium positioning while cloud-native platforms capture mid-market expansion. The vendor base clusters around three strategic archetypes: full-stack sensor manufacturers, platform-centric software vendors, and geospatial data service integrators. Dominant competitive moves include strategic partnerships with municipal procurement bodies and portfolio diversification into AI-augmented feature extraction pipelines.
Among Sweden-based sensor-to-software conglomerates, Hexagon AB exemplifies the vertically integrated archetype with sovereign defense and surveying accounts. French software specialists Dassault Systemes SE and California-headquartered platform vendors Autodesk, Inc. occupy positions on the cloud-native vector serving mid-sized engineering consultancies. These three anchors represent divergent responses to EU AI Act compliance timelines and CSRD-driven procurement compression.
| Leading Market Players |
|---|
| Hexagon AB |
| Dassault Systemes SE |
| Bentley Systems, Inc. |
| Autodesk, Inc. |
| Airbus SE |
| Esri, Inc. |
| Trimble Inc. |
| Google LLC |
| Topcon Corporation |
| Others |
Cost & Logistics Intelligence
Stuttgart's manufacturing belt concentrates high-precision lidar module production, with German and Swedish component suppliers anchoring capacity that downstream integrators access through multi-year offtake agreements indexed to automotive sector demand cycles. This geographic concentration grants sensor manufacturers pricing power over mid-tier surveying firms while exposing buyers to allocation risk during OEM procurement surges.
Pricing Analysis
Cost-plus contracts with steel and semiconductor indexation dominate municipal procurement for smart city infrastructure, compressing margins for systems integrators serving Germany's Ruhr region and France's Lyon corridor. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade sovereign data custody from SaaS platforms targeting mid-sized engineering consultancies in the Netherlands and Belgium. Pricing pressure stems from photogrammetry cost curves undercutting lidar point clouds at scale, with Spanish agricultural cooperatives and Italian coastal monitoring programs exhibiting highest price sensitivity.
Supply Chain Analysis
Upstream feedstock for high-precision scanning systems draws from German automotive sensor fabs, Swedish optical component manufacturers, and Taiwanese semiconductor foundries. German and Swedish suppliers concentrate lidar module production, while photogrammetry hardware sources from Chinese drone manufacturers and South Korean image sensor foundries. Single-source vulnerability runs through German precision optics capacity, with REACH-aligned F-Gas Regulation compliance forcing hardware refresh cycles. Distribution runs through systems integrators holding municipal procurement frameworks and defense ministry security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's 3D mapping and modeling market sits in early-cycle expansion, with CSRD disclosure deadlines and EU Green Deal digital twin mandates accelerating penetration among corporates and municipal governments previously reliant on 2D spatial baselining.
For Market Incumbents: Insulate premium positioning by deepening captive supply of high-precision lidar modules through backward integration into Stuttgart-area sensor manufacturing, while accelerating EU AI Act pre-certification for lidar-AI fusion pipelines before compliance deadlines force competitor displacement. Threat substitution from neural radiance fields compressing hardware procurement budgets demands defensive patent filings around rapid prototyping workflows.
For New Entrants and Emerging Players: Pursue white-space expansion in Spain's agricultural water management and Italy's coastal erosion tracking, where satellite-derived digital elevation model adoption lags Western EU curves by three to five years. Target mid-budget surveying segments in Andalusia and Lombardy through photogrammetry platforms with subscription pricing that displaces perpetual license models among regional engineering cooperatives.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because EMA, ECHA, and EU Green Deal frameworks collectively mandate environmental impact digitization that 3D spatial baselining satisfies. Acquisition focus centers on geospatial data service integrators holding municipal procurement frameworks and defense security clearances. Signal to monitor: pace of EU AI Act implementation against lidar-AI fusion development timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Algorithmic audit trails for defense and rail operator procurement satisfy high-risk system classification requirements. |
| Backward Integration into Sensor Manufacturing | Captive supply of German precision optics reduces allocation risk during automotive sector demand surges. |
| Photogrammetry Platform Subscription Launch | Operational expenditure predictability captures mid-sized engineering consultancies in the Netherlands and Belgium. |
| Hybrid Deployment Architecture Rollout | EU-hosted cloud infrastructure satisfies GDPR data residency for cross-border infrastructure projects. |
| Neural Radiance Field Pipeline Development | Rapid prototyping workflows for French aerospace and German automotive designers compress hardware procurement budgets. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with municipal procurement officers, defense ministry surveying leads, geospatial data scientists, and civil engineering consultancy principals; and secondary validation through EU Green Deal implementation trackers, ECHA chemical site documentation standards, CSRD disclosure guidance, and national smart city tender databases. Bottom-up triangulation against top-down market sizing anchored volume estimates across deployment modes and technology segments.
Forecast inputs considered technology adoption curves, regulatory enforcement timelines, and municipal infrastructure spending cycles across the projection horizon. Segmentation dimensions modeled include deployment architecture, technology type, application vertical, and end-user category, with additional granularity on data sovereignty requirements and AI Act risk classification tiers. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion.
Sensitivities concentrate around EU AI Act implementation pace, automotive sector demand surges affecting sensor allocation, and fiber network density gaps delaying SaaS penetration in Eastern Europe. Cross-checking against EEA environmental monitoring expenditure benchmarks and national geospatial agency procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market