
 Satellite Image Data Services Market | 2026-2036
Satellite Image Data Services Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Image Data Services Market Analysis
The gap between premium sub-meter resolution contracts and commodity tasking services is repositioning how vendors structure pricing and capacity allocation. Maxar Technologies leverages its constellation of high-resolution optical satellites to anchor defense and intelligence relationships. Planet Labs sustains daily coverage density through its Dove and SkySat fleets, competing on temporal revisit rather than spatial precision. ICEYE differentiates with all-weather Synthetic Aperture Radar capability, occupying a niche where optical systems face atmospheric constraints.
Satellite Image Data Services encompass the capture, processing, analysis, and distribution of geospatial imagery from Earth-observation platforms, typically spanning spatial resolutions from 30-meter multispectral scans to sub-30-centimeter panchromatic frames, with revisit frequencies ranging from bi-daily to on-demand tasking for applications including cadastral mapping, crop health indexing, and maritime domain awareness. Image Processing and Analysis Services command expanding margin pools as customers shift from raw imagery procurement to derived intelligence products, while Optical Imaging retains volume leadership though Synthetic Aperture Radar is gaining share in defense and disaster-response segments where cloud penetration and night-time collection prove essential. Agriculture Monitoring and Disaster Response applications are absorbing disproportionate investment as climate volatility intensifies demand for predictive analytics and rapid damage assessment.
NOAA and the US National Geospatial-Intelligence Agency shape procurement standards through resolution and accuracy certifications that gate access to classified workflows, while the EU Space Surveillance and Tracking programme and GDPR-aligned data-localization rules constrain cross-border imagery distribution for European operators. Commercial enterprises and government agencies must monitor how ITAR export controls and emerging orbital-debris regulations reshape constellation deployment timelines and international partnership structures.
Market Dynamics
The satellite imagery sector is reconfiguring around a supply squeeze in launch capacity and a demand surge for analytics-ready data products, compressing margins for raw imagery wholesalers while expanding them for vertically integrated intelligence platforms.
Growth Catalysts
- EU Space Surveillance and Tracking framework:Mandates collision avoidance and debris monitoring for commercial operators, creating recurring revenue streams for tracking data services and orbital safety analytics.
- Defense and intelligence procurement:Border surveillance and threat detection programs across NATO member states are locking in multi-year tasking contracts for high-resolution optical and SAR constellations.
- Synthetic Aperture Radar maturation:All-weather, day-night collection capability is penetrating disaster response and maritime domain awareness applications where optical systems face persistent cloud cover constraints.
Market Restraints
- Launch cost volatility:Dependence on limited heavy-lift providers concentrates constellation deployment risk, with slot scarcity extending deployment timelines for new entrants.
- Data sovereignty fragmentation:GDPR-aligned localization rules and ITAR export controls create jurisdictional friction for cross-border imagery distribution, forcing redundant ground infrastructure investments.
- Optical atmospheric limitation:Persistent cloud cover in tropical and maritime zones degrades collection economics for electro-optical platforms, capping addressable market share regardless of resolution advancement.
Strategic Opportunities
- Agriculture predictive analytics:Crop health indexing and yield forecasting applications remain underpenetrated in South American and Southeast Asian markets, offering first-mover advantages for localized model training.
- AI-ML fusion with SAR:Machine learning classification of radar backscatter signatures enables automated change detection, opening subscription-based monitoring services for infrastructure and environmental compliance.
- US National Geospatial-Intelligence Agency certification pathways:Resolution and accuracy standards gating classified workflows create vendor consolidation incentives for operators achieving full certification.
Industry Challenges
- Geospatial data scientist scarcity:Shortage of practitioners capable of fusing multi-sensor feeds with ground-truth validation is constraining analytics product rollout timelines.
- Legacy ground system integration:Defense and intelligence customers require seamless ingestion into existing GEOINT architectures, demanding costly middleware development for non-standard formats.
- Orbital debris liability exposure:Emerging regulations on end-of-life disposal and active debris removal are extending insurance costs and compliance overhead for constellation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Image Data Services Market |
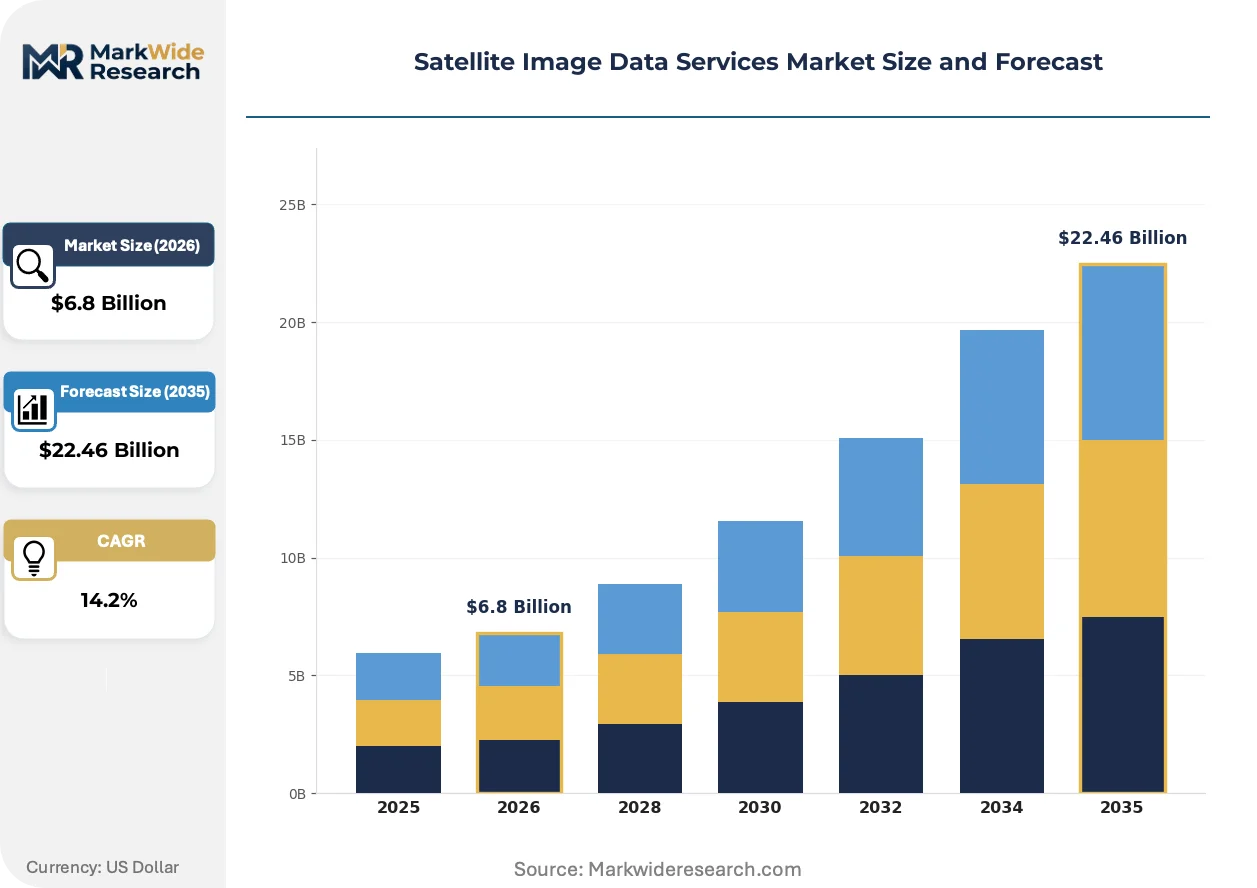
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Image Processing, Analysis Services, Consulting Application: Agriculture Monitoring, Urban Planning, Disaster Response, Environmental Assessment Technology: Optical Imaging, Synthetic Aperture Radar, Multispectral Imaging, Hyperspectral Imaging End User: Government Agencies, Research Institutions, Commercial Enterprises, NGOs |
| Companies Covered | Maxar Technologies, Airbus, Planet Labs, L3Harris Technologies, ICEYE, BlackSky, Ursa Space Systems, Satellite Imaging Corporation, EOS Data Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Image Data Services Market Emerging Trajectories
Automation of image processing pipelines and the migration from pixel delivery to decision-ready intelligence products are compressing value capture toward analytics layers while commoditizing raw acquisition.
Synthetic Aperture Radar is overtaking electro-optical systems in defense and disaster-response procurement cycles where atmospheric penetration determines mission success. Maritime domain awareness and flood monitoring agencies are accelerating SAR adoption despite higher per-scene costs. This modality shift is compressing addressable market share for pure-play optical operators in tropical and high-latitude zones.
GDPR-aligned data-localization mandates are fragmenting cloud storage architectures for European operators, forcing ground segment investments in EU sovereign territory. The EU Space Surveillance and Tracking programme extends this sovereignty logic to orbital safety data, requiring member-state residency for critical tracking services. Commercial providers are responding with dual-ground-station deployments and jurisdictional data routing to maintain cross-border contract eligibility.
Subscription-based monitoring contracts are displacing per-tasking procurement in agriculture and infrastructure verticals, locking in recurring revenue but demanding guaranteed revisit density. Insurance and commodity trading firms are driving this shift, requiring continuous temporal coverage rather than episodic capture. The United States and Brazil exhibit the strongest migration toward annual subscription models, compressing spot-market liquidity for ad-hoc tasking.
Satellite Image Data Services Market Segmentation
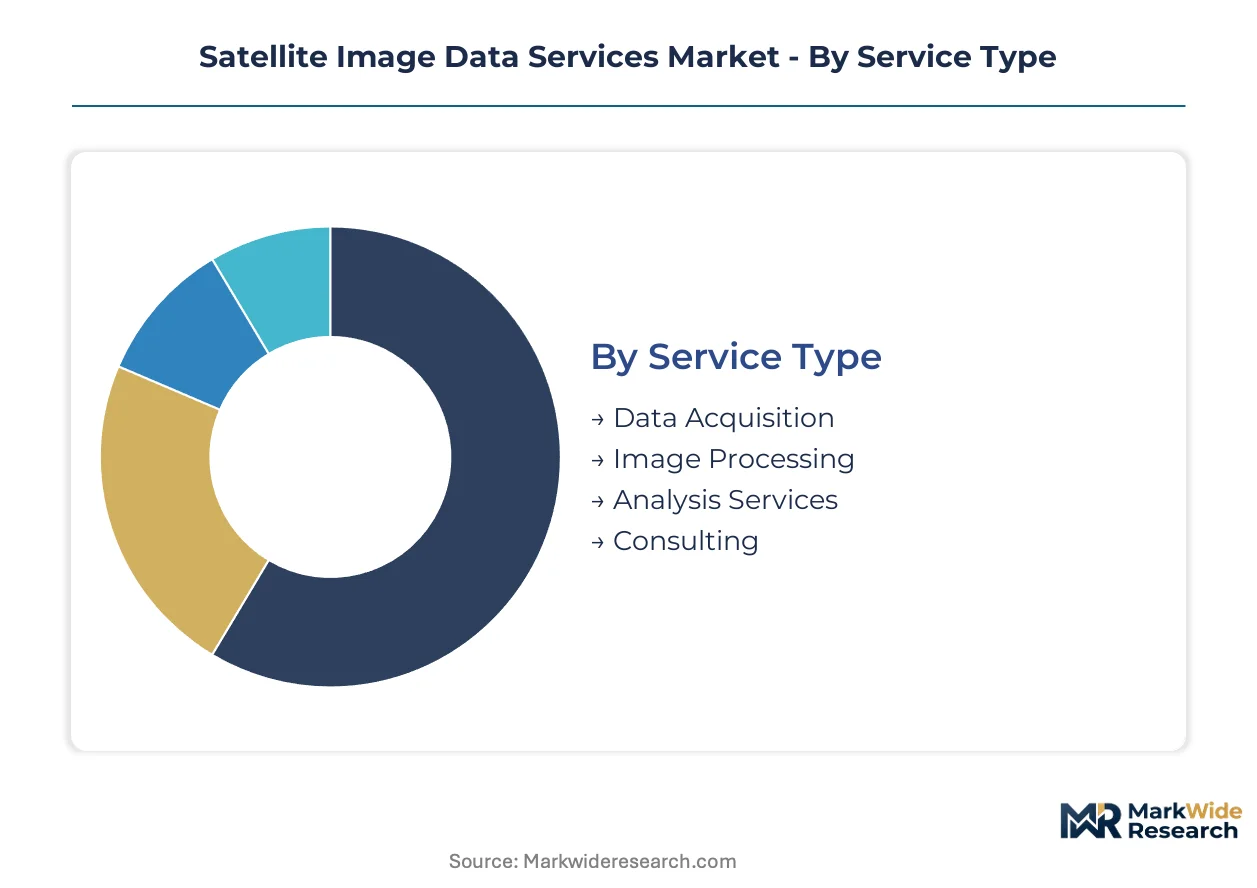
Segmentation in satellite imagery services determines which vendors qualify for defense contracts, how pricing tiers align with resolution specifications, and where analytics capabilities create margin expansion. Certification requirements from NOAA and the US National Geospatial-Intelligence Agency gate access to classified workflows, fragmenting competitive position by segment.
Service Type:
NOAA resolution certifications and NGA accuracy standards apply differentially across service tiers, with raw data acquisition facing lighter compliance burdens than finished intelligence products.
- Data Acquisition:Constellation operators capture panchromatic, multispectral, and radar imagery through owned or leased satellite assets. Defense and intelligence agencies in the United States concentrate procurement here, locking in multi-year tasking contracts for sub-meter resolution coverage.
- Image Processing:Radiometric correction, orthorectification, and mosaicking transform raw sensor data into georeferenced products. Commercial enterprises in Brazil and Southeast Asia drive demand for cloud-free, analysis-ready imagery, constrained by atmospheric degradation in tropical zones.
- Analysis Services:Change detection, feature extraction, and predictive modeling deliver decision-ready intelligence rather than pixel products.
- Consulting:Mission planning, sensor selection advisory, and integration support for ground segment architectures.
Leading the category by volume: Data Acquisition. Growing fastest: Analysis Services.
Application:
Cost tier differentiation separates episodic disaster response procurement from subscription-based agriculture monitoring contracts.
- Agriculture Monitoring:Crop health indexing, yield forecasting, and irrigation optimization leverage temporal revisit density over spatial precision. Commodity trading firms and agribusiness operators in the United States and Brazil are migrating toward annual subscription models, compressing spot-market liquidity.
- Disaster Response:Rapid damage assessment and flood extent mapping demand all-weather collection capability. FEMA and international relief agencies prioritize Synthetic Aperture Radar for cloud-penetrating, night-capable acquisition in tropical and high-latitude zones where optical systems fail.
- Urban Planning:Cadastral mapping, infrastructure monitoring, and zoning enforcement applications.
- Environmental Assessment:Deforestation tracking, carbon stock estimation, and ecosystem health monitoring.
Volume concentration: Agriculture Monitoring. Steepest expansion trajectory: Disaster Response.
Technology:
Maturity curves separate decades-old optical platforms from emerging SAR constellations still scaling manufacturing and launch cadence.
- Optical Imaging:Electro-optical sensors capture panchromatic and multispectral data at resolutions from 30 meters to sub-30 centimeters. Persistent cloud cover in maritime and tropical regions degrades collection economics, capping addressable market share regardless of resolution advancement.
- Synthetic Aperture Radar:Active microwave sensors enable day-night, all-weather imaging through cloud, rain, and darkness. NATO maritime domain awareness programs and flood monitoring agencies in Southeast Asia are accelerating procurement despite higher per-scene costs.
- Multispectral Imaging:Discrete band capture across visible, near-infrared, and shortwave infrared wavelengths for vegetation and mineral discrimination.
- Hyperspectral Imaging:Continuous narrow-band spectral sampling enables material identification and biochemical property estimation.
Dominant by revenue: Optical Imaging. Expanding most quickly: Synthetic Aperture Radar.
End User:
Customer type determines contract structure, with government agencies demanding ITAR-compliant supply chains and commercial enterprises prioritizing API accessibility and cloud-native delivery.
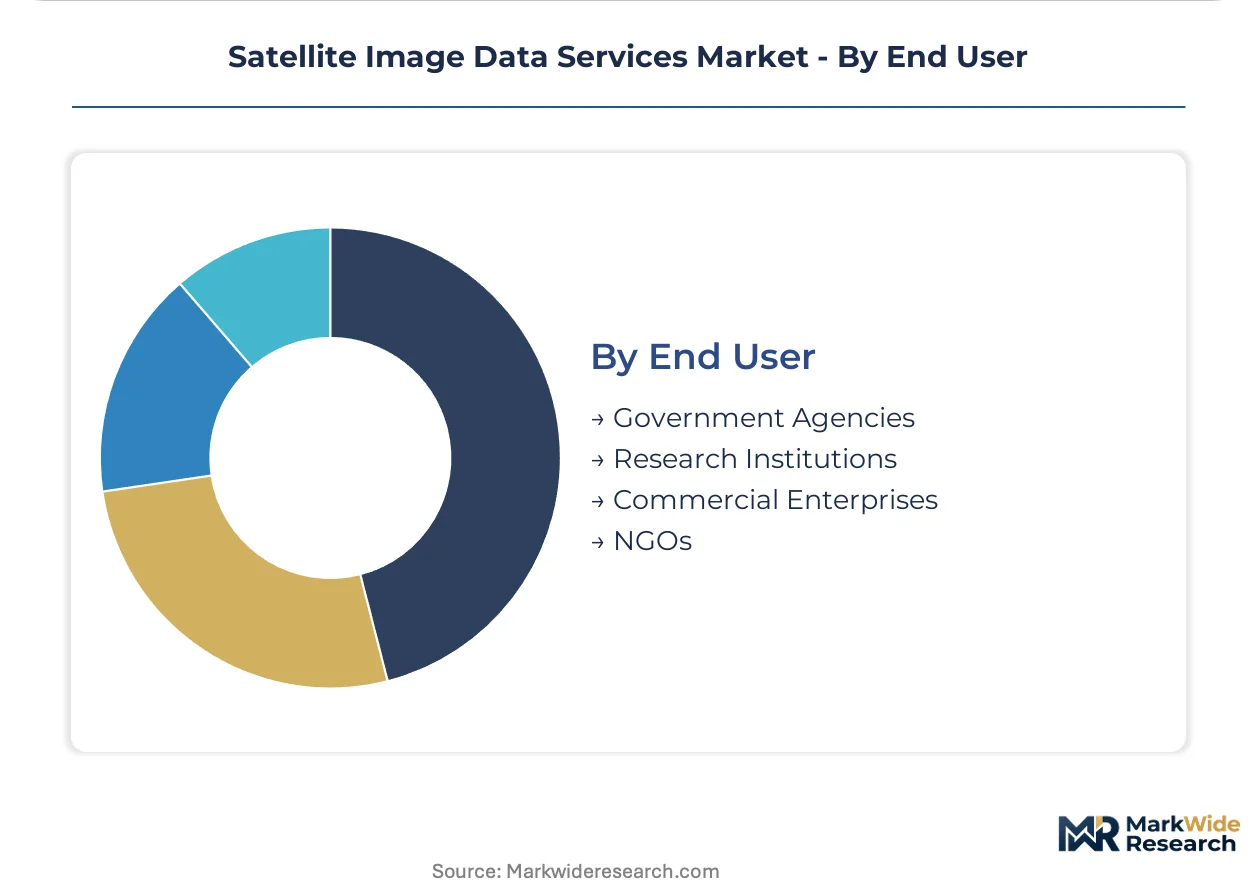
- Government Agencies:Defense, intelligence, and civilian mapping organizations procure through formal acquisition programs with resolution and accuracy certifications. The US National Geospatial-Intelligence Agency and NOAA shape procurement standards that gate vendor participation in classified workflows.
- Commercial Enterprises:Agriculture, insurance, finance, and infrastructure operators consume imagery through subscription APIs and analytics platforms. GDPR-aligned data-localization rules force redundant ground infrastructure investments for European operators serving these customers.
- Research Institutions:Universities and national laboratories access archived and tasking data through educational licensing programs.
- NGOs:Conservation, humanitarian, and development organizations leverage imagery for transparency and accountability applications.
Largest revenue pool: Government Agencies. Fastest contract volume growth: Commercial Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American geospatial intelligence procurement through the US National Geospatial-Intelligence Agency's contractor concentration and NOAA's certification authority. Federal tasking contracts sustain the largest revenue pool for high-resolution imagery services.
United States
Defense and intelligence agencies in Colorado and Virginia drive sub-meter resolution procurement for border surveillance and maritime domain awareness. NOAA and NGA certification standards gate vendor access to classified workflows. The Denver-Aurora corridor hosts Maxar Technologies and multiple imagery analytics clusters serving federal contracts.
Canada
Arctic sovereignty monitoring and natural resource extraction in Alberta and Saskatchewan sustain demand for Synthetic Aperture Radar capability. The Canadian Space Agency's RADARSAT program shapes domestic procurement standards for all-weather imaging. Montreal and Toronto house ground segment operations for cross-border defense partnerships.
Germany
Bavaria-based aerospace manufacturers and Munich's satellite control centers anchor European optical imaging capacity. GDPR-aligned data-localization rules force redundant ground infrastructure investments for commercial operators serving EU clients. The country's national space agency DLR influences pan-European Earth observation policy through Copernicus participation.
United Kingdom
Defense intelligence procurement through the UK Space Agency and Ministry of Defence sustains demand for high-revisit optical constellations. Harwell's space cluster hosts imagery analytics operations serving NATO maritime surveillance contracts. British operators navigate post-Brexit data-sharing friction with EU Space Surveillance and Tracking frameworks.
Japan
Disaster response agencies in Tokyo and Osaka prioritize SAR procurement for earthquake and flood monitoring where cloud cover degrades optical collection. METI's space industrial policy promotes domestic constellation manufacturing. The Tsukuba space cluster integrates JAXA research with commercial imagery distribution platforms.
Satellite Image Data Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across resolution certification tiers, with NGA-accredited operators capturing multi-year defense contracts while uncertified wholesalers compete on spot-market tasking prices. The vendor base stratifies into three archetypes: constellation owners with captive satellite assets, analytics platforms aggregating multi-source feeds, and defense contractors integrating imagery into broader intelligence systems. Dominant competitive moves include backward integration into launch services and strategic partnerships with AI-ML model providers for automated feature extraction.
Within the constellation-owner tier, Maxar Technologies exemplifies the premium-position archetype through its high-resolution optical heritage, while ICEYE occupies a specialized position representing the all-weather SAR capability segment. Among analytics-focused operators, Planet Labs anchors the high-revisit density model competing on temporal coverage rather than spatial precision. These three companies illustrate how resolution certification, revisit frequency, and atmospheric penetration capability define competitive positioning in procurement cycles.
| Leading Market Players |
|---|
| Maxar Technologies |
| Airbus |
| Planet Labs |
| L3Harris Technologies |
| ICEYE |
| BlackSky |
| Ursa Space Systems |
| Satellite Imaging Corporation |
| EOS Data Analytics |
| Others |
Supply Flow & Price Mechanics
Geospatial data scientist scarcity in the Denver-Aurora corridor and Munich satellite control centers widens labor-cost differentials between premium analytics tiers and commodity imagery products. ITAR-compliant workforce premiums in Colorado and GDPR-aligned data-localization engineering costs in Bavaria feed directly into pricing spreads across certification-grade service levels.
Pricing Analysis
Outcome-based pricing anchored to actionable intelligence delivery dominates defense and intelligence contracts, separating NGA-certified vendors from uncertified wholesalers. Three-tier pricing structure across premium, standard, and economy levels aligns with resolution certification, temporal revisit guarantees, and atmospheric penetration capability. Price compression runs through raw imagery spot markets as subscription models lock in recurring revenue for analytics-ready products. Commercial enterprises in Brazil and Southeast Asia exhibit highest price sensitivity, while NATO maritime domain awareness programs demonstrate lowest elasticity for all-weather SAR tasking.
Supply Chain Analysis
Heavy-lift launch capacity rests on United States, Russia, and China providers, with slot scarcity extending constellation deployment timelines for new entrants. Satellite bus manufacturing draws from German precision engineering, Japanese sensor components, and Canadian SAR antenna specialists. Single-source vulnerability concentrates in SpaceX Falcon Heavy and Long March launch manifests, exposing deployment schedules to geopolitical friction. Distribution runs through dual-ground-station architectures with jurisdictional data routing to satisfy GDPR and ITAR compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation operators and analytics platforms are racing to capture upstream launch services and downstream AI-ML model providers, compressing margin capture toward vertically integrated intelligence delivery.
For Market Incumbents: Acquire synthetic aperture radar manufacturing capacity to defend against optical atmospheric limitations in tropical and maritime zones. Lock in multi-year NATO tasking contracts before SAR procurement cycles mature. Certification investment in NOAA and NGA accuracy standards gates vendor participation in classified workflows, creating consolidation incentives for accredited operators. For New Entrants and Emerging Players: Enter via agriculture predictive analytics in South American and Southeast Asian markets where crop health indexing remains underpenetrated. Target subscription-based monitoring contracts displacing per-tasking procurement in insurance and commodity trading verticals. Partner with localized model training providers to overcome geospatial data scientist scarcity constraining analytics rollout timelines. For Investors and Strategic Acquirers: Re-rating potential sits with AI-ML fusion specialists given automated change detection catalysts opening subscription infrastructure monitoring services. Long-term viability centers on analytics-layer margin capture rather than raw imagery commoditization. Watch NGA certification pathway completion rates as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Launch Services | SpaceX and Long March slot scarcity forces captive heavy-lift capacity to secure constellation deployment timelines. |
| AI-ML Model Provider Acquisition | Machine learning classification of radar backscatter signatures enables automated infrastructure compliance monitoring subscriptions. |
| Dual-Ground-Station Deployment | Jurisdictional data routing through EU and US sovereign territory satisfies GDPR localization and ITAR export control requirements. |
| NGA Certification Investment | Resolution and accuracy standards gating classified workflows create vendor consolidation incentives for accredited operators. |
| SAR Constellation Scale-Up | All-weather capability penetrates disaster response and maritime domain awareness where optical systems face cloud cover constraints. |
Methodological Framework
SEC 10-K filings, NOAA resolution certification databases, and NATO procurement registries formed the secondary backbone, cross-referenced with primary interviews across constellation operators, defense intelligence procurement officers, geospatial analytics platform engineers, and satellite ground segment architects. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level revenue estimates across service type, application, technology, and end-user dimensions.
Historical trendline analysis of tasking contract volumes and subscription migration patterns anchored the projection framework across the analysis window. Segmentation modeling incorporated service tier, resolution certification level, revisit frequency guarantee, and regional regulatory cluster. CAGRs derived from weighted average of technology diffusion curves and procurement cycle maturation, with specific inputs from SAR manufacturing scale-up timelines and AI-ML model deployment rates in agriculture and infrastructure verticals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under launch cost volatility and orbital debris liability exposure scenarios. Assumptions reflect current ITAR export control regimes and EU Space Surveillance and Tracking framework mandates. Launch slot availability, geospatial data scientist labor market tightness, and NGA certification queue lengths warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market