
 Electronic Cartography Market | 2026-2036
Electronic Cartography Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Cartography Market Analysis
The EU Green Deal's digital mapping requirements for environmental monitoring is expanding the addressable market for electronic cartography vendors serving European public sector clients. Garmin leverages its consumer navigation heritage to compete in outdoor recreation mapping, while Thales anchors defense-grade electronic chart systems for naval command platforms. Honeywell Aerospace dominates integrated flight deck solutions where cartographic databases synchronize with avionics suites.
Electronic cartography encompasses the digital creation, storage, manipulation, and visualization of geographic information through vector and raster data structures, typically rendered at scales from 1:1,000 for urban planning to 1:500,000 for aeronautical route segments. Its primary commercial purpose is to replace paper-based charts with real-time, updateable spatial databases that integrate positioning telemetry and sensor feeds. Software solutions lead revenue contribution as agencies migrate from perpetual licenses to subscription-based SaaS platforms, while GIS technology captures the fastest expansion due to its interoperability with IoT sensor networks and AI-driven spatial analytics. Hardware segments face margin compression as commoditized GPS receivers and display units compete with smartphone-based alternatives.
FAA mandates for electronic flight bag compatibility and EASA's instrument flight procedure digitization standards shape product certification requirements for aviation-facing suppliers. The EPA and EEA both enforce geospatial data standards for environmental compliance reporting, creating dual jurisdictional complexity for multinational platform vendors. Stakeholders must monitor how emerging sovereign data localization laws in defense-critical markets reshape cross-border cloud hosting strategies for sensitive terrain databases.
Market Dynamics
Cloud-native GIS architectures are displacing legacy on-premise deployments across defense and civilian agencies, compressing deployment cycles from months to weeks while forcing vendors to restructure pricing around consumption-based SaaS metrics.
Growth Catalysts
- EU Green Deal mandates:Environmental monitoring requirements across European public sector clients expand procurement of digital mapping platforms for land-use tracking and carbon accounting.
- IoT sensor mesh density:Real-time telemetry integration from connected infrastructure assets drives demand for geospatial databases that synchronize positioning data with sensor feeds.
- NATO defense procurement:Allied military modernization programs accelerate adoption of electronic chart systems for mission planning and battlefield situational awareness.
Market Restraints
- Semiconductor supply concentration:Specialized GPU and FPGA components for real-time rendering face sourcing constraints from Taiwan-based foundry capacity limitations.
- Sovereign data localization:Defense-critical markets impose cross-border hosting restrictions that fragment cloud infrastructure economics and duplicate compliance costs.
- Smartphone navigation substitution:Consumer-grade GPS applications erode addressable demand for dedicated handheld cartographic hardware in outdoor recreation segments.
Strategic Opportunities
- AI-driven spatial analytics convergence:Machine learning inference layered atop vector databases enables predictive terrain analysis for autonomous vehicle routing.
- Subscription model migration:Perpetual license displacement creates recurring revenue pools as federal agencies adopt SaaS platforms with automatic update pipelines.
- India infrastructure digitization:National geospatial policy reforms open public procurement to private electronic cartography vendors for urban planning applications.
Industry Challenges
- Geodetic datum harmonization:Inconsistent coordinate reference systems across national mapping agencies force costly transformation layer development for multinational deployments.
- Avionics certification timelines:FAA and EASA airworthiness validation for integrated flight deck databases extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Cartography Market |
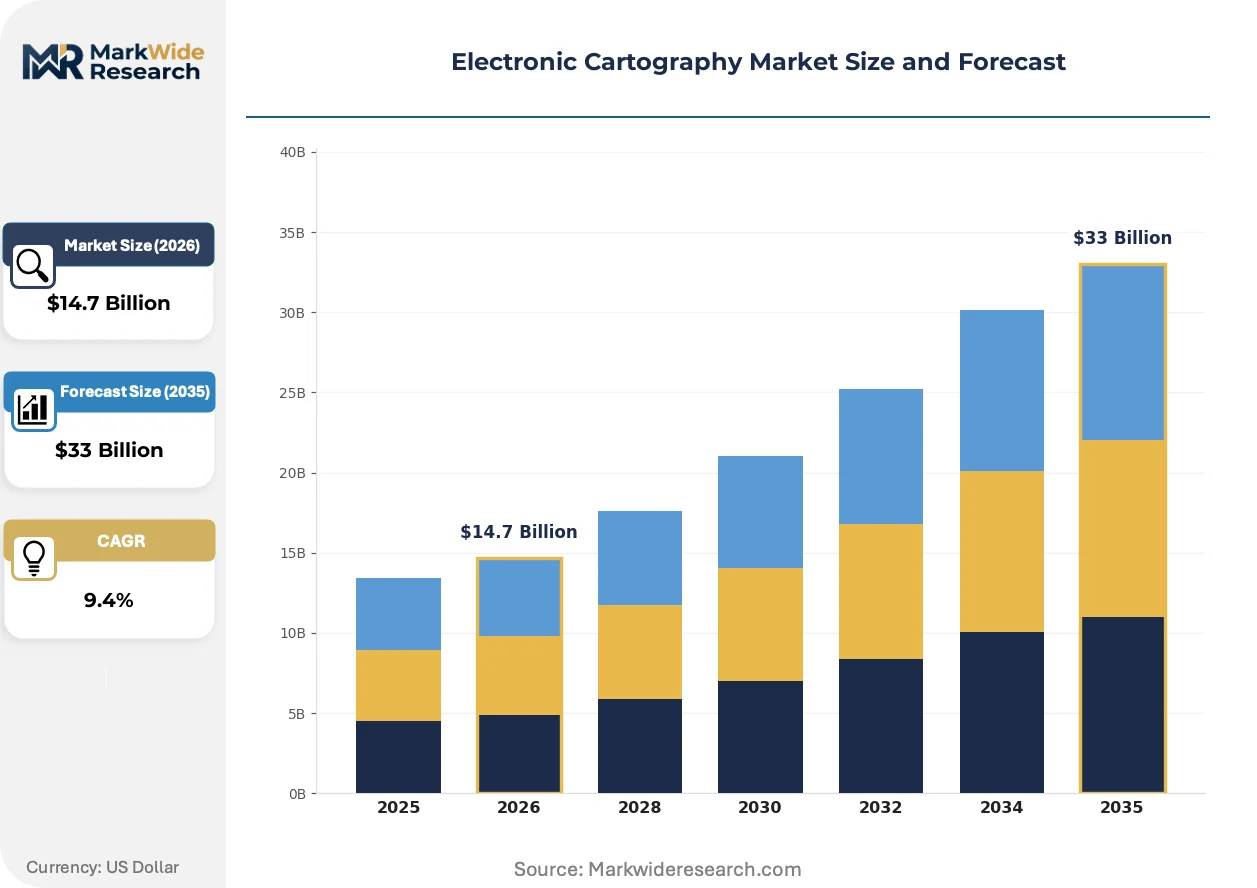
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Mapping Tools, Navigation Systems Application: Transportation, Urban Planning, Environmental Monitoring, Disaster Management End User: Government Agencies, Private Companies, Educational Institutions, NGOs Technology: GIS, GPS, Remote Sensing, 3D Mapping |
| Companies Covered | Jeppesen, Garmin, Universal Avionics, Rockwell Collins, Honeywell Aerospace, Thales, Northrop Grumman, Esri, Transas Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Cartography Market Emerging Trajectories
Real-time cartographic rendering is compressing the boundary between data collection and visualization, enabling dynamic map layers that refresh from sensor inputs rather than static batch updates.
Vector tile streaming is consolidating how urban planning agencies consume base map data, replacing bulk downloads with viewport-bounded requests. Municipal GIS departments in Germany and the Netherlands have adopted this architecture for zoning visualization tools. The shift compresses storage requirements while enabling sub-second zoom-level transitions that raster pyramids cannot match.
EASA instrument flight procedure digitization standards mandate electronic chart compatibility for all new avionics certifications, forcing navigation database suppliers to restructure quality assurance pipelines. Honeywell Aerospace and Thales have reconfigured their terrain validation workflows to meet these requirements. The regulation compresses supplier margins while raising barriers for uncertified entrants.
Consumption-based licensing is supplanting seat-count models across federal procurement channels, with US Geological Survey and Environment Agency contracts now tied to API call volumes rather than user entitlements. SaaS-native vendors capture this transition faster than legacy platform providers. The pattern concentrates account value in platforms with elastic infrastructure rather than installed-base incumbents.
Electronic Cartography Market Segmentation
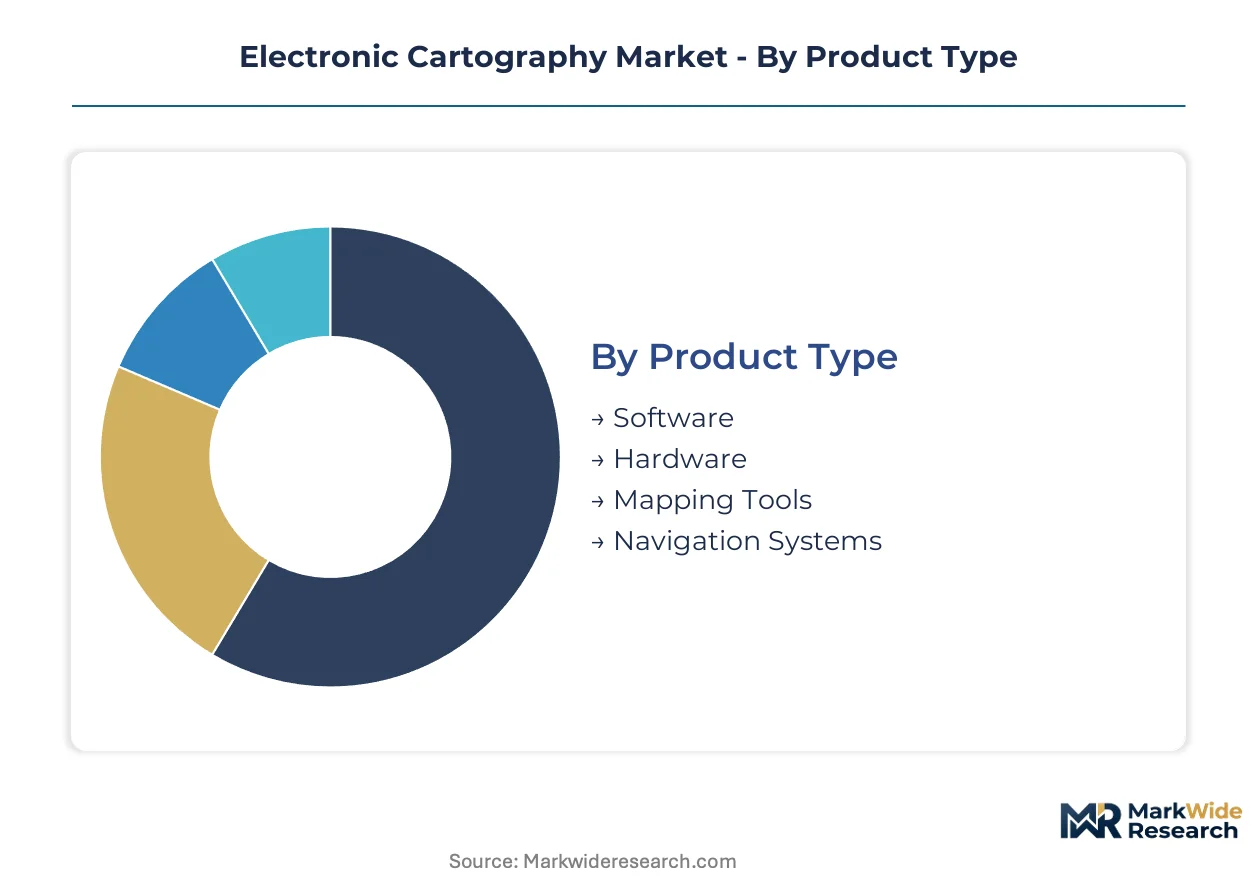
Electronic cartography vendors structure offerings around distinct procurement cycles and capability tiers. Software platforms displace installed systems on 3-5 year refresh schedules, while hardware refresh extends to 7-10 year cycles in defense applications. Understanding segment boundaries clarifies where subscription revenue concentrates versus capital expenditure dominance.
Product Type:
Upgrade cycles vary sharply across product categories, with cloud-native software compressing deployment timelines against extended hardware certification periods.
- Software:Cloud-native GIS platforms deliver vector and raster data manipulation through browser-based interfaces with automatic update pipelines. Federal geospatial modernization initiatives in the United States and EU Green Deal digitization mandates in Germany and France concentrate procurement of SaaS-based mapping suites.
- Hardware:Specialized GPU and FPGA components power real-time terrain rendering for avionics and naval command platforms. NATO defense procurement programs across member states sustain demand for ruggedized display units and positioning receivers despite smartphone substitution pressure in consumer segments.
- Mapping Tools:Vector tile streaming architectures enable viewport-bounded data consumption for municipal zoning visualization.
- Navigation Systems:Integrated flight deck solutions synchronize cartographic databases with avionics suites under FAA and EASA certification requirements.
Volume placements concentrate in Software; the faster expansion belongs to Navigation Systems.
Application:
Cost-tier differentiation separates enterprise-grade deployments from municipal procurement, with environmental monitoring commanding premium pricing against standardized urban planning tools.
- Transportation:Autonomous vehicle routing and fleet management systems ingest real-time telemetry for dynamic path optimization. AI-driven spatial analytics convergence in the United States and India infrastructure digitization programs drive procurement of predictive terrain analysis platforms.
- Urban Planning:Zoning visualization tools leverage vector tile streaming to compress storage requirements and enable sub-second zoom transitions. German and Dutch municipal GIS departments have adopted this architecture for land-use tracking applications.
- Environmental Monitoring:Carbon accounting and compliance reporting platforms integrate IoT sensor meshes with geospatial databases.
- Disaster Management:Real-time situational awareness systems synchronize positioning data with emergency response coordination.
Revenue concentration sits with Transportation; Environmental Monitoring climbs the fastest as EU Green Deal mandates expand addressable demand.
End User:
Customer-type fragmentation creates distinct sales motion requirements, with government agencies demanding FedRAMP-equivalent compliance against commercial sector speed-to-value priorities.
- Government Agencies:Federal procurement channels in the United States and national geospatial policy reforms in India drive consumption-based licensing adoption. US Geological Survey and Environment Agency contracts now tie vendor compensation to API call volumes rather than seat counts.
- Private Companies:Logistics and infrastructure operators deploy electronic cartography for asset tracking and route optimization.
- Educational Institutions:Research consortia license base map data for academic spatial analysis and training programs.
- NGOs:Humanitarian organizations utilize portable mapping tools for field-based disaster response coordination.
Account value aggregates in Government Agencies; Private Companies gain share fastest as consumption-based models penetrate commercial procurement.
Technology:
Supply concentration in specialized components creates margin tiering, with GIS platforms capturing recurring revenue against commoditized GPS receiver hardware.
- GIS:Interoperability with IoT sensor networks and AI-driven spatial analytics positions geographic information systems as the central integration layer. Cloud-native architectures displace legacy on-premise deployments across defense and civilian agencies.
- GPS:Positioning telemetry integration underpins real-time map refreshing from sensor inputs rather than static batch updates.
- Remote Sensing:Satellite and aerial imagery feeds enable environmental monitoring and land-use classification at scale.
- 3D Mapping:Lidar and photogrammetry pipelines generate terrain models for autonomous vehicle navigation and urban digital twin applications.
Deployment scale favors GIS; 3D Mapping exhibits the steepest expansion trajectory as autonomous vehicle routing requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of electronic cartography systems concentrates in defense-industrial clusters across the United States and France, while consumption spreads across NATO procurement channels and civilian agencies. The United States generates the largest procurement volumes through federal geospatial modernization programs. Germany and the Netherlands anchor European municipal adoption through vector tile streaming architectures.
United States
Federal agencies drive demand through the US Geological Survey's consumption-based licensing contracts and FAA mandates for electronic flight bag compatibility. EPA geospatial data standards enforce environmental compliance reporting requirements that shape vendor certification pipelines. Defense procurement concentrates in the Washington-Baltimore corridor where Northrop Grumman and Honeywell Aerospace maintain integrated flight deck development facilities.
Germany
Municipal GIS departments in Berlin and Munich deploy vector tile streaming for zoning visualization and land-use tracking applications. EU Green Deal mandates expand addressable demand for carbon accounting platforms that integrate geospatial databases with IoT sensor meshes. The country's national mapping agency enforces geodetic datum standards that force transformation layer development for multinational platform vendors.
France
Thales anchors naval command platform development from defense-industrial clusters outside Paris, supplying electronic chart systems for NATO mission planning. EASA instrument flight procedure digitization standards mandate quality assurance restructuring for navigation database suppliers. The Île-de-France region hosts avionics certification workflows that extend product launch cycles by 18-24 months.
India
National geospatial policy reforms open public procurement to private electronic cartography vendors for urban planning applications in Delhi-NCR and Maharashtra. The country's central mapping regulator enforces localization requirements that reshape cross-border cloud hosting strategies for sensitive terrain databases. Infrastructure digitization programs in Karnataka and Telangana drive predictive terrain analysis platform adoption for autonomous vehicle routing.
Netherlands
Municipal zoning visualization tools in Amsterdam and Rotterdam leverage viewport-bounded data consumption architectures that compress storage requirements. EU environmental monitoring mandates expand procurement of digital mapping platforms for land-use tracking across Dutch water management districts. The Randstad cluster concentrates SaaS-native vendors capturing subscription model migration faster than legacy platform providers.
Electronic Cartography Market Vendor Landscape
The competitive structure tilts toward defense-aerospace conglomerates with extended certification timelines and SaaS-native geospatial specialists with compressed deployment cycles. Tiered positioning separates avionics-integrated platform vendors from municipal GIS tool providers. Three archetypes dominate: vertically integrated flight deck suppliers, cloud-native mapping platform vendors, and handheld navigation heritage players. M&A activity concentrates in geospatial data aggregation assets, while strategic partnerships proliferate between sensor manufacturers and vector database providers.
Among defense-aerospace conglomerates, Thales and Northrop Grumman exemplify the avionics-integrated archetype through extended certification workflows and NATO procurement relationships. Garmin occupies a position bridging consumer navigation heritage with outdoor recreation mapping applications. Esri represents the SaaS-native platform tier, anchoring municipal and federal agency migration from perpetual licenses to consumption-based API models.
| Leading Market Players |
|---|
| Jeppesen |
| Garmin |
| Universal Avionics |
| Rockwell Collins |
| Honeywell Aerospace |
| Thales |
| Northrop Grumman |
| Esri |
| Transas Marine |
| Others |
Supply Flow & Price Mechanics
NATO defense procurement programs concentrate buying power among certified avionics suppliers, forcing pricing models toward long-term service contracts with embedded update subscriptions rather than perpetual licenses.
Pricing Analysis
Margin tightening in hardware tiers traces to smartphone GPS substitution eroding consumer handheld demand while defense-grade systems command certification premiums. Three-tier pricing structure across defense-integrated, municipal-SaaS, and consumer-outdoor levels separates Honeywell's flight deck bundles from Esri's API-metered platforms and Garmin's retail units. Price differentiation hinges on FAA airworthiness validation tier and data refresh frequency. Cost-down pressure on municipal GIS accelerates as vector tile streaming commoditizes base map delivery. Government agencies exhibit lowest price sensitivity due to FedRAMP compliance requirements, while outdoor recreation buyers face highest substitution elasticity.
Supply Chain Analysis
Dual-sourcing mandates from defense buyers force GPU and FPGA qualification across Taiwan Semiconductor Manufacturing Company and Samsung Foundry capacity, fragmenting volume discounts. Component supply draws from Taiwan for specialized rendering chips, the United States for ruggedized display assemblies, and Germany for precision positioning receivers. Raw material dependencies include high-purity silicon substrates, gallium arsenide wafers, and rare-earth magnet alloys for antenna systems. Single-source vulnerability concentrates in Taiwan-based foundry capacity for real-time terrain processing chips. Distribution runs through defense-industrial integrators for NATO programs, direct SaaS provisioning for federal agencies, and retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA and EASA certification timelines erect a cost-of-compliance moat that protects incumbent avionics suppliers from uncertified entrants, with airworthiness validation extending product cycles by 18-24 months.
For Market Incumbents: Anticipate smartphone navigation substitution by hardening defense certification pipelines and deepening API consumption metrics in federal contracts. Consolidate position through backward integration into vector database assets and exclusive sensor manufacturer partnerships. Threat from SaaS-native platform vendors compressing municipal deployment cycles demands countermeasures. For New Entrants and Emerging Players: The premium-economy price gap in municipal GIS tools creates entry space for viewport-bounded streaming architectures. Target German and Dutch zoning visualization procurement where legacy installed-base incumbents lag SaaS transition. Penetrate through consumption-based licensing with automatic update pipelines as the go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors geospatial data aggregation specialists with IoT sensor mesh integration capabilities. Long-term viability rests on recurring revenue concentration in federal procurement channels. Acquisition target archetype: SaaS-native platforms with elastic infrastructure and existing FedRAMP authorization. Signal to watch: India national geospatial policy enforcement accelerating private vendor qualification.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Airworthiness Certification Investment | Validates flight deck databases for Honeywell and Thales avionics integration. |
| Vector Tile Streaming Platform Launch | Enables Esri and municipal vendors to compress German zoning tool deployment cycles. |
| Backward Integration into Sensor Manufacturing | Secures FPGA supply for Northrop Grumman NATO command platform rendering. |
| Consumption-Based Licensing Migration | Aligns US Geological Survey contracts with API call volume metrics. |
| India Geospatial Policy Partnership | Positions vendors for Delhi-NCR urban planning digitization procurement. |
Methodological Framework
Document review covered FAA certification databases, EU Green Deal implementation directives, and NATO procurement registers, complemented by interviews with avionics platform engineers, federal GIS procurement officers, and municipal zoning department heads. Secondary validation drew from EPA geospatial data standards filings, EASA airworthiness directives, and India national geospatial policy circulars. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Cross-referencing historical certification timeline patterns with panel input from Thales and Honeywell program managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user category, and technology layer with deployment model complexity. CAGRs derived from elasticity-adjusted procurement volume trajectories. Forecast inputs incorporated EU Green Deal mandate enforcement schedules and India infrastructure digitization program ramp rates.
Underlying measurement precision varies by segment; defense procurement carries tighter precision than municipal SaaS adoption forecasting. Forecasts reflect assumptions on NATO spending continuity, foundry capacity allocation, and sovereign data localization enforcement. Deviation in Taiwan semiconductor supply availability or EASA certification timeline extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market