
 Saudi Arabia Location-Based Services Market | 2026-2036
Saudi Arabia Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Location-Based Services Market Insights
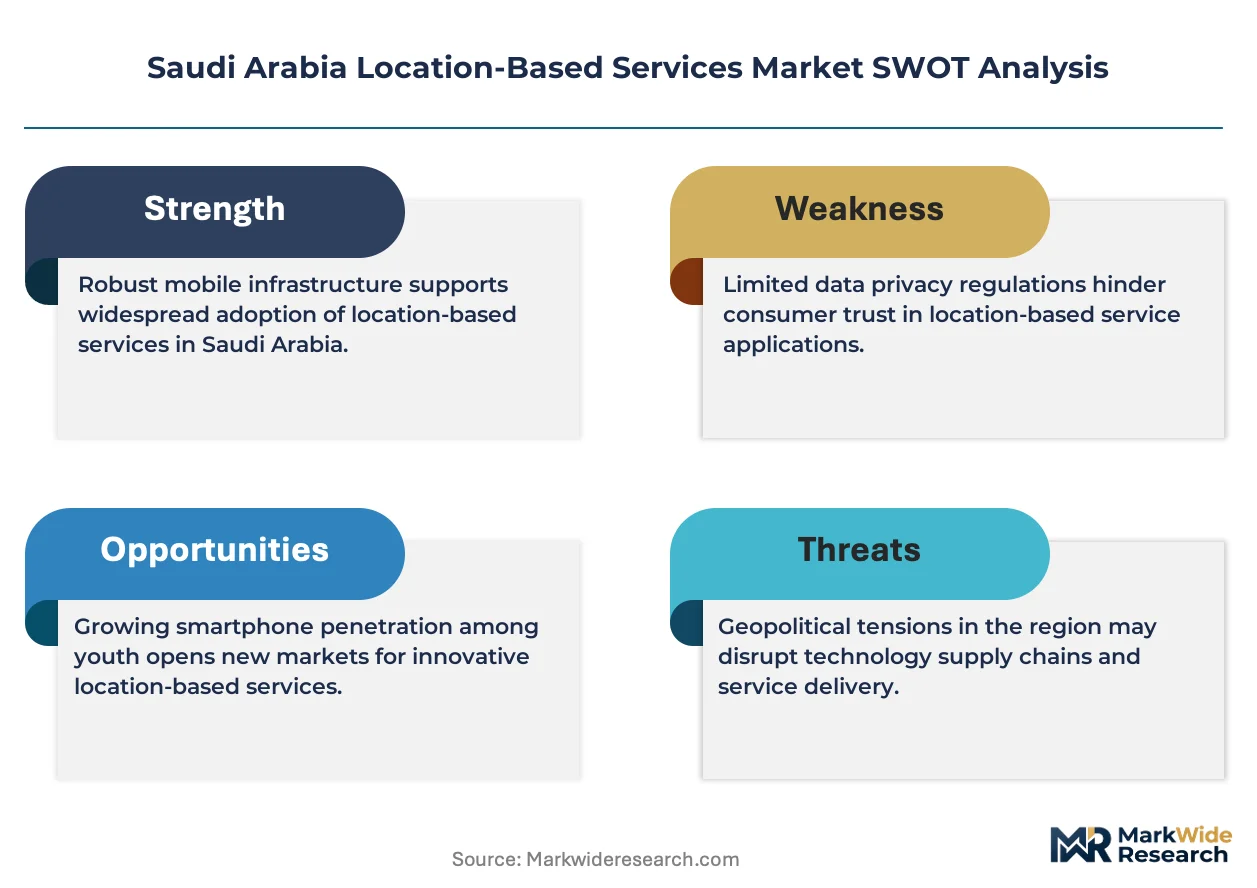
Project finance for telecom infrastructure is tilting competitive dynamics toward operators with balance-sheet capacity for multi-year network builds. Cisco Systems Inc leverages its routing and switching dominance to anchor large-scale Wi-Fi and BLE deployments across Saudi commercial zones. HERE Technologies competes through specialized automotive-grade mapping layers that sustain premium positioning in navigation contracts. Google LLC extends its consumer location data ecosystem into enterprise geofencing tools, occupying a distinct tier against industrial-focused rivals.
Location-based services encompass spatial data acquisition, coordinate processing, and real-time position analytics delivered through satellite, radio-frequency, or sensor networks with sub-meter accuracy thresholds. These systems enable route optimization, perimeter enforcement, and contextual service delivery across mobile and fixed infrastructure. GPS technology dominates navigation and fleet management applications due to mature chipset availability and minimal incremental hardware cost. Platform as a Service offerings are expanding fastest as Saudi enterprises outsource spatial analytics infrastructure rather than building proprietary stacks. API Integration services command margin premiums where retail and transportation clients demand seamless embedding of geofencing engines into existing ERP systems.
SFDA mandates strict data residency for health-related location tracking, while NCA cybersecurity standards enforce encryption protocols on all commercial positioning data flows. CITC spectrum allocations for private 5G networks directly shape where industrial asset-tracking deployments achieve viable latency performance. Stakeholders must monitor how MOF procurement rules for government smart-city tenders privilege vendors with in-Kingdom data centers over regional cloud operators.
Market Dynamics
Smart city deployments in Riyadh are compressing procurement cycles for municipal location infrastructure, forcing vendors to pre-integrate with Saudi-specific data residency architectures before contract award.
Growth Catalysts
- SFDA data-localization mandates:Health-related location tracking systems must store coordinates within Kingdom borders, creating captive demand for domestic cloud infrastructure providers.
- Aramco-led industrial digitization:Precise asset-tracking requirements across Eastern Province oil and gas facilities are pulling sub-meter accuracy hardware into hazardous environment certifications.
- CITC private 5G spectrum allocations:Dedicated bandwidth for industrial zones is enabling latency-sensitive fleet management applications that cellular networks previously could not support.
Market Restraints
- Semiconductor supply concentration:GPS and BLE chipset fabrication depends on Taiwan and South Korea foundries, exposing Saudi integrators to geopolitical disruption risk.
- NCA encryption protocol costs:Mandatory cybersecurity frameworks for commercial positioning data flows impose hardware-level security module expenses that inflate unit economics for mid-scale deployments.
- Lithium battery thermal limitations:Outdoor asset tags in Saudi summer conditions face accelerated degradation, compressing replacement cycles and total cost of ownership calculations.
Strategic Opportunities
- Neom urban corridor:The linear city project requires greenfield location infrastructure without legacy system integration burden, favoring vendors with modular API-first architectures.
- MOF procurement rule advantages:Government smart-city tenders now privilege vendors operating in-Kingdom data centers, creating structural preference against regional cloud competitors.
- Ultra-wideband and 5G convergence:Indoor positioning accuracy below 10 centimeters becomes viable where private network density supports time-of-flight triangulation, opening warehouse automation contracts.
Industry Challenges
- Geospatial data science talent scarcity:Spatial analytics engineering expertise concentrates in Riyadh and Jeddah, forcing Eastern Province operators into wage-premium recruitment or remote workforce dependency.
- Multi-vendor API harmonization:Municipal clients demand seamless embedding of geofencing engines into existing ERP systems, requiring costly custom integration layers that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Location-Based Services Market |
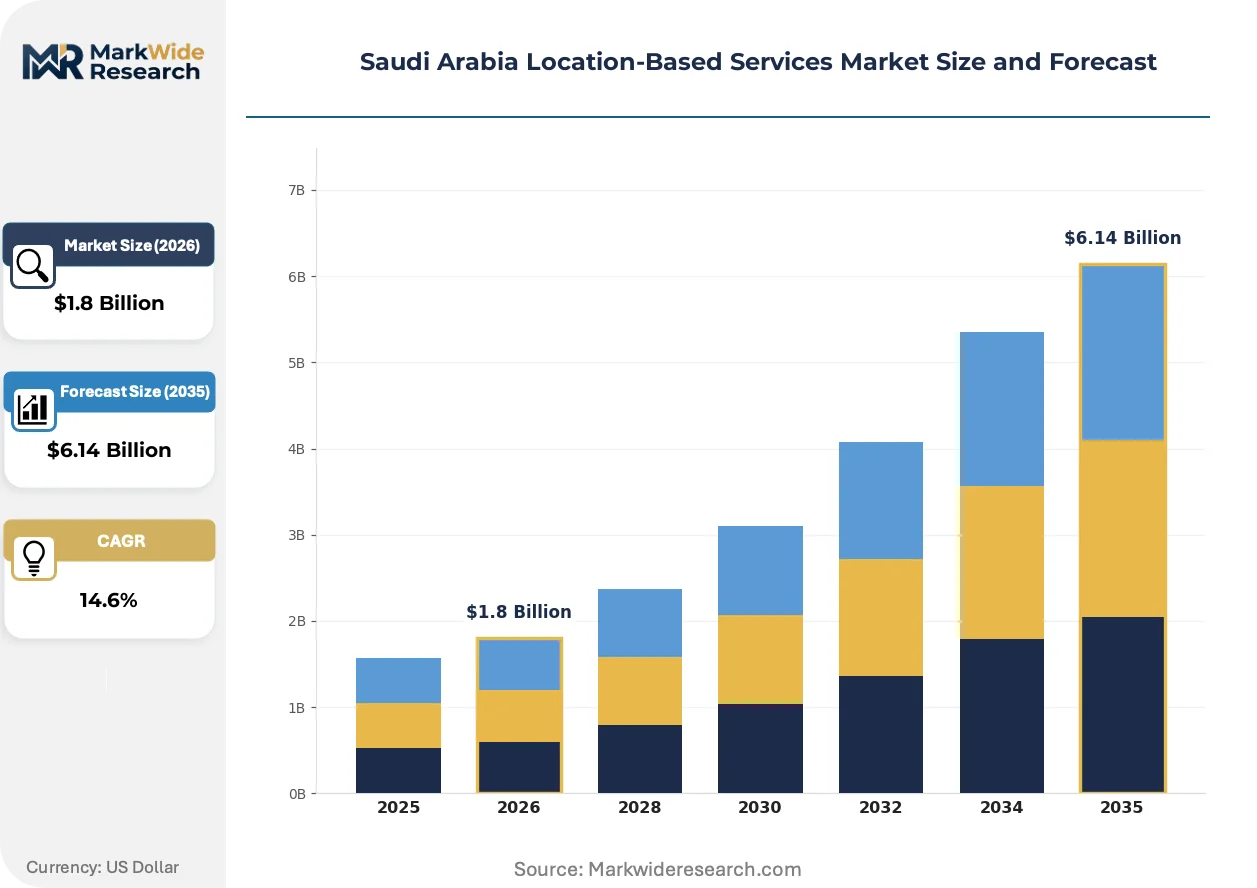
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Wi-Fi, BLE, RFID Application: Navigation, Asset Tracking, Geofencing, Proximity Marketing End User: Retail, Transportation, Healthcare, Government Service Type: Data Analytics, Platform as a Service, API Integration, Custom Solutions |
| Companies Covered | Cisco Systems Inc, Esri Saudi Arabia Ltd, Zebra Technologies Corp, Telefonaktiebolaget LM Ericsson, ALE International, Google LLC, HERE Technologies, Microsoft Corporation, Uber Technologies Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Location-Based Services Market Trends and Innovations
Platform-as-a-Service architectures are displacing proprietary spatial analytics stacks across Saudi enterprise buyers, compressing vendor differentiation toward API reliability and data residency guarantees rather than algorithmic performance.
Real-time kinematic positioning is digitizing surveying and construction workflows across Neom and Red Sea Project sites. Engineering contractors are adopting network-RTK subscriptions at accelerating pace to eliminate base station capital expenditure. This technology is digitizing terrain modeling timelines from weeks to hours, compressing project milestone risk for master developers.
NCA cybersecurity standards are mandating encryption protocols on all commercial positioning data flows traversing public networks. Industrial operators must retrofit existing fleet management systems with hardware security modules or risk contract disqualification. Oil and gas logistics providers in the Eastern Province face the steepest compliance burden given the classified status of facility coordinates.
Enterprise buyers are unbundling spatial analytics infrastructure from application software, preferring subscription-based geofencing engines over perpetual-license mapping platforms. Retail and transportation clients in Riyadh and Jeddah now evaluate vendors on API response latency and uptime SLAs rather than feature depth. This pattern is most visible in quick-commerce delivery optimization, where sub-second location queries determine competitive positioning.
Saudi Arabia Location-Based Services Market Segmentation
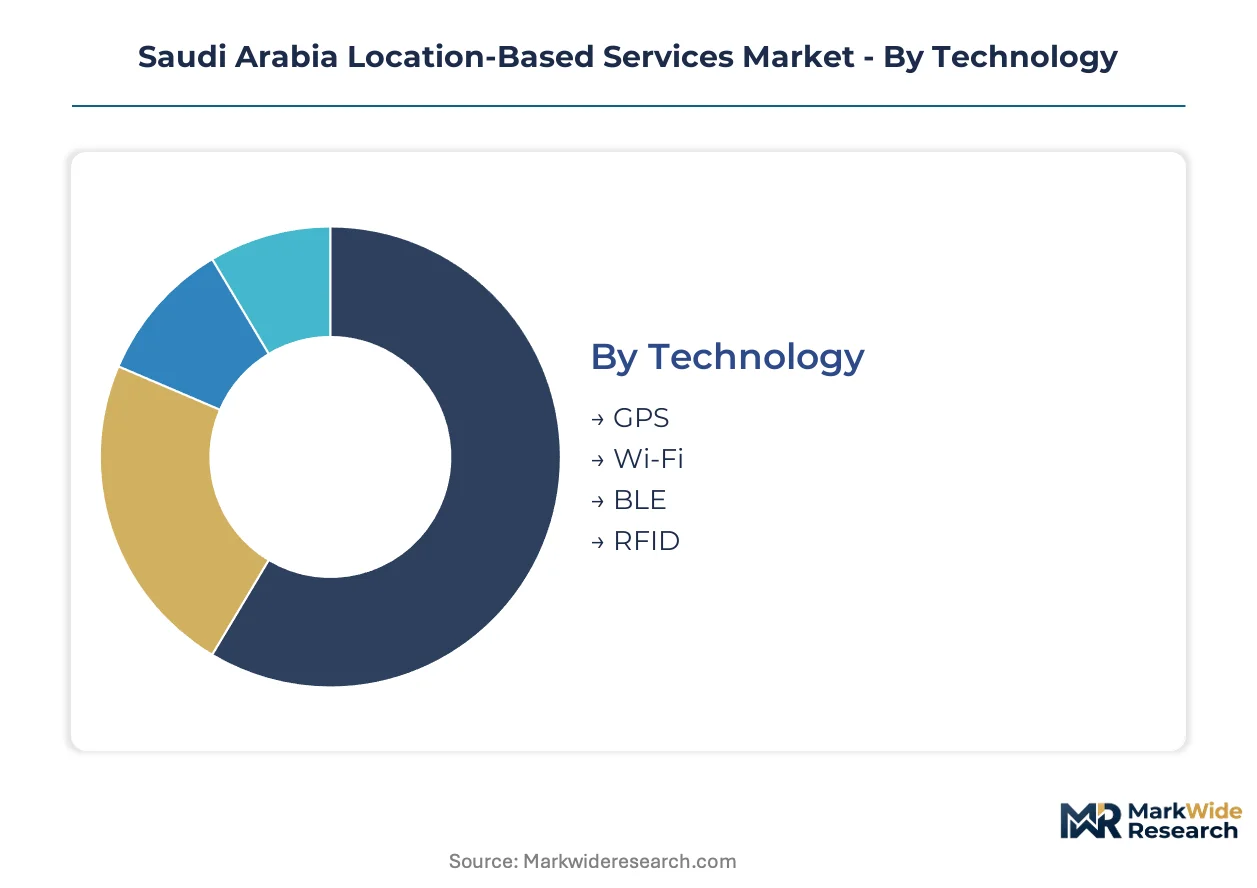
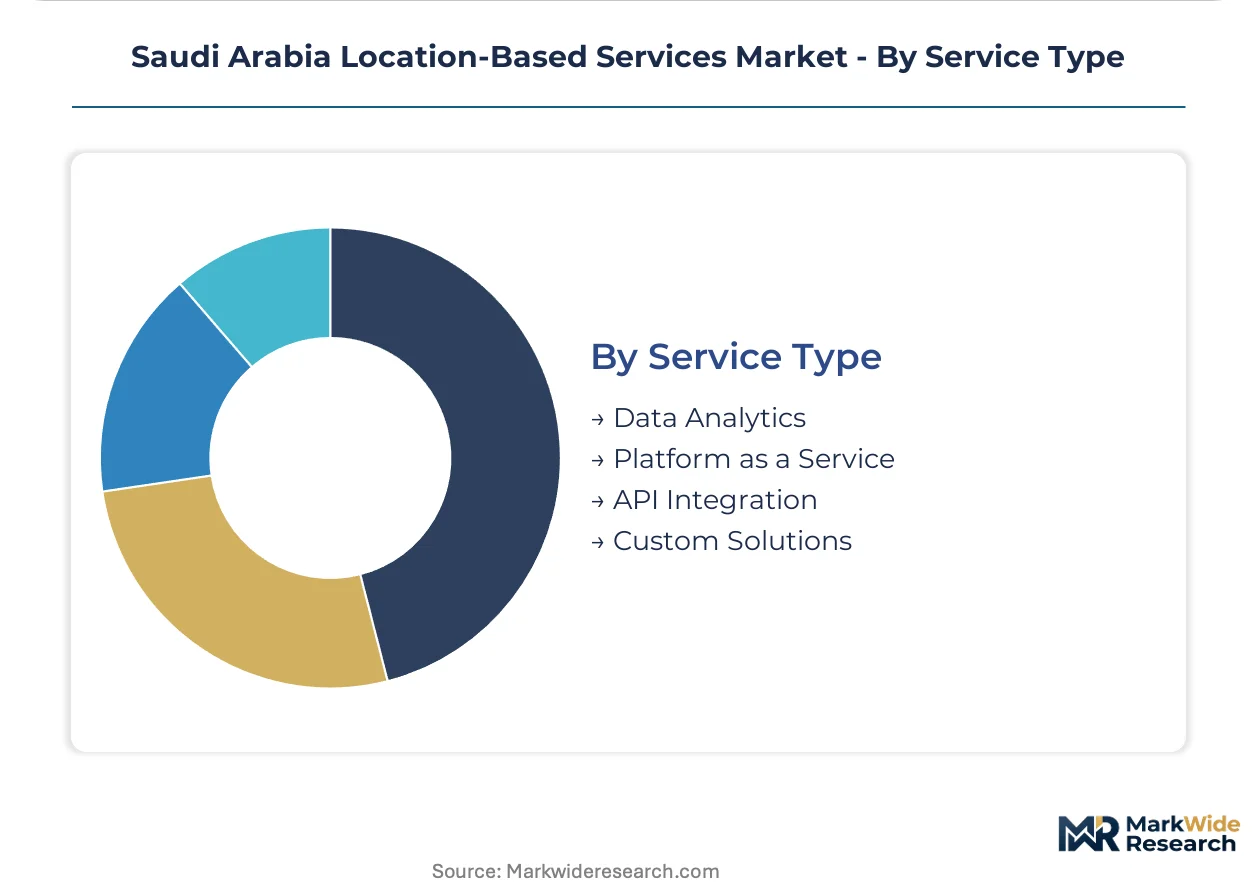
Segmentation in the Saudi Arabia Location-Based Services Market reveals distinct procurement rhythms across technology layers and service models. Municipal smart-city contracts cycle through multi-year infrastructure builds, while retail geofencing deployments refresh annually based on campaign performance.
Technology:
GPS chipsets and BLE beacon networks operate on fundamentally different replacement cycles, with satellite-dependent hardware lasting 5-7 years versus proximity sensors requiring 18-24 month refreshes in Saudi summer conditions.
- GPS:Satellite-based positioning systems leverage mature chipset architectures with minimal incremental hardware cost. Aramco-led asset-tracking mandates across the Eastern Province pull GPS units into hazardous environment certifications requiring sub-meter accuracy thresholds.
- BLE:Bluetooth Low Energy beacons enable proximity-triggered services through low-power radio transmissions. Riyadh retail zones deploy dense beacon grids for indoor navigation, though lithium battery thermal degradation accelerates replacement cycles during peak summer months.
- Wi-Fi:Positioning through wireless access point triangulation dominates commercial zone deployments where existing infrastructure reduces capital requirements.
- RFID:Radio-frequency identification tags support passive asset tracking in controlled logistics environments without battery dependency.
GPS anchors the volume base while BLE gains share at the steepest rate.
Application:
Cost tier differentiation separates navigation platforms commanding perpetual-license premiums from geofencing tools migrating toward subscription APIs.
- Navigation:Route optimization engines process real-time coordinate streams for fleet management and consumer mapping interfaces. HERE Technologies maintains premium positioning through automotive-grade map layers in Saudi navigation contracts.
- Geofencing:Perimeter enforcement systems trigger contextual actions when devices cross defined boundaries. SFDA mandates for health-related location tracking create captive demand for domestic cloud infrastructure with Kingdom-border data residency.
- Asset Tracking:Real-time position monitoring for industrial equipment and vehicle fleets.
- Proximity Marketing:Location-triggered promotional content delivery in retail environments.
Navigation commands the highest contract values while geofencing expands most quickly through API-first delivery models.
End User:
Customer type segmentation aligns procurement authority with divergent compliance burdens and integration complexity.
- Government:Municipal smart-city tenders privilege vendors operating in-Kingdom data centers under MOF procurement rules. Riyadh deployments compress procurement cycles, forcing pre-integration with Saudi-specific residency architectures.
- Transportation:Fleet operators demand sub-second location query performance for quick-commerce delivery optimization. CITC private 5G spectrum allocations enable latency-sensitive applications previously unsupported by cellular networks.
- Retail:Consumer-facing location services for store navigation and targeted promotions.
- Healthcare:Patient and equipment tracking systems subject to SFDA data-localization mandates.
Government contracts anchor revenue stability while transportation applications climb the fastest.
Service Type:
Margin structure varies sharply between outsourced infrastructure and bespoke development engagements.
- Platform as a Service:Subscription-based spatial analytics infrastructure displaces proprietary stacks across Saudi enterprises. API reliability and data residency guarantees now outweigh algorithmic performance as vendor differentiation factors.
- API Integration:Seamless embedding of geofencing engines into existing ERP systems commands margin premiums. Retail and transportation clients evaluate vendors on response latency and uptime SLAs rather than feature depth.
- Data Analytics:Processing and visualization of location-derived intelligence for operational decision-making.
- Custom Solutions:Purpose-built location systems for specialized industrial requirements.
Platform as a Service anchors the subscriber base while API Integration captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA data-localization mandates and CITC spectrum policy are redrawing vendor footprints across Saudi sub-regions. Municipal procurement rules now privilege operators with in-Kingdom data centers.
Riyadh
Smart city deployments compress procurement cycles for municipal location infrastructure. MOF procurement rules force pre-integration with Saudi-specific data residency architectures before contract award. Riyadh retail zones deploy dense BLE beacon grids for indoor navigation despite lithium battery thermal degradation accelerating replacement cycles.
Eastern Province
Aramco-led industrial digitization projects pull sub-meter accuracy hardware into hazardous environment certifications. CITC private 5G spectrum allocations enable latency-sensitive fleet management applications previously unsupported by cellular networks. Oil and gas logistics providers face steep NCA encryption compliance burdens given classified facility coordinates.
Western Region
Red Sea Project sites adopt real-time kinematic positioning subscriptions to eliminate base station capital expenditure. Engineering contractors digitize terrain modeling timelines from weeks to hours. Jeddah quick-commerce operators evaluate vendors on sub-second location query performance for delivery optimization.
NEOM Northwest
The linear city project requires greenfield location infrastructure without legacy system integration burden. Modular API-first architectures gain preference against enterprise-stack incumbents. Network-RTK deployments accelerate across construction corridors as master developers compress project milestone risk.
Saudi Arabia Location-Based Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. The vendor base clusters around three strategic archetypes: routing and switching incumbents anchoring large-scale Wi-Fi deployments, automotive-grade mapping specialists sustaining premium navigation contracts, and cloud-native platforms extending consumer data ecosystems into enterprise geofencing. Dominant competitive moves include strategic partnerships with domestic cloud operators for data residency compliance and API-first portfolio diversification targeting quick-commerce logistics.
Within the infrastructure tier, Cisco Systems Inc and Telefonaktiebolaget LM Ericsson occupy positions shaped by balance-sheet capacity for multi-year network builds. HERE Technologies exemplifies the specialized mapping archetype through automotive-grade layer development. Google LLC sits within the consumer-ecosystem extension vector, leveraging location data scale into enterprise geofencing tools against industrial-focused rivals.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Esri Saudi Arabia Ltd |
| Zebra Technologies Corp |
| Telefonaktiebolaget LM Ericsson |
| ALE International |
| Google LLC |
| HERE Technologies |
| Microsoft Corporation |
| Uber Technologies Inc |
| Others |
Pricing and Supply Chain Analysis
Taiwan and South Korea foundry concentration for GPS and BLE chipsets determines both three-tier pricing structure across premium, standard, and economy levels and supply chain vulnerability to geopolitical disruption. NCA encryption protocol mandates add hardware security module costs that compress margins in mid-scale deployments while favoring vendors with balance-sheet capacity for compliance investment.
Pricing Analysis
Certification level creates the primary spread between hazardous environment-rated GPS units and standard commercial hardware. Subscription-based Platform as a Service models dominate as Saudi enterprises outsource spatial analytics infrastructure, with API Integration services commanding margin premiums for seamless ERP embedding. Pricing pressure stems from lithium battery thermal degradation accelerating BLE beacon replacement cycles in Saudi summer conditions. Quick-commerce transportation operators exhibit highest price sensitivity due to sub-second latency requirements, while Aramco-led industrial digitization projects show lowest sensitivity given classified facility coordinate compliance burdens.
Supply Chain Analysis
TSMC and Samsung Foundry anchor contract manufacturing capacity for positioning chipsets serving Saudi deployments. Component sourcing draws from Taiwan for advanced GPS silicon, South Korea for BLE modules, and China for passive RFID tags and battery cells. Raw material dependencies include lithium carbonate for beacon power cells, rare earth elements for antenna substrates, and high-purity silicon for chipset fabrication. Single-source vulnerability concentrates in Taiwan Strait geopolitical exposure. Distribution runs through Riyadh-based system integrators serving municipal smart-city tenders and Eastern Province industrial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-as-a-Service subscription layers expand faster than hardware sales as Saudi buyers unbundle spatial analytics from application software, creating service-attach opportunities with recurring revenue profiles superior to perpetual-license models.
For Market Incumbents: Pre-empt cloud-native challengers by securing in-Kingdom data center certifications before MOF procurement rules harden structural preference against regional cloud operators. Anchor large-scale Wi-Fi and BLE deployments through balance-sheet capacity for multi-year network builds. Defensive consolidation should target domestic cloud infrastructure providers to satisfy SFDA data-localization mandates for health-related location tracking.
For New Entrants and Emerging Players: Western Region quick-commerce logistics present underpenetrated white space where sub-second location query performance determines vendor selection. Neom greenfield construction corridors offer second entry point without legacy system integration burden. API-first modular architectures provide the most penetrable go-to-market angle against enterprise-stack incumbents.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors vendors with Saudi-specific data residency architectures and private 5G spectrum relationships. Long-term viability hinges on CITC regulatory alignment and NCA cybersecurity certification pathways. Acquisition targets should demonstrate in-Kingdom cloud operations and modular service delivery. The signal to watch is MOF tender award patterns privileging domestic data center operators over regional competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| In-Kingdom Data Center Certification | MOF procurement rules now structurally preference vendors with domestic cloud operations over regional competitors. |
| Private 5G Spectrum Partnership | CITC allocations enable latency-sensitive fleet management applications previously unsupported by cellular networks. |
| API-First Platform Integration | Retail and transportation clients evaluate vendors on response latency and uptime SLAs rather than feature depth. |
| Hazardous Environment Certification | Aramco-led Eastern Province projects require sub-meter accuracy hardware with specialized safety ratings. |
| Strategic Partnership with Domestic Cloud Operator | SFDA mandates for health-related location tracking create captive demand for Kingdom-border data residency. |
Research Methodology
Cross-validation between municipal smart-city procurement officers and CITC regulatory affairs specialists anchors the qualitative findings on spectrum allocation impacts. Primary interviews with platform engineers at system integrators, logistics operators managing Eastern Province fleet deployments, and ERP integration specialists at retail enterprises combined with secondary validation from CITC spectrum filings, SFDA regulatory guidance documents, and MOF procurement rule updates. Bottom-up project pipeline analysis and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical deployment timelines for Riyadh smart-city infrastructure and Neom construction phases refines growth trajectory assumptions. Segmentation dimensions modeled include technology layer, service delivery model, end-user vertical, and regional adoption pattern. CAGRs derive from weighted average of project-based contract values and subscription revenue run-rates. Industry-specific forecast inputs incorporate CITC private 5G license issuance velocity and SFDA data-localization enforcement intensity.
Practitioners should monitor CITC spectrum auction outcomes and NCA cybersecurity protocol amendments for early signals of regulatory-driven demand shifts. Forecasts reflect assumptions on semiconductor supply continuity and lithium battery thermal performance in Saudi climatic conditions. Quarterly review of MOF tender award patterns and Aramco digitization project milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Digital Elevation Model Market