
 Belgium Data Center Storage Market | 2026-2036
Belgium Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Storage Market Insights
NVMe-over-Fabrics deployment across Belgian facilities is tilting performance benchmarks away from legacy SAS architectures toward low-latency, disaggregated storage pools. Proximus S.A. leverages its nationwide fiber backbone to anchor edge-to-core data pipelines for enterprise clients. Interxion, operating under Digital Realty Trust Inc., sustains cross-border connectivity density at its Brussels campus, competing for hyperscale contracts against newer entrants. AtlasEdge Data Centres specializes in distributed metro deployments, positioning its Antwerp and Ghent nodes to capture latency-sensitive workloads from port logistics and media streaming operators.
Belgium Data Center Storage encompasses solid-state, magnetic, and tape-based media systems engineered to retain, protect, and serve structured and unstructured digital assets at enterprise scale, typically measured by IOPS density, throughput in gigabytes per second, and durability ratings exceeding 99.999% availability. These systems serve banking transaction logs, medical imaging repositories, and real-time analytics clusters where data locality and retrieval speed determine operational continuity. Object Storage leads capacity expansion as unstructured data volumes from video surveillance and IoT sensor networks overwhelm traditional file hierarchies, while SSD arrays capture premium margin pools in high-performance computing environments where microsecond latency directly impacts algorithmic trading and genomic sequencing outcomes. Hybrid Storage configurations are gaining traction among mid-tier colocation tenants seeking to balance flash-tier hot data performance against cold-archive tape economics.
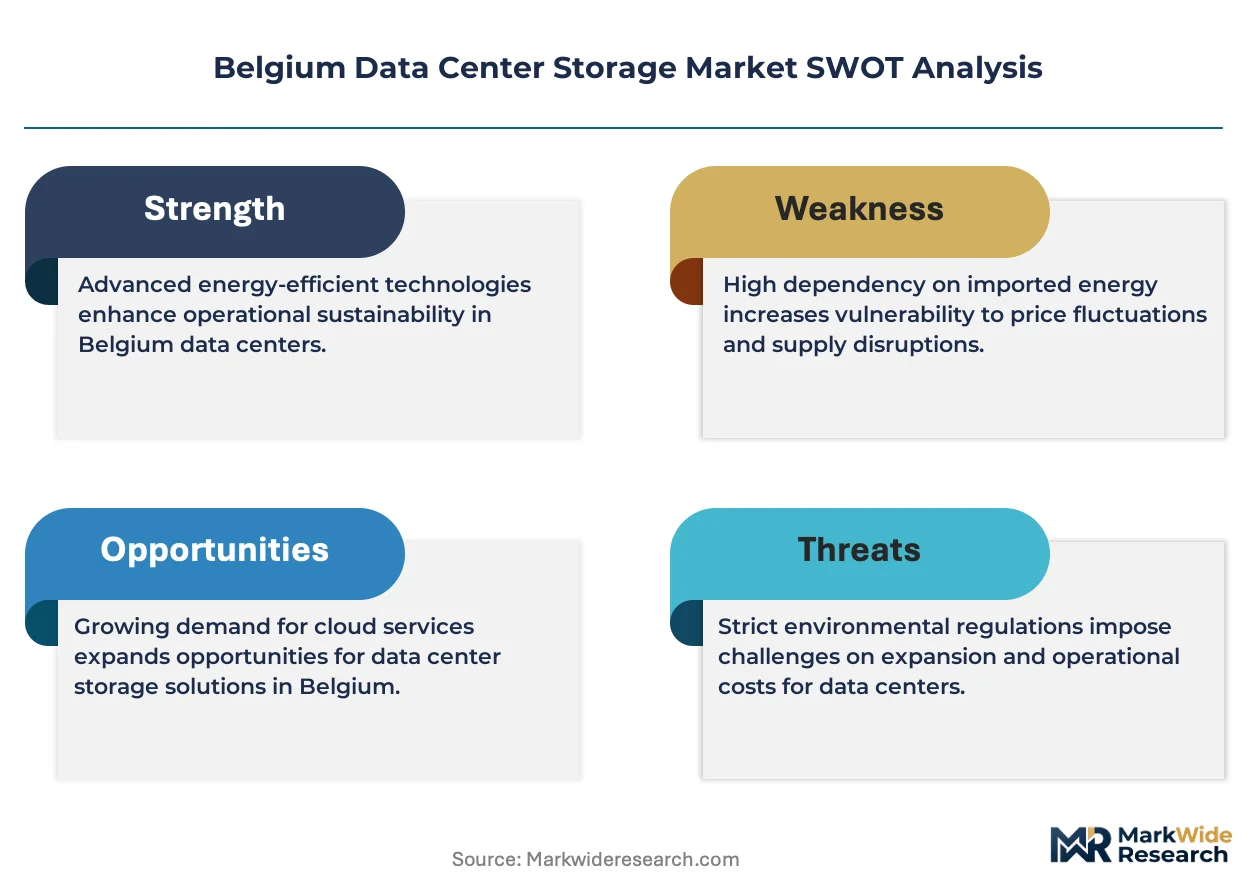
Belgium's national data protection authority enforces GDPR compliance with cross-border transfer restrictions that mandate domestic storage for sensitive citizen records, directly expanding local capacity requirements across healthcare and public sector verticals. The EU Green Deal and CSRD reporting obligations are pressuring operators to document embodied carbon in storage hardware procurement, favoring vendors with verified supply chain transparency. Stakeholders must weigh energy efficiency certifications against sovereignty mandates when selecting between centralized hyperscale builds and distributed edge configurations.
Market Dynamics
NVMe-over-Fabrics architecture is collapsing latency hierarchies across Belgian colocation facilities, forcing infrastructure operators to reconfigure storage tiering around disaggregated pools rather than localized arrays. This structural shift redistributes competitive advantage toward fiber-rich operators capable of anchoring edge-to-core pipelines.
Growth Catalysts
- GDPR Data Sovereignty Mandates:Belgian healthcare and financial services firms must retain citizen records within national borders, expanding domestic storage capacity requirements.
- Port Logistics Digitization:Antwerp's container terminals generate petabyte-scale sensor and video analytics workloads demanding low-latency object storage.
- Genomic Sequencing Clusters:Academic medical centers in Leuven and Ghent deploy all-flash arrays to accelerate proteomic research pipelines.
Market Restraints
- Flash Memory Supply Concentration:NAND fabrication concentrates in South Korea and Taiwan, exposing Belgian operators to geopolitical supply disruptions.
- CSRD Carbon Disclosure Burden:The EU Corporate Sustainability Reporting Directive mandates granular embodied carbon documentation for storage hardware procurement.
- Tape Archive Substitution Limits:Cold data retention requirements exceed flash cost economics, yet tape library expertise has atrophied among younger technicians.
Strategic Opportunities
- Wallonia Edge Expansion:Underpenetrated Liège and Namur markets present greenfield deployment opportunities for latency-sensitive manufacturing IoT.
- EU Green Deal Incentives:Operators documenting renewable energy procurement gain preferential positioning in public sector storage tenders.
- NVMe-TCP Convergence:Standard Ethernet transport for NVMe commands eliminates specialized fabric hardware requirements for mid-tier deployments.
Industry Challenges
- Distributed Systems Expertise Gap:Belgian labor markets lack sufficient engineers trained in Ceph and MinIO object storage orchestration.
- Legacy SAN Integration Friction:Financial institutions maintaining IBM and Dell EMC block storage face complex data migration paths to software-defined architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Storage Market |
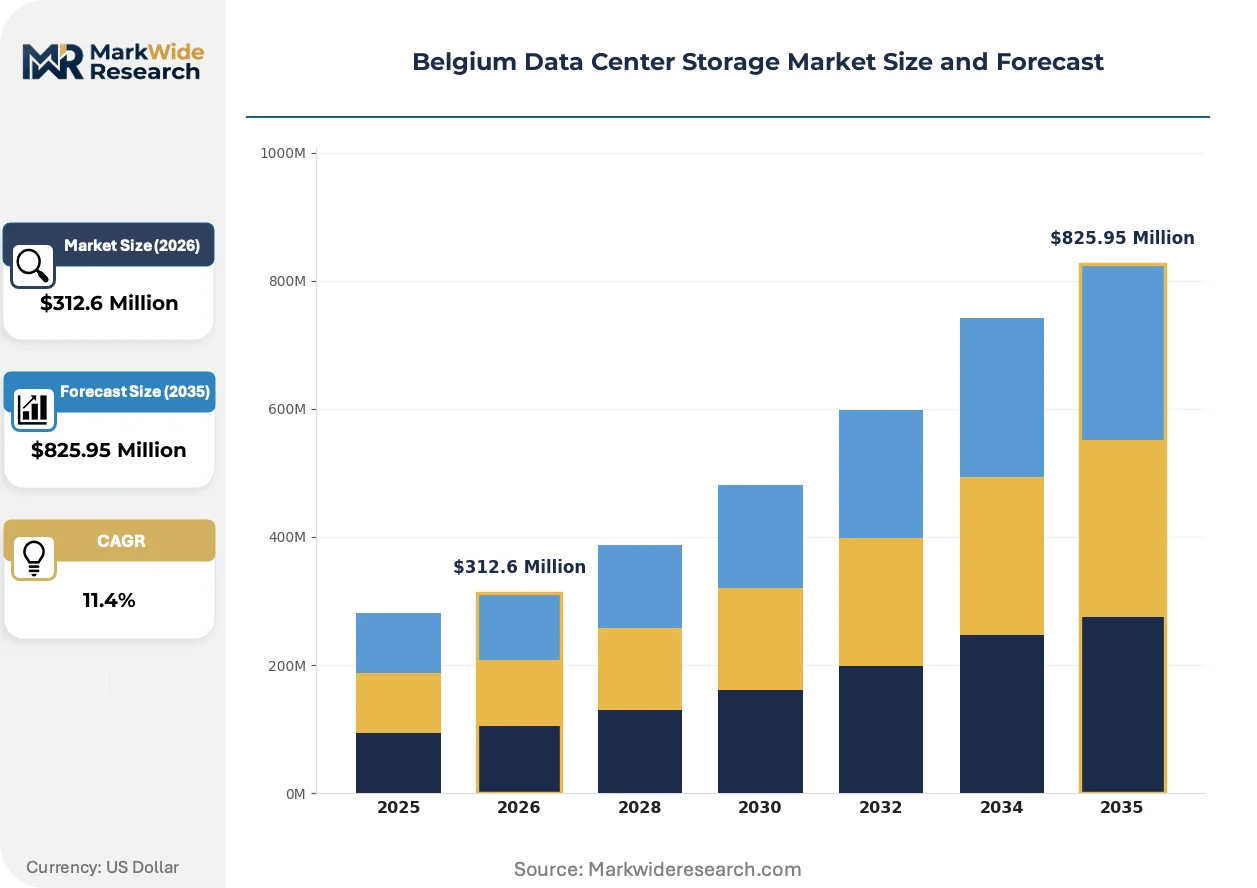
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $825.95 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SAN, NAS, DAS, Object Storage Technology: SSD, HDD, Tape, Hybrid Storage End User: IT & Telecom, BFSI, Healthcare, Retail Application: Backup & Recovery, Data Archiving, High-Performance Computing, Cloud Storage |
| Companies Covered | Proximus S.A., AtlasEdge Data Centres, Interxion (Digital Realty Trust Inc.), Wallonie Data Center SA, EXA Infrastructure, Datacenter United NV, Etix Everywhere, Network Research Belgium SA, LCL Belgium NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Storage Market Trends and Innovations
Computational storage, regulatory carbon accounting, and procurement model fragmentation are simultaneously reshaping Belgian infrastructure investment patterns. These forces compress traditional technology lifecycles while elevating operational transparency requirements.
Computational storage drives is collapsing the boundary between processing and persistence layers by embedding ARM cores directly within NVMe SSD controllers. Belgian genomics and algorithmic trading clusters adopt these devices to reduce data movement overhead. The architecture compresses rack space requirements while accelerating pattern-matching workloads that previously demanded separate GPU tiers.
CSRD implementation is mandating granular Scope 3 emissions disclosure for storage hardware across Belgian enterprise procurement. Operators must now verify supply chain carbon intensity from NAND wafer fabrication through end-of-life recycling. Financial services and healthcare verticals face the steepest compliance curves, with procurement teams restructuring vendor evaluation scorecards around verified environmental product declarations.
Consumption-based financing is displacing capital-intensive storage ownership among mid-market Belgian enterprises. Colocation tenants increasingly negotiate capacity-as-a-service contracts with automatic tiering and burst pricing provisions. This shift concentrates vendor selection power with hyperscale-adjacent operators in Flanders while compressing traditional reseller margins.
Belgium Data Center Storage Market Segmentation
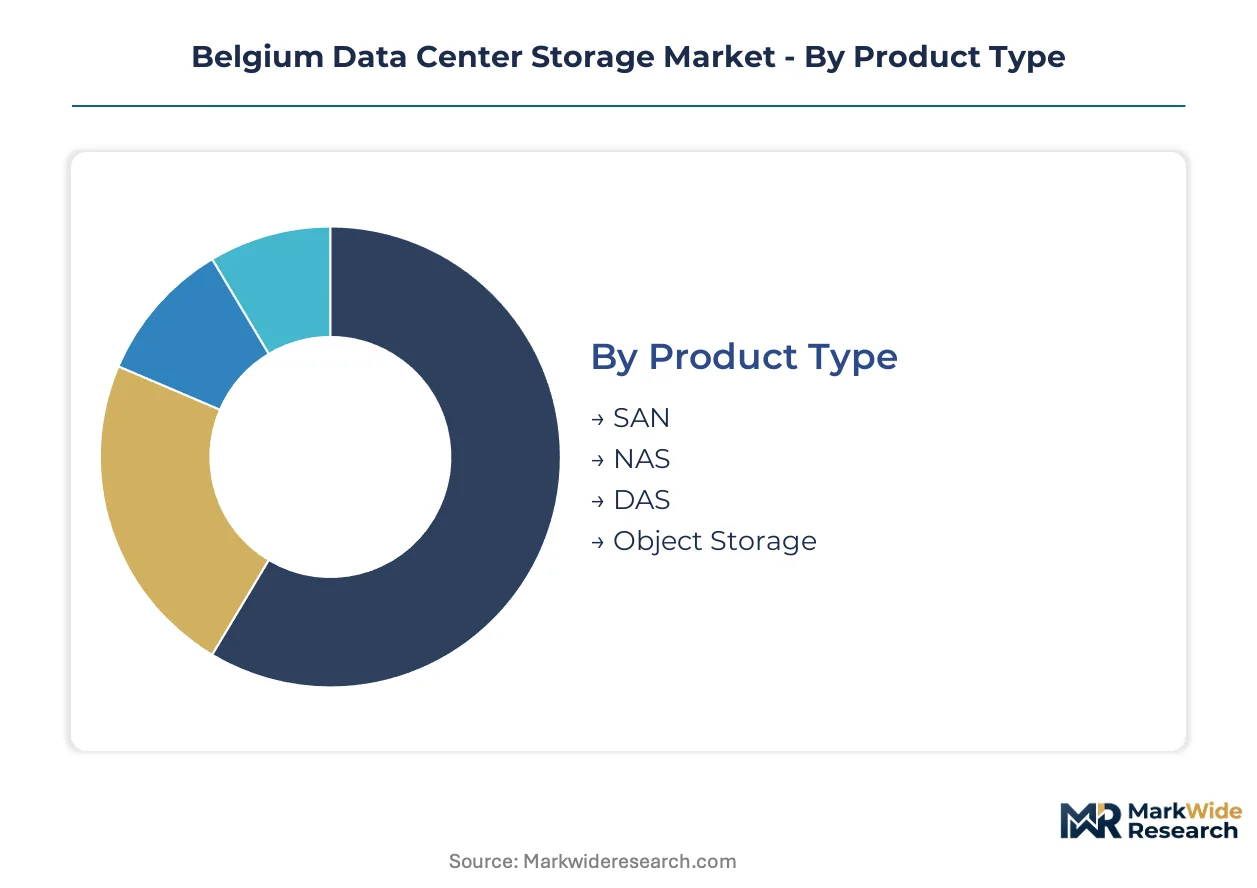
Belgian data center operators configure storage procurement around workload-specific performance tiers and compliance mandates. Segmentation reveals how GDPR sovereignty requirements and NVMe performance benchmarks reshape vendor selection criteria across Brussels, Antwerp, and Flanders facilities.
Product Type:
After-sales service intensity varies sharply across storage architectures, with software-defined systems demanding continuous firmware management versus hardware-centric alternatives requiring less frequent intervention.
- SAN:Block-level storage networks deliver dedicated fiber channel connectivity for transactional databases. Belgian financial services firms in Brussels deploy SAN clusters to meet sub-millisecond latency requirements for payment clearing systems, with service contracts emphasizing 24/7 remote monitoring.
- Object Storage:Flat namespace architectures scale horizontally across commodity servers. Port logistics operators in Antwerp ingest petabyte-scale container tracking imagery, driving demand for erasure-coded durability without traditional RAID overhead.
- NAS:File-level access protocols serve departmental shares and media workflows. Colocation tenants favor NAS for mixed read-write environments where POSIX compliance simplifies application migration.
- DAS:Direct-attached configurations persist in edge compute nodes and legacy application silos. Manufacturing IoT deployments in Wallonia retain DAS for deterministic latency in quality control imaging systems.
Object Storage holds the largest share; momentum sits with SAN deployments in financial services clusters.
Technology:
Cost tier differentiation separates flash-based performance premiums from magnetic media economics, with procurement teams balancing capital efficiency against retrieval latency SLAs.
- SSD:NAND-based solid-state drives eliminate mechanical seek latency. Genomic sequencing facilities at KU Leuven deploy NVMe SSD arrays to accelerate proteomic analysis pipelines, where microsecond response times compress research cycles.
- HDD:Magnetic spinning disks retain cost-per-gigabyte advantages for warm data tiers. Hyperscale cloud operators in Flanders provision high-capacity helium-filled drives for secondary storage pools.
- Tape:Linear tape-open libraries provide air-gapped archival for ransomware protection. Belgian healthcare networks maintain LTO-9 installations for decade-long medical imaging retention under GDPR mandates.
- Hybrid Storage:Automated tiering software migrates data across flash and disk media. Mid-market enterprises favor hybrid configurations to balance performance spikes against budget constraints.
SSD commands premium positioning; tape maintains irreplaceable share in compliance-driven long-term retention.
End User:
Customer type determines procurement authority concentration, with centralized IT governance in telecom operators contrasting distributed purchasing in healthcare networks.
- BFSI:Banking and insurance operators prioritize transactional integrity and audit trails. Brussels-based financial institutions specify storage with immutable snapshot capabilities for regulatory examination readiness.
- Healthcare:Medical centers manage DICOM imaging repositories and patient record systems. Academic hospitals in Ghent and Leuven require storage architectures supporting simultaneous diagnostic access and research analytics.
- IT & Telecom:Service providers provision multi-tenant infrastructure with metered consumption models. Proximus and regional carriers negotiate capacity-as-a-service contracts with automatic burst provisioning.
- Retail:Omnichannel operators consolidate e-commerce transaction logs and supply chain data. Belgian retail chains deploy edge caching nodes to accelerate click-and-collect fulfillment systems.
BFSI holds the largest share; healthcare is climbing the fastest on genomic and imaging data expansion.
Application:
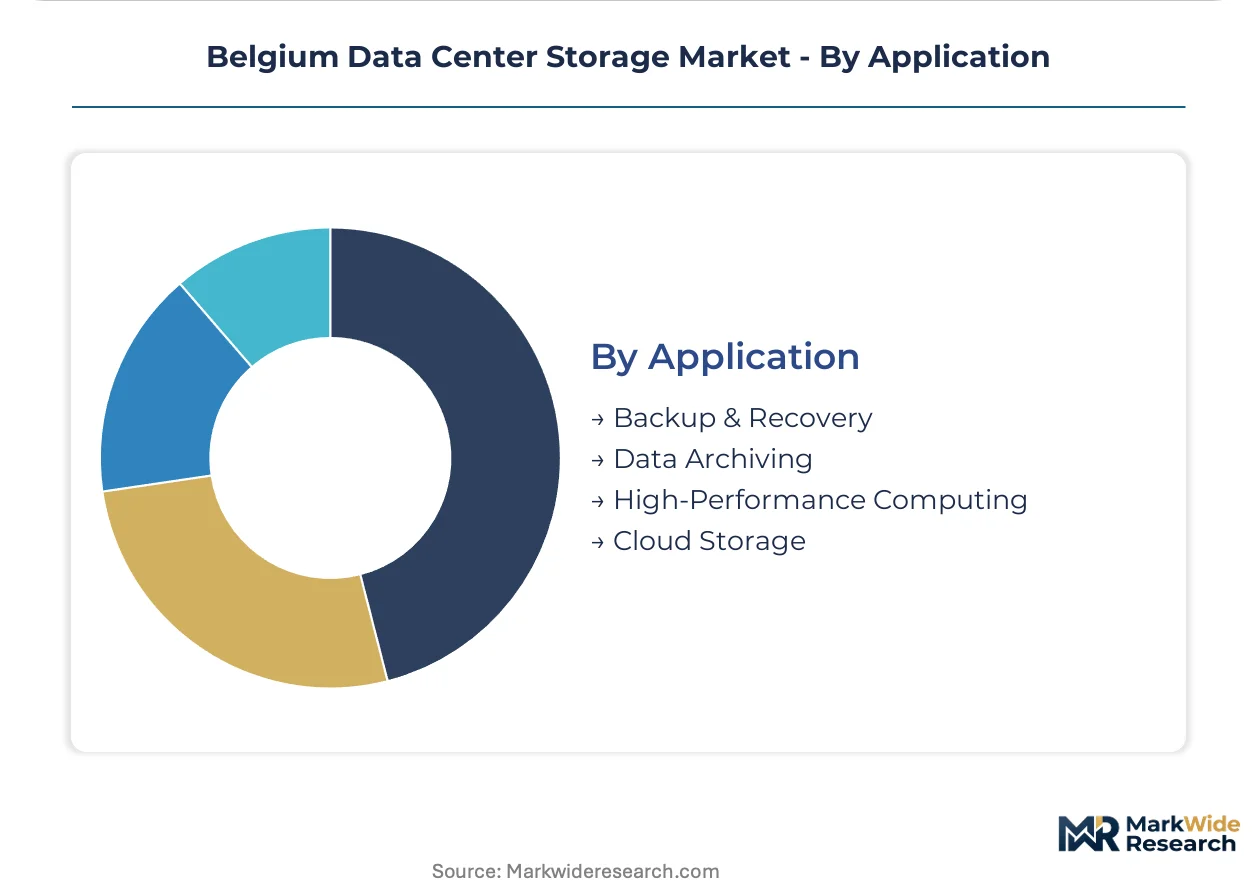
Volume concentration follows data lifecycle patterns, with backup operations consuming the greatest raw capacity while high-performance computing drives the steepest performance requirements.
- Backup & Recovery:Snapshot and replication systems protect against operational disruption. Financial services operators in Brussels implement immutable backup targets to satisfy DORA operational resilience mandates.
- Cloud Storage:Multi-tenant object and file services enable elastic capacity scaling. Flanders hyperscale campuses attract cloud storage demand from EU enterprises seeking GDPR-compliant alternatives to US-based providers.
- Data Archiving:Long-term retention systems satisfy legal hold and compliance requirements. Public sector agencies specify WORM-enabled storage for administrative record preservation.
- High-Performance Computing:Parallel file systems feed computational clusters with sustained throughput. Academic research consortia deploy Lustre and GPFS backends for climate modeling and materials science simulations.
Backup & Recovery holds the largest share; cloud storage is gaining share fastest on hyperscale expansion in Flanders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian financial services and healthcare operators concentrate procurement authority in Brussels and Flanders, driving capacity expansion decisions that ripple through Wallonia's underpenetrated markets. Port logistics digitization and genomic research clusters anchor demand density in specific sub-regions.
Flanders
Hyperscale cloud campuses in Ghent and Antwerp attract EU enterprises seeking GDPR-compliant alternatives to US-based providers. The region benefits from Flemish government innovation vouchers supporting data infrastructure investments. Port of Antwerp-Bruges generates petabyte-scale sensor workloads demanding low-latency object storage for container tracking analytics.
Brussels-Capital Region
Banking and insurance headquarters dominate transactional storage procurement with sub-millisecond latency requirements. Belgium's data protection authority enforces cross-border transfer restrictions that mandate domestic retention for sensitive records. Interxion's Brussels campus sustains cross-border connectivity density competing for hyperscale contracts.
Wallonia
Liège and Namur present greenfield deployment opportunities for latency-sensitive manufacturing IoT networks. The Walloon Region's industrial transition strategy allocates recovery funds toward digital infrastructure modernization. AtlasEdge positions Charleroi nodes to capture edge workloads from aerospace supply chain operators.
Antwerp Province
Genomic sequencing facilities at KU Leuven deploy NVMe SSD arrays accelerating proteomic research pipelines. Academic medical centers require architectures supporting simultaneous diagnostic access and research analytics. Datacenter United NV operates facilities serving pharmaceutical compliance workloads.
Limburg
Hasselt's logistics corridor generates cold storage demand from e-commerce fulfillment networks. The province connects Flanders density with German border data traffic flows. LCL Belgium NV maintains presence capturing backup and disaster recovery contracts from mid-market enterprises.
Belgium Data Center Storage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Belgium's fragmented colocation landscape. Proximus S.A. leverages nationwide fiber backbone anchoring edge-to-core pipelines, while Interxion sustains hyperscale connectivity density. Three archetypes dominate: telecom-integrated operators, pure-play data center specialists, and regional edge deployers. Competitive moves concentrate on fiber-rich site acquisition and renewable energy certification for public sector tenders.
Within the telecom-integrated tier, Proximus S.A. anchors enterprise connectivity bundles. Among pure-play specialists, Interxion (Digital Realty Trust Inc.) and AtlasEdge Data Centres exemplify divergent scale strategies—Interxion operating Brussels hyperscale campuses versus AtlasEdge pursuing distributed metro deployments in Antwerp and Ghent. Wallonie Data Center SA represents regional edge specialization capturing underpenetrated southern markets.
| Leading Market Players |
|---|
| Proximus S.A. |
| AtlasEdge Data Centres |
| Interxion (Digital Realty Trust Inc.) |
| Wallonie Data Center SA |
| EXA Infrastructure |
| Datacenter United NV |
| Etix Everywhere |
| Network Research Belgium SA |
| LCL Belgium NV |
| Others |
Pricing and Supply Chain Analysis
Flash memory supply concentration in South Korea and Taiwan generates dual exposure to geopolitical disruption and NAND spot price volatility, compressing Belgian operators into long-term offtake contracts while widening spreads between all-flash premium tiers and hybrid-economy configurations. This single-source dependency forces procurement teams to index service contracts against commodity benchmarks and prioritize vendors with verified secondary sourcing.
Pricing Analysis
Cost-plus contracts with NAND indexation dominate Belgian hyperscale procurement, with pricing stratifying across premium NVMe arrays, standard hybrid tiers, and economy HDD pools based on latency SLAs and GDPR certification levels. Price erosion runs through mid-market hybrid configurations as Taiwanese fabrication capacity expands, while financial services buyers in Brussels exhibit lowest price sensitivity due to regulatory mandates. Colocation tenants in Flanders face tightening margins from consumption-based financing models that shift capex risk to operators.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn and Wistron facilities in Taiwan and China for storage controller assembly, with Belgian operators drawing from South Korean NAND fabs and Dutch ASML lithography equipment. Raw material dependencies span silicon wafers, rare earth elements for drive motors, and cobalt for battery backup systems. Single-source vulnerability in EUV equipment creates chokepoint exposure for next-generation SSD procurement. Distribution runs through Rotterdam port logistics and fiber-connected Flanders distribution hubs serving Brussels and Antwerp facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium Data Center Storage operates as a defensive-moat market where GDPR regulatory entrenchment creates substantial switching costs for financial services and healthcare incumbents, locking in multi-year capacity commitments.
For Market Incumbents: Pre-empt NVMe-TCP standardization by upgrading Brussels and Antwerp facilities to disaggregated storage pools before mid-tier competitors eliminate fabric hardware differentiation. Defend against AtlasEdge's distributed metro expansion through fiber-rich site acquisition in Ghent and Liège. Prioritize renewable energy certification to capture public sector tenders under EU Green Deal incentives.
For New Entrants and Emerging Players: Pursue Wallonia's underpenetrated manufacturing IoT segment in Charleroi and Namur, where latency-sensitive edge workloads lack established provider relationships. Target genomic sequencing facilities at KU Leuven with consumption-based all-flash offerings that bypass capital-intensive ownership models. Lead with NVMe-over-Fabrics expertise to differentiate against legacy SAN incumbents.
For Investors and Strategic Acquirers: The market sits at an infrastructure consolidation phase that favors fiber-anchored operators with renewable certification and cross-border connectivity density. Long-term viability rests on regulatory entrenchment deepening through DORA operational resilience mandates and CSRD carbon disclosure requirements. Monitor NAND spot price volatility and EUV equipment lead times as inflection indicators for margin compression windows.
| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabrics Deployment | Collapses latency hierarchies at Interxion Brussels campus, attracting algorithmic trading workloads. |
| Renewable Energy Certification | Unlocks preferential positioning in Belgian public sector tenders under EU Green Deal procurement rules. |
| Wallonia Edge Expansion | Captures manufacturing IoT demand in Liège and Namur with distributed metro configurations. |
| Consumption-Based Financing | Shifts capex risk to operators while compressing traditional reseller margins in Flanders. |
| CSRD Carbon Documentation | Mandates granular Scope 3 disclosure, favoring vendors with verified supply chain transparency. |
Research Methodology
A spread of perspectives from data center operations directors, storage procurement managers at financial institutions, colocation sales executives, and healthcare IT infrastructure leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Digital Realty Trust, hyperscaler capex disclosures, and Belgian Data Protection Authority enforcement records. Bottom-up capacity modeling triangulated against top-down GDPR compliance-driven demand projections.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning storage architecture type, technology tier, end-user vertical, and regional facility density. CAGRs derived from installed base expansion rates, replacement cycles, and workload growth patterns in genomic sequencing and port logistics analytics. Forecast inputs incorporated NAND supply elasticity, fiber backbone capacity, and EU regulatory implementation timelines.
Sensitivities concentrate around NAND spot price volatility, EUV equipment availability, and GDPR enforcement intensity that could accelerate or delay domestic capacity requirements. Forecasts reflect documented assumptions on technology adoption curves and regulatory compliance deadlines. Quarterly review of NAND contract pricing, renewable energy certificate markets, and Belgian DPA enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Europe Data Center Storage Market